
 Australia Schizophrenia Drugs Market | 2026-2036
Australia Schizophrenia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Schizophrenia Drugs Market Insights
The Australia schizophrenia drugs landscape is rebalancing between premium atypical antipsychotics and commodity typical antipsychotic tiers as PBS pricing reforms compress generic margins. Johnson & Johnson leverages its long-acting injectable portfolio to sustain premium positioning in chronic care settings. Eli Lilly and Company anchors hospital formulary access through specialized mental health center partnerships. Alkermes PLC differentiates via depot formulation technology leadership, while AstraZeneca PLC competes on established atypical antipsychotic brand strength in first-episode psychosis protocols.
Schizophrenia drugs comprise pharmaceutical agents targeting dopamine and serotonin receptor modulation to manage psychotic symptoms, with formulations spanning oral tablets, orally disintegrating doses, and intramuscular long-acting injectables requiring precise particle size control and polymer matrix engineering for sustained release. Atypical antipsychotics lead prescription volumes due to superior extrapyramidal side effect profiles, while long-acting injectables represent the fastest-expanding segment as clinicians prioritize adherence monitoring in community care settings. Patient care setting dynamics reveal margin pools concentrating in outpatient clinics where medication management fees supplement pharmaceutical reimbursement.
The Therapeutic Goods Administration (TGA) governs schizophrenia drug registration through stringent bioequivalence and stability standards, while the Pharmaceutical Benefits Scheme (PBS) determines market access via cost-effectiveness thresholds that directly shape manufacturer pricing submissions. The Australian Commission on Safety and Quality in Health Care enforces clinical practice standards that influence prescriber preference for specific drug classes and formulations. Stakeholders must monitor evolving PBS listing negotiations and TGA expedited review pathways for novel mechanisms of action as these regulatory levers determine competitive positioning across the forecast horizon.
Market Dynamics
The PBS pricing reforms are compressing generic antipsychotic margins while simultaneously accelerating long-acting injectable uptake across New South Wales and Victoria community mental health networks.
Growth Catalysts
- Long-acting injectable formulations:Community mental health services in Queensland and Western Australia are expanding depot antipsychotic programs to reduce hospital readmission rates.
- TGA streamlined approval pathways:The Therapeutic Goods Administration's expedited review mechanisms for novel mechanisms of action are shortening time-to-market for next-generation dopamine modulators.
- Telehealth-enabled outpatient networks:Psychiatric services in metropolitan Melbourne and Sydney are integrating remote medication management to extend prescriber reach into regional patient populations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for atypical antipsychotics concentrates among Indian and Chinese contract manufacturers, exposing Australian formulators to geopolitical supply disruptions.
- PBS cost-effectiveness thresholds:The Pharmaceutical Benefits Scheme's incremental cost-effectiveness ratio requirements block reimbursement for premium-priced novel antipsychotics lacking demonstrable mortality or hospitalization benefits.
- Generic price erosion:Oral risperidone and olanzapine commoditization has collapsed per-dose margins below sustainable levels for domestic distributors.
Strategic Opportunities
- Western Australia regional penetration:The Perth-to-Bunbury corridor presents underdeveloped community mental health infrastructure where depot formulation services could anchor first-mover prescriber relationships.
- Digital therapeutics convergence:Smartphone-based adherence monitoring paired with pharmacogenomic testing enables personalized dosing protocols for clozapine-resistant patient subpopulations.
- Pharmacy-administered depot programs:The Community Pharmacy Agreement's medication management fee structure creates reimbursement pathways for pharmacist-delivered long-acting injectable administration outside hospital settings.
Industry Challenges
- Psychiatric nurse practitioner scarcity:The Australian College of Mental Health Nurses reports insufficient trained clinicians to administer depot formulations across expanding community catchment areas.
- Cold chain integrity for biologic depot formulations:Polymer matrix stability requirements demand continuous temperature monitoring during distribution to remote Northern Territory and Tasmania clinics.
- Stability testing timeline compression:TGA's accelerated bioequivalence review expectations conflict with extended-release formulation characterization protocols, delaying generic depot submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Schizophrenia Drugs Market |
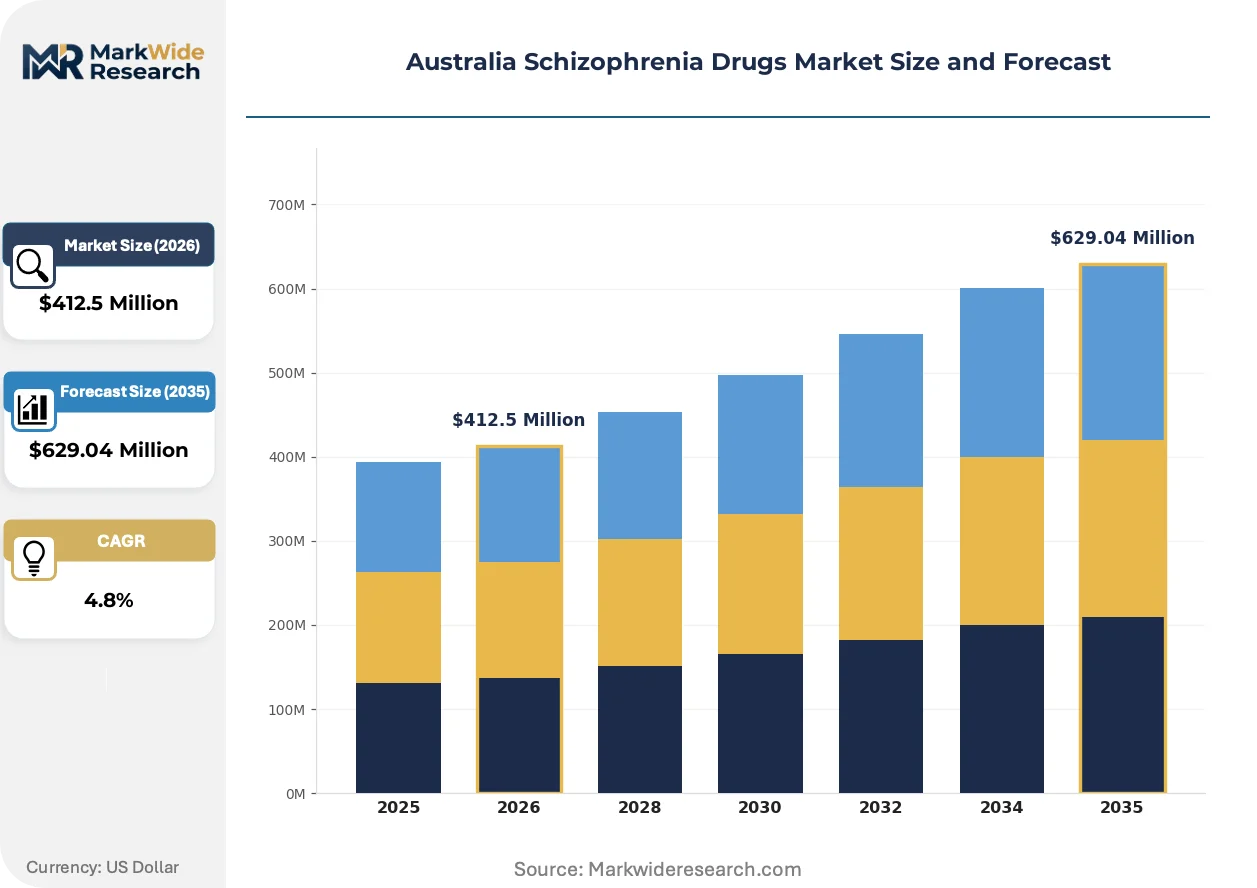
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Typical Antipsychotics, Atypical Antipsychotics, Long-Acting Injectables, Adjunctive Treatments Indication: First-Episode Psychosis, Chronic Schizophrenia, Treatment-Resistant Schizophrenia, Acute Psychotic Episodes Patient Care Setting: Inpatient Facilities, Outpatient Clinics, Community Care Centers, Residential Treatment Facilities Distribution Channel: Pharmacies, Hospitals, Online Pharmacies, Specialized Mental Health Centers |
| Companies Covered | Johnson & Johnson, Eli Lilly and Company, Alkermes PLC, AstraZeneca PLC, Otsuka Pharmaceutical, AbbVie Inc., Pfizer Inc., H. Lundbeck AS, Bristol-Myers Squibb, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Schizophrenia Drugs Market Trends and Innovations
Formulation engineering and reimbursement redesign are converging to displace oral maintenance therapy in chronic schizophrenia management across Australian psychiatric services.
Long-acting injectable technology is consolidating market structure around three-monthly paliperidone palmitate and monthly aripiprazole depot formulations. Community mental health teams in Victoria and New South Wales are standardizing these products as default maintenance options for patients with two or more hospitalizations. This consolidation is compressing oral atypical antipsychotic volumes in stable chronic populations while concentrating margin pools with manufacturers possessing polymer matrix engineering capabilities.
TGA's expedited review pathway for novel antipsychotic mechanisms is compressing registration timelines for trace amine-associated receptor 1 (TAAR1) agonists and muscarinic receptor modulators. The regulatory shift is forcing established atypical antipsychotic sponsors to defend hospital formulary access through real-world evidence generation rather than trial-based efficacy claims. First-episode psychosis protocols in Queensland's public mental health services are most affected, with clinicians awaiting these mechanisms to address metabolic side effect burdens.
Medication adherence monitoring is displacing passive prescription renewal in community care settings. Psychiatric nurse practitioners in South Australia and Tasmania are deploying Bluetooth-enabled pill dispensers and depot injection tracking systems to identify non-adherence patterns before psychotic relapse. This behavioral shift is most visible in the Perth metropolitan catchment, where telehealth-integrated medication management fees now exceed pharmaceutical reimbursement in total episode cost structures.
Australia Schizophrenia Drugs Market Segmentation
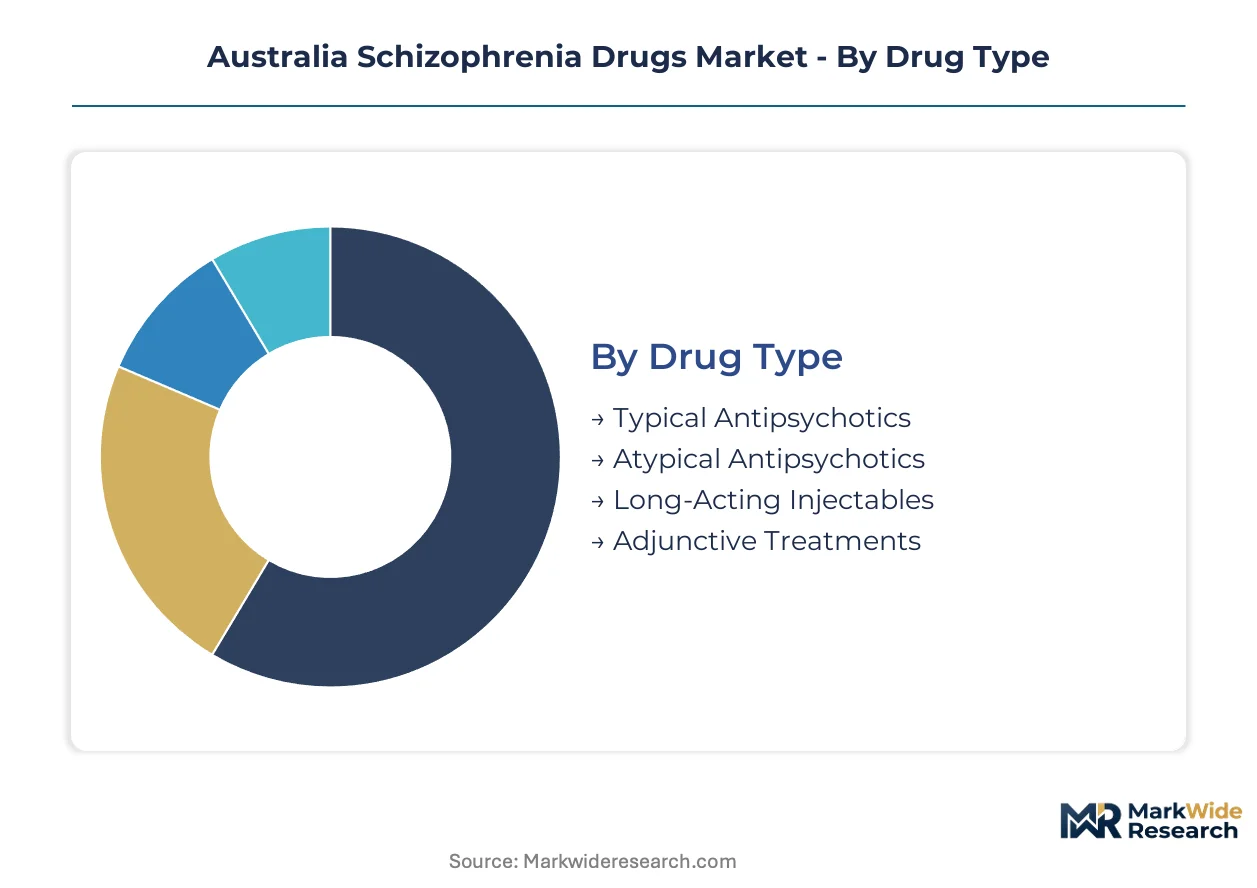
Segmentation in the Australian schizophrenia drugs market reveals how formulation technology and care setting economics determine competitive positioning. Each dimension exposes distinct margin structures and regulatory access points that manufacturers must navigate.
Drug Type:
Integration depth varies sharply across pharmacological classes, with standalone oral formulations competing against embedded depot delivery systems in chronic care protocols.
- Atypical Antipsychotics:Second-generation dopamine-serotonin modulators with reduced extrapyramidal burden dominate maintenance prescribing across New South Wales and Victoria community mental health services. PBS reimbursement favors established oral atypicals in first-episode protocols, though metabolic monitoring requirements constrain formulary placement for clozapine-resistant populations.
- Long-Acting Injectables:Polymer matrix depot formulations requiring precise particle engineering integrate directly into adherence-monitoring infrastructure. Queensland and Western Australia health services are embedding three-monthly paliperidone and monthly aripiprazole depots as default discharge options for high-readmission risk patients.
- Typical Antipsychotics:First-generation dopamine antagonists function as standalone cost-tier options in acute containment settings where sedation speed outweighs side effect profiles.
- Adjunctive Treatments:Mood stabilizers and antidepressant co-therapies embed within multi-drug regimens for treatment-resistant subpopulations in specialized Melbourne and Sydney clinics.
Atypical antipsychotics lead volumes today; long-acting injectables are gaining share fastest.
Indication:
Cost tier stratification separates acute intervention budgets from chronic maintenance funding pools across Australian state health systems.
- Chronic Schizophrenia:Persistent symptom management drives the largest prescription volumes through community mental health team caseloads. Victoria's assertive outreach programs concentrate depot formulation demand in this segment, with medication management fees supplementing pharmaceutical margins.
- First-Episode Psychosis:Early intervention protocols in Queensland's Youth Mental Health services embed atypical antipsychotic selection within recovery-oriented care models. TGA streamlined pathways are accelerating novel mechanism access for this population.
- Treatment-Resistant Schizophrenia:Clozapine-mandatory populations require specialized monitoring infrastructure concentrated in tertiary Melbourne and Sydney centers.
- Acute Psychotic Episodes:Hospital emergency departments and inpatient units drive rapid-acting formulation demand with compressed decision windows.
Chronic schizophrenia commands the largest spend; first-episode psychosis protocols are expanding most quickly.
Patient Care Setting:
Volume concentration tracks state government mental health infrastructure investment, with margin pools shifting toward outpatient administration models.
- Community Care Centers:Nurse practitioner-delivered depot programs in Perth-to-Bunbury corridors and Adelaide northern suburbs anchor expanding catchment areas. The Community Pharmacy Agreement's medication management fee structure enables pharmacist-administered long-acting injectables outside hospital settings.
- Outpatient Clinics:Metropolitan psychiatric services in Sydney and Melbourne integrate telehealth-enabled medication management with in-person depot administration. This hybrid model concentrates margin capture in private practice networks.
- Inpatient Facilities:Acute admission wards in Queensland and New South Wales public hospitals drive rapid-acting antipsychotic demand with formulary-controlled procurement.
- Residential Treatment Facilities:Transitional housing programs in Tasmania and regional Victoria embed medication adherence monitoring within supported accommodation frameworks.
Community care centers are expanding fastest; outpatient clinics retain the highest per-patient margins.
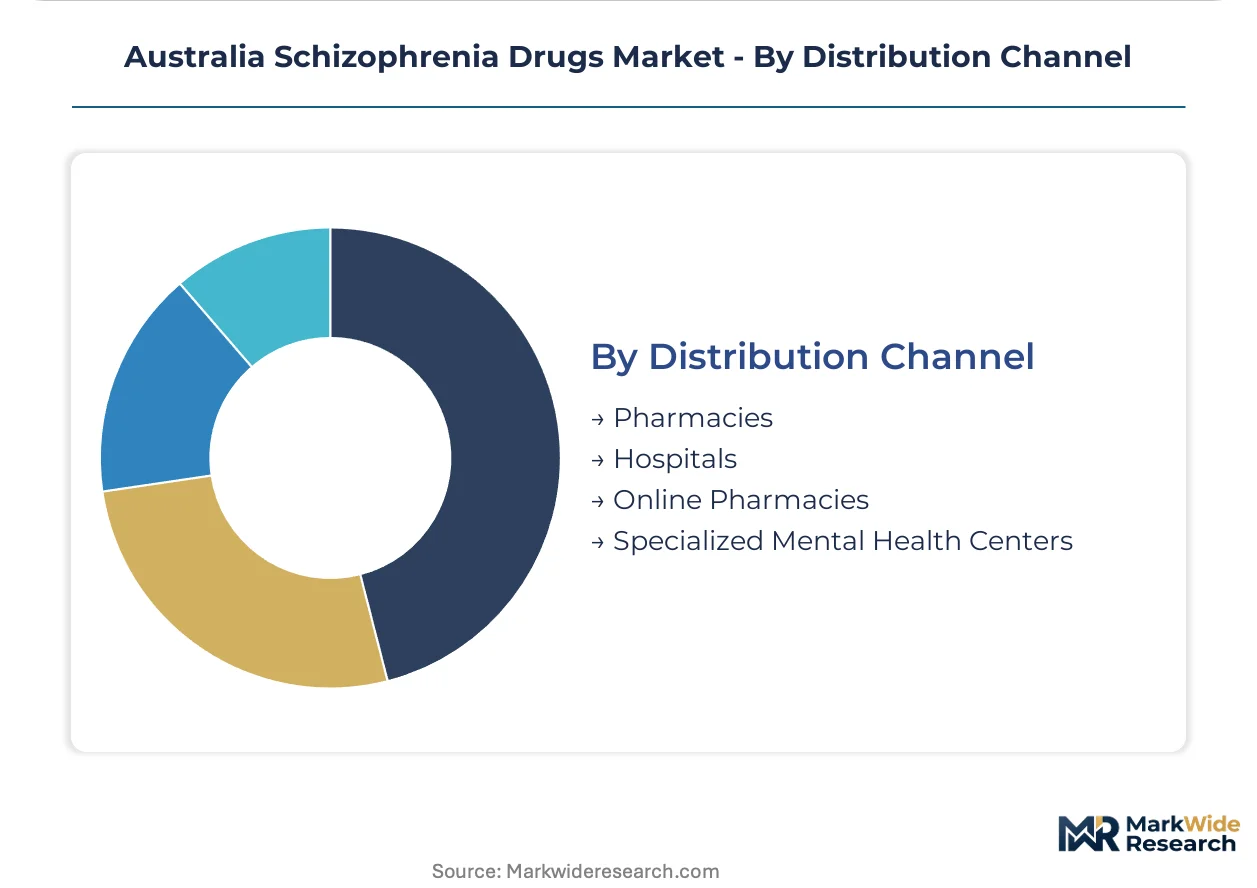
Distribution Channel:
Supply concentration reflects PBS reimbursement pathway complexity and cold chain requirements for depot formulations.
- Hospitals:Public mental health service procurement in New South Wales and Victoria concentrates volume through centralized pharmacy committees. TGA batch release testing requirements for biological depot products reinforce hospital pharmacy control.
- Specialized Mental Health Centers:Stand-alone psychiatric facilities in Melbourne and Sydney embed dispensing within multidisciplinary care teams, capturing adherence data for outcomes-based contracting.
- Pharmacies:Community pharmacy networks across Queensland and Western Australia are piloting depot administration under pharmacist scope-of-practice expansion.
- Online Pharmacies:Oral maintenance therapy refills concentrate in metropolitan same-day delivery corridors with electronic prescription infrastructure.
Hospitals dominate volume throughput; specialized mental health centers are capturing margin through integrated care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychiatric nurse practitioners and specialized mental health clinicians concentrate in Australia's southeastern metropolitan corridors, anchoring depot formulation service expansion across state-funded community networks.
New South Wales
Sydney's assertive outreach programs drive long-acting injectable demand through integrated community mental health teams. The state's Mental Health Commission funds depot administration training for nurse practitioners across Western Sydney and Newcastle corridors. The Nepean Blue Mountains and Illawarra Shoalhaven districts embed medication adherence monitoring within housing support frameworks.
Victoria
Melbourne's first-episode psychosis protocols embed atypical antipsychotic selection within youth mental health recovery models. The state's Department of Health prioritizes clozapine-resistant patient pathways through specialized metropolitan clinics. The Barwon and Gippsland regions extend telehealth-enabled depot programs into rural catchments lacking psychiatrist density.
Queensland
Brisbane's early intervention services accelerate novel mechanism access through TGA streamlined review participation. The state's Hospital and Health Services integrate three-monthly paliperidone depots as default discharge options for high-readmission risk patients. The Gold Coast and Sunshine Coast corridors pilot pharmacy-administered long-acting injectables under scope-of-practice expansion.
Western Australia
Perth's northern suburbs present underdeveloped community mental health infrastructure where depot services could anchor first-mover prescriber relationships. The state's Mental Health Commission funds regional workforce training to address psychiatric nurse scarcity across the Perth-to-Bunbury corridor. The Pilbara and Kimberley regions face cold chain integrity challenges for biologic depot distribution.
South Australia
Adelaide's northern suburbs concentrate community mental health team caseloads driving chronic schizophrenia maintenance volumes. The state's SA Health embeds Bluetooth-enabled adherence monitoring within supported accommodation programs. The Adelaide Hills and Fleurieu Peninsula regions extend telehealth medication management into areas below psychiatrist-to-population ratio thresholds.
Australia Schizophrenia Drugs Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light formulation specialists across Australia's schizophrenia drug supply base. The market structure consolidates around multinational sponsors with polymer matrix engineering capabilities and domestic distributors navigating PBS reimbursement complexity. Three archetypes dominate: established atypical antipsychotic brand holders, long-acting injectable technology leaders, and generic oral formulation commoditizers. Competitive moves center on real-world evidence generation for hospital formulary defense and strategic partnerships with community mental health networks.
Within the multinational sponsor tier, Johnson & Johnson and Eli Lilly and Company exemplify divergent positioning strategies. Johnson & Johnson anchors premium positioning through depot formulation portfolio depth in chronic care settings. Eli Lilly and Company occupies a position tied to hospital formulary access via specialized mental health center partnerships. Alkermes PLC represents the technology-specialist archetype, differentiating through sustained-release engineering capabilities rather than primary care brand recognition.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Eli Lilly and Company |
| Alkermes PLC |
| AstraZeneca PLC |
| Otsuka Pharmaceutical |
| AbbVie Inc. |
| Pfizer Inc. |
| H. Lundbeck AS |
| Bristol-Myers Squibb |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient procurement costs for atypical antipsychotics flow from Indian and Chinese contract manufacturers through PBS reimbursement tiers, compressing generic oral formulation margins while sustaining premium pricing for polymer matrix depot products in chronic care settings.
Pricing Analysis
The bundled medication management fee model separates pharmaceutical reimbursement from nurse practitioner administration charges across Australian community mental health services. Price differentiation rests on formulation complexity and cold chain requirements, with depot formulations commanding premium positioning over commoditized oral tablets. Cost compression in generic risperidone and olanzapine segments is intensifying due to PBS price disclosure mechanisms. Public hospital procurement committees exhibit lowest price sensitivity, while community pharmacies face margin pressure from dispensing fee constraints.
Supply Chain Analysis
Dual-sourcing requirements for critical antipsychotic APIs mandate qualification of both Indian and Chinese contract manufacturers to mitigate geopolitical disruption exposure. Raw material dependencies center on dopamine receptor ligand precursors, polymer matrix excipients, and sterile packaging components. Single-source vulnerability concentrates in specialized depot formulation technology held by limited polymer engineering specialists. Distribution runs through hospital pharmacy committees for inpatient volumes, with community mental health teams and accredited pharmacists handling outpatient depot administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia schizophrenia drugs market functions as a geographic-arbitrage play where TGA streamlined approval pathways and PBS reimbursement thresholds create faster market access than European EMA processes, rewarding sponsors with novel mechanisms.
For Market Incumbents: Deepen depot formulation portfolio breadth to defend against TAAR1 agonist entrants targeting metabolic side effect advantages. Secure psychiatric nurse practitioner training contracts across Western Australia and Queensland to lock in administration infrastructure. Vertical integration into polymer matrix engineering reduces exposure to single-source excipient suppliers. For New Entrants and Emerging Players: Community pharmacy networks present the most penetrable channel for pharmacist-administered depot programs under scope-of-practice expansion. Target the Perth-to-Bunbury corridor where psychiatric service density lags prescriber demand. Partner with telehealth-enabled outpatient clinics to bypass hospital formulary gatekeeping. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer matrix engineering capabilities concentrate among mid-cap formulation specialists lacking global distribution reach. Five-to-ten year viability favors sponsors with real-world evidence generation infrastructure for PBS reimbursement defense. Watch TGA novel mechanism approval velocity as inflection indicator for first-episode psychosis protocol disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Portfolio Expansion | Polymer matrix capabilities anchor premium positioning in Victoria and New South Wales community care networks. |
| PBS Reimbursement Strategy | Cost-effectiveness submissions determine formulary access for novel antipsychotics in Queensland public health services. |
| Psychiatric Nurse Practitioner Training Programs | Workforce development secures administration infrastructure for long-acting injectable uptake across regional Western Australia. |
| Telehealth-Integrated Medication Management | Remote adherence monitoring extends prescriber reach into South Australia and Tasmania rural catchments. |
| Pharmacogenomic Testing Partnership | Personalized dosing protocols address clozapine-resistant subpopulations in specialized Melbourne and Sydney clinics. |
Research Methodology
Multiple input streams — regulatory filings with TGA, PBS pricing and reimbursement databases, and hospital procurement records — were reconciled with primary interviews involving drug development executives, formulary directors at New South Wales and Victoria public health services, psychiatric nurse practitioners, and community pharmacy operators. Secondary validation drew from TGA registration databases, PBS Schedule listings, Australian Commission on Safety and Quality in Health Care standards, and state mental health commission annual reports. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis were cross-referenced to establish market sizing.
Data-stream reconciliation across drug type, indication, patient care setting, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of PBS expenditure patterns and depot formulation uptake curves in community mental health services. Forecast inputs incorporated psychiatric nurse practitioner workforce expansion projections and TGA expedited review pathway participation rates for novel mechanisms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PBS cost-effectiveness threshold adjustments and geopolitical API supply disruptions. Deviation in TGA approval timelines for muscarinic receptor modulators would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Cannabinoid Drugs Market