
 Fibroblast Growth Factor Receptor Inhibitor Market | 2026-2036
Fibroblast Growth Factor Receptor Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Fibroblast Growth Factor Receptor Inhibitor Market Foresight
Combination therapy bundling is shifting buyer choice in the FGFR inhibitor space as oncologists prefer regimens pairing targeted small molecules with checkpoint inhibitors over monotherapy. Pfizer leverages its oncology portfolio breadth to anchor combination trial design across multiple tumor types. Blueprint Medicines specializes in precision kinase inhibitors and sustains a differentiated position through biomarker companion diagnostic alignment. Incyte competes through geographic dominance in European oncology markets with established regulatory pathways.
Fibroblast Growth Factor Receptor inhibitors are small-molecule or biologic agents that selectively block tyrosine kinase activity at FGFR1, FGFR2, FGFR3, or FGFR4, interrupting downstream MAPK/PI3K signaling that drives tumor proliferation in FGFR-altered malignancies; they are manufactured through multi-step organic synthesis with chiral resolution or recombinant protein expression, depending on molecular format, and serve primarily to treat solid tumors harboring FGFR fusions or mutations. The oral delivery mode commands the largest patient volume due to outpatient convenience, while intravenous formulations retain higher per-dose pricing power in hospital infusion centers. Oncology dominates therapy area demand as FGFR alterations concentrate in urothelial, biliary, and endometrial cancers, though dermatology applications for FGFR-driven conditions represent an emerging expansion vector.
The FDA accelerates demand through its Breakthrough Therapy and accelerated approval designations for biomarker-selected populations, while the EMA's conditional marketing authorization pathway shapes European launch sequencing for novel FGFR agents. REACH compliance and ECHA substance registration requirements govern active pharmaceutical ingredient import and manufacturing site qualification across EU member states. Stakeholders must monitor evolving companion diagnostic co-development requirements and payer evidence thresholds for combination therapy reimbursement as the competitive set broadens beyond first-mover FGFR inhibitors.
Market Dynamics
The FGFR inhibitor market pivots on accelerated biomarker-driven trial designs that compress regulatory review timelines and reshape how oncology developers sequence indication expansion.
Growth Catalysts
- Accelerated Approval Pathway:The FDA's Breakthrough Therapy designation compresses development timelines for FGFR-altered malignancies, enabling earlier commercial access.
- Companion Diagnostic Alignment:NGS-based testing platforms identify FGFR2 fusions in cholangiocarcinoma, expanding addressable patient populations.
- Combination Therapy Demand:Oncology clinics increasingly bundle FGFR inhibitors with checkpoint inhibitors, creating protocol-driven volume expansion.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for kinase inhibitors clusters in select Asian contract manufacturers, creating single-source vulnerability.
- Reimbursement Friction:Medicare's evidence thresholds for precision oncology require companion diagnostic co-approval, delaying formulary placement.
- Resistance Mechanisms:Acquired FGFR kinase domain mutations limit duration of response, forcing continuous pipeline investment.
Strategic Opportunities
- Dermatology Expansion:FGFR-driven conditions like congenital melanocytic nevi represent untapped indications beyond oncology.
- EMA Conditional Authorization:The European pathway enables revenue generation during confirmatory trial completion.
- Oral Formulation Preference:Outpatient administration models capture patient volume from hospital-based infusion centers.
Industry Challenges
- Biomarker Testing Infrastructure:Community oncology practices lack standardized NGS workflows, creating patient identification bottlenecks.
- Cross-Resistance Profiling:Sequential FGFR inhibitor therapy requires complex molecular monitoring capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibroblast Growth Factor Receptor Inhibitor Market |
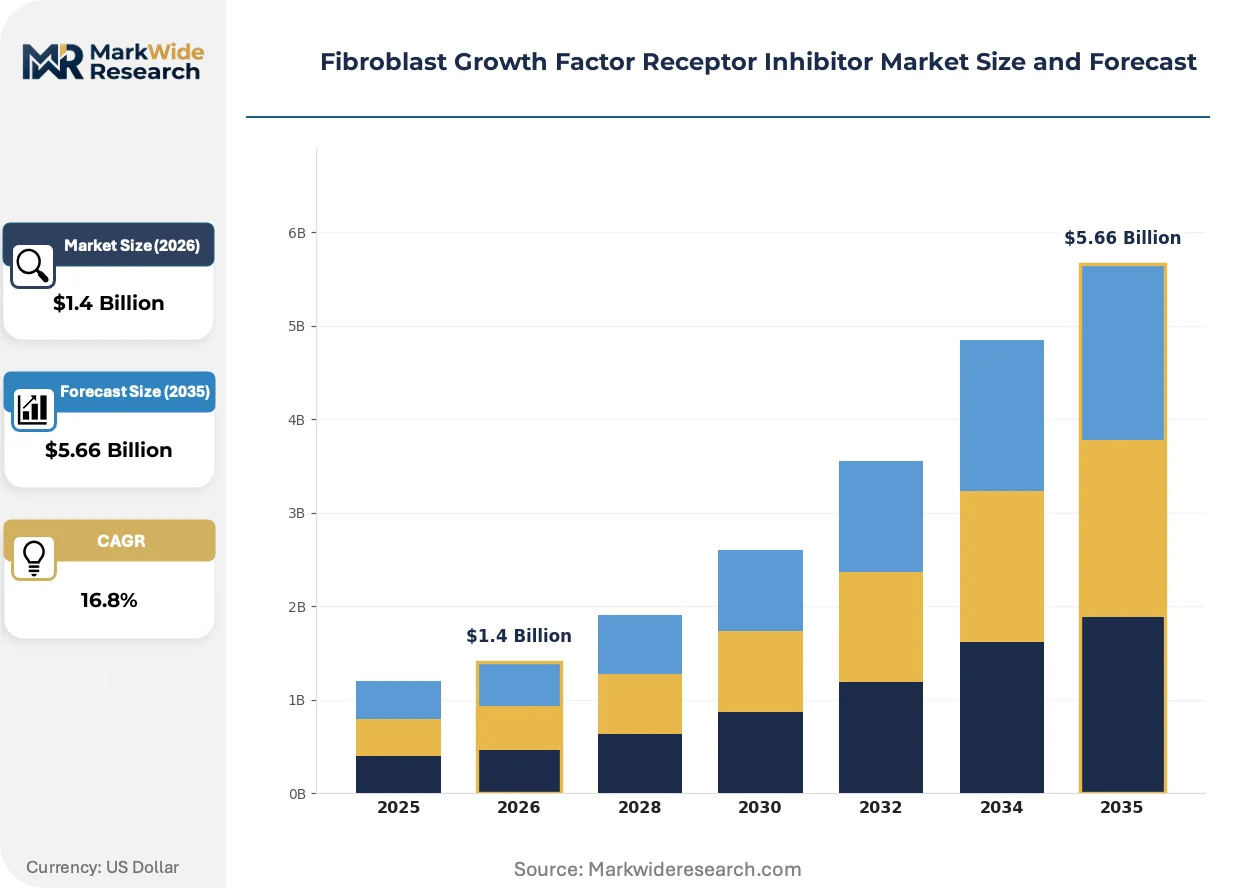
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.66 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pembrolizumab, Atezolizumab, Nivolumab, Dovitinib Therapy Area: Oncology, Dermatology, Cardiovascular, Neurology Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Research Institutions, Oncology Clinics, Pharmacies |
| Companies Covered | Pfizer, Blueprint Medicines, Boehringer Ingelheim, Janssen Pharmaceuticals, AstraZeneca, Novartis, Incyte, Johnson & Johnson, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibroblast Growth Factor Receptor Inhibitor Market Shifts & Advancements
Next-generation sequencing integration and selective irreversible inhibitor chemistry are compressing development cycles and expanding addressable mutation spectra.
Irreversible FGFR inhibitors are rewriting competitive positioning by targeting cysteine residues in the kinase ATP-binding pocket, overcoming resistance mutations that limit reversible agents. Academic medical centers are adopting these molecules in early-phase basket trials. The technology is rewriting durability expectations and forcing first-generation asset repositioning.
REACH substance registration requirements are governing EU manufacturing site qualification for FGFR inhibitor APIs, forcing supply chain reconfiguration. The regulation mandates full toxicological dossiers for imported active ingredients. European developers are responding by qualifying domestic synthesis capacity or securing ECHA-registered suppliers.
Site-of-care migration is shifting administration economics as oral FGFR inhibitors displace hospital infusion protocols. Community oncology networks are capturing patient volume previously retained by academic centers. This shift concentrates in the United States, where Medicare reimbursement differentials favor outpatient dispensing models.
Fibroblast Growth Factor Receptor Inhibitor Market Segmentation
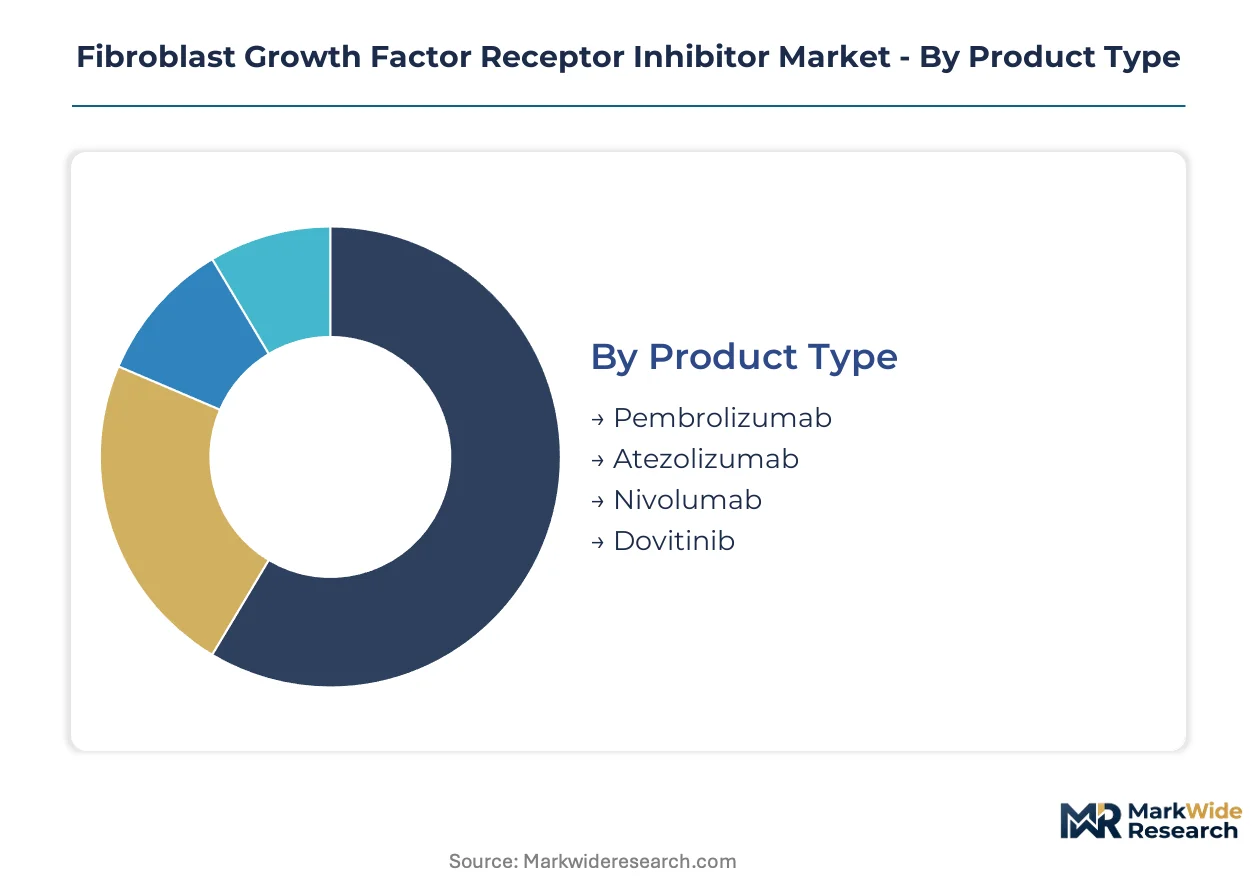
FGFR inhibitor segmentation reveals how formulation chemistry, administration logistics, and care setting economics fragment commercial opportunity. Developers must align molecule design with specific delivery infrastructure and reimbursement pathways to capture value.
Product Type:
Volume concentrates in checkpoint inhibitor combinations, while premium pricing attaches to selective small molecules with biomarker-defined indications.
- Pembrolizumab:Anti-PD-1 monoclonal antibody manufactured through recombinant DNA technology in Chinese hamster ovary cells. Demand clusters in combination protocols with FGFR inhibitors for urothelial carcinoma at Memorial Sloan Kettering and MD Anderson Cancer Center. FDA Breakthrough Therapy designation for FGFR-altered tumors compresses trial timelines.
- Atezolizumab:PD-L1 inhibitor engineered with Fc-engineered backbone to reduce antibody-dependent cytotoxicity. European oncology networks in Germany and France prefer this backbone for FGFR combination studies due to EMA's centralized marketing authorization pathway.
- Nivolumab:First-in-class PD-1 antagonist with established checkpoint inhibitor infrastructure across Japanese oncology centers.
- Dovitinib:Multi-kinase FGFR inhibitor with oral bioavailability and established cholangiocarcinoma data package.
Mature deployment sits with pembrolizumab. Newer deployment is concentrated in dovitinib as developers pursue selective FGFR inhibition strategies.
Therapy Area:
Application focus determines regulatory pathway selection and companion diagnostic investment intensity.
- Oncology:Solid tumors with FGFR2 fusions or FGFR3 mutations drive clinical development, with cholangiocarcinoma and urothelial carcinoma representing lead indications. NGS testing penetration at academic medical centers creates addressable patient identification infrastructure.
- Dermatology:Congenital melanocytic nevi and other FGFR-driven skin conditions represent expansion indications with lower competitive intensity. Pediatric dermatology centers at Boston Children's Hospital and Great Ormond Street Hospital are piloting topical FGFR inhibitor formulations.
- Cardiovascular:FGFR signaling in vascular remodeling creates mechanistic rationale for heart failure applications.
- Neurology:Blood-brain barrier penetration challenges limit CNS application development for FGFR-driven gliomas.
Oncology commands the deepest clinical infrastructure. Dermatology is gaining share fastest as topical delivery formats advance through formulation development.
Delivery Mode:
Patient convenience and site-of-care economics create divergent margin structures across administration formats.
- Oral:Small-molecule kinase inhibitors with once-daily dosing enable community oncology dispensing and Medicare Part D reimbursement. Outpatient administration avoids hospital facility fees that inflate infusion center costs.
- Intravenous:Monoclonal antibodies and antibody-drug conjugates require hospital-based administration with higher per-dose reimbursement rates. Academic medical centers retain this volume through specialized infusion protocols.
- Subcutaneous:Self-administration potential for maintenance dosing after IV induction is expanding in European homecare settings.
- Topical:Dermatology applications for FGFR-driven cutaneous lesions limit systemic exposure and enable localized therapy.
Intravenous retains the highest reimbursement rates. Oral formulations are expanding most quickly as community oncology networks capture volume from hospital-based centers.
End User:
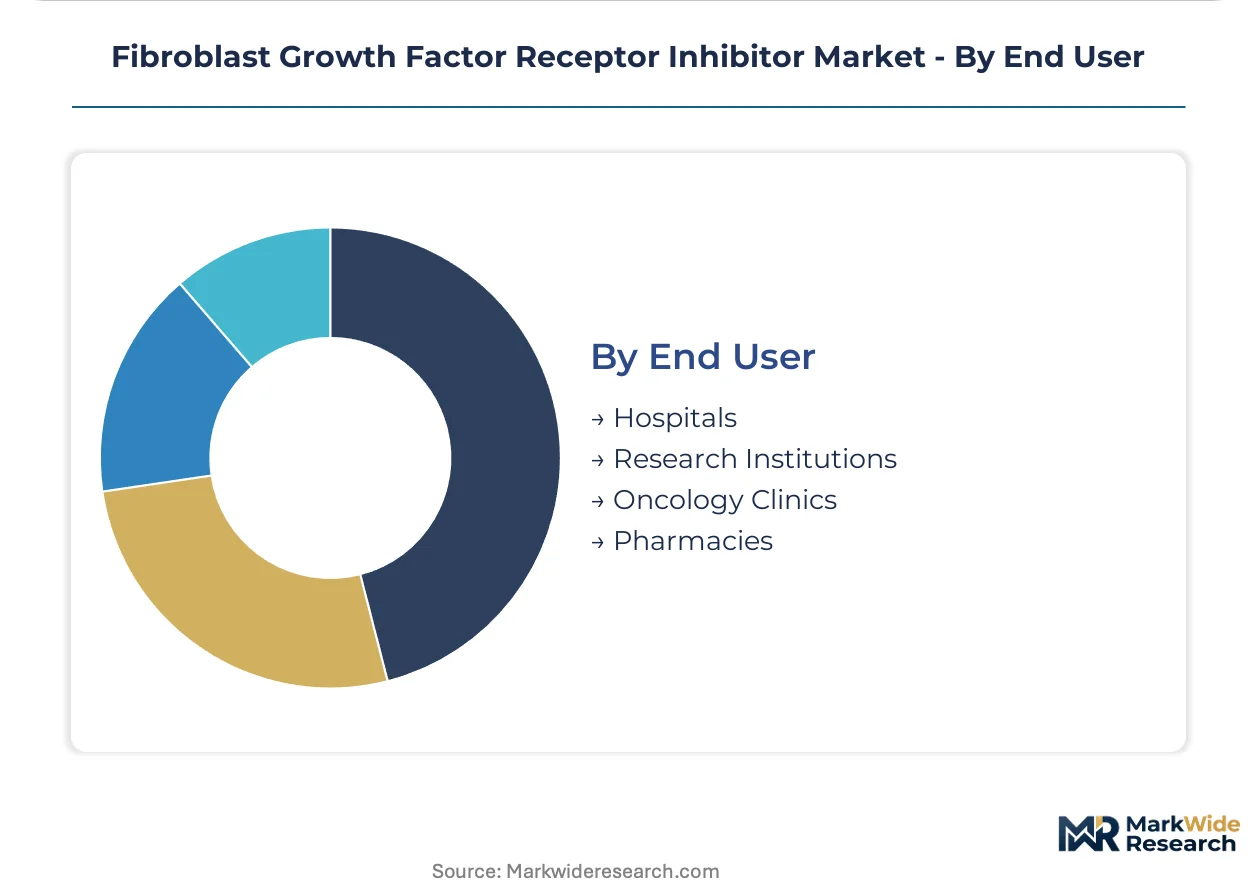
Procurement authority and prescribing influence fragment across institutional types with divergent formulary control mechanisms.
- Hospitals:Integrated delivery networks with 340B pricing access and captive specialty pharmacies dominate high-cost infused therapy administration. Medicare reimbursement differentials favor hospital outpatient departments for IV FGFR inhibitors.
- Oncology Clinics:Community-based practices with NGS testing partnerships identify biomarker-selected patients and dispense oral FGFR inhibitors through in-house pharmacies. United States volume concentrates in Florida, Texas, and Arizona networks.
- Research Institutions:Academic medical centers with early-phase trial infrastructure conduct basket studies for FGFR-altered rare tumors.
- Pharmacies:Retail and specialty pharmacy channels handle oral prescription fulfillment with prior authorization management.
Hospitals anchor infused therapy volume. Oncology clinics are capturing oral formulation share fastest through dispensing model economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FGFR inhibitor production concentrates in contract manufacturing clusters across Asia, while consumption and clinical trial activity concentrate in North American and European oncology centers. This geographic split shapes regulatory strategy and supply chain risk profiles for developers.
United States
Medicare reimbursement policies for precision oncology create favorable access conditions for approved FGFR inhibitors, with oncology clinics in Florida, Texas, and Arizona capturing patient volume through dispensing models. The FDA's Breakthrough Therapy designation compresses development timelines for biomarker-selected populations. Memorial Sloan Kettering and MD Anderson Cancer Center anchor combination therapy research in cholangiocarcinoma and urothelial carcinoma.
Germany
EMA centralized marketing authorization pathways enable streamlined European launch sequencing for novel FGFR agents, with German oncology networks preferring PD-L1 backbone combinations. REACH compliance and ECHA substance registration requirements govern active pharmaceutical ingredient import and manufacturing site qualification. The Heidelberg and Munich academic medical center clusters conduct basket trials for FGFR-altered rare tumors.
China
Domestic contract manufacturers supply active pharmaceutical ingredients for kinase inhibitors, creating single-source vulnerability amid concentrated production. NMPA regulatory pathways for innovative oncology drugs are accelerating biomarker-driven approval timelines. Shanghai and Suzhou biotech clusters are building companion diagnostic co-development capabilities for NGS-based FGFR fusion detection.
Japan
PMDA consultation programs for oncology drugs support early engagement on biomarker-selected trial designs, with Japanese oncology centers contributing to global checkpoint inhibitor combination studies. METI industrial policy incentivizes domestic pharmaceutical manufacturing capacity. The Tokyo and Osaka metropolitan areas host specialized infusion protocols for intravenous FGFR inhibitor administration.
United Kingdom
NHS England's Cancer Drugs Fund creates reimbursement pathways for precision oncology therapies pending full NICE appraisal, accelerating patient access to FGFR inhibitors. The MHRA operates post-Brexit recognition pathways for EMA-approved oncology products. London's Great Ormond Street Hospital and Cambridge oncology networks pilot pediatric dermatology applications for topical FGFR formulations.
Fibroblast Growth Factor Receptor Inhibitor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the FGFR inhibitor space, creating a tiered market structure with divergent resource allocation strategies. Large pharmaceutical companies leverage oncology portfolio breadth to anchor combination trial design, while precision kinase specialists sustain differentiation through biomarker alignment. Three archetypes dominate: diversified oncology majors with checkpoint inhibitor infrastructure, selective kinase inhibitors with companion diagnostic partnerships, and emerging biotechs with irreversible chemistry platforms. Competitive moves concentrate on M&A for pipeline assets and strategic partnerships for NGS testing integration.
Within the diversified oncology tier, Pfizer and AstraZeneca occupy positions anchored by broad immuno-oncology portfolios that enable combination protocol design. Among precision kinase specialists, Blueprint Medicines exemplifies the focused archetype through selective inhibitor development with aligned diagnostic strategies. Incyte sits within the geographic expansion specialist tier, leveraging established European regulatory pathways. These three represent distinct competitive positions without implying specific market shares or strategic actions.
| Leading Market Players |
|---|
| Pfizer |
| Blueprint Medicines |
| Boehringer Ingelheim |
| Janssen Pharmaceuticals |
| AstraZeneca |
| Novartis |
| Incyte |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| Others |
Supply & Pricing Matrix
Captive API synthesis partnerships in Suzhou and Hyderabad anchor supply positions for FGFR inhibitor developers, concentrating manufacturing leverage among contract manufacturers with ECHA-registered facilities and FDA-inspected sites. This integration choice locks in raw material access while enabling tiered pricing power based on regulatory qualification tiers.
Pricing Analysis
Margin tightening in oral small-molecule FGFR inhibitors reflects Medicare Part D reimbursement compression and 340B pricing differentials at hospital outpatient departments. Three-tier pricing structure across premium selective inhibitors, standard multi-kinase agents, and economy pipeline molecules separates reimbursement tiers by companion diagnostic alignment and indication breadth. Community oncology clinics exhibit highest price sensitivity due to dispensing model economics, while academic medical centers retain pricing tolerance for IV combination protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese contract manufacturers supplying chiral intermediates for FGFR kinase inhibitor synthesis. Active pharmaceutical ingredient production draws from facilities in Jiangsu province, Zhejiang province, and select Indian API hubs near Hyderabad. Tariff exposure on imported intermediates threatens margin structures for European and North American developers. Distribution runs through captive specialty pharmacy networks and hospital-based 340B programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FGFR inhibitor market sits in a technology-transition phase as irreversible covalent inhibitors displace first-generation reversible ATP-competitive agents. This chemistry shift demands repositioning of legacy assets and accelerated investment in resistance-mutation coverage.
For Market Incumbents: Deepen companion diagnostic co-development partnerships with NGS platform providers to lock in biomarker testing infrastructure. Anchor combination trial design with checkpoint inhibitor portfolios at Memorial Sloan Kettering and MD Anderson. Vertical integration into oral formulation manufacturing in New Jersey and North Carolina mitigates single-source API risk from Asian contract manufacturers.
For New Entrants and Emerging Players: Irreversible FGFR inhibitor chemistry serves as the technology-first wedge for differentiation against established reversible agents. Pediatric dermatology applications for congenital melanocytic nevi represent the most penetrable white-space indication with minimal competitive presence. Pursue EMA conditional marketing authorization pathways to generate revenue during confirmatory trial completion.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified oncology majors seeking precision kinase capabilities. Long-term viability hinges on pipeline depth addressing acquired resistance mutations and expansion beyond urothelial and biliary carcinomas. Watch FDA Breakthrough Therapy designation velocity as the signal for competitive inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | NGS alignment with Foundation Medicine and Guardant Health secures patient identification infrastructure. |
| Irreversible Inhibitor Chemistry Investment | Covalent binding platforms at Blueprint Medicines overcome resistance mutations limiting reversible agents. |
| EMA Conditional Authorization Pathway | European revenue generation during confirmatory trials compresses cash runway requirements. |
| Oral Formulation Manufacturing Scale-Up | New Jersey captive production reduces dependency on Chinese API contract manufacturers. |
| Dermatology Indication Expansion | Topical FGFR programs at Boston Children's Hospital open pediatric rare disease pathways. |
Research Methodology
FDA Breakthrough Therapy designation records, EMA centralized marketing authorization submissions, and ClinicalTrials.gov protocol databases formed the secondary backbone for this analysis. Primary interviews with oncology drug development executives, regulatory affairs leads at pharmaceutical sponsors, formulary directors at integrated delivery networks, and payer access specialists at Medicare Advantage plans validated pipeline timelines and reimbursement assumptions. Bottom-up patient volume estimates by indication and top-down market sizing by therapeutic area were triangulated to anchor projections.
Bottom-up modeling of addressable patient populations by FGFR alteration frequency and treatment line combined with top-down pharmaceutical revenue allocation by oncology segment. Segmentation dimensions across the projection horizon include administration route, biomarker selection methodology, regional regulatory cluster, and combination versus monotherapy protocol. CAGRs were derived from patient volume growth trajectories and pricing evolution assumptions. Forecast inputs incorporated NGS testing penetration rates at community oncology practices and Medicare reimbursement policy stability.
Several conditions sit outside the modeled scope, including pipeline attrition rates for early-phase FGFR programs and unforeseen resistance mechanism emergence. Forecasts reflect assumptions regarding FDA accelerated approval pathway continuity and EMA conditional authorization precedent stability. Deviation in biomarker testing infrastructure deployment at community oncology sites would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market