
 Pyrolysis Gas Market | 2026-2036
Pyrolysis Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrolysis Gas Market Analytics
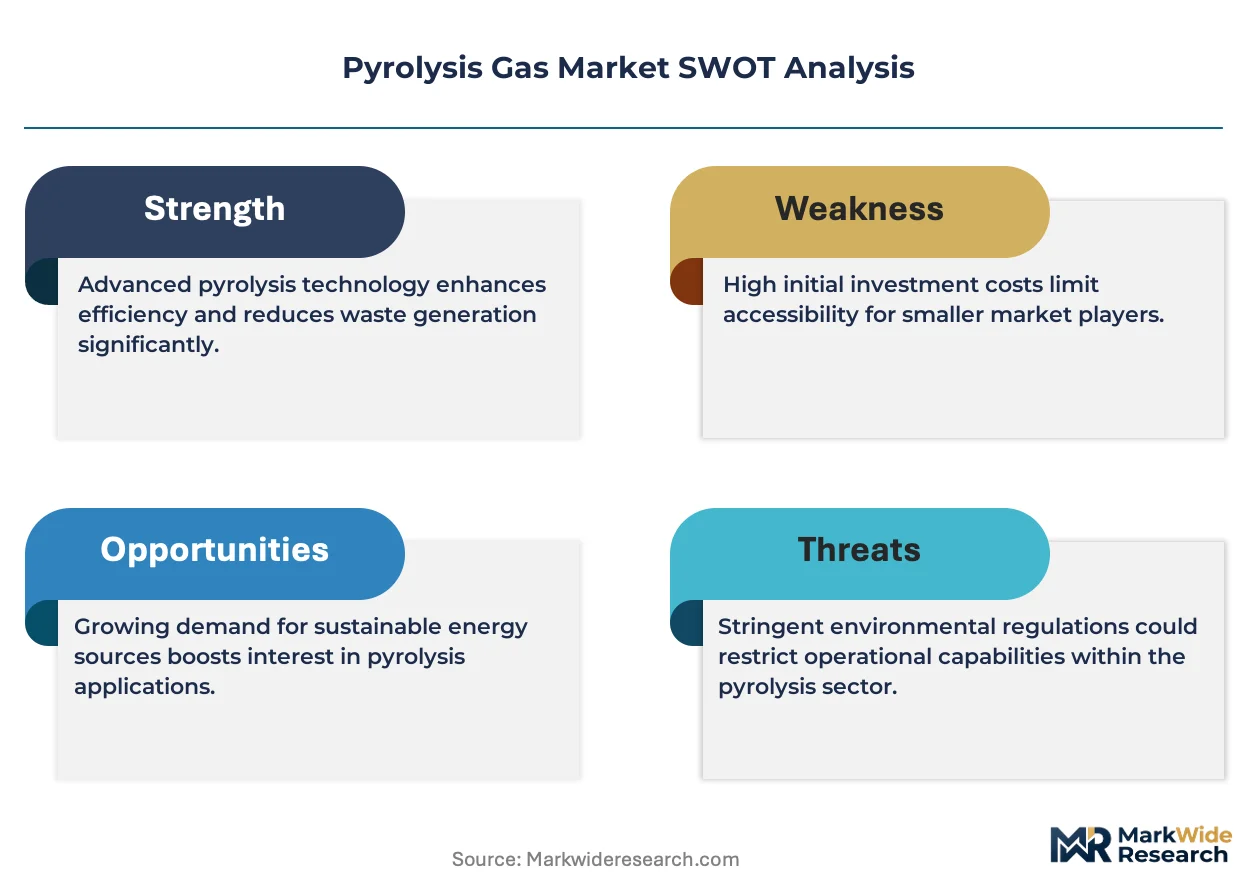
High-purity olefin-grade pyrolysis gas is rotating toward premium pricing as chemical manufacturers tighten feedstock specifications. Exxon Mobil Corporation leverages its integrated refining-petrochemical complexes to sustain captive pyrolysis gas output. Dow anchors North American supply through its Gulf Coast steam cracker network. Chevron Phillips Chemical Company differentiates via proprietary metathesis technology that upgrades pyrolysis gas into polymer-grade propylene.
Pyrolysis gas comprises volatile hydrocarbons generated through thermal decomposition of organic feedstocks at temperatures between 400°C and 800°C in oxygen-starved conditions, yielding a mixture rich in methane, ethylene, propylene, and heavier olefins that serve as chemical building blocks or fuel substitutes. The wood feedstock segment dominates current volumes due to established biomass supply chains, while the plastic feedstock segment captures expanding margin pools as mechanical recycling faces quality constraints. Continuous process technology leads capital deployment because of superior throughput economics, though batch process systems retain share in distributed waste-to-energy installations where feedstock variability is high.
The EPA enforces Renewable Fuel Standard compliance pathways that credit pyrolysis gas-derived fuels, while the EU Green Deal's waste hierarchy rules restrict landfill diversion and mandate chemical recycling quotas. India's BIS is drafting pyrolysis gas quality standards for industrial burner applications under its waste-to-energy mission. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost competitiveness of pyrolysis gas against naphtha-derived olefins.
Market Dynamics
Chemical manufacturers are tightening olefin-grade specifications faster than pyrolysis gas producers can upgrade purification trains, creating a structural bottleneck between feedstock supply and downstream qualification.
Growth Catalysts
- EU Green Deal waste hierarchy:The mandate restricting landfill diversion and establishing chemical recycling quotas pulls plastic-derived pyrolysis gas into formal olefin supply chains. Industrial clusters near Rotterdam now integrate pyrolysis units with steam crackers.
- Biomass supply chain maturity:Established wood pellet logistics in Scandinavia and the US Southeast reduce feedstock procurement friction for thermal decomposition units. Wood-derived pyrolysis gas volumes scale without virgin infrastructure investment.
- Continuous process technology:Superior throughput economics versus batch systems attract capital deployment from chemical manufacturers seeking captive olefin supply. Throughput advantages compound across integrated refining-petrochemical complexes.
Market Restraints
- Natural gas price volatility:Input cost swings for hydrogen and process heat compress margins for pyrolysis gas producers competing against naphtha-derived olefins. US Gulf Coast pricing transmits directly to production economics.
- German industrial cluster concentration:Demand gravity centers on the Rhine-Ruhr corridor and Rotterdam hinterland, creating geographic supply risk. Logistic bottlenecks at the Port of Rotterdam constrain feedstock import flexibility.
- Contamination thresholds in plastic feedstocks:Mechanical recycling quality constraints limit available pyrolysis-ready plastic waste. Halogenated and mixed-polymer streams require pre-treatment capital that distributed operators cannot deploy.
Strategic Opportunities
- India's waste-to-energy mission:BIS quality standards for industrial burner applications open a regulatory pathway for pyrolysis gas in captive power and process heat. Early movers establish feedstock collection networks before standards finalize.
- Carbon border adjustment mechanisms:The EU CBAM redefines cost competitiveness against naphtha-derived olefins by internalizing embodied carbon. Pyrolysis gas from biomass and plastic waste feedstocks captures preferential treatment.
- Metathesis technology convergence:Proprietary catalyst systems upgrading pyrolysis gas into polymer-grade propylene unlock premium chemical value chains. Technology licensors can wedge into olefin supply gaps left by conventional steam cracker constraints.
Industry Challenges
- Feedstock certification timelines:ISCC PLUS and RSB traceability standards require 12-18 month qualification cycles for pyrolysis gas producers. Auditing bottlenecks delay offtake agreements with brand-owner chemical purchasers.
- Process control engineering scarcity:Operators lack personnel skilled in oxygen-starved reactor management at 400-800°C operating windows. Training programs have not kept pace with unit commissioning schedules.
- Legacy steam cracker integration:Retrofitting 1960s-era Gulf Coast crackers to accept pyrolysis gas feedstock requires furnace metallurgy upgrades and burner modifications. Engineering complexity extends payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrolysis Gas Market |
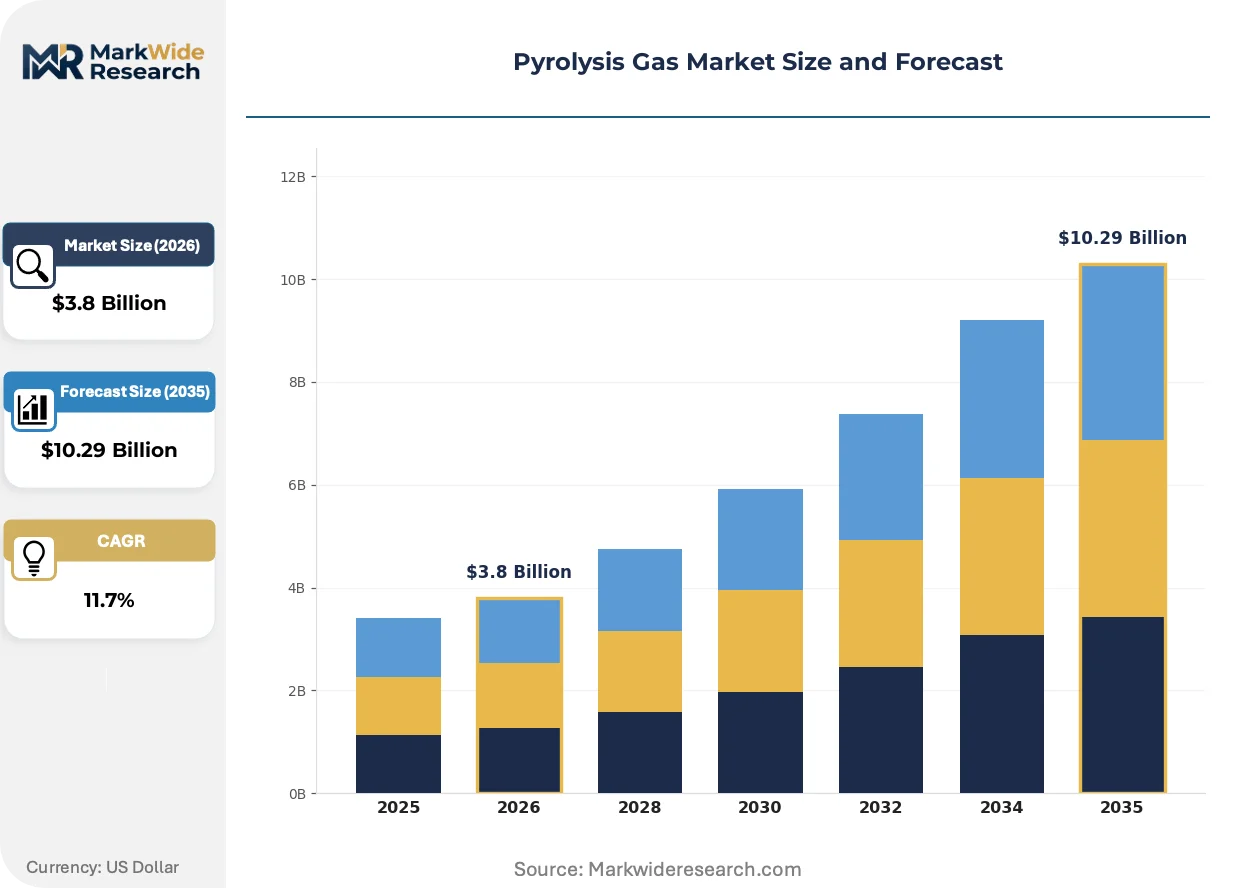
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Wood, Plastic, Rubber, Agricultural Residue End User: Energy Sector, Chemical Manufacturers, Waste Management, Transportation Technology: Batch Process, Continuous Process, Indirect Heating, Direct Heating Application: Fuel Production, Chemical Synthesis, Carbon Black Production, Oil Recovery |
| Companies Covered | ONGC Petro additions Limited, Chevron Phillips Chemical Company, Exxon Mobil Corporation, Axens, Dow, Shell, Haldia Petrochemicals Limited, TotalEnergies, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrolysis Gas Market Evolving Landscape
Thermal decomposition technology is advancing on three fronts: reactor design precision, regulatory recognition of chemical recycling pathways, and buyer consolidation around certified sustainable olefins. These forces are compressing the gap between waste feedstock and chemical-grade output.
Plasma-assisted pyrolysis is decomposing mixed plastic waste at higher energy efficiency than conventional heated reactors. Chemical manufacturers in Germany and the Netherlands are piloting units at 10-50 tonne per day scale. The technology is decomposing technical barriers to halogenated feedstock processing that previously excluded PVC-rich waste streams from chemical recycling.
The EU Green Deal's waste-to-energy mandates are tightening feedstock traceability requirements beyond current voluntary certification schemes. Industrial clusters must document mass balance across pyrolysis, upgrading, and olefin production stages. German chemical parks and Rotterdam-area refiners are investing in blockchain-tracked custody systems to satisfy upcoming delegated acts under the Renewable Energy Directive.
Buyers are consolidating procurement around vertically integrated suppliers with captive pyrolysis gas production. Long-term offtake agreements now specify olefin-grade purity thresholds and ISCC certification rather than commodity spot pricing. This pattern concentrates most visibly among polyethylene producers on the US Gulf Coast and in the ARA refining hub, where supply security outweighs marginal cost savings from fragmented sourcing.
Pyrolysis Gas Market Segmentation
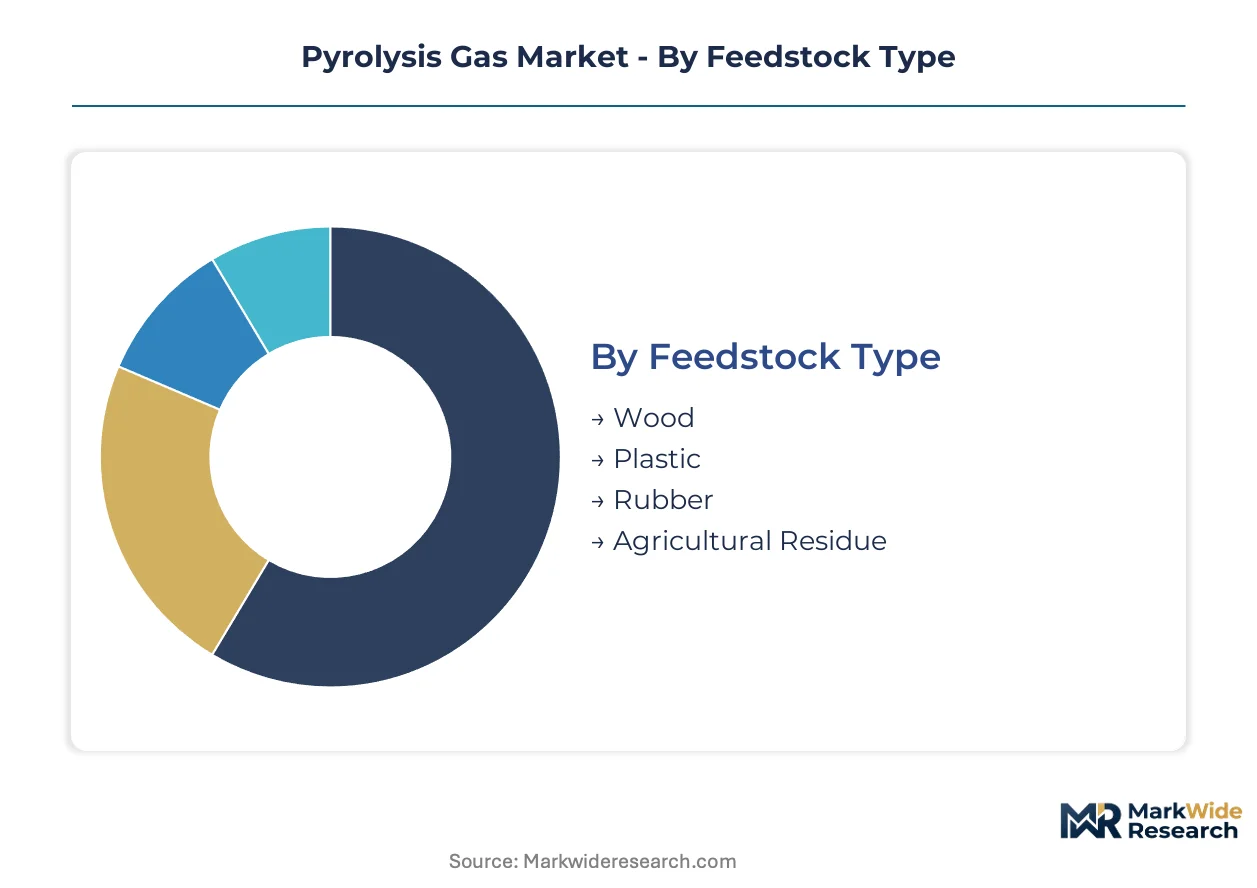
Feedstock variability and purification requirements fragment the Pyrolysis Gas Market into distinct supply tiers. Chemical manufacturers select segments based on olefin-grade specifications and ISCC PLUS certification status.
Feedstock Type:
EU Green Deal waste hierarchy rules differentiate feedstock eligibility for chemical recycling quotas, creating tiered compliance pathways.
- Wood:Established biomass supply chains in Scandinavia and the US Southeast deliver consistent moisture-controlled feedstock. Chemical manufacturers in Germany favor wood-derived pyrolysis gas for its low halogen content and predictable olefin yields.
- Plastic:Mixed-polymer streams require pre-treatment to meet contamination thresholds, yet Rotterdam-area industrial clusters now integrate plastic-fed pyrolysis units with steam crackers to satisfy landfill diversion mandates.
- Rubber:Tire-derived feedstock yields higher sulfur content requiring dedicated upgrading trains.
- Agricultural Residue:Seasonal availability and collection logistics constrain scale-up beyond distributed waste-to-energy installations.
Wood handles the majority of throughput; Plastic is the fastest mover on share.
End User:
Procurement patterns diverge between spot-market fuel buyers and long-term offtake agreements from integrated chemical producers.
- Chemical Manufacturers:Dow and Exxon Mobil Corporation anchor demand through captive pyrolysis gas production at Gulf Coast refining-petrochemical complexes, specifying polymer-grade propylene purity thresholds.
- Energy Sector:Industrial burner applications in India's waste-to-energy mission drive BIS quality standard development for process heat substitution.
- Waste Management:Municipal operators prioritize batch process flexibility over olefin-grade output.
- Transportation:EPA Renewable Fuel Standard compliance pathways credit pyrolysis gas-derived transport fuels.
Chemical Manufacturers command the largest volume commitments; Energy Sector procurement is climbing the fastest.
Technology:
Capital deployment favors throughput economics over distributed deployment flexibility.
- Continuous Process:Superior reactor utilization rates attract investment from chemical manufacturers seeking captive olefin supply at Rotterdam and US Gulf Coast hubs.
- Batch Process:Lower capital barriers suit waste-to-energy operators handling variable feedstock quality in distributed installations.
- Indirect Heating:Temperature control precision reduces tar formation in oxygen-starved conditions.
- Direct Heating:Simpler reactor architecture trades energy efficiency for equipment cost reduction.
Continuous Process dominates capital flows; Batch Process retains share in feedstock-variable environments.
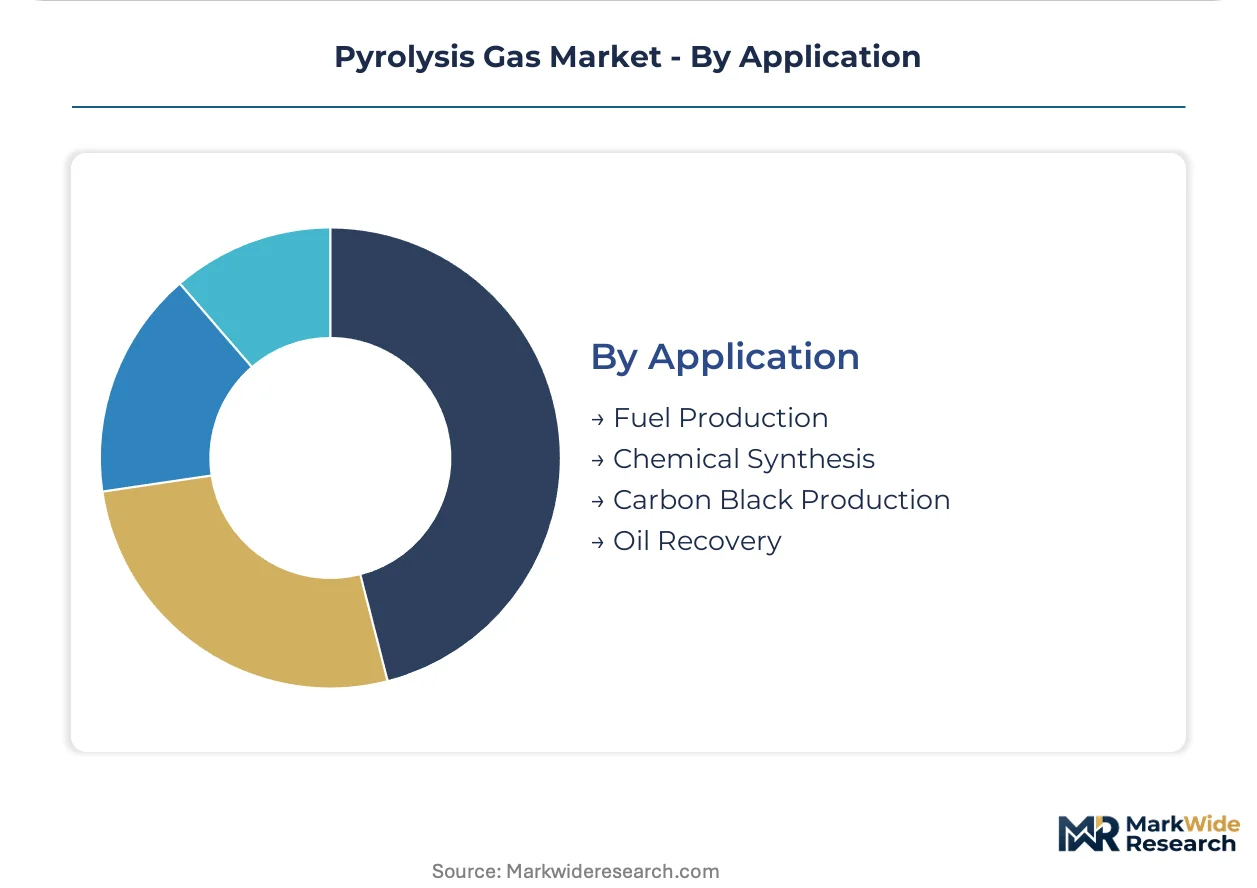
Application:
Carbon border adjustment mechanisms revalue applications by embodied carbon intensity.
- Chemical Synthesis:Polymer-grade propylene and ethylene production commands premium pricing as EU CBAM internalizes carbon costs against naphtha-derived alternatives.
- Fuel Production:EPA RFS compliance and EU Renewable Energy Directive delegated acts create regulatory demand for pyrolysis gas-derived transport and industrial fuels.
- Carbon Black Production:Rubber recycling integration yields recovered carbon black for tire manufacturing.
- Oil Recovery:Enhanced oil recovery applications face margin pressure from electrification trends.
Chemical Synthesis captures the highest value per tonne; Fuel Production shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor established chemical clusters with integrated pyrolysis capacity, while emerging markets build domestic supply chains to reduce feedstock dependence. The Netherlands and Germany run structural deficits in olefin-grade pyrolysis gas, pulling volumes through Rotterdam's port infrastructure. India's waste-to-energy mission is catalyzing import substitution through localized production.
Germany
Chemical manufacturers along the Rhine-Ruhr corridor anchor European demand for polymer-grade pyrolysis gas. The EU Green Deal's waste hierarchy rules mandate chemical recycling quotas that pull plastic-derived feedstock into formal supply chains. Industrial parks near Cologne and Leverkusen now integrate pyrolysis units with downstream steam crackers.
United States
Gulf Coast refining-petrochemical complexes sustain captive pyrolysis gas production for integrated olefin supply. EPA Renewable Fuel Standard compliance pathways credit pyrolysis gas-derived fuels, creating regulatory pull for waste-to-energy investments. Houston and Corpus Christi host the densest concentration of continuous-process units.
India
BIS quality standards for industrial burner applications are opening regulatory pathways for pyrolysis gas in captive power and process heat substitution. The waste-to-energy mission prioritizes distributed production near urban plastic waste generation centers. Gujarat and Maharashtra industrial corridors are commissioning pilot units ahead of standard finalization.
Netherlands
Rotterdam's port infrastructure serves as the primary import gateway for pyrolysis gas feedstock into northwest European chemical manufacturing. EU delegated acts under the Renewable Energy Directive tighten mass balance documentation requirements across the value chain. Chemical parks in the Rotterdam-Moerdijk cluster invest in blockchain-tracked custody systems.
Saudi Arabia
SABIC's integrated petrochemical complexes explore pyrolysis gas as a diversification feedstock alongside conventional naphtha cracking. The Kingdom's circular carbon economy framework incentivizes chemical recycling investments. Jubail Industrial City hosts pilot projects linking plastic waste collection to olefin production.
Pyrolysis Gas Market Competitive Landscape
Concentration sits with integrated petrochemical majors that control captive pyrolysis gas output through refining-petrochemical complex ownership. The competitive terrain splits between scale-driven operators with proprietary upgrading technology and regional specialists securing feedstock collection networks. Two strategic archetypes dominate: vertically integrated oil majors leveraging existing infrastructure, and technology licensors deploying proprietary catalyst systems. Capacity expansion and strategic partnerships constitute the primary competitive moves, with operators racing to secure long-term offtake agreements ahead of carbon border adjustment mechanism implementation.
Among integrated oil majors, Exxon Mobil Corporation and Shell exemplify the archetype of captive supply control through Gulf Coast and Rotterdam-area refining-petrochemical complexes. Chevron Phillips Chemical Company occupies a distinct position through proprietary metathesis technology licensing. Dow anchors North American supply security through its steam cracker network. ONGC Petro additions Limited represents state-backed vertical integration into olefin production. Technology specialists including Axens sit within the licensing tier, deploying reactor and catalyst packages without direct feedstock exposure.
| Leading Market Players |
|---|
| ONGC Petro additions Limited |
| Chevron Phillips Chemical Company |
| Exxon Mobil Corporation |
| Axens |
| Dow |
| Shell |
| Haldia Petrochemicals Limited |
| TotalEnergies |
| SABIC |
| Others |
Value Network & Pricing Analysis
Biomass-to-olefin substitution is compressing naphtha-derived feedstock margins while redrawing procurement geography toward Rotterdam and US Gulf Coast clusters. This feedstock pivot simultaneously concentrates buyer power among integrated chemical manufacturers and fragments spot-market pricing for uncertified volumes.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that specify ISCC PLUS certification tiers and polymer-grade purity thresholds. Price differentiation rests on feedstock traceability grade and volume scale, with certified biomass-derived pyrolysis gas commanding premium positioning over plastic-waste alternatives. Cost compression in standard-grade volumes is intensifying because natural gas price volatility transmits directly to hydrogen and process heat inputs. Municipal waste-to-energy operators exhibit highest price sensitivity due to distributed scale constraints, while Dow and Exxon Mobil Corporation demonstrate lowest sensitivity through captive supply integration.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for plastic waste feedstock imports. Supply concentrates in Germany, the United States, and the Netherlands, with raw material dependencies spanning wood pellet networks, mixed-polymer waste streams, and natural gas for process heat. Single-source vulnerability sits with German industrial clusters dependent on Rotterdam gateway infrastructure. Distribution runs through integrated refining-petrochemical complexes rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with certification-tier differentiation as EU Green Deal waste hierarchy rules create parallel compliance pathways for biomass versus plastic-derived supply.
For Market Incumbents: Fortify captive supply positions through backward integration into wood pellet procurement networks in Scandinavia and the US Southeast. Invest in ISCC PLUS certification infrastructure ahead of delegated act finalization under the EU Renewable Energy Directive. Defend margin position by locking 10-15 year offtake agreements with polyethylene producers before carbon border adjustment mechanisms reshape cost competitiveness. For New Entrants and Emerging Players: Lead with distributed waste-to-energy installations in India's Gujarat and Maharashtra corridors ahead of BIS quality standard finalization. Target plastic feedstock pre-treatment capabilities as the most penetrable white-space, given mechanical recycling quality constraints that exclude halogenated streams from chemical recycling. Deploy plasma-assisted pyrolysis licensing partnerships as the go-to-market angle for mixed-polymer processing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed technology licensors holding proprietary metathesis catalyst packages for polymer-grade propylene upgrading. Five-to-ten year viability hinges on carbon border adjustment mechanism implementation timelines and the pace of steam cracker retrofit engineering. Watch for inflection in long-term offtake agreement pricing spreads between certified and uncertified pyrolysis gas tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Secures wood pellet supply chains in Scandinavia against Rotterdam logistics bottlenecks. |
| ISCC PLUS Certification Investment | Unlocks EU Green Deal chemical recycling quota compliance for German chemical manufacturers. |
| Plasma-Assisted Pyrolysis Licensing | Enables halogenated plastic waste processing that conventional heated reactors cannot handle. |
| Long-Term Offtake Agreement Structuring | Locks in polymer-grade propylene pricing ahead of carbon border adjustment mechanism phase-in. |
| Rotterdam Port Infrastructure Partnership | Reduces feedstock import delays through dedicated pyrolysis gas handling capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant managers at continuous-process pyrolysis units, procurement leads at Gulf Coast steam crackers, distribution channel partners handling wood pellet logistics, and technical R&D directors developing metathesis catalyst systems. Secondary validation drew from EU delegated acts documentation, EPA Renewable Fuel Standard compliance pathways, SEC 10-K filings from integrated petrochemical majors, and customs data tracking biomass feedstock flows. Bottom-up unit economics triangulated against top-down olefin demand projections.
Across the analysis window, the forecasting framework modeled feedstock type segmentation, end-user industry concentration, technology deployment scale, and regional regulatory cluster intensity. CAGRs were derived from installed capacity buildout trajectories and olefin-grade purity threshold adoption curves. Key inputs included natural gas price volatility assumptions, EU CBAM carbon cost pass-through rates, and ISCC PLUS certification timeline distributions.
Underlying assumptions cover continuous process technology cost curves and EU Green Deal implementation sequencing, with deviation risk concentrated in feedstock certification auditing bottlenecks and plasma-assisted pyrolysis scale-up engineering. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India LNG Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Japan Bunker Fuel Market
Fuels
Brazil Bunker Fuel Market
Fuels
Mobile Gas Pumping System Market
Fuels
Wood Charcoal Market
Fuels
North America Bunker Fuel Market
Fuels
CNG Dispenser Market
Fuels
Bunker Fuel Market
Fuels
Europe Bunker Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Europe Gas Market
Fuels
Brazil LNG Market
Fuels
Global Steam Coal Market
Fuels
Anthracite Coal Mining Market