
 United Kingdom Bunker Fuel Market | 2026-2036
United Kingdom Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Bunker Fuel Market Analytics
ISO 8217 fuel quality certification is rotating the competitive set as British port authorities enforce stricter testing protocols for residual fuel deliveries. BP PLC leverages its integrated refining and terminal network along the Thames and Humber to sustain supply continuity for deep-sea vessels. Shell Marine Products Ltd anchors its position through dedicated bunker barges serving Southampton and Liverpool. Maritime Bunkering Ltd competes via specialized MDO distribution to offshore support fleets in Aberdeen.
United Kingdom bunker fuel denotes marine residual and distillate products meeting ISO 8217 viscosity, density, and sulfur specifications, blended from vacuum residues and cutter stocks to power two-stroke diesel engines aboard ocean-going vessels. The fuel type dimension shows LSFO commanding margin pools as ship operators abandon HSFO following IMO sulfur regulations, while MDO retains niche value for coastal and naval applications. Distribution channel structure favors bunker barges for their cargo-transfer efficiency at anchorage points, though import terminals at Immingham and Fawley absorb volume spikes during refinery maintenance cycles.
The Maritime and Coastguard Agency enforces bunkering standards under UK flag-state authority, while the Environment Agency monitors spill-response readiness at marine fueling points. These frameworks compel operators to maintain segregated low-sulfur storage and document every custody transfer. Stakeholders must track how the EU Emissions Trading System's maritime inclusion reshapes fuel economics for vessels calling at British ports.
Market Dynamics
IMO 2020 sulfur regulations have permanently altered the United Kingdom bunker fuel landscape by mandating low-sulfur formulations and forcing capital reallocation across storage, blending, and distribution infrastructure. Refineries serving British terminals now operate under fundamentally different margin economics than the pre-regulation era.
Growth Catalysts
- EU Emissions Trading System maritime inclusion:British port calls now face carbon pricing exposure, accelerating demand for verified low-carbon fuel alternatives and incentivizing vessel operators to optimize bunker procurement timing.
- Container shipping lines:Deep-sea carriers operating Felixstowe and Southampton rotations are expanding fleet capacity on UK-Europe routes, directly lifting marine fuel offtake volumes at Thames and Solent supply points.
- ISO 8217:2017 quality specifications:Stricter testing protocols for density, viscosity, and sulfur content are standardizing fuel certification across British terminals, reducing off-spec disputes and smoothing custody transfers.
Market Restraints
- Crude oil price volatility:Vacuum residue feedstock costs swing bunker blend economics unpredictably, compressing supplier margins during upstream price spikes and complicating term contract pricing.
- Refinery concentration on the Continent:British terminals depend heavily on Rotterdam and Antwerp supply corridors, creating single-point vulnerability during Northwest European maintenance turnarounds or transit disruptions.
- Limited domestic refining capacity:Fawley and Grangemouth output insufficiently covers national marine fuel demand, necessitating import dependence that amplifies currency and logistics exposure.
Strategic Opportunities
- Scottish offshore support vessels:Aberdeen harbor and Peterhead terminals service North Sea oil platform logistics fleets with specialized MDO requirements, a niche segment with premium pricing tolerance.
- Biofuel blending mandates:The UK Renewable Transport Fuel Obligation creates compliance credit value for marine bio-component incorporation, rewarding early movers in BDN-documented sustainable fuel supply.
- Digital bunker trading platforms:Real-time price discovery and stem optimization tools are penetrating shipowner procurement departments, opening channel disruption potential against traditional broker networks.
Industry Challenges
- Segregated storage infrastructure:Terminal operators must maintain physically separate tanks for VLSFO, HSFO, and MDO grades, multiplying capex requirements and complicating inventory management at capacity-constrained sites.
- Mass flow meter certification:The Maritime and Coastguard Agency's enforcement of accurate quantity measurement creates compliance timeline pressure for barge operators retrofitting older transfer equipment.
- Marine fuel chemist shortage:Specialized laboratory capacity for ISO 8217 full-parameter testing is concentrating in a handful of UK service providers, creating bottleneck risk for rapid turnaround certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Bunker Fuel Market |
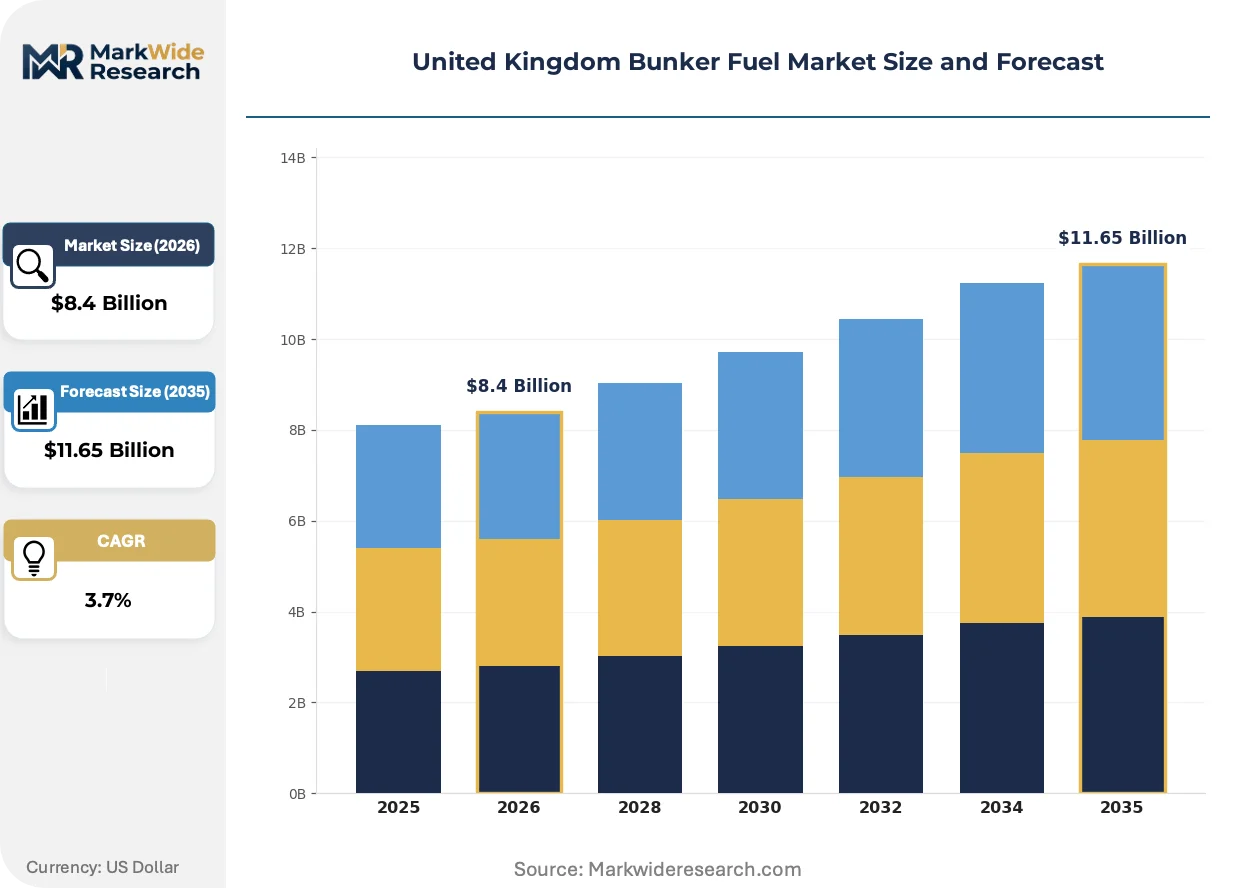
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.65 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: HSFO, LSFO, MDO, Marine Gas Oil Distribution Channel: Direct Supply, Bunker Barges, Import Terminals, Onshore Facilities Application: Shipping, Maritime Transport, Offshore Operations, Naval Customer Segment: Ship Owners, Operators, Supply Companies, Charterers |
| Companies Covered | Phillips 66, Maritime Bunkering Ltd, GB Oils Ltd, Shell Marine Products Ltd, Exxon Mobil Corporation, ConocoPhillips Ltd, BP PLC, Greenergy International Ltd, Mærsk A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Bunker Fuel Market Evolving Landscape
Digital instrumentation and alternative fuel pathways are restructuring how marine fuel moves from refinery gate to vessel manifold across British waters. Three developments merit particular attention.
Mass flow meters with real-time density compensation are displacing traditional volumetric measurement systems in bunker barge operations. Shipowners operating UK-flagged and UK-calling fleets are mandating MFM-equipped suppliers to eliminate quantity disputes and accelerate stem completion. This technology is compressing the competitive position of barge operators unable to fund retrofit capital, concentrating supply relationships toward equipped vendors.
The EU Emissions Trading System's phased maritime inclusion imposes carbon allowance obligations on vessels above five thousand gross tonnage calling at British ports. Ship operators now face direct cost exposure for CO2 emitted during UK port stays and adjacent waters, redirecting procurement attention toward lower-carbon fuel alternatives and voyage optimization. Container lines with regular Felixstowe and Southampton rotations are most affected, adjusting scheduling and slow-steaming practices to minimize allowance purchases.
Consolidation among shipowner procurement departments is concentrating bunker buying power into fewer hands with sophisticated analytics capabilities. Large container carriers and dry bulk operators are internalizing fuel purchasing functions previously outsourced to specialized traders, deploying proprietary price forecasting and inventory optimization models. This behavioral shift is most visible among London-headquartered ship management companies serving global fleets, where in-house trading desks now rival traditional marine fuel brokers in transaction volume.
United Kingdom Bunker Fuel Market Segmentation
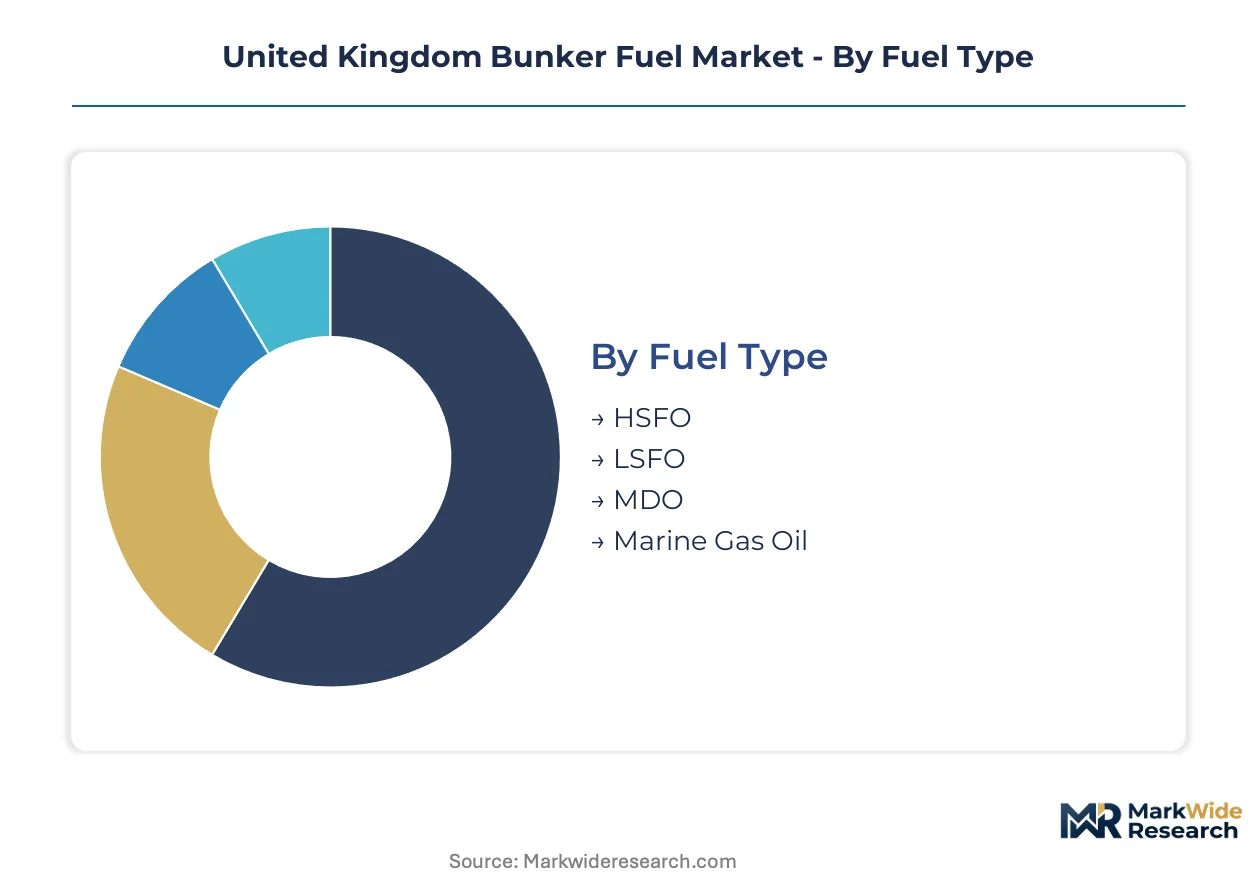
Marine fuel procurement in British waters fragments across multiple technical and commercial dimensions. Each segmentation axis carries distinct margin profiles, regulatory exposure, and infrastructure requirements that shape supplier strategy and buyer behavior.
Fuel Type:
Channel allocation varies sharply by sulfur content and viscosity grade, with high-volume residual fuels moving through barge networks while specialized distillates route through dedicated terminal infrastructure.
- LSFO:Low-sulfur residual formulations meeting ISO 8217 sulfur caps dominate procurement at Thames and Solent anchorages. Container lines operating Felixstowe rotations have standardized on this grade to comply with IMO 2020 regulations and EU Emissions Trading System exposure.
- HSFO:High-sulfur residual fuel retains viability only for vessels equipped with exhaust gas cleaning systems. Demand concentrates among bulk carriers with scrubber installations calling at Immingham and Fawley.
- MDO:Marine diesel oil serves coastal traffic and offshore support fleets with stricter emission requirements. Aberdeen harbor terminals maintain dedicated MDO storage for North Sea platform logistics.
- Marine Gas Oil:Distillate fuel with lower viscosity and sulfur content supports naval applications and high-speed craft. Royal Navy procurement at Portsmouth and Devonport anchors this segment.
LSFO dominates installed base across deep-sea rotations. MDO is where expansion concentrates for offshore and coastal applications.
Distribution Channel:
Cost tier separation is pronounced, with barge delivery commanding premium pricing for convenience while terminal offtake offers volume discounts for buyers with storage flexibility.
- Bunker Barges:Floating delivery vessels transfer fuel at anchorage points, eliminating port entry delays for deep-sea carriers. Southampton and Liverpool maintain the densest barge fleets, with real-time scheduling systems reducing stem completion times.
- Direct Supply:Refinery-gate offtake from Fawley and Grangemouth serves buyers with dedicated storage and transport arrangements. Large container lines with contracted volumes leverage this channel for cost efficiency.
- Import Terminals:Rotterdam-connected facilities at Immingham and Thamesport absorb volume spikes during domestic refinery maintenance. Currency exposure and transit time variability complicate procurement planning.
- Onshore Facilities:Coastal storage depots at Peterhead and Milford Haven serve niche markets with limited barge access. Infrastructure constraints limit throughput capacity during peak demand periods.
Bunker barges capture the highest-margin stems. Import terminals handle the greatest volume throughput.
Application:
Customer type determines specification stringency, with commercial shipping accepting standard ISO grades while naval and offshore applications demand enhanced testing protocols.
- Shipping:Deep-sea container and bulk carriers consume the largest fuel volumes at British ports. Felixstowe and Southampton rotations drive procurement timing and inventory cycles.
- Maritime Transport:Ferry operators and coastal feeders require frequent small-batch deliveries with strict sulfur compliance. Solent and Thames estuary routes exhibit the densest service patterns.
- Offshore Operations:North Sea oil platform supply vessels operate from Aberdeen and Peterhead with specialized MDO and marine gas oil requirements. Weather windows and platform schedules create volatile demand spikes.
- Naval:Ministry of Defence procurement follows distinct quality and security protocols. Devonport and Portsmouth facilities maintain segregated supply chains.
Shipping commands the greatest aggregate volume. Offshore operations deliver the steepest expansion trajectory as North Sea decommissioning activity intensifies.
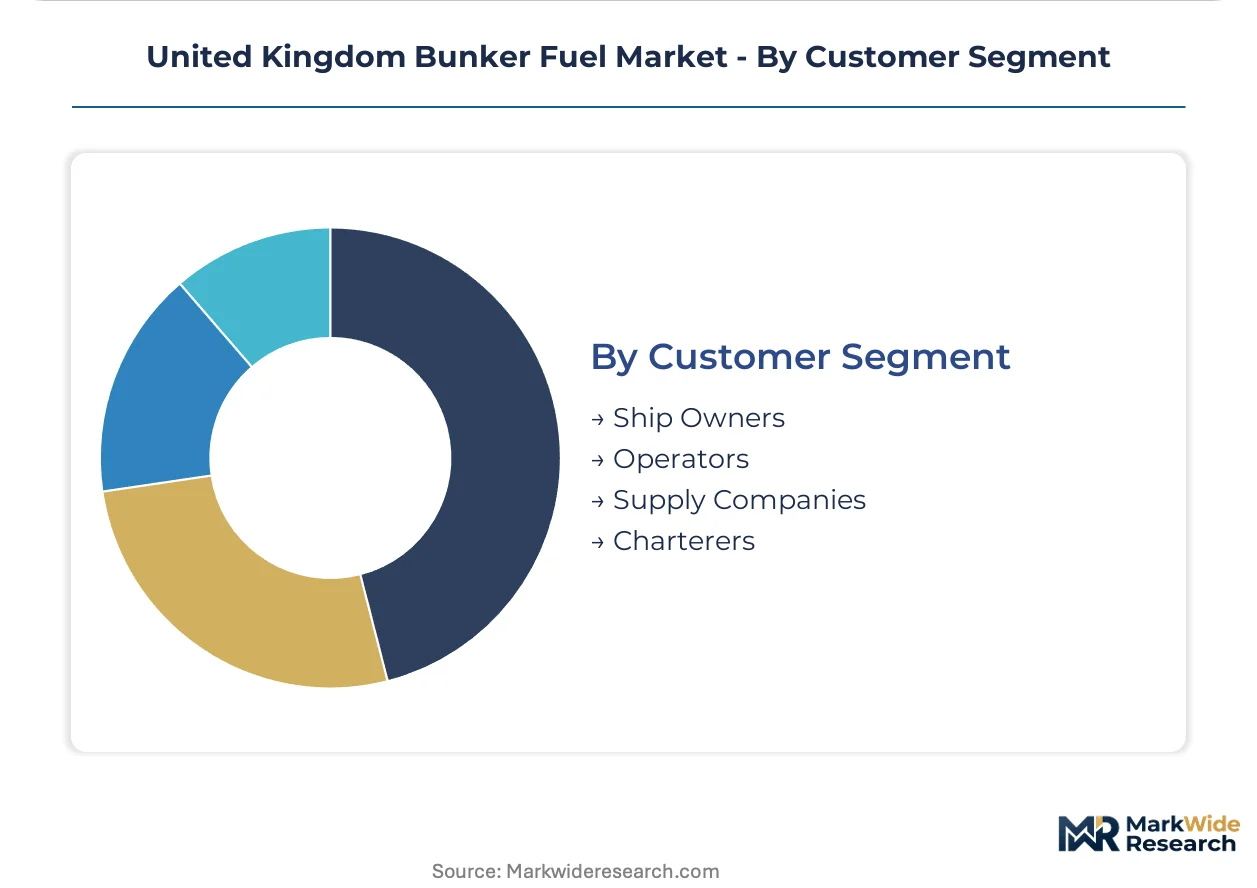
Customer Segment:
Procurement sophistication varies widely, with integrated shipowners internalizing trading functions while smaller operators rely on broker-mediated spot purchases.
- Ship Owners:Asset-holding companies with global fleets negotiate term contracts and manage inventory across multiple bunkering points. London-headquartered entities dominate this segment.
- Operators:Technical managers responsible for voyage execution and fuel optimization. Real-time price discovery platforms are penetrating this group's procurement decisions.
- Supply Companies:Specialized marine fuel traders and physical suppliers managing storage and logistics infrastructure. Rotterdam-integrated players compete with British terminal operators.
- Charterers:Cargo interests contracting vessel capacity and often retaining fuel cost exposure. Container lines with UK-Europe rotations represent the most active charterer-procurers.
Ship owners control the largest contracted volumes. Operators are gaining share fastest as fleet management consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Emissions Trading System's maritime inclusion reshapes fuel economics for vessels calling at British ports. Terminal operators across the United Kingdom are reallocating storage capacity toward low-sulfur formulations. The Maritime and Coastguard Agency enforces bunkering standards under UK flag-state authority.
London and the Southeast
Container shipping lines operating Thames estuary rotations drive marine fuel procurement volumes. The Environment Agency monitors spill-response readiness at marine fueling points along the river. Felixstowe and Thamesport terminals absorb Rotterdam-connected supply during refinery maintenance cycles.
Scotland
North Sea oil platform logistics fleets generate specialized MDO demand at Aberdeen harbor and Peterhead terminals. Scottish offshore support vessels operate under Maritime and Coastguard Agency bunkering standards with premium pricing tolerance. Weather windows and platform schedules create volatile demand spikes in the region.
Southampton and the Solent
Deep-sea carriers with UK-Europe rotations anchor marine fuel offtake at this supply point. Shell Marine Products Ltd maintains dedicated bunker barges serving vessel traffic. The densest barge fleet concentration in British waters reduces stem completion times through real-time scheduling systems.
Immingham and the Humber
BP PLC leverages integrated refining and terminal network infrastructure to sustain supply continuity. Import terminals absorb volume spikes when domestic refinery output proves insufficient. Currency exposure and transit time variability complicate procurement planning for Rotterdam-dependent supply corridors.
Liverpool and the Northwest
Bunker barges serving this anchorage point compete for container line and dry bulk operator contracts. Maritime Bunkering Ltd distributes specialized MDO to coastal traffic with strict sulfur compliance requirements. Terminal operators maintain segregated low-sulfur storage tanks under Environment Agency oversight.
United Kingdom Bunker Fuel Market Competitive Landscape
Player mix skews toward integrated energy majors with captive refining and terminal networks. Market concentration favors suppliers controlling physical infrastructure along the Thames, Humber, and Solent corridors. Strategic archetypes include Rotterdam-integrated traders, domestic refinery operators, and specialized coastal distributors. Capacity expansion and ISO 8217 certification investments constitute the dominant competitive moves.
Within the integrated major tier, BP PLC and Shell Marine Products Ltd exemplify upstream-to-terminal control strategies. Maritime Bunkering Ltd occupies a specialist position serving offshore and coastal segments with dedicated MDO distribution. Phillips 66 represents the international trading house archetype with Rotterdam-linked supply flexibility. These three anchors demonstrate how infrastructure ownership, geographic focus, and product specialization stratify competitive positioning across British bunkering points.
| Leading Market Players |
|---|
| Phillips 66 |
| Maritime Bunkering Ltd |
| GB Oils Ltd |
| Shell Marine Products Ltd |
| Exxon Mobil Corporation |
| ConocoPhillips Ltd |
| BP PLC |
| Greenergy International Ltd |
| Mærsk A/S |
| Others |
Value Network & Pricing Analysis
Rotterdam corridor throughput economies concentrate supply leverage among Northwest European refiners, compressing margin pools for British terminal operators while elevating price floors for vessel operators dependent on import-reliant supply chains. This scale asymmetry between continental production hubs and UK distribution points structures competitive dynamics across Thames, Humber, and Solent bunkering zones.
Pricing Analysis
Certification level under ISO 8217:2017 creates the primary spread between premium and standard fuel tiers, with full-parameter testing commanding 8-12% uplifts over basic sulfur-density verification. Contract-based long-term offtake dominates procurement for container lines with regular Felixstowe rotations, while spot purchases concentrate among dry bulk operators with irregular port calls. Price differentiation stems from sulfur compliance grade and barge delivery convenience, with MDO coastal premiums widening as North Sea logistics demand intensifies. Charterers with voyage-cost exposure exhibit highest price sensitivity, whereas integrated shipowners with captive storage tolerate premium spreads for supply security.
Supply Chain Analysis
Northwest European port congestion and Rotterdam-Antwerp barge availability constraints elevate inbound logistics costs for British terminals during peak refinery maintenance windows. Supply concentrates in the Netherlands, Belgium, and Germany, with vacuum residue feedstock and cutter stock blending components drawing from these continental hubs. Single-source vulnerability through the Rotterdam corridor creates structural exposure during Rhine transit disruptions or Northwest European labor actions. Distribution runs through bunker barge networks for deep-sea vessels, while direct refinery-gate offtake serves buyers with dedicated storage at Fawley and Grangemouth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom bunker fuel market sits at a high-growth inflection as EU ETS maritime inclusion and IMO 2020 compliance enforcement permanently restructure fuel procurement economics. Digital mass flow meter mandates and low-carbon alternative fuel pathways are accelerating competitive disruption across traditional supply relationships.
For Market Incumbents: Fortify terminal infrastructure control through segregated low-sulfur storage expansion at Thames and Humber corridors, countering Rotterdam-integrated traders' supply flexibility advantage. Deepen backward integration into biofuel blending capabilities to capture Renewable Transport Fuel Obligation credit value, while accelerating mass flow meter certification timelines ahead of Maritime and Coastguard Agency enforcement deadlines.
For New Entrants and Emerging Players: Differentiate on digital procurement platform integration, targeting mid-size operators with real-time price discovery and stem optimization tools underserved by traditional broker networks. Aberdeen offshore support vessels present the most penetrable segment, with specialized MDO distribution requirements and premium pricing tolerance creating viable entry economics against established coastal suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors terminal operators with EU ETS-compliant storage infrastructure and ISO 8217 certification capabilities. Long-term viability hinges on low-carbon fuel transition readiness across the projection horizon. Acquisition targets should demonstrate Rotterdam corridor supply relationships and barge fleet mass flow meter retrofit completion. The signal to watch is Maritime and Coastguard Agency enforcement timeline acceleration for quantity measurement compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Storage Expansion | Enables VLSFO/HSFO/MDO grade separation required by ISO 8217 enforcement at capacity-constrained Thames terminals. |
| Mass Flow Meter Retrofit | Eliminates quantity disputes under Maritime and Coastguard Agency custody transfer standards for barge operators. |
| Biofuel Blending Capacity | Captures Renewable Transport Fuel Obligation credit value for BDN-documented sustainable marine fuel supply. |
| Digital Trading Platform Launch | Disrupts traditional broker networks with real-time stem optimization for container line procurement departments. |
| Rotterdam Supply Integration | Secures vacuum residue feedstock continuity during Fawley and Grangemouth refinery maintenance turnarounds. |
Research Methodology
A standing panel of refinery operations managers, marine fuel traders, shipowner procurement directors, and terminal infrastructure planners provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through customs trade data, Maritime and Coastguard Agency enforcement records, Environment Agency spill-response documentation, and SEC filings from integrated energy majors. Bottom-up volume modeling across fuel type, distribution channel, and application segments triangulated against top-down macroeconomic indicators to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including fuel sulfur grade, delivery mechanism, vessel application category, and customer procurement sophistication. CAGRs were derived from trend extrapolation of historical offtake patterns adjusted for regulatory inflection impacts. Forecast inputs incorporated EU ETS allowance price trajectories, refinery capacity utilization assumptions, and North Sea offshore activity projections.
Material uncertainties — crude oil price volatility, Rhine water level disruptions, and EU ETS maritime inclusion timeline revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure investment pacing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America Wood Pellet Market
Fuels
South America Aviation Fuel Market
Fuels
India Petrol Station Market
Fuels
South Korea LNG Bunkering Market
Fuels
Gasoline Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Singapore Bunker Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
Fuel Oil Market
Fuels
Brazil Bunker Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
UAE Chemical Logistics Market
Fuels
Global Turbine Oil Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Waste-Derived Pyrolysis Oil Market