
 Bran Market | 2026-2036
Bran Market Size, Share, and Industry Trends Forecast 2026-2036
Bran Market Analytics
Precision milling technology is fragmenting traditional bran production into discrete particle-size streams tailored to nutraceutical and bakery specifications. Ardent Mills leverages its North American grain elevator network to secure premium hard red wheat supply chains. GoodMills Group GmbH anchors European organic bran capacity through vertically controlled milling assets in Austria and Germany. Wilmar International Limited extends its Southeast Asian oilseed infrastructure into rice bran extraction, competing on byproduct recovery economics.
Bran constitutes the outer aleurone and pericarp layers of cereal grains, typically comprising 14-16% dietary fiber by weight and retaining B-vitamin complexes lost in refined flour processing. Roller milling and air classification separate bran streams by granulometry for targeted end uses in human nutrition and animal feed formulations. Wheat bran dominates volume throughput across industrial bakeries seeking cost-effective fiber fortification, while oat bran commands premium positioning in cholesterol-management dietary supplements where beta-glucan content drives clinical substantiation. Rice bran oil extraction co-products now supply growing nutraceutical demand in capsule and granule formats.
The FDA's dietary fiber definition under Nutrition Facts labeling rules shapes how manufacturers quantify and market bran-derived fiber content to U.S. food producers. EFSA health claim assessments in Europe determine which oat bran beta-glucan concentrations qualify for cholesterol-reduction statements, directly influencing formulation decisions by dietary supplement brands. India's FSSAI fortification standards for wheat flour create incremental bran demand through mandated micronutrient restoration protocols. Stakeholders must monitor evolving fiber quantification methodologies across FDA, EFSA, and FSSAI jurisdictions to align product positioning with enforceable label claims.
Market Dynamics
Precision milling fragmentation is splitting bran into discrete particle-size streams, forcing processors to retool facilities for nutraceutical-grade specifications while bakery buyers demand coarser fiber fractions at divergent price points.
Growth Catalysts
- EU Green Deal compliance mandates:The EU Green Deal and F-Gas Regulation tighten milling emission standards, accelerating capital deployment into closed-loop processing systems that capture bran fractions more efficiently.
- Bakery fiber fortification protocols:Industrial bakeries across Germany and Austria now specify wheat bran with defined granulometry for dough rheology control, creating pull-through demand for classified bran streams.
- Rice bran oil extraction expansion:Southeast Asian oilseed processors are capturing rice bran as a co-product stream, feeding nutraceutical capsule and granule manufacturers with stabilized bran derivatives.
Market Restraints
- Wheat input cost volatility:Hard red wheat premiums fluctuate with Black Sea supply disruptions, compressing bran processor margins when grain elevators pass through spot price spikes.
- German milling concentration:GoodMills Group GmbH and vertically integrated Austrian facilities control disproportionate organic bran capacity, creating supply vulnerability for second-tier buyers.
- Beta-glucan quantification inconsistency:EFSA health claim thresholds for oat bran cholesterol-reduction statements remain technically demanding, excluding some milling batches from premium supplement positioning.
Strategic Opportunities
- India FSSAI fortification mandates:The FSSAI's wheat flour micronutrient restoration standards create incremental bran demand through mandated fiber reintroduction protocols in packaged atta.
- Air classification-microbiome convergence:Precision air classification systems combined with fermentation bioprocessing enable tailored prebiotic bran fractions targeting gut health formulations.
- Direct-to-supplement brand channels:Bran processors are bypassing traditional ingredient distributors to supply contract manufacturers serving private-label dietary supplement brands directly.
Industry Challenges
- Milling engineer skill scarcity:Roller mill optimization for multi-stream bran classification requires specialized expertise that vocational programs in Central Europe are not producing at sufficient rates.
- Stabilization capex intensity:Rice bran lipase inactivation through extrusion or microwave stabilization demands seven-figure equipment investments that smaller Southeast Asian processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bran Market |
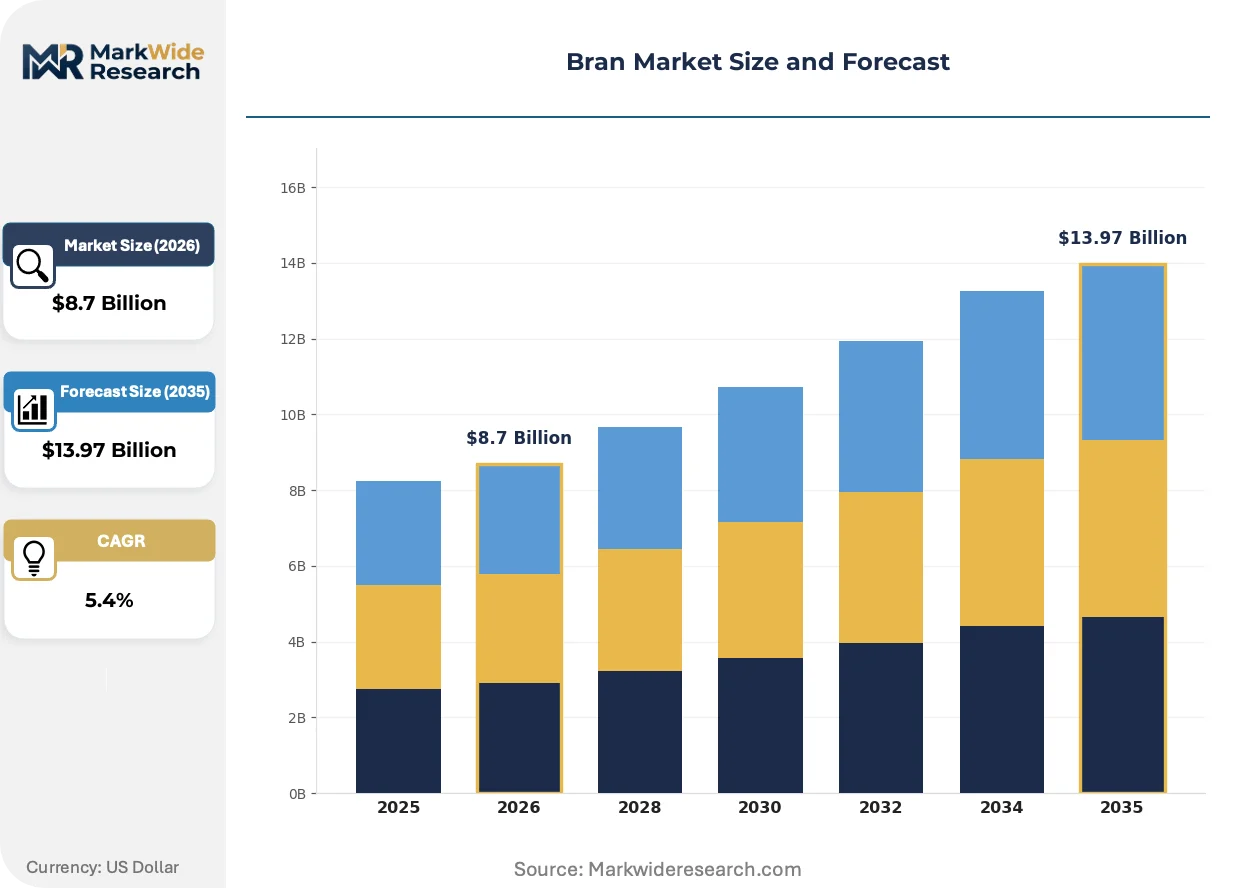
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Bran, Oat Bran, Rice Bran, Barley Bran Form: Flour, Fiber Supplement, Granules, Capsules End User: Food Industry, Nutraceuticals, Bakery Sector, Dietary Supplements Packaging Type: Bags, Bottles, Boxes, Pouches |
| Companies Covered | Ardent Mills, GoodMills Group GmbH, Wilmar International Limited, Archer Daniels Midland Company, Riceland Foods, Inc., Siemer Milling Company, Grain Millers, Inc., Didion Inc., Grain Processing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bran Market Evolving Landscape
Active restructuring of bran value chains centers on three vectors: processing technology convergence, regulatory fiber definition evolution, and procurement pattern fragmentation across end-use verticals.
Air classification systems with integrated near-infrared spectroscopy are hybridizing traditional roller milling workflows. Nutraceutical contract manufacturers in Switzerland and Germany now specify real-time fiber fraction verification during production runs. This hybridization is compressing quality assurance timelines from batch testing to inline monitoring, enabling just-in-time bran stream adjustments for beta-glucan or arabinoxylan targets.
The FDA's dietary fiber definition under Nutrition Facts labeling rules continues reshaping how U.S. food producers quantify bran-derived fiber content. Manufacturers must demonstrate physiological benefits for isolated fibers to count toward daily values, forcing reformulation of legacy bran-enriched products. Bakery brands with national distribution are responding by reverting to intact bran fractions rather than processed fiber isolates to maintain label claim certainty.
Ingredient procurement from dietary supplement brands is fragmenting away from long-term sole-source contracts toward multi-origin qualification systems. Buyers now maintain approved supplier lists across three to four milling regions to mitigate climate-driven crop variability. This pattern is most visible among North American private-label capsule manufacturers sourcing oat bran from both Upper Midwest elevators and Scandinavian organic processors simultaneously.
Bran Market Segmentation
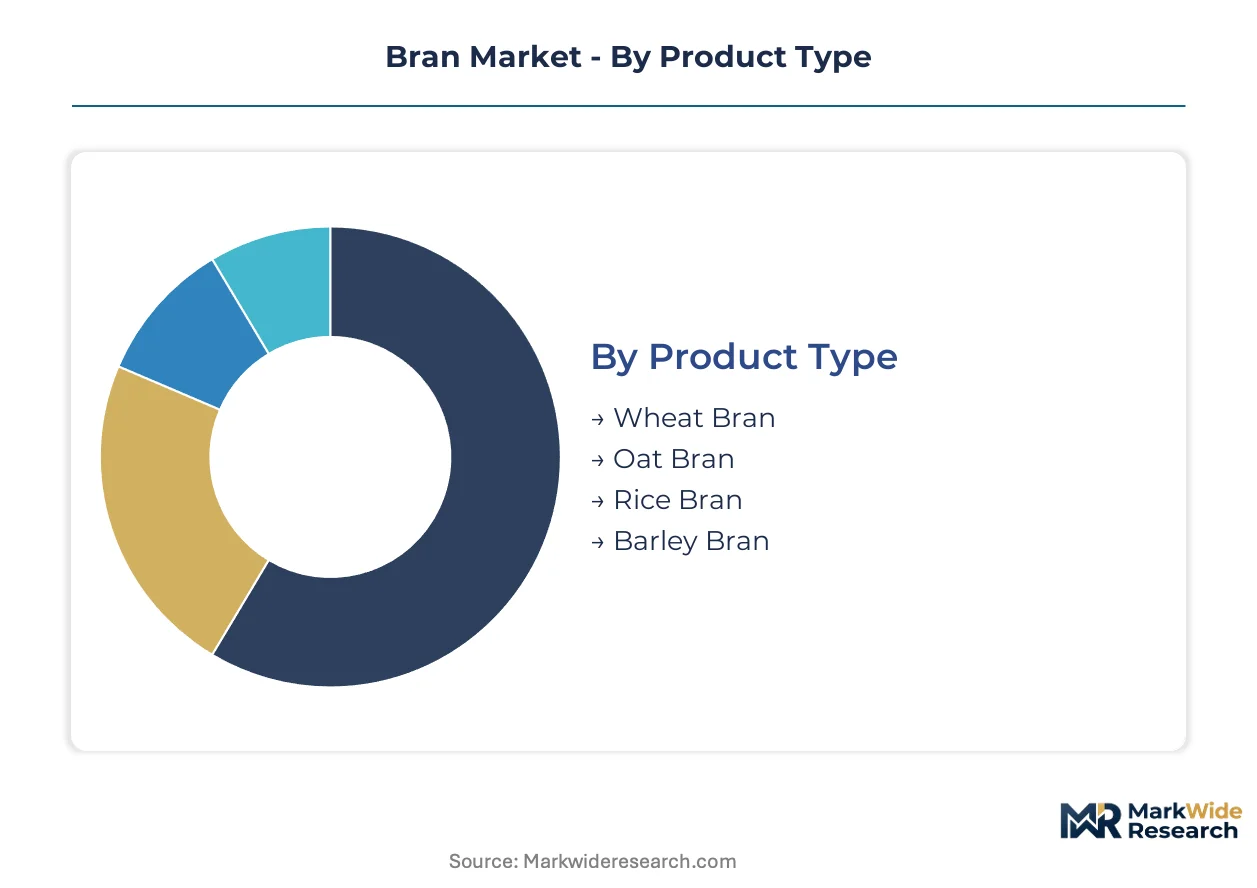
Bran segmentation reflects divergent processing intensities and end-use specifications. Wheat bran flows toward industrial bakeries seeking cost-effective fiber fortification, while oat bran commands premium positioning in cholesterol-management supplements where beta-glucan content requires clinical substantiation.
Product Type:
The use-case spectrum spans commodity-grade fiber fortification to high-value nutraceutical extraction, with each grain type carrying distinct compositional profiles that determine downstream applications.
- Wheat Bran:Comprises the outer aleurone and pericarp layers of Triticum aestivum, typically delivering 14-16% dietary fiber by weight with retained B-vitamin complexes. Industrial bakeries across Germany absorb the largest volumes for dough rheology control and cost-effective fiber enrichment in packaged breads. Roller milling classification separates coarse fractions for bakery use from finer streams targeting animal feed.
- Oat Bran:Contains concentrated beta-glucan soluble fiber in the outer groat layers, requiring specific granulometry to meet EFSA health claim thresholds for cholesterol-reduction statements. Dietary supplement manufacturers in Switzerland and North America qualify multiple milling origins simultaneously to mitigate climate-driven crop variability and secure consistent beta-glucan concentrations.
- Rice Bran:Stabilized through extrusion or microwave inactivation of lipase enzymes to prevent rancidity, yielding oil extraction co-products for nutraceutical capsule and granule formats. Southeast Asian processors leverage existing oilseed infrastructure to capture this stream.
- Barley Bran:Delivers beta-glucan content intermediate between oat and wheat varieties, finding niche positioning in specialty bakery formulations and regional feed applications where price sensitivity limits oat bran substitution.
Established volume favors wheat bran; emerging adoption favors oat bran.
Form:
Processing depth determines margin capture, with minimally refined formats serving commodity buyers and extracted isolates targeting clinical-grade specifications.
- Flour:Coarsely milled bran fractions integrate directly into bakery dough systems without additional processing, offering the lowest unit cost for fiber fortification. German industrial bakeries specify defined particle-size distributions to maintain consistent hydration rates and mixing tolerances.
- Fiber Supplement:Concentrated arabinoxylan or beta-glucan isolates require enzymatic extraction and purification to meet FDA dietary fiber definition standards for physiological benefit substantiation. U.S. manufacturers face reformulation pressures as legacy products lose label claim certainty under evolving fiber quantification rules.
- Granules:Agglomerated bran derivatives improve handling characteristics and dissolution profiles for beverage and smoothie applications, commanding mid-tier pricing between commodity flour and purified isolates.
- Capsules:Encapsulated rice bran oil derivatives and stabilized bran extracts serve direct-to-consumer supplement channels, with contract manufacturers in North America bypassing traditional ingredient distributors to secure supply directly from Southeast Asian processors.
Commodity flour dominates tonnage; fiber supplements climb the fastest on clinical substantiation premiums.
End User:
Customer technical requirements fragment procurement patterns, with food manufacturers prioritizing cost and consistency while nutraceutical buyers demand batch-level compositional verification.
- Food Industry:Encompasses processed food manufacturers integrating bran as a functional ingredient for texture modification and macronutrient labeling advantages. India's FSSAI wheat flour fortification mandates create incremental demand through mandated micronutrient restoration protocols.
- Nutraceuticals:Requires real-time near-infrared spectroscopy verification of fiber fractions during production runs, with Swiss and German contract manufacturers specifying inline monitoring to compress quality assurance timelines.
- Bakery Sector:Represents the largest volume sink for wheat bran, with Austrian and German facilities controlling disproportionate organic capacity and forcing second-tier buyers into supply vulnerability.
- Dietary Supplements:Private-label capsule manufacturers maintain approved supplier lists across three to four milling regions, fragmenting procurement away from long-term sole-source contracts toward multi-origin qualification systems.
Bakery sector absorbs baseline volume; nutraceuticals gain share fastest on precision specification premiums.
Packaging Type:
Packaging selection tracks distribution channel requirements and shelf-stability needs across industrial and consumer-facing formats.
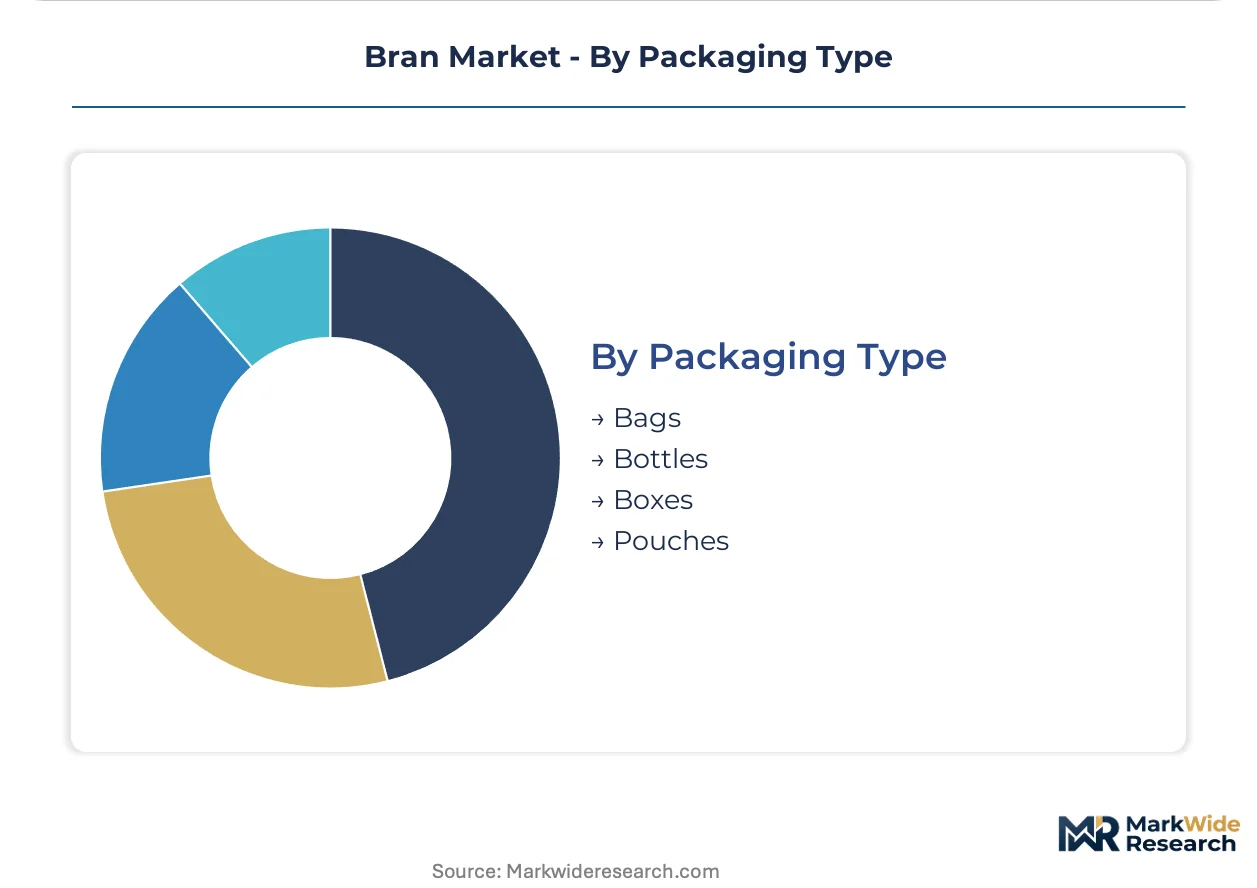
- Bags:Multi-wall paper or woven polypropylene sacks serve bulk industrial shipments to bakery and food manufacturing facilities, with German milling clusters optimizing pallet configurations for just-in-time delivery.
- Bottles:Rigid PET or HDPE containers protect capsule and granule formats from moisture ingress in retail supplement channels.
- Boxes:Corrugated secondary packaging supports wholesale distribution of bagged products and direct-to-supplement-brand bulk shipments.
- Pouches:Flexible stand-up pouches with resealable closures address consumer convenience preferences in specialty flour and single-serve supplement segments.
Industrial bags command tonnage dominance; pouches expand most quickly on consumer convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakeries in Germany absorb the largest wheat bran volumes for dough rheology control, while Southeast Asian oilseed processors capture rice bran as a nutraceutical co-product stream. Nutraceutical contract manufacturers in Switzerland and North America qualify multiple oat bran milling origins simultaneously to secure consistent beta-glucan concentrations.
Germany
GoodMills Group GmbH operates major refining facilities that supply industrial bakeries with classified bran streams for fiber fortification protocols. The EU Green Deal and F-Gas Regulation tighten milling emission standards, accelerating capital deployment into closed-loop processing systems in Baden-Württemberg and North Rhine-Westphalia.
United States
Ardent Mills leverages its grain elevator network across the Upper Midwest to secure premium hard red wheat supply chains for bakery applications. The FDA's dietary fiber definition under Nutrition Facts labeling rules forces reformulation of legacy bran-enriched products, with manufacturers reverting to intact bran fractions to maintain label claim certainty.
India
The FSSAI's wheat flour micronutrient restoration standards create incremental bran demand through mandated fiber reintroduction protocols in packaged atta. Milling clusters in Maharashtra and Gujarat process wheat bran for both domestic bakery use and export to Middle Eastern markets seeking cost-effective fiber fortification.
Switzerland
Contract manufacturers specify real-time near-infrared spectroscopy verification of fiber fractions during production runs for dietary supplement brands. Swissmedic oversight of nutraceutical quality standards compresses quality assurance timelines from batch testing to inline monitoring, enabling just-in-time bran stream adjustments.
Indonesia
Wilmar International Limited extends its oilseed infrastructure into rice bran extraction, competing on byproduct recovery economics in Java and Sumatra processing corridors. Stabilization through extrusion or microwave inactivation of lipase enzymes feeds nutraceutical capsule manufacturers with derivatives for direct-to-consumer supplement channels.
Bran Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement patterns. The vendor base spans multinational grain processors with captive milling assets and regional specialists focusing on single-grain bran streams. Three archetypes dominate: scale-driven commodity suppliers, precision-milling nutraceutical specialists, and vertically integrated oilseed processors capturing rice bran co-products. Competitive moves center on multi-origin supplier qualification systems and direct-to-supplement-brand channel bypass strategies.
Among North American grain processors, Ardent Mills and Archer Daniels Midland Company represent scale-driven archetypes with elevator network control over hard red wheat supply chains. GoodMills Group GmbH anchors European organic bran capacity through GmbH-structured milling assets in German and Austrian corridors. Wilmar International Limited exemplifies the oilseed-processor expansion model, occupying a position where rice bran extraction leverages existing Southeast Asian infrastructure for nutraceutical co-product recovery.
| Leading Market Players |
|---|
| Ardent Mills |
| GoodMills Group GmbH |
| Wilmar International Limited |
| Archer Daniels Midland Company |
| Riceland Foods, Inc. |
| Siemer Milling Company |
| Grain Millers, Inc. |
| Didion Inc. |
| Grain Processing Corporation |
| Others |
Value Network & Pricing Analysis
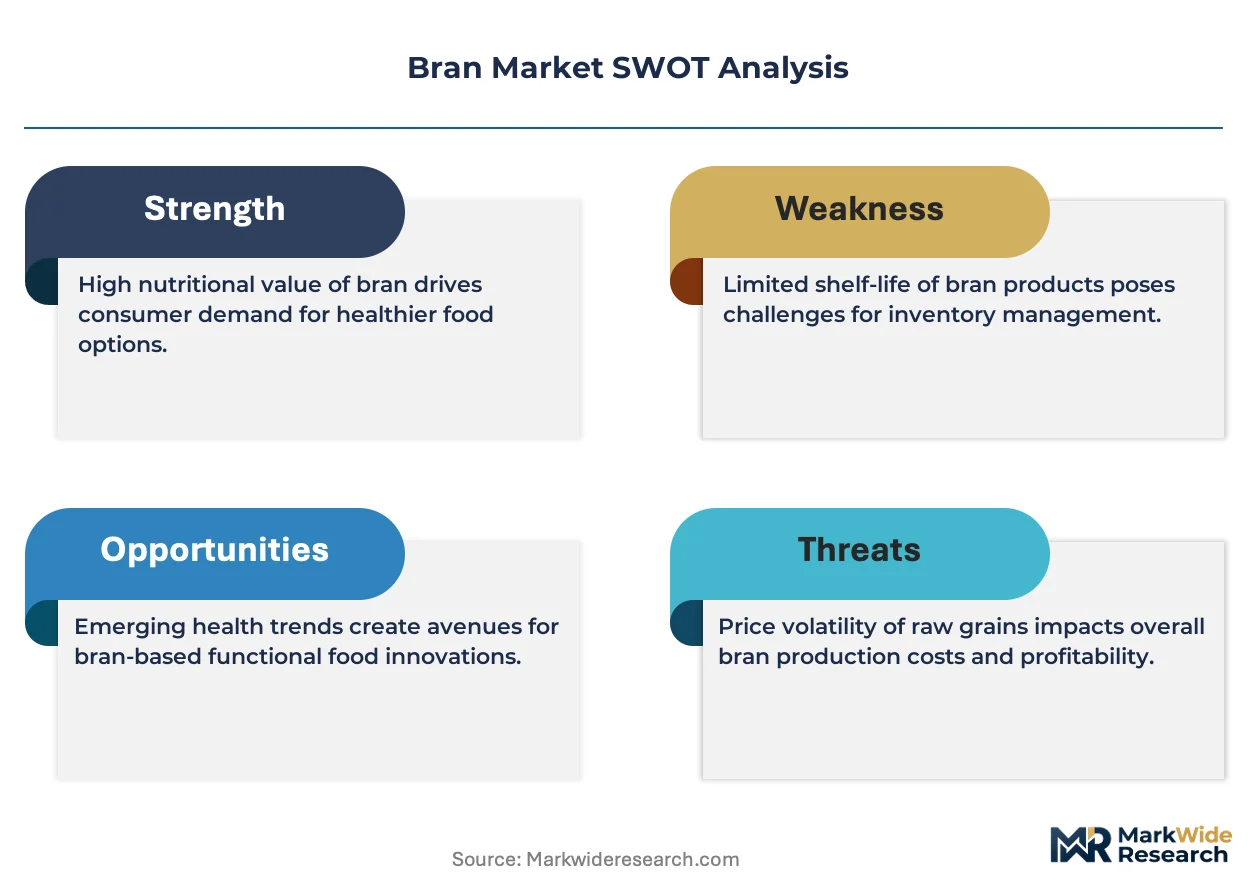
Hard red wheat elevator concentration across the Upper Midwest and Black Sea corridors directly determines where margin pools accumulate in downstream bran classification. Buyers facing spot price spikes from grain elevators pass through cost volatility into differentiated bran stream pricing, compressing processor margins while rewarding multi-origin qualification systems.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade indexation dominate wheat bran transactions between North American grain elevators and industrial bakery buyers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified organic oat bran from conventional bakery-grade wheat fractions and animal feed residuals. Cost compression in standard-tier wheat bran is intensifying because Black Sea supply disruptions trigger elevator spot price spikes that processors cannot fully pass through. Industrial bakeries in Germany exhibit highest price sensitivity due to thin dough-margin economics, while Swiss nutraceutical contract manufacturers show least sensitivity given beta-glucan clinical substantiation premiums.
Supply Chain Analysis
Upstream feedstock flows from hard red wheat belts in the United States, Germany, and India into roller milling clusters controlled by GoodMills Group GmbH and Ardent Mills. Rice bran extraction draws from Southeast Asian oilseed infrastructure in Indonesia and Thailand, while oat groat processing rests on Scandinavian and Upper Midwest elevator networks. Single-source vulnerability concentrates in German organic bran capacity where GoodMills Group GmbH and Austrian facilities control disproportionate throughput. Distribution runs through just-in-time pallet configurations to industrial bakeries and direct-to-supplement-brand bulk shipments bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bran value chains are approaching a platform-economics inflection where air classification-microbiome convergence creates interoperable prebiotic ingredient platforms. Real-time near-infrared spectroscopy verification enables just-in-time bran stream adjustments that reshape procurement relationships between processors and contract manufacturers.
For Market Incumbents: Insulate organic bran margin pools through captive supply of Austrian and German milling assets while accelerating closed-loop processing system deployment ahead of EU Green Deal emission enforcement. Precision milling fragmentation from nutraceutical-grade specifications threatens traditional volume-based bakery contracts, requiring inline monitoring investments to defend beta-glucan certification premiums against Swiss and German contract manufacturer quality demands. For New Entrants and Emerging Players: Build out rice bran stabilization capabilities in Southeast Asian corridors where Wilmar International Limited's oilseed infrastructure demonstrates byproduct recovery economics, targeting direct-to-supplement-brand channels bypassing traditional ingredient distributors. India's FSSAI wheat flour fortification mandates create the most penetrable white-space through mandated fiber reintroduction protocols in packaged atta, with Maharashtra and Gujarat milling clusters offering regional entry points. For Investors and Strategic Acquirers: Capital is best deployed toward precision-milling nutraceutical specialists with air classification-microbiome convergence capabilities and multi-origin supplier qualification systems spanning three to four milling regions. Long-term viability across the projection horizon hinges on prebiotic fraction targeting gut health formulations, with fermentation bioprocessing integration serving as the inflection indicator for platform-economy capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hard Red Wheat Elevators | Ardent Mills secures premium supply chains against Black Sea spot price volatility. |
| Air Classification-Microbiome Convergence | Swiss contract manufacturers enable tailored prebiotic fractions for gut health formulations. |
| Direct-to-Supplement-Brand Channel Bypass | Southeast Asian processors capture margin from traditional ingredient distributor disintermediation. |
| Closed-Loop Processing System Deployment | GoodMills Group GmbH accelerates capital deployment ahead of EU Green Deal F-Gas Regulation enforcement. |
| Multi-Origin Supplier Qualification Systems | North American private-label capsule manufacturers mitigate climate-driven crop variability across Scandinavian and Upper Midwest oat bran origins. |
Research Methodology
Initial hypotheses were tested against primary input from grain elevator procurement managers, roller mill operations engineers, nutraceutical contract manufacturing quality directors, and industrial bakery R&D formulation scientists and refined through secondary validation. Trade data from USDA Foreign Agricultural Service, EUROSTAT milling statistics, FSSAI fortification compliance records, and SEC 10-K filings from publicly traded grain processors anchored supply-side quantification. Bottom-up capacity modeling across German, Austrian, and Southeast Asian milling clusters triangulated against top-down demand segmentation from bakery, nutraceutical, and dietary supplement end-use channels.
Demand-supply-balance framing across the analysis window integrated wheat bran tonnage flows to industrial bakeries, oat bran beta-glucan concentration requirements for EFSA health claim eligibility, and rice bran oil extraction co-product recovery rates. Segmentation dimensions modeled included grain type, processing form, end-use vertical, and regional regulatory cluster. CAGRs were derived from rolling average growth rate convergence across projection scenarios. Forecast inputs incorporated FSSAI fortification mandate implementation timelines and EU Green Deal emission standard phase-in schedules.
Stress conditions across Black Sea wheat supply disruptions, EFSA beta-glucan quantification threshold revisions, and rice bran lipase stabilization equipment financing access were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding climate-driven crop variability and regulatory enforcement pacing. Cross-checking against USDA Wheat Outlook and IGC grain market assessments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Horehound Extract Market
Ingredients
Organic Starch Market
Ingredients
Textured Soy Flour Market
Ingredients
Yeast Peptide Market
Ingredients
Textured Wheat Protein Market
Ingredients
Cacao Extracts Market
Ingredients
Gluten-Free Flour Market
Ingredients
Commercial Amino Acids Market
Ingredients
Carrot Fiber Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Beef Concentrate Market
Ingredients
Protein Trends and Technologies Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Egg Albumin Protein Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Global Cocoa Products Market