
 Ice Cream Bases Market | 2026-2036
Ice Cream Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Bases Market Analytics
Artisanal dessert chains and craft gelaterias is reorganizing demand away from mass-market food manufacturers. Unilever leverages its dairy supply networks to secure consistent base quality across European production hubs. Nestlé anchors its position through specialized stabilizer research for clean-label applications. Fonterra competes by dominating Oceania's dairy-derived base exports with vertically integrated milk sourcing.
Ice cream bases comprise formulated blends of milk solids, sweeteners, emulsifiers, and stabilizers that provide the structural foundation for frozen dessert production, typically requiring fat content between 10-16% and overrun control of 80-100% for optimal texture. The ingredient source dimension shows plant-based bases capturing the fastest expansion as oat and coconut proteins displace conventional dairy in premium formulations, while dairy-sourced bases retain the largest margin pool due to established cold-chain infrastructure. Powder bases lead in shipping efficiency for remote manufacturers, though liquid bases command preference among high-volume restaurant chains seeking batch consistency.
The FDA governs dairy ingredient standards and labeling requirements for ice cream bases sold in the United States, while EFSA evaluates novel plant protein safety for European base formulations, and Japan's Ministry of Health, Labour and Welfare sets microbiological specifications for imported base concentrates. These frameworks elevate compliance costs for cross-border suppliers but simultaneously create barriers that favor established multi-regional producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving allergen disclosure mandates and carbon footprint auditing rules that will soon differentiate market-access tiers across major importing jurisdictions.
Market Dynamics
Clean-label reformulations and plant-based ingredient approvals are compressing formulation cycles while fragmenting supplier qualification requirements across FDA and EFSA jurisdictions.
Growth Catalysts
- ESFA Novel Protein Safety Pathways:Accelerated approvals for oat and coconut protein isolates enable faster European product launches. Artisanal gelaterias exploit these pathways to differentiate premium lines.
- Artisanal Parlor Expansion:Craft dessert chains in the United States and Japan are procuring specialized bases with customized fat profiles. This segment demands batch-specific consistency that mass manufacturers cannot deliver.
- Cold-Chain Infrastructure Maturation:Liquid base distribution now reaches secondary cities in Italy and Japan. Restaurant chains leverage this density for just-in-time inventory models.
Market Restraints
- Dairy Commodity Volatility:Milk solids pricing swings compress margin predictability for dairy-derived base producers. Fonterra's vertical integration buffers this exposure.
- Regulatory Fragmentation:Divergent allergen disclosure mandates between FDA and Japan's Ministry of Health, Labour and Welfare inflate compliance overhead. Cross-border suppliers face duplicated testing protocols.
- Plant-Based Texture Limitations:Current oat protein formulations struggle to replicate dairy mouthfeel above 12% fat equivalents. Premium positioning requires expensive stabilizer packages.
Strategic Opportunities
- Underpenetrated Japanese Regional Markets:Secondary cities outside Tokyo and Osaka lack specialized base distribution. Local craft chains represent captive demand for powder base formats.
- FDA Clean-Label Incentive Alignment:Streamlined review pathways for reduced-ingredient declarations reward early reformulators. Stabilizer suppliers can bundle compliance consulting with ingredient sales.
- Direct-to-Parlor Digital Channels:E-procurement platforms bypass traditional foodservice distributors. Small-batch producers gain margin recovery through disintermediation.
Industry Challenges
- Specialized Food Science Talent Scarcity:Formulation chemists with dual expertise in dairy chemistry and plant protein functionality command premium compensation. Recruitment bottlenecks delay R&D timelines.
- Legacy Equipment Retrofit Costs:Powder-to-liquid conversion requires capital outlay for hydration and homogenization systems. Mid-scale manufacturers defer upgrades, constraining product mix flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Bases Market |
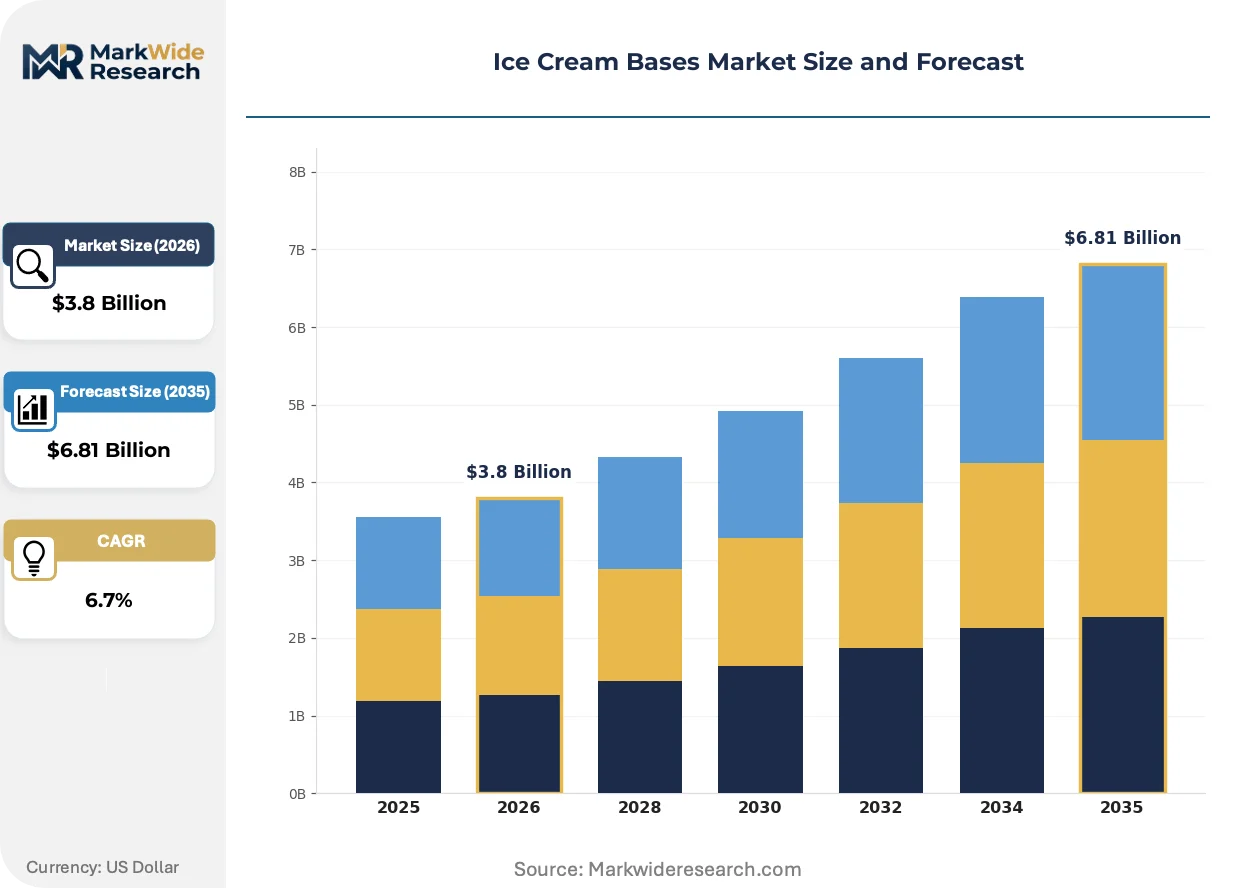
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Base, Powder Base, Mix Base, Stabilizer Base Ingredient Source: Dairy, Plant-Based, Organic, Conventional Flavor Profile: Vanilla, Chocolate, Strawberry, Mint End User: Food Manufacturers, Restaurants, Retailers, Home Users |
| Companies Covered | Unilever, Nestlé, Danone, Fonterra, General Mills, Irca, Fabbri, Arla Foods Ingredients, Glanbia Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Bases Market Evolving Landscape
Formulation science is compressing ingredient lists while precision fermentation and enzymatic processing unlock novel protein functionalities. Three developments dominate current competitive positioning.
Precision fermentation-derived dairy proteins are miniaturizing the functional gap between plant and animal bases. Artisanal producers in Italy and the United States are piloting these ingredients for premium positioning. The technology is miniaturizing the scale threshold for clean-label claims, enabling smaller batch runs with full ingredient transparency.
EFSA's updated guidance on novel food allergenicity assessments is accelerating European plant base approvals. Manufacturers must now submit proteomic stability data that previous submissions lacked. Dairy-alternative specialists are restructuring regulatory affairs teams to front-load these documentation requirements.
Buyer concentration among premium dessert chains is compressing supplier negotiation cycles. Long-term base supply agreements are displacing spot purchasing for volume accounts. This pattern is most visible in Japan, where parlor chains now contract directly with New Zealand dairy processors for exclusive fat-profile specifications.
Ice Cream Bases Market Segmentation
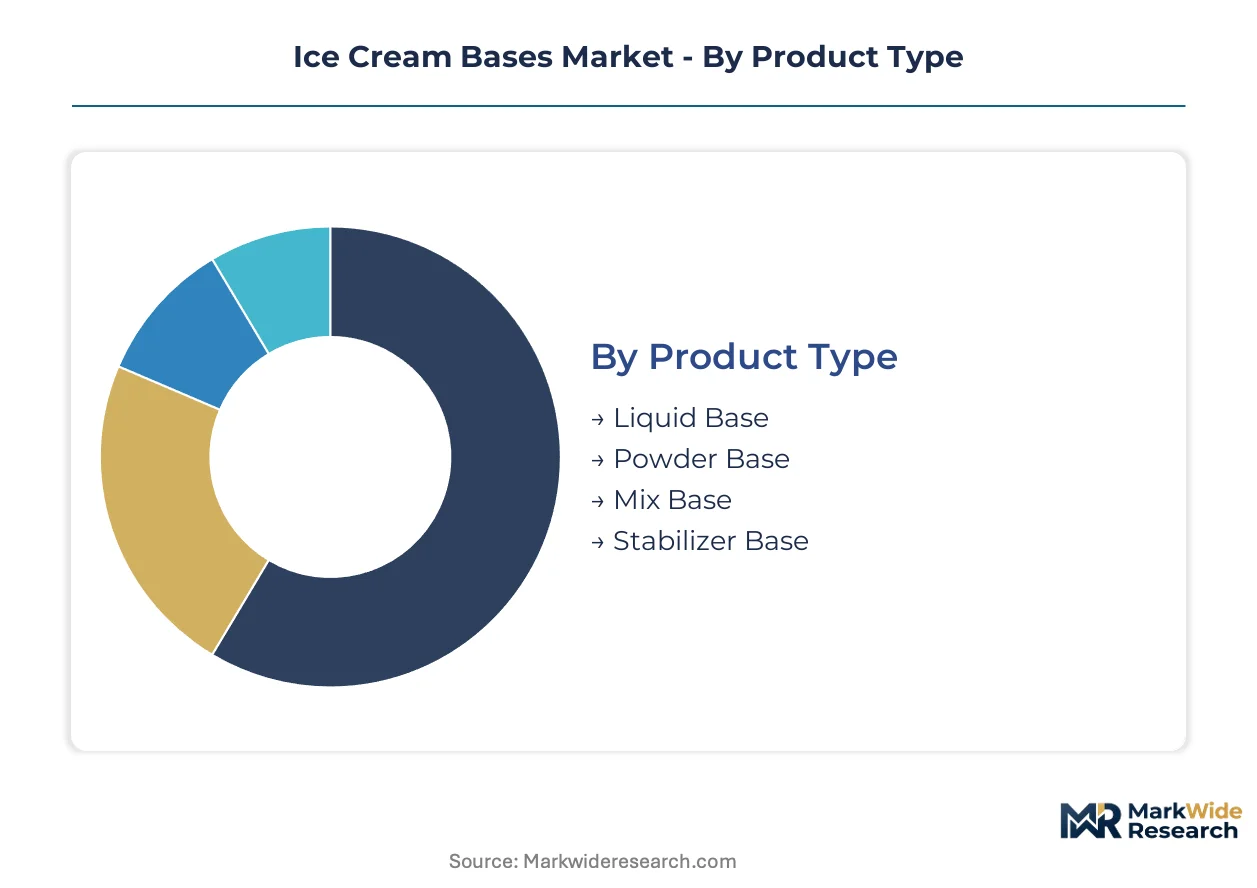
Ice cream base procurement patterns diverge sharply between mass-production food manufacturers and craft dessert operations. Each segmentation dimension reveals distinct substitution pressures as plant-based alternatives displace conventional dairy across premium channels.
Product Type:
Liquid and powder formats face divergent substitution threats from emerging mix-base hybrids that promise hydration flexibility without capital-intensive equipment.
- Liquid Base:Pre-hydrated emulsions requiring cold-chain distribution at 2-4°C. High-volume restaurant chains in Japan and Italy leverage this format for batch consistency in just-in-time inventory models. FDA pasteurization standards elevate compliance costs for cross-border suppliers.
- Powder Base:Dehydrated blends of milk solids, sweeteners, and stabilizers offering shipping efficiency and extended shelf stability. Secondary cities across Japan's regional markets favor this format where liquid distribution remains sparse. Reconstitution requires precise hydration protocols.
- Mix Base:Semi-hydrated concentrates bridging powder convenience with liquid performance.
- Stabilizer Base:Specialized hydrocolloid and emulsifier packages for custom formulation.
Liquid base anchors the volume base while powder base gains share at the steepest rate.
Ingredient Source:
Cost tier stratification separates premium-positioned organic and plant-based sources from commodity-grade conventional dairy.
- Dairy:Milk-derived bases with 10-16% fat content specifications and established cold-chain infrastructure. Fonterra's vertically integrated New Zealand operations dominate Oceania export flows. EFSA dairy safety protocols govern European import qualifications.
- Plant-Based:Oat and coconut protein formulations capturing fastest expansion as artisanal parlors reformulate for clean-label positioning. Current texture limitations above 12% fat equivalents require expensive stabilizer packages. FDA novel protein pathways accelerate US market entry.
- Organic:Certified ingredient supply chains with audited traceability documentation.
- Conventional:Standard-grade inputs without certification premiums or specialty sourcing requirements.
Dairy anchors the volume base while plant-based climbs the fastest.
Flavor Profile:
Application-driven demand concentrates in neutral vanilla bases that enable downstream customization versus finished-flavor concentrates.
- Vanilla:Neutral base platform permitting end-user flavor customization. Food manufacturers in the United States specify this format for multi-SKU production efficiency. Madagascar and Tahitian vanilla bean sourcing differentiates premium tiers.
- Chocolate:Cocoa-infused formulations with fat-content calibration for viscosity control. Italian gelaterias demand specialized chocolate bases with customized overrun specifications. EFSA cocoa contaminant thresholds regulate European import compliance.
- Strawberry:Fruit-puree integrated bases with pH stability challenges.
- Mint:Flavor-oil emulsified formats with volatile compound retention requirements.
Vanilla anchors the volume base while chocolate gains share at the steepest rate.
End User:
Customer type fragmentation separates high-volume procurement by food manufacturers from specialized batch requirements of artisanal dessert chains.
- Food Manufacturers:Industrial-scale buyers demanding consistent fat profiles and overrun control for automated production lines. Unilever's European dairy supply networks secure dedicated base volumes with long-term contracting terms. Japan's Ministry of Health, Labour and Welfare microbiological specifications govern import qualification.
- Restaurants:Artisanal parlors and premium dessert chains procuring customized bases with batch-specific consistency requirements. This segment demands fat-profile flexibility that mass manufacturers cannot deliver. Direct-to-parlor digital channels are disintermediating traditional foodservice distributors.
- Retailers:Private-label base procurement for in-house frozen dessert production.
- Home Users:Small-format consumer bases for domestic ice cream machine applications.
Food manufacturers anchor the volume base while restaurants expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand dairy processors supply premium fat-profile bases to Japanese parlor chains through direct contracting arrangements. Fonterra's vertically integrated operations anchor Oceania export flows into Asian markets. Cold-chain infrastructure maturation in secondary Japanese cities enables just-in-time liquid base distribution.
United States
Artisanal dessert chains in California and New York Metro drive procurement of specialized bases with customized overrun specifications. FDA pasteurization standards and novel protein pathways govern dairy and plant-based formulation approvals. Chicago-area food manufacturers leverage neutral vanilla bases for multi-SKU production efficiency.
Japan
Craft gelaterias in Tokyo and Osaka demand batch-specific consistency that mass manufacturers cannot deliver. The Ministry of Health, Labour and Welfare sets microbiological specifications for imported base concentrates. Secondary cities in Kyushu and Hokkaido represent underpenetrated demand for powder base formats.
Italy
Traditional gelaterias in Lombardy and Emilia-Romagna anchor European demand for premium chocolate bases with specialized viscosity calibration. EFSA dairy safety protocols and novel food allergenicity assessments regulate import qualifications. Turin-based producers pilot precision fermentation-derived proteins for clean-label positioning.
Germany
Industrial food manufacturers in Bavaria and North Rhine-Westphalia procure consistent fat-profile bases for automated production lines. EFSA evaluates plant protein safety for European base formulations, elevating compliance documentation requirements. Frankfurt-area distributors serve as consolidation points for liquid base cold-chain distribution.
Netherlands
Amsterdam and Rotterdam function as European import hubs for dairy-derived bases from Oceania and South America. REACH compliance and CSRD carbon footprint auditing rules differentiate market-access tiers. Foodservice distributors in the Randstad region are disintermediated by direct-to-parlor digital procurement platforms.
Ice Cream Bases Market Competitive Landscape
Player mix skews toward multinational dairy conglomerates with captive ingredient supply chains and specialized stabilizer research capabilities. Tiered competition separates vertically integrated milk processors from formulation specialists and plant-protein innovators. Strategic archetypes include cold-chain logistics integrators, clean-label reformulation consultants, and precision fermentation technology licensors. Dominant competitive moves encompass long-term supply agreements with premium dessert chains and portfolio diversification into plant-based alternatives.
Among European dairy conglomerates, Unilever and Nestlé occupy positions as archetypal cold-chain integrators with dedicated regulatory affairs capacity across FDA and EFSA jurisdictions. Fonterra anchors the Oceania export vector through backward integration into New Zealand milk sourcing. Danone represents the plant-based transition archetype, while Arla Foods Ingredients and Glanbia Nutritionals exemplify specialized ingredient suppliers competing on stabilizer research and clean-label formulation bundles. Irca and Fabbri occupy positions as Italian craft-focused specialists serving artisanal gelateria demand.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Danone |
| Fonterra |
| General Mills |
| Irca |
| Fabbri |
| Arla Foods Ingredients |
| Glanbia Nutritionals |
| Others |
Value Network & Pricing Analysis
Capacity utilization at New Zealand dairy processing facilities shapes both supply concentration and price floors across premium fat-profile segments. Fonterra's backward integration into milk sourcing compresses input volatility for Oceania exporters while elevating entry barriers for non-integrated competitors.
Pricing Analysis
Plant-protein formulation premiums versus conventional dairy bases versus precision fermentation-derived alternatives stratify across three performance tiers. Pricing separates certified organic supply chains from commodity-grade inputs from clean-label reformulation bundles. Cost compression in commodity dairy bases is intensifying because milk solids volatility compresses margin predictability. Food manufacturers exhibit highest price sensitivity due to volume procurement leverage, while artisanal parlors accept premium positioning for batch-specific consistency.
Supply Chain Analysis
New Zealand and Australia anchor dairy-derived base production for Asian export markets. Manufacturing draws from milk solids, hydrocolloid stabilizers, and novel protein isolates. Single-source vulnerability concentrates in Fonterra's vertically integrated Oceania operations. Distribution runs through cold-chain logistics networks serving restaurant chains and foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation consulting services and regulatory compliance bundling expand faster than commodity base sales as artisanal customers outsource clean-label navigation. Recurring revenue from stabilizer subscriptions and technical support contracts outpaces transactional base volumes.
For Market Incumbents: Secure long-term supply agreements with premium dessert chains before direct-to-parlor digital channels disintermediate traditional distributors. Invest in FDA and EFSA regulatory affairs capacity to defend against emerging plant-protein specialists. Add precision fermentation R&D capabilities to counter texture limitations in oat-based formulations.
For New Entrants and Emerging Players: Lead with powder base formats targeting secondary Japanese cities outside Tokyo and Osaka where liquid distribution remains sparse. Exploit EFSA's accelerated novel protein pathways to differentiate premium European lines. Bundle compliance consulting with ingredient sales to capture clean-label reformulation budgets.
For Investors and Strategic Acquirers: Specialized stabilizer research firms with dual dairy-plant protein expertise represent priority acquisition targets. Five-to-ten-year viability hinges on regulatory affairs scalability across FDA and EFSA jurisdictions. Watch for FDA clean-label incentive alignment announcements as inflection indicators for early reformulator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Bundle | Combines stabilizer sales with FDA compliance consulting for artisanal parlors. |
| Direct-to-Parlor Digital Platform | Bypasses foodservice distributors to recover margin for small-batch producers. |
| Precision Fermentation Partnership | Licenses dairy-identical proteins to bridge plant-based texture gaps. |
| Secondary City Distribution Expansion | Extends powder base reach into Kyushu and Hokkaido regional markets. |
| Long-Term Supply Agreement | Locks exclusive fat-profile specifications with Japanese parlor chains. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists, regulatory affairs directors at base manufacturers, procurement managers at artisanal dessert chains, and foodservice distribution executives and refined through secondary validation. FDA novel protein pathway filings, EFSA novel food allergenicity assessments, Japan's Ministry of Health import specifications, and customs trade data provided triangulation anchors. Bottom-up volume estimates from parlor-level procurement patterns were reconciled with top-down dairy commodity flow analysis.
Variance decomposition across ingredient source, product format, and end-user segmentation dimensions structured the analytical framework. CAGRs were derived from modeled adoption curves for plant-based alternatives and infrastructure maturation rates for cold-chain distribution. Precision fermentation scale-up timelines and EFSA approval velocity served as scenario-weighting inputs throughout the projection horizon.
Forecasts assume regulatory continuity in FDA pasteurization standards and EFSA novel food pathways; material policy shifts would require re-modeling. Dairy commodity volatility and plant-protein texture breakthroughs represent specific revision triggers. Recalibration cycles align with material shifts in clean-label incentive structures and precision fermentation commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Arrowroot Starch Market
Ingredients
Carotenoids Market
Ingredients
Icing Shortening Market
Ingredients
Low Fat Oil Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Carob Powder Market
Ingredients
High Protein Flour Market
Ingredients
Avocado Oil Market
Ingredients
Peanut Ingredients Market
Ingredients
Bouillon Cubes Market
Ingredients
Cocoa Maker Market
Ingredients
Acetylated Starch Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Agar Market
Ingredients
Baobab Ingredient Market