
 Virgin Coconut Oil Market | 2026-2036
Virgin Coconut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Virgin Coconut Oil Market Analysis
Palm kernel oil is restructuring cost benchmarks across medium-chain triglyceride applications, forcing virgin coconut oil suppliers to reposition on premium positioning. Marico Ltd. leverages its South Asian distribution depth to sustain household penetration in edible and personal care segments. Celebes Coconut Corporation anchors Philippine export volumes through integrated milling operations in Mindanao. Greenville Agro Corporation differentiates via organic certification streams that command shelf space in North American natural retail channels.
Virgin coconut oil denotes mechanically extracted endosperm oil from fresh coconut meat without chemical refining, retaining lauric acid concentrations typically between 47% and 53% alongside intact polyphenol fractions. The unrefined product type captures the dominant value pool as consumers equate minimal processing with bioactive retention, though organic certification commands measurable price premiums in European and North American retail. Cosmetics applications now outpace traditional food and beverage volume growth as formulators seek plant-derived emollients with established INCI recognition, while pharmaceutical-grade specifications remain concentrated among a limited supplier base with GMP-aligned extraction protocols.
The Philippines Bureau of Product Standards mandates virgin coconut oil labeling integrity, compelling exporters to maintain chain-of-custody documentation from farm to port. USDA organic equivalence and EU organic regulation cross-recognition determine market access eligibility for Asian-origin suppliers serving Western retail channels. Stakeholders must monitor evolving EFSA novel food opinions and state-level cosmetic ingredient disclosure rules in California that could recalibrate formulation specifications and sourcing geography requirements.

Market Dynamics
Mechanical cold-press extraction protocols are fragmenting the supplier base as Philippine and Indonesian cooperatives bypass centralized millers, redistributing value capture toward farm-gate processors with direct export certification.
Growth Catalysts
- EU Organic Regulation cross-recognition:Asian-origin suppliers with USDA organic equivalence gain automatic shelf access in German and French natural retail channels, compressing market entry timelines.
- Cosmetics formulators:Personal care brands specify virgin coconut oil for INCI-recognized emollient properties, displacing petroleum-derived alternatives in Southeast Asian manufacturing hubs.
- Mindanao copra processing clusters:Integrated milling cooperatives in Davao del Sur and South Cotabato redirect export volumes through direct port arrangements, shortening supply chains.
Market Restraints
- Copra price volatility:Weather-driven yield fluctuations in Quezon and Bicol provinces destabilize input cost structures for mechanical extraction operators lacking forward contracting.
- Philippine Bureau of Product Standards purity mandates:Chain-of-custody documentation requirements from farm to port impose compliance burdens that exclude uncertified smallholders from formal export channels.
- Palm kernel oil substitution:Refined palm kernel fractions with comparable lauric acid profiles undercut virgin coconut oil pricing in bulk MCT applications, compressing addressable volume in commodity segments.
Strategic Opportunities
- North American natural retail channel expansion:Organic certification streams command dedicated shelf space in Whole Foods and Sprouts networks, creating premium positioning unavailable to conventional suppliers.
- Pharmaceutical-grade GMP extraction protocols:Limited supplier base with validated manufacturing standards captures contract manufacturing margins for nutraceutical encapsulation and topical drug delivery systems.
- Direct-to-consumer e-commerce platforms:Indonesian cooperatives in Central Java bypass traditional export aggregators through Shopify and Amazon storefronts, retaining margin previously captured by trading houses.
Industry Challenges
- Organic certification audit timelines:Three-year conversion periods for conventional coconut lands delay revenue recognition for farm-gate processors seeking EU organic market access.
- Cold-press equipment technical capacity:Mechanical extraction at sub-60°C thresholds requires stainless steel pressing infrastructure that cooperatives finance through development agency microcredit with 18-24 month deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virgin Coconut Oil Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Unrefined, Organic, Non-Organic Application: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals Form: Liquid, Solid, Powdered, Blended End User: Retail Consumers, Food Manufacturers, Cosmetic Companies, Health Organizations |
| Companies Covered | Greenville Agro Corporation, Celebes Coconut Corporation, Cargill, Incorporated, Barlean's Organic Oils, LLC, Tantuco Enterprises, Inc., The Hain Celestial Group, Marico Ltd., Forest Essentials, Nutiva Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virgin Coconut Oil Market Emerging Trajectories
Extraction technology democratization and regulatory disclosure mandates are redrawing competitive boundaries between artisanal cooperatives and integrated millers across Southeast Asian supply origins.
Small-scale stainless steel cold-press units with temperature monitoring sensors are decentralizing virgin coconut oil production from centralized Mindanao millers to provincial cooperative facilities. Indonesian farmer associations in Sulawesi and Central Java deploy these systems to retain value at origin while meeting Philippine Bureau of Product Standards documentation requirements. The technology is decentralizing export volume concentration previously captured by three integrated Philippine processors.
California's Safe Cosmetics Act ingredient disclosure rules now mandate reporting of trace contaminants in personal care formulations, compelling brands to specify extraction method and geographic origin on packaging. EFSA novel food opinion updates for lauric acid derivatives are recalibrating pharmaceutical-grade specification thresholds. Cosmetics manufacturers serving EU and US markets simultaneously are consolidating supplier bases toward dual-certified Philippine and Indonesian operations with validated chain-of-custody systems.
Ingredient sourcing managers at personal care brands now require extraction temperature logs and polyphenol retention certificates as standard procurement documentation, displacing commodity spot purchasing. Direct supplier relationships with certified cooperatives replace traditional trading house intermediation for mid-tier natural brands. This pattern concentrates most visibly in German and Dutch formulator networks where retailer sustainability scorecards weight provenance transparency heavily in supplier selection algorithms.
Virgin Coconut Oil Market Segmentation
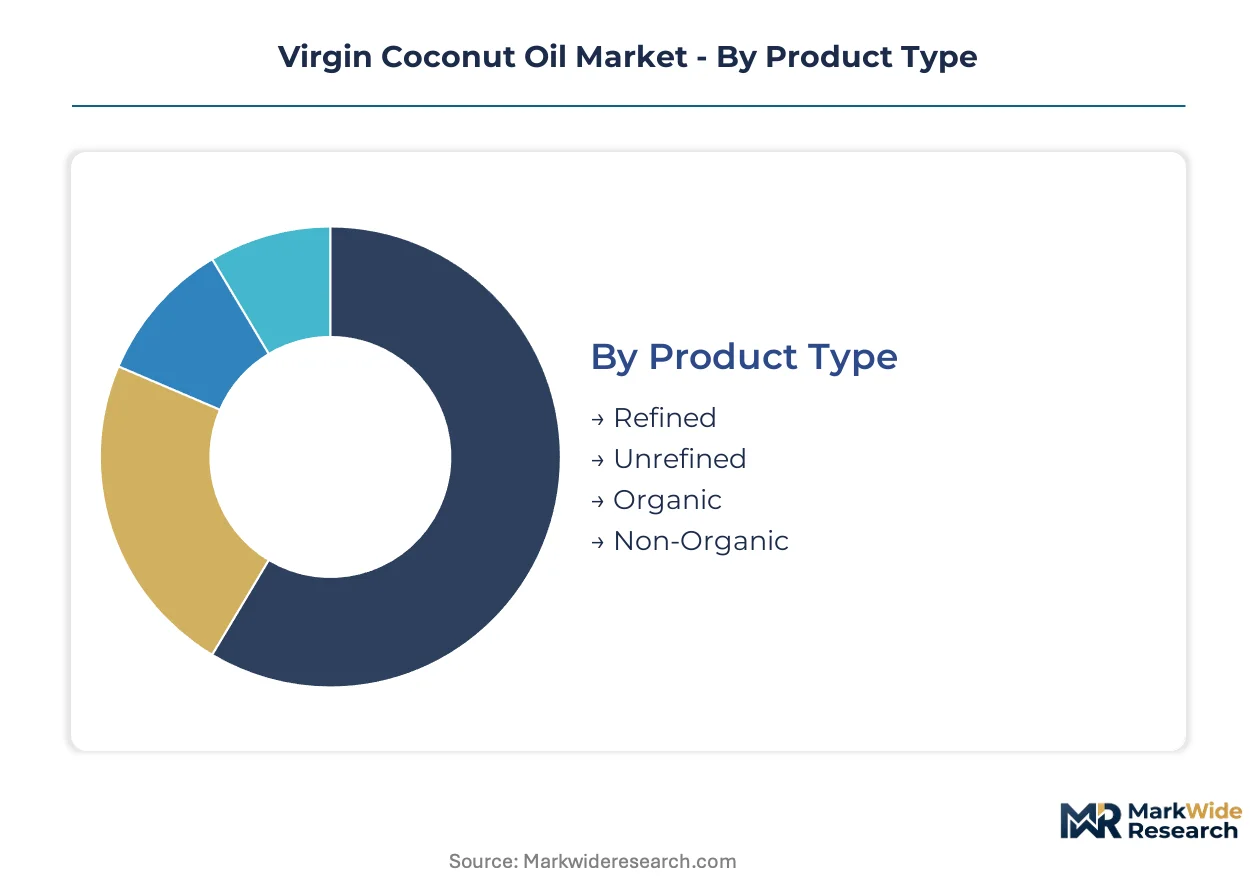
Virgin coconut oil segmentation reveals distinct value capture patterns between commodity-grade bulk supply and certified specialty streams. Procurement specifications diverge sharply across end-use applications, with cosmetic formulators demanding documentation that food manufacturers rarely require.
Product Type:
Integration depth varies significantly across processing tiers, with unrefined and organic grades commanding standalone premium positioning while refined variants embed into commodity formulations.
- Unrefined:Mechanical cold-press extraction at sub-60°C preserves lauric acid concentrations between 47% and 53% alongside intact polyphenol fractions. Personal care brands in Southeast Asia specify this grade for INCI-recognized emollient properties, displacing petroleum-derived alternatives in regional manufacturing hubs.
- Organic:USDA organic equivalence and EU organic regulation cross-recognition determine market access eligibility for Asian-origin suppliers serving Western retail channels. Three-year conversion periods for conventional coconut lands delay revenue recognition for farm-gate processors seeking European market access.
- Refined:Chemical processing strips volatile compounds for neutral flavor profiles suited to high-heat food applications.
- Non-Organic:Conventional cultivation supplies bulk MCT extraction for industrial nutraceutical encapsulation.
Unrefined leads volumes today; organic is gaining share fastest.
Application:
Cost tier stratification separates pharmaceutical-grade specifications from commodity food service, with cosmetics applications now outpacing traditional edible volume growth.
- Cosmetics:Formulators specify virgin coconut oil for established INCI recognition as a plant-derived emollient. California's Safe Cosmetics Act ingredient disclosure rules mandate reporting of trace contaminants, compelling brands to specify extraction method and geographic origin on packaging.
- Pharmaceuticals:GMP-aligned extraction protocols with validated manufacturing standards capture contract manufacturing margins for nutraceutical encapsulation and topical drug delivery systems. EFSA novel food opinion updates for lauric acid derivatives are recalibrating specification thresholds.
- Food & Beverage:Edible applications concentrate in South Asian household penetration for direct consumption and cooking.
- Nutraceuticals:Medium-chain triglyceride supplements drive demand for standardized lauric acid content.
Cosmetics leads volumes today; pharmaceuticals is expanding most quickly.
Form:
Supply concentration patterns favor liquid extraction at origin, with downstream blending and powder conversion occurring closer to end-use markets.
- Liquid:Cold-press output ships in bulk flexitanks from Davao del Sur and South Cotabato port arrangements. Philippine Bureau of Product Standards chain-of-custody documentation accompanies export certification.
- Solid:Fractionation separates high-melting triglycerides for topical balm formulations in temperate climates.
- Powdered:Spray-dried encapsulation serves convenience-oriented nutraceutical tablet manufacturing.
- Blended:Formulators combine virgin coconut oil with complementary carriers to adjust oxidative stability and skin-feel characteristics.
Liquid leads volumes today; powdered is climbing the fastest.
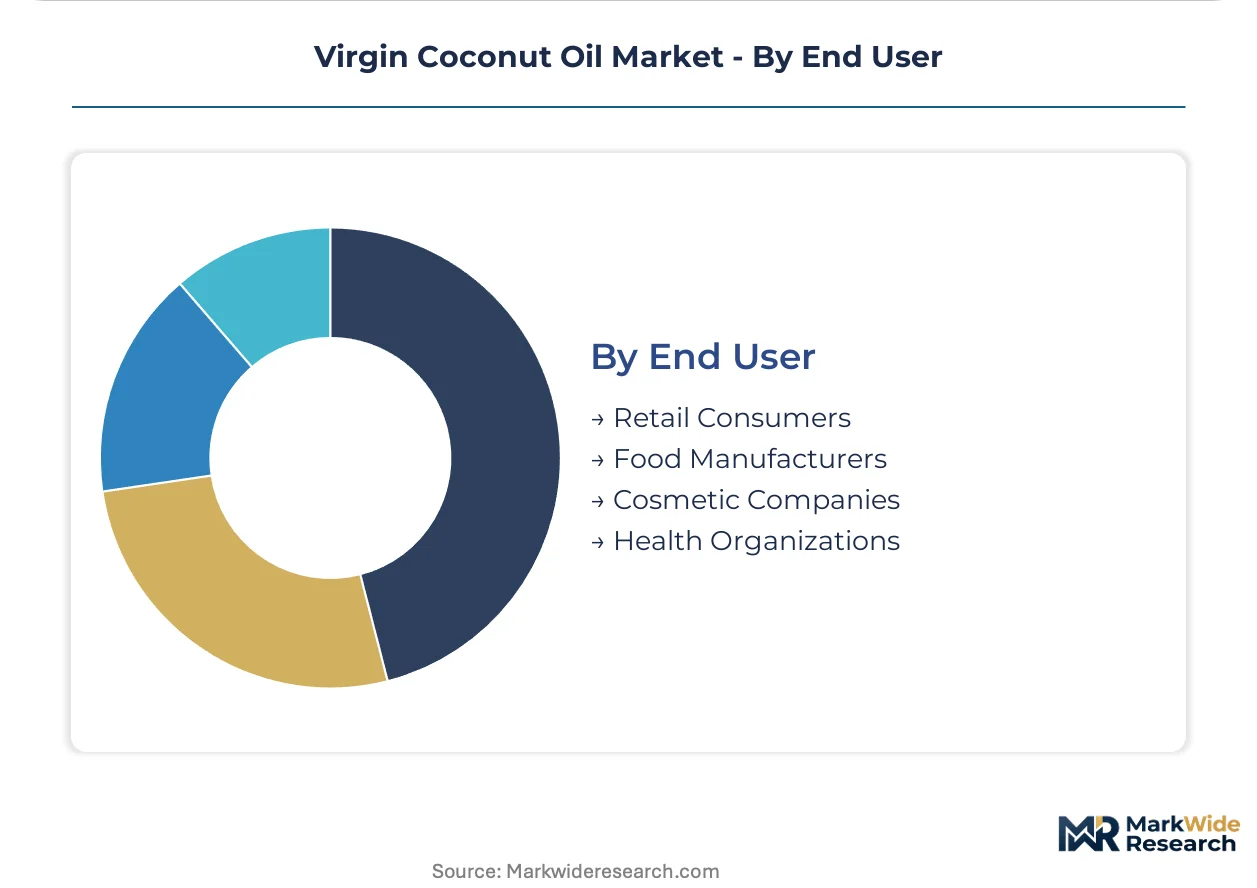
End User:
Customer type determines procurement channel structure, with direct-to-consumer platforms disrupting traditional trading house intermediation.
- Cosmetic Companies:Ingredient sourcing managers require extraction temperature logs and polyphenol retention certificates as standard procurement documentation. German and Dutch formulator networks weight provenance transparency heavily in supplier selection algorithms.
- Retail Consumers:Indonesian cooperatives in Central Java bypass export aggregators through Shopify and Amazon storefronts, retaining margin previously captured by trading houses. Organic certification streams command dedicated shelf space in Whole Foods and Sprouts networks.
- Food Manufacturers:Bulk procurement redirects toward certified suppliers meeting Philippine Bureau of Product Standards labeling purity thresholds.
- Health Organizations:Institutional buyers source pharmaceutical-grade specifications from limited supplier bases with validated protocols.
Food manufacturers lead volumes today; retail consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mindanao-based integrated milling clusters anchor virgin coconut oil export capacity, with Philippine and Indonesian processing cooperatives redirecting volumes through direct port arrangements that shorten supply chains and redistribute value capture toward farm-gate operations.
Philippines
Davao del Sur and South Cotabato processing clusters supply cold-pressed volumes for North American natural retail channels. The Philippine Bureau of Product Standards enforces labeling purity thresholds that redirect bulk procurement toward certified suppliers with complete chain-of-custody documentation. Celebes Coconut Corporation anchors Mindanao export volumes through integrated milling operations serving EU and US markets.
Indonesia
Central Java and Sulawesi farmer associations deploy small-scale stainless steel cold-press units to retain value at origin. USDA organic equivalence and EU organic regulation cross-recognition determine market access eligibility for Indonesian suppliers serving Western retail channels. Expanding copra processing cooperatives in these provinces concentrate demand for mechanical extraction equipment financed through development agency microcredit.
United States
California's Safe Cosmetics Act mandates ingredient disclosure rules that compel personal care brands to specify extraction method and geographic origin on packaging. FDA cosmetic ingredient regulations intersect with state-level disclosure requirements to recalibrate formulation specifications. Whole Foods and Sprouts networks command dedicated shelf space for organic certification streams that create premium positioning unavailable to conventional suppliers.
India
Marico Ltd. leverages South Asian distribution depth to sustain household penetration across edible and personal care segments. FSSAI food safety standards and BIS quality certification requirements shape import specifications for virgin coconut oil entering Indian retail channels. Domestic consumption concentrates in Kerala and Tamil Nadu where traditional direct consumption patterns persist alongside modern retail expansion.
Germany
German formulator networks weight provenance transparency heavily in supplier selection algorithms for INCI-recognized emollient sourcing. EFSA novel food opinions for lauric acid derivatives recalibrate pharmaceutical-grade specification thresholds affecting Asian-origin imports. Natural retail channels in German and French markets grant automatic shelf access to Asian suppliers with USDA organic equivalence, compressing market entry timelines.
Virgin Coconut Oil Market Vendor Landscape
Global majors compete with regional champions across certification and distribution dimensions, producing a tiered structure where integrated millers, organic specialists, and consumer-facing brands occupy distinct competitive positions. The supplier base fragments between Philippine and Indonesian farm-gate cooperatives with direct export capability and centralized processors with legacy trading house relationships. Three archetypes dominate: integrated origin processors with port-direct arrangements, organic-certified specialists commanding North American natural retail premiums, and South Asian FMCG houses with household penetration depth. Competitive moves concentrate on backward integration into copra supply and e-commerce platform deployment that bypasses traditional export aggregators.
Within the integrated origin-processor tier, Celebes Coconut Corporation and Greenville Agro Corporation exemplify divergent strategic positioning. Celebes anchors Philippine export volumes through Mindanao-based milling operations, representing the scale-driven archetype with direct port arrangements. Greenville occupies the organic-certified specialist position, commanding shelf space in North American natural retail channels through certification streams that create premium positioning. Marico Ltd. represents the South Asian FMCG house archetype, leveraging distribution infrastructure across edible and personal care segments to sustain household penetration depth that origin-focused competitors cannot replicate.
| Leading Market Players |
|---|
| Greenville Agro Corporation |
| Celebes Coconut Corporation |
| Cargill, Incorporated |
| Barlean's Organic Oils, LLC |
| Tantuco Enterprises, Inc. |
| The Hain Celestial Group |
| Marico Ltd. |
| Forest Essentials |
| Nutiva Inc. |
| Others |
Supply Flow & Price Mechanics
California's Safe Cosmetics Act ingredient disclosure mandates now compel personal care brands to specify extraction method and geographic origin on packaging, forcing supply chains toward certified cooperatives with validated documentation and compressing margins for uncertified bulk suppliers.
Pricing Analysis
Copra price volatility in Quezon and Bicol provinces passes directly through to mechanical extraction operators lacking forward contracting, compressing margins at the farm-gate tier. Three-tier pricing structure across organic-certified premium, unrefined standard, and refined economy levels separates suppliers by documentation depth. Cost compression in commodity MCT applications is intensifying because refined palm kernel fractions with comparable lauric acid profiles undercut virgin coconut oil pricing. Food manufacturers exhibit highest price sensitivity due to volume procurement and substitution elasticity, while cosmetic formulators accept premium positioning for INCI-recognized emollient properties.
Supply Chain Analysis
Fresh coconut meat supply rests on Philippine Mindanao clusters and Indonesian Central Java cooperatives, with Sulawesi farmer associations deploying small-scale stainless steel cold-press units. Mechanical extraction equipment and organic certification audit services feed from development agency microcredit programs and third-party accreditation bodies. Single-source vulnerability concentrates in Davao del Sur port arrangements where integrated millers anchor export volumes. Distribution runs through direct-to-consumer e-commerce platforms and natural retail channel partnerships that bypass traditional trading house intermediation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in organic certification premiums and direct-to-consumer channel capture, with cold-press equipment cost curves declining through development agency financing programs.
For Market Incumbents: Hedge against palm kernel oil substitution by deepening backward integration into copra supply in Mindanao and securing Philippine Bureau of Product Standards chain-of-custody documentation ahead of purity mandate enforcement. Prioritize GMP-aligned extraction protocol investment to capture pharmaceutical-grade contract manufacturing margins. For New Entrants and Emerging Players: Capture white-space in North American natural retail channels through USDA organic equivalence certification, targeting Whole Foods and Sprouts networks with dedicated shelf space requirements. Deploy Shopify and Amazon storefronts to bypass export aggregators and retain margin at origin. For Investors and Strategic Acquirers: Asymmetric upside sits with Indonesian farm-gate cooperatives in Central Java and Sulawesi with direct export capability and validated temperature monitoring infrastructure. Long-term viability hinges on EU organic regulation cross-recognition maintenance and EFSA novel food opinion trajectory for lauric acid derivatives. Watch EFSA novel food opinion updates as inflection indicator for pharmaceutical-grade specification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copra Supply | Mindanao processors secure farm-gate volume through cooperative partnership structures. |
| Organic Certification Investment | USDA organic equivalence unlocks automatic shelf access in German natural retail channels. |
| Direct-to-Consumer Platform Launch | Indonesian cooperatives retain margin previously captured by trading house intermediation. |
| GMP Extraction Protocol Validation | Limited supplier base captures contract manufacturing margins for nutraceutical encapsulation. |
| Cold-Press Equipment Deployment | Stainless steel pressing infrastructure decentralizes production from centralized millers. |
Methodological Framework
Coverage spans the Philippines, Indonesia, the United States, India, and Germany, with primary inputs from each market through structured interviews with cooperative processing managers, personal care brand ingredient sourcing directors, natural retail channel category buyers, organic certification audit specialists, and development agency microcredit officers. Secondary validation draws from Philippine Bureau of Product Standards filings, USDA organic equivalence databases, EFSA novel food opinion registers, California Safe Cosmetics Act disclosure records, and customs export documentation. Bottom-up volume modeling triangulates against top-down demand aggregation across end-use applications.
Granularity-level framing applies extraction method, certification tier, end-use application, and geographic origin as modeled dimensions throughout the forecast period. CAGRs derive from segment-level volume trajectories weighted by price realization patterns. Industry-specific inputs include lauric acid retention thresholds, polyphenol fraction stability curves, and cold-press equipment deployment cycles through development agency financing programs.
Copra yield fluctuations, regulatory opinion shifts at EFSA, and organic certification audit timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on substitution elasticity between virgin coconut oil and palm kernel fractions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Textured Milk Protein Market
Ingredients
Cocoa Derivatives Market
Ingredients
Desiccated Coconut Market
Ingredients
Mastic Gum Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
North America Carrageenan Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Vegetable Extract Market
Ingredients
United Kingdom Protein Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Bran Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Codonopsis Extract Market
Ingredients
Aroma Ingredients Market
Ingredients
North America Dairy Protein Market