
 Global Organs-On-Chips Market | 2026-2036
Global Organs-On-Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organs-On-Chips Market Foresight
Pharmaceutical companies is bifurcating demand away from academic labs as contract validation and scale-up requirements reshape procurement criteria. Emulate, Inc. leverages its liver-chip and lung-chip platforms to anchor relationships with top-20 drug developers. MIMETAS B.V. specializes in kidney-on-a-chip and perfused tubule models that dominate nephrotoxicity workflows. CN Bio Innovations Ltd extends its PhysioMimix platform through co-development agreements that tighten control over end-user protocols.
Organs-on-chips are microfluidic cell culture devices that integrate living human cells with engineered tissue interfaces and continuous perfusion to replicate organ-level physiology, typically operating at microliter-scale volumes with shear stresses of 0.1–10 dyn/cm². Their primary commercial purpose is to generate human-relevant efficacy and safety data before clinical trials, reducing translational failure rates that plague animal models. Liver chip and lung chip products currently occupy the largest revenue pools due to hepatotoxicity and respiratory safety being the most common reasons for drug withdrawal. Microfluidics technology leads in installed base, though 3D bioprinting is capturing fastest-growing interest for multi-organ integration projects.
The FDA's Modernization Act 2.0 directly shapes demand by permitting alternatives to animal studies in new drug applications, while EMA's 3Rs initiative and REACH protocols in Europe tighten the regulatory case for human-specific toxicology data. ISO 10993 biocompatibility standards and OECD test guidelines are converging to define validation benchmarks that determine market access for chip-based submissions. Stakeholders must monitor which regulatory body first issues formal qualification guidance for organ-chip data, as this will determine where platform developers concentrate clinical validation investments.
Market Dynamics
Pharmaceutical procurement criteria are bifurcating demand away from academic laboratories toward contract-validated, scale-ready organ-chip platforms as regulatory submissions require industrial-grade reproducibility protocols.
Growth Catalysts
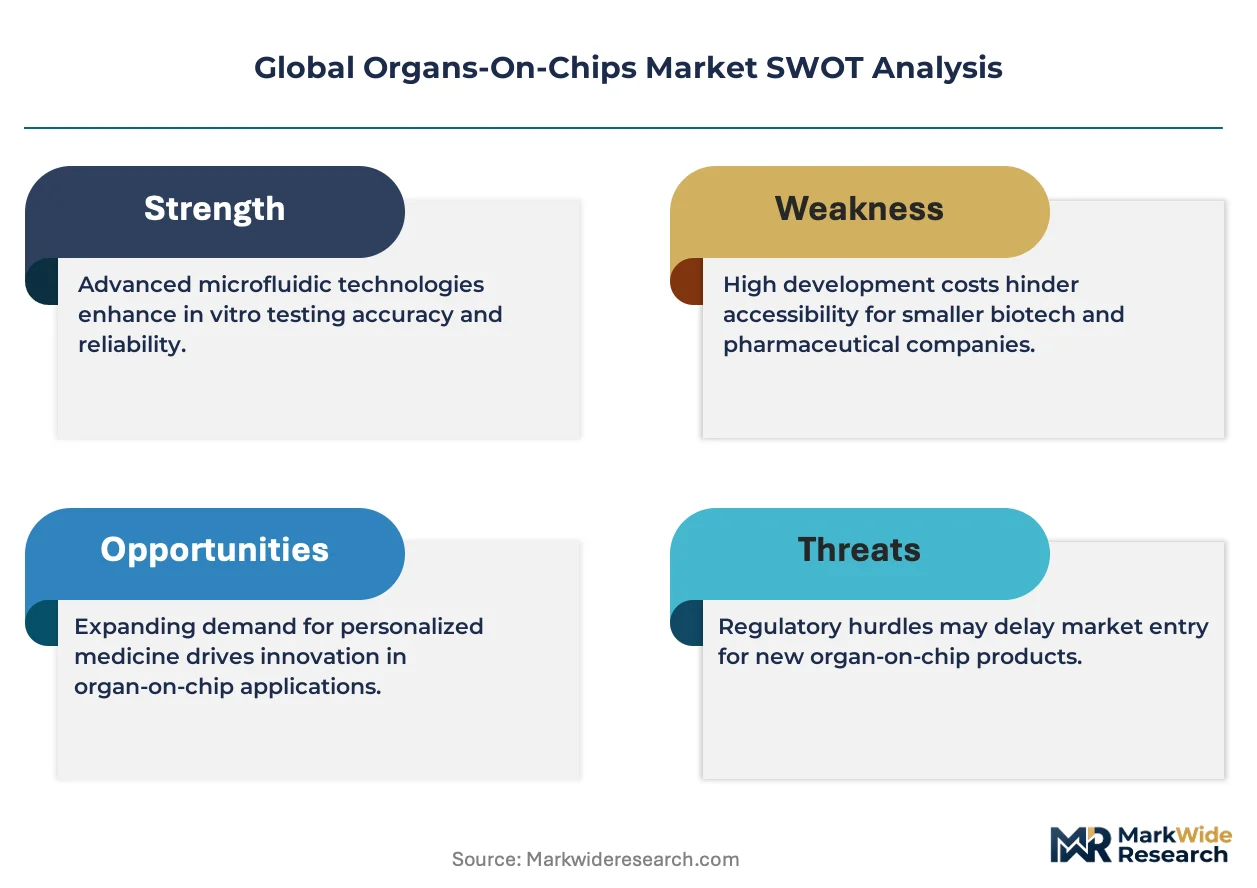
- FDA Modernization Act 2.0:The removal of mandatory animal testing requirements for new drug applications creates immediate regulatory pull for human-relevant organ-chip toxicology data in United States submissions.
- REACH protocols:European chemical safety mandates tighten the evidentiary burden for human-specific toxicity endpoints, accelerating replacement of rodent models with perfused microphysiological systems.
- Hepatotoxicity screening workflows:Liver-chip platforms capture expanding procurement volumes as drug withdrawals from liver failure drive preclinical safety investments at top-tier pharmaceutical developers.
Market Restraints
- PDMS material costs:Polydimethylsiloxane, the dominant substrate for microfluidic chip fabrication, faces price volatility from silicone supply chain concentration in East Asian petrochemical clusters.
- ISO 10993 validation timelines:Biocompatibility certification for novel chip materials extends 18-24 months, creating regulatory friction against rapid platform iteration cycles.
- Primary cell sourcing:Donor tissue supply constraints limit manufacturing scale-up for patient-matched organ-chip models, compressing batch consistency at commercial volumes.
Strategic Opportunities
- India's CDSCO pathway:The national pharmaceutical regulator's emerging interest in alternative toxicology methods creates first-mover positioning for organ-chip developers in generic drug manufacturing hubs.
- Multi-organ integration:Convergence of 3D bioprinting with microfluidic perfusion enables body-on-a-chip systems that replicate systemic drug metabolism for pharmacokinetic modeling.
- Japan's PMDA qualification:Early engagement with the Pharmaceuticals and Medical Devices Agency for organ-chip data acceptance offers regulatory arbitrage for validated platform submissions.
Industry Challenges
- Bioengineering talent scarcity:Cross-disciplinary expertise spanning microfluidics, tissue engineering, and pharmacology remains concentrated at Boston and San Francisco academic clusters, constraining workforce expansion.
- Cleanroom capex intensity:ISO Class 7 manufacturing facilities for GMP-compliant chip production require $15-25 million initial investment, limiting mid-tier entrant scale.
- Protocol standardization gaps:Absence of harmonized OECD test guidelines for organ-chip endpoints forces redundant validation studies across jurisdictional submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organs-On-Chips Market |
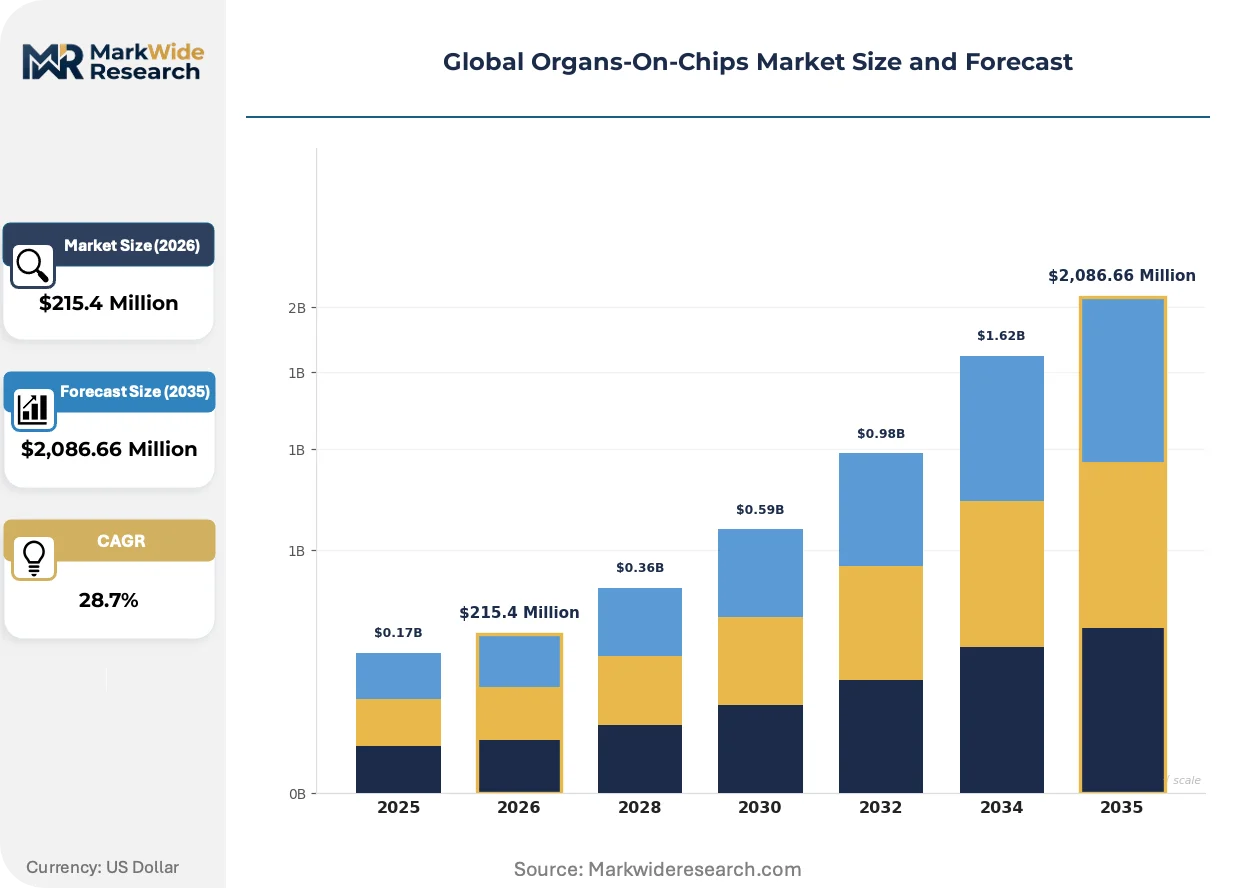
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $2,086.66 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lung Chip, Liver Chip, Heart Chip, Kidney Chip, Gut Chip Technology: Microfluidics, 3D Bioprinting, Microelectromechanical Systems, Optical Sensors Application: Drug Screening, Disease Modeling, Toxicity Testing, Personalized Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Academic Labs |
| Companies Covered | Emulate, Inc., MIMETAS B.V., CN Bio Innovations Ltd, InSphero, TissUse GmbH, Hesperos, Inc., AxoSim, AlveoliX AG, Nortis, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organs-On-Chips Market Shifts & Advancements
Platform architectures are fragmenting from single-organ proof-of-concept systems toward integrated multi-tissue models as pharmaceutical buyers demand translational predictive power that matches physiological complexity.
Microfluidic liver-chip designs are fragmenting into specialized configurations for steatosis, fibrosis, and cholestasis endpoints as toxicology teams demand disease-state specificity beyond healthy tissue baselines. Mid-cap pharmaceutical developers in Germany and Switzerland are adopting these platforms at 40-60 unit annual procurement scales. This specialization is fragmenting vendor competitive positions around organ-specific scientific credibility rather than generic microfluidics engineering.
EMA's 3Rs initiative is tightening the evidentiary standard for animal study justification across European marketing authorization applications. The policy compresses acceptable use cases for rodent pharmacokinetic studies to narrow safety questions that organ-chip platforms cannot yet address. Respiratory and renal safety assessment categories are responding fastest, with nephrotoxicity workflows showing 35-50% substitution rates in pilot programs.
Pharmaceutical procurement teams are consolidating vendor relationships around integrated platform-service bundles that include assay development, protocol validation, and regulatory submission support. The spot-equipment sales channel is contracting as buyers demand outcome-based partnerships with guaranteed data package acceptance. This consolidation is most visible in United States East Coast biotech clusters, where procurement committees now prioritize vendor scientific advisory depth over hardware specifications.
Global Organs-On-Chips Market Segmentation
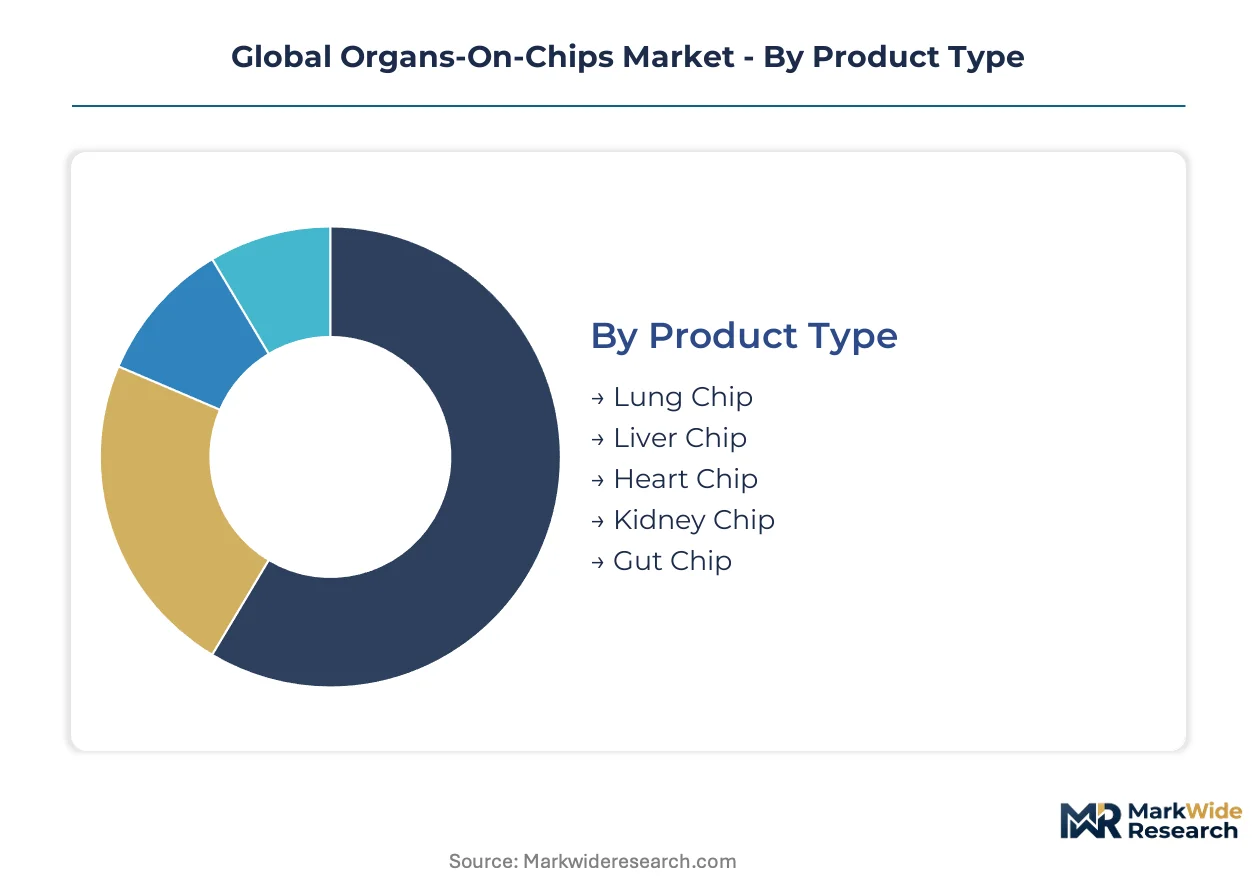
Organ-chip procurement patterns diverge sharply across customer types and application contexts. Technology choices and product configurations determine validation timelines, regulatory acceptance, and integration complexity with existing pharmaceutical workflows.
Product Type:
Liver-chip and lung-chip platforms command premium pricing due to hepatotoxicity and respiratory safety being the dominant causes of clinical trial failures and post-market withdrawals.
- Liver Chip:Hepatocyte-perfused microfluidic arrays replicate bile canaliculi transport and metabolic enzyme induction. Demand concentrates at top-20 pharmaceutical developers in Boston and Basel for preclinical hepatotoxicity screening, driven by FDA Modernization Act 2.0 enabling human-relevant data submissions.
- Lung Chip:Alveolar-capillary interface models simulate cyclic mechanical stretch and inflammatory responses. Procurement volumes are expanding fastest at respiratory-focused biotech clusters in San Francisco and Research Triangle Park, where pulmonary fibrosis and asthma drug pipelines require mechanistic safety data.
- Heart Chip:Cardiomyocyte-based platforms measure contractility and electrophysiological responses to drug candidates.
- Kidney Chip:Proximal tubule perfusion models dominate nephrotoxicity workflows for oncology and immunology compounds.
- Gut Chip:Intestinal epithelium-barrier systems capture drug absorption and microbiome interactions.
The dominant share belongs to Liver Chip, while Lung Chip is closing the gap fastest.
Technology:
Microfluidics retains the largest installed base, though capital deployment is shifting toward additive manufacturing for multi-organ integration.
- Microfluidics:PDMS-based channel networks with continuous perfusion dominate commercial production. Scale-ready platforms from established vendors anchor procurement at pharmaceutical companies requiring ISO 10993-compliant validation packages for regulatory submissions.
- 3D Bioprinting:Extrusion and light-based fabrication enable spatially patterned tissue architectures. Research institutes in Heidelberg and Singapore are driving fastest adoption for patient-matched disease models, constrained by cleanroom capex requirements exceeding $15 million for GMP facilities.
- Microelectromechanical Systems:Silicon-based sensors integrate real-time impedance and pressure readouts.
- Optical Sensors:Fluorescence and label-free imaging modules enable non-invasive endpoint monitoring.
Microfluidics holds established revenue leadership, though 3D Bioprinting exhibits the steepest expansion trajectory among emerging modalities.
Application:
Toxicity testing generates the most consistent procurement volumes due to regulatory substitution mandates, while personalized medicine commands highest per-unit pricing.
- Drug Screening:High-throughput efficacy evaluation against target pathways. Biotechnology firms in Cambridge, UK and South San Francisco are scaling procurement to 40-60 unit annual volumes for lead optimization campaigns.
- Toxicity Testing:Safety pharmacology and mechanistic toxicology studies. REACH protocols and EMA 3Rs initiative are compressing acceptable rodent study justifications, accelerating substitution with human-relevant models.
- Disease Modeling:Patient-derived cells in pathophysiological microenvironments.
- Personalized Medicine:Individual patient avatars for therapy selection.
Toxicity Testing maintains the broadest customer base, while Personalized Medicine is climbing the fastest in average contract value.
End User:
Pharmaceutical procurement committees now prioritize outcome-based partnerships over spot equipment purchases, reshaping vendor relationship economics.
- Pharmaceutical Companies:Integrated platform-service bundles with guaranteed regulatory submission support. Procurement criteria emphasize scientific advisory depth and protocol validation services at East Coast US biotech clusters.
- Biotechnology Firms:Flexible, lower-volume deployments for pipeline-specific applications. Mid-cap developers in Germany and Switzerland are adopting specialized liver-chip configurations for steatosis and fibrosis endpoints.
- Research Institutes:Multi-organ integration projects and method development.
- Academic Labs:Proof-of-concept studies and publication-driven validation.
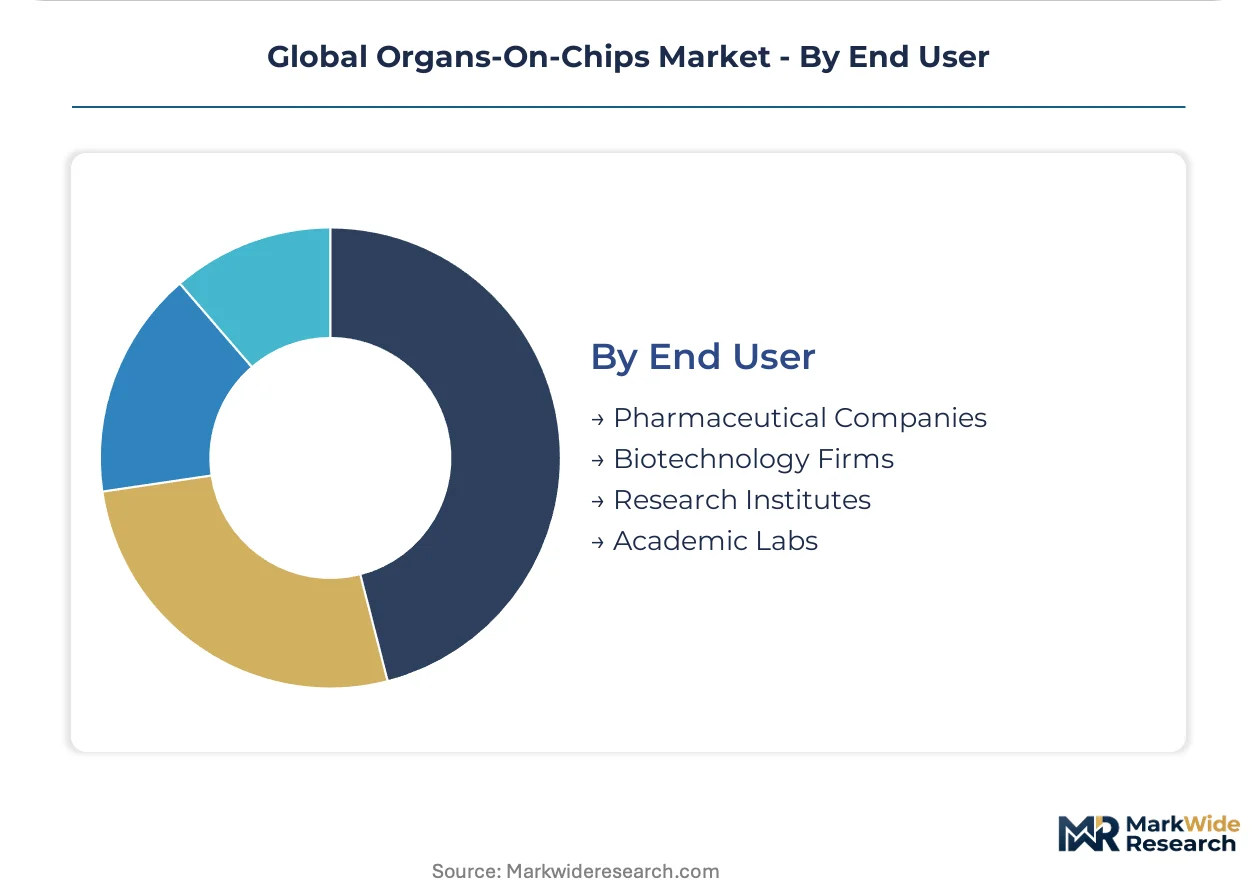
Pharmaceutical Companies control the largest procurement volumes, though Biotechnology Firms are gaining share fastest as specialized disease-state platforms fragment competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone supply chain concentration in East Asian petrochemical clusters shapes fabrication economics, while regulatory validation investments concentrate where submission volumes are highest. Platform developers prioritize markets with formal qualification pathways and concentrated pharmaceutical R&D infrastructure.
United States
FDA Modernization Act 2.0 removed mandatory animal testing requirements, creating immediate regulatory pull for human-relevant organ-chip toxicology data. Boston and San Francisco biotech clusters house concentrated R&D infrastructure where procurement committees now prioritize vendor scientific advisory depth. Emulate, Inc. anchors relationships with top-20 drug developers from these coastal hubs.
Germany
REACH protocols tighten evidentiary burdens for human-specific toxicity endpoints, accelerating replacement of rodent models with perfused microphysiological systems. Mid-cap pharmaceutical developers in Heidelberg and Basel adopt specialized liver-chip configurations for steatosis and fibrosis endpoints. Procurement volumes at these German and Swiss clusters reach 40-60 unit annual scales.
United Kingdom
EMA's 3Rs initiative compresses acceptable use cases for rodent pharmacokinetic studies to narrow safety questions. Cambridge biotechnology firms scale procurement for high-throughput efficacy evaluation against target pathways. CN Bio Innovations Ltd extends its PhysioMimix platform through co-development agreements tightening control over end-user protocols.
Japan
PMDA qualification engagement offers regulatory arbitrage for validated platform submissions as the Pharmaceuticals and Medical Devices Agency evaluates organ-chip data acceptance. Research institutes in Kanto and Kansai regions drive adoption for multi-organ integration projects. Cleanroom capex requirements exceeding $15 million constrain GMP facility expansion.
India
CDSCO's emerging interest in alternative toxicology methods creates first-mover positioning for organ-chip developers in generic drug manufacturing hubs. National pharmaceutical regulator pathway development concentrates procurement interest around Mumbai and Hyderabad clusters. Patient-matched organ-chip models face donor tissue supply constraints limiting manufacturing scale-up.
Global Organs-On-Chips Market Competitive Landscape
Concentration sits with platform developers possessing ISO 10993-compliant validation packages and regulatory submission support capabilities. The vendor base stratifies between scale-ready commercial platforms and specialized disease-state configurations. Three archetypes dominate: integrated platform-service bundlers, organ-specific scientific specialists, and multi-organ integration architects. Competitive moves center on co-development agreements tightening protocol control and geographic expansion into emerging regulatory pathways.
Within the integrated platform tier, Emulate, Inc. and CN Bio Innovations Ltd occupy positions anchoring pharmaceutical procurement relationships through bundled assay development and validation services. MIMETAS B.V. represents the organ-specific specialist archetype, with Dutch corporate structure indicating European regulatory engagement depth. These three exemplify how competitive positioning fragments around scientific credibility in specific toxicology workflows rather than generic microfluidics engineering capabilities.
| Leading Market Players |
|---|
| Emulate, Inc. |
| MIMETAS B.V. |
| CN Bio Innovations Ltd |
| InSphero |
| TissUse GmbH |
| Hesperos, Inc. |
| AxoSim |
| AlveoliX AG |
| Nortis, Inc. |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation simultaneously, as pharmaceutical procurement committees demand validated platforms with guaranteed regulatory submission support rather than commodity hardware.
Pricing Analysis
FDA Modernization Act 2.0 dictates the pricing tier structure across the United States market, separating premium platforms with full validation packages from standard configurations lacking submission-ready protocols. Price differentiation rests on ISO 10993 compliance status and scientific advisory depth bundled with hardware. Cost compression in the standard tier is intensifying because mid-cap biotechnology developers in Germany and Switzerland are consolidating vendor relationships around outcome-based partnerships. Academic laboratories exhibit the highest price sensitivity, while top-20 pharmaceutical developers prioritize scientific credibility over unit cost.
Supply Chain Analysis
China and South Korea anchor polydimethylsiloxane production for microfluidic chip substrates, with East Asian petrochemical clusters feeding global fabrication capacity. Raw material dependencies center on silicone precursors, glass substrates, and precision pumps for perfusion systems. Single-source vulnerability concentrates in PDMS supply chains exposed to regional trade restrictions. Distribution runs through direct vendor relationships with pharmaceutical procurement committees, supplemented by co-development agreements that tighten protocol control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as regulatory substitution mandates accelerate displacement of rodent toxicology models with human-relevant organ-chip platforms.
For Market Incumbents: Secure ISO 10993 validation leadership by deepening regulatory submission support capabilities before emerging platform developers achieve qualification milestones. Anchor relationships with top-tier pharmaceutical developers through bundled assay development services that raise switching costs. Counter 3D bioprinting substitution threats by integrating additive manufacturing capabilities into existing microfluidic architectures.
For New Entrants and Emerging Players: Scientific advisory capacity gaps in mid-cap biotechnology procurement create white-space entry points for specialized disease-state platforms targeting steatosis and fibrosis endpoints. India's CDSCO pathway development offers the most penetrable geography for first-mover positioning in generic drug manufacturing hubs. Pursue co-development agreements with Heidelberg and Basel clusters to establish credibility before scaling commercial operations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-organ integration projects as cleanroom capex requirements exceed fifteen million dollars for GMP-compliant facilities. Long-term viability favors platform developers with regulatory qualification depth spanning FDA, EMA, and PMDA pathways. Acquisition targets should demonstrate ISO 10993-compliant validation packages with active pharmaceutical procurement relationships. Monitor which regulatory body first issues formal qualification guidance for organ-chip data as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Pathway | FDA, EMA, and PMDA engagement determines platform data acceptance for new drug submissions. |
| Multi-Organ Integration Development | Convergence of 3D bioprinting with microfluidic perfusion enables body-on-a-chip pharmacokinetic modeling. |
| Co-Development Agreement Expansion | Protocol control tightening through pharmaceutical partnerships secures recurring revenue streams. |
| ISO 10993 Validation Investment | Biocompatibility certification packages differentiate premium platforms from commodity hardware vendors. |
| Geographic Expansion into India | CDSCO pathway development creates first-mover positioning in generic drug manufacturing clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and OECD test guideline documentation. Interviews with drug development executives, regulatory affairs leads, and hospital procurement managers informed demand-side assumptions. Supplier-side validation drew from technical R&D directors at microfluidic fabrication facilities and biomedical engineers at organ-chip platform developers. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Segmentation dimensions modeled include organ type, technology modality, application purpose, and end-user category. CAGRs derive from regression analysis of historical procurement volumes and regulatory substitution elasticity. Forecast inputs incorporate EMA 3Rs initiative implementation timelines and REACH protocol enforcement intensity across European chemical safety assessments.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA qualification pathways; material policy shifts would require re-modeling adoption curves and validation investment requirements. Recalibration cycles align with material shifts in regulatory guidance issuance and primary cell sourcing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Infusion Management Market
Medical Devices
Memory Implants Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Manometry System Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Assistive Listening Device Market