
 Compression Therapy Devices Market | 2026-2036
Compression Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Therapy Devices Market Analysis
A shift from single-source to multi-source component procurement is recalibrating cost structures across the Compression Therapy Devices landscape. Essity Aktiebolag leverages its hygiene-to-medical supply chain breadth to secure raw material flexibility. Medi GmbH & Co. KG anchors its position through vertically integrated knitting operations in Germany. SIGVARIS Group differentiates via physician-direct channels that bypass traditional distributor markups.
Compression therapy devices apply controlled external pressure to limbs through pneumatic bladders, elastic textiles, or mechanical pumps, typically operating at 20–60 mmHg for venous insufficiency protocols and higher gradients for lymphedema protocols. These systems restore lymphatic and venous return, reduce edema, and prevent thrombotic complications in post-surgical and chronic care populations. Pneumatic systems command premium positioning due to programmable cycle algorithms and reimbursement eligibility, while compression stockings represent the high-volume, lower-margin baseline accessed through pharmacy and online retail channels. Hospitals remain the gatekeeper segment for initial patient qualification, though homecare settings are capturing the fastest growth trajectory as ambulatory reimbursement expands.
FDA 510(k) clearance requirements and the EU MDR's tightened clinical evidence standards are elevating barriers for pneumatic controller entrants while reinforcing incumbent quality positions. The EPA and OSHA frameworks indirectly shape manufacturing through material safety and workplace exposure protocols for textile adhesives and polymer processing. Stakeholders must monitor reimbursement parity between in-clinic and at-home pneumatic therapy as payer policies determine volume migration speed.
Market Dynamics
Medicare reimbursement parity between in-clinic and at-home pneumatic therapy is accelerating patient volume migration toward ambulatory settings, forcing manufacturers to redesign controller portability and patient monitoring capabilities.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for lymphedema pumps under the Medicare Improvements for Patients and Providers Act sustains homecare demand in the United States.
- Chronic Disease Prevalence:Rising post-mastectomy lymphedema cases and venous insufficiency in aging populations expand the addressable patient base across North America and Western Europe.
- Smart Textile Integration:Embedded pressure sensors and Bluetooth-enabled controllers enable remote patient monitoring, attracting health system investment in connected device infrastructure.
Market Restraints
- Polymer Input Volatility:Medical-grade elastomer and polyurethane bladder material costs fluctuate with petrochemical feedstock prices, compressing margin stability for pneumatic system manufacturers.
- EU MDR Compliance Burden:The Medical Device Regulation's tightened clinical evidence requirements extend clearance timelines and elevate documentation costs for pneumatic controller market entrants.
- Compression Garment Substitution:Low-cost graduated compression stockings address mild venous insufficiency cases, limiting addressable volume for premium pneumatic systems in early-stage patient populations.
Strategic Opportunities
- India Outpatient Penetration:Underdeveloped lymphedema management infrastructure and expanding private hospital networks create first-mover potential for portable pneumatic systems in tier-2 cities.
- Oncology Rehabilitation Integration:Cancer center partnerships for post-surgical edema prevention open institutional procurement channels distinct from traditional wound care distribution.
- ISO 13485 Certification Acceleration:Quality management system standardization enables faster regulatory pathway navigation across multiple jurisdictions for compliant manufacturers.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of professionals skilled in pneumatic pump algorithm development and textile-pressure interface design constrains R&D throughput for mid-tier manufacturers.
- FDA 510(k) Documentation Intensity:Substantial equivalence demonstrations for programmable cycle controllers require extensive predicate device analysis and clinical data compilation, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Therapy Devices Market |
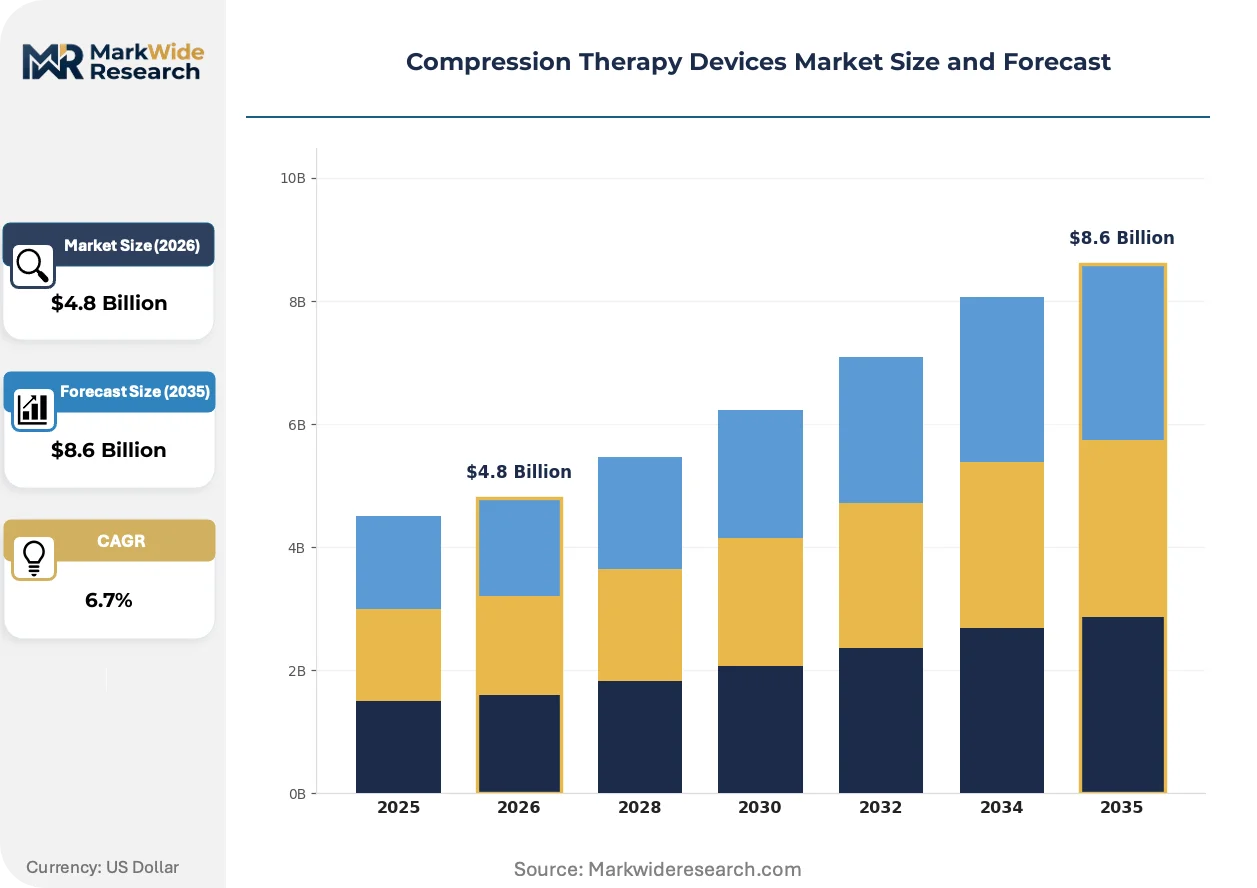
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequential, Gradient, Compression Stockings, Pneumatic End User: Hospitals, Homecare Settings, Rehabilitation Centers, Sports Clinics Treatment Area: Venous Insufficiency, Lymphedema, Post-Surgical Recovery, Varicose Veins Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Essity Aktiebolag, Medi GmbH & Co. KG, SIGVARIS Group, 3M, Cardinal Health, Tactile Systems Technology, Arjo, Julius Zorn GmbH, Bio Compression Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Therapy Devices Market Emerging Trajectories
Programmable pneumatic controllers with embedded biosensors are displacing static compression modalities, while regulatory tightening and procurement centralization reshape competitive positioning across manufacturer tiers.
Dynamic pressure mapping technology with real-time limb circumference adjustment is overtaking fixed-cycle pneumatic pumps in post-acute care settings. Hospital systems in Germany and the United States are prioritizing these systems for lymphedema protocols. This capability is overtaking conventional timer-based pumps by reducing nursing intervention requirements and supporting value-based reimbursement metrics.
The EU MDR's post-market surveillance requirements and Unique Device Identification mandates are elevating traceability infrastructure investments. Manufacturers must now maintain clinical follow-up registries for Class IIa pneumatic devices. European contract manufacturers are absorbing these compliance costs by consolidating production footprints and abandoning low-volume SKUs.
Hospital procurement consortia are consolidating supplier panels and demanding outcome guarantees for pneumatic therapy programs. Group purchasing organizations are displacing independent distributor relationships in the United States. This concentration is most visible in integrated delivery networks across Texas and Florida, where standardized device protocols reduce variation in edema management outcomes.
Compression Therapy Devices Market Segmentation
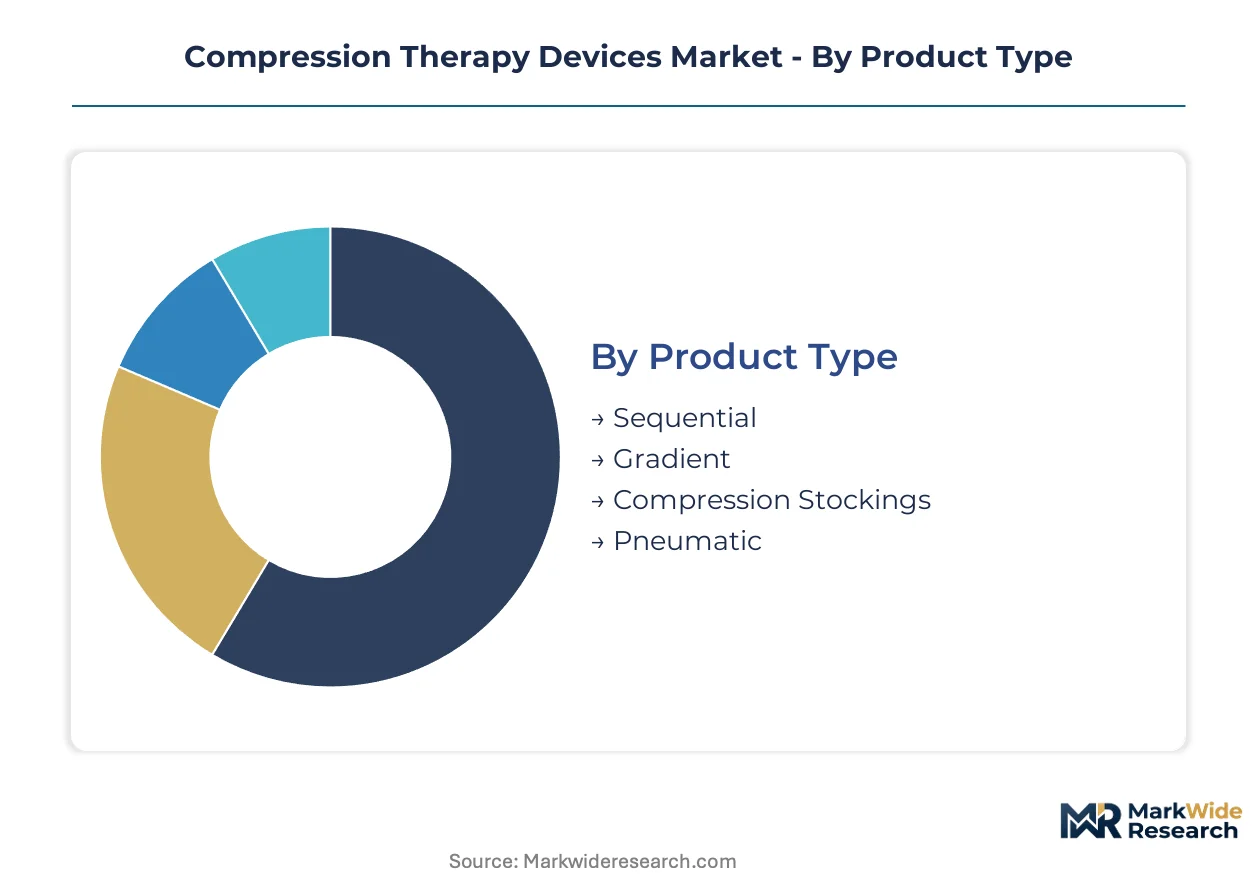
Segmentation in compression therapy devices reveals divergent margin structures and procurement pathways. Product architecture, care setting, clinical indication, and channel economics each reshape competitive positioning and investment priorities for manufacturers.
Product Type:
Supply concentration in pneumatic controller manufacturing creates tiered competitive barriers across device architectures.
- Sequential:Multi-chamber inflatable garments deliver calibrated pressure waves from distal to proximal limb segments. Demand concentrates in post-mastectomy lymphedema protocols at US cancer centers, where Medicare reimbursement for sequential pumps sustains premium pricing.
- Gradient:Static textile-based systems with engineered compression gradients operate without powered components. German knitting houses and Italian medical textile specialists anchor European supply, serving chronic venous insufficiency patients through pharmacy channels.
- Compression Stockings:Elastic hosiery manufactured on circular knitting machines dominates unit volume.
- Pneumatic:Programmable pump-driven systems with biosensor feedback command the highest reimbursement tiers.
Today's leader: Sequential systems. Tomorrow's challenger: Pneumatic platforms with embedded monitoring.
End User:
Cost tier stratification separates capital-intensive institutional procurement from patient-directed retail acquisition.
- Hospitals:Integrated delivery networks in Texas and Florida standardize pneumatic protocols through group purchasing organization contracts. These systems require FDA 510(k) clearance and clinical outcome documentation for value-based reimbursement.
- Homecare Settings:Portable sequential pumps with Bluetooth connectivity enable remote patient monitoring. Medicare coverage expansion under the Medicare Improvements for Patients and Providers Act accelerates patient volume migration from inpatient to ambulatory management.
- Rehabilitation Centers:Outpatient physical therapy facilities prioritize rental-ready pneumatic units.
- Sports Clinics:Athletic recovery applications favor rapid-inflation gradient systems.
Volume concentrates in hospitals. Margin expansion is climbing the fastest in homecare settings.
Treatment Area:
Application maturity varies across clinical indications, with established protocols competing against emerging therapeutic expansions.
- Venous Insufficiency:Chronic lower-limb edema management represents the most penetrated indication. Graduated compression stockings address mild-to-moderate cases through pharmacy and online retail channels.
- Lymphedema:Post-surgical and primary lymphatic disorders drive pneumatic system adoption. US cancer center partnerships and dedicated lymphedema clinics sustain demand for programmable sequential pumps with pressure mapping capabilities.
- Post-Surgical Recovery:Orthopedic and vascular surgery protocols increasingly specify intermittent pneumatic compression for thromboprophylaxis.
- Varicose Veins:Cosmetic and symptomatic vein treatment supports compression stocking volume.
Revenue leadership sits with lymphedema. Post-surgical recovery is gaining share fastest.
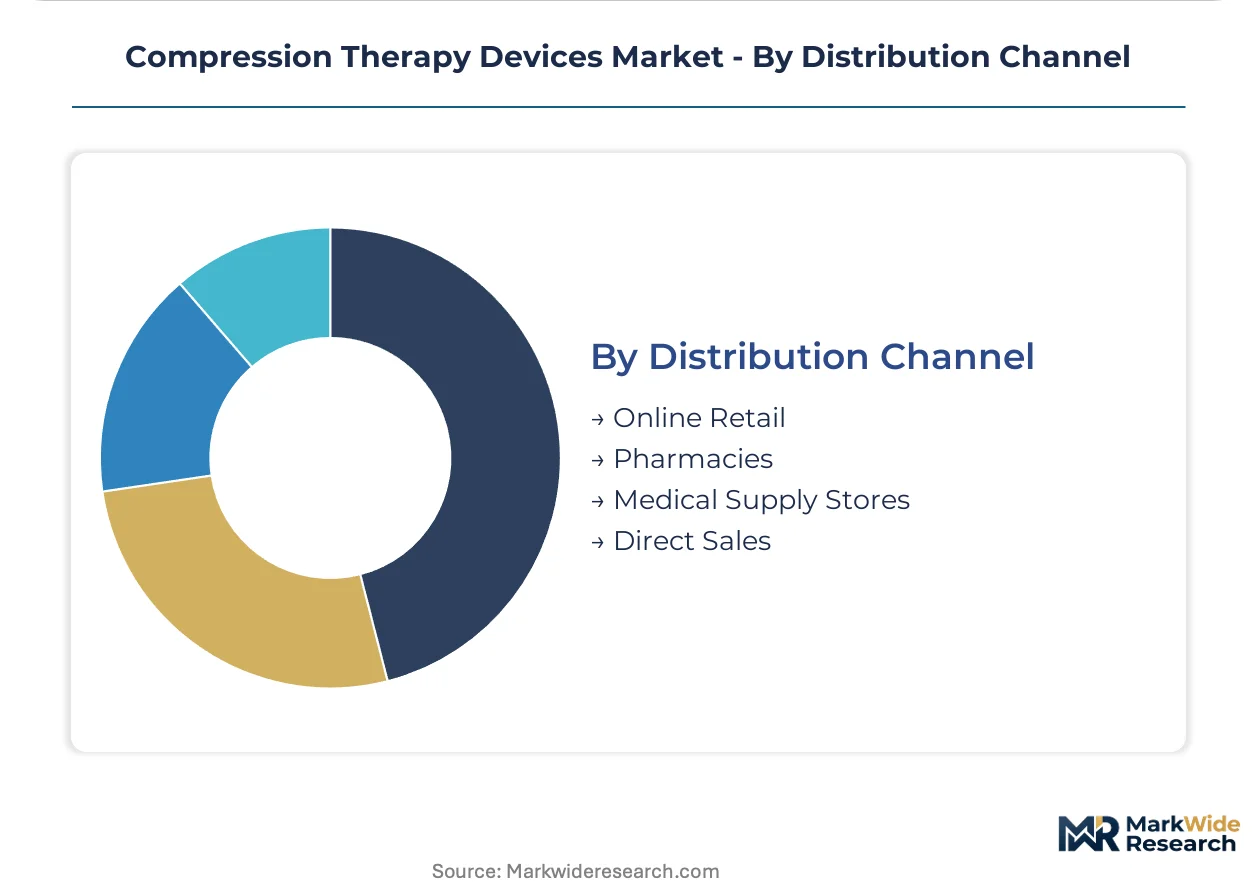
Distribution Channel:
Customer type fragmentation separates institutional procurement from direct-to-patient commerce.
- Online Retail:Direct-to-consumer compression stocking sales bypass traditional medical supply intermediaries. Amazon and specialized orthopedic e-commerce platforms capture patient self-pay volume for mild venous insufficiency management.
- Pharmacies:Community and hospital outpatient pharmacies stock graduated compression hosiery. Walgreens and CVS Health maintain dedicated medical supply sections for physician-recommended compression garments.
- Medical Supply Stores:Durable medical equipment dealers handle pneumatic pump rentals and sales.
- Direct Sales:Manufacturer field representatives call on hospital wound care committees and cancer center procurement.
Pharmacies anchor volume. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Essity Aktiebolag's Swedish headquarters anchors the European medical textile cluster, though Medicare reimbursement dynamics in the United States generate the dominant revenue pool for pneumatic compression systems.
United States
Post-mastectomy lymphedema protocols at MD Anderson Cancer Center and Memorial Sloan Kettering sustain sequential pump demand. CMS reimbursement parity between in-clinic and at-home pneumatic therapy accelerates patient volume migration toward ambulatory settings. Texas and Florida integrated delivery networks standardize device protocols through group purchasing organization contracts.
Germany
Medi GmbH & Co. KG's vertically integrated knitting operations in Bayreuth anchor European graduated compression supply. EU MDR post-market surveillance requirements and Unique Device Identification mandates elevate traceability infrastructure investments. Baden-Württemberg medical device manufacturers consolidate production footprints to absorb compliance costs.
India
Underdeveloped lymphedema management infrastructure and expanding private hospital networks in tier-2 cities create first-mover potential for portable pneumatic systems. CDSCO medical device regulations tighten quality benchmarks for imported controllers. Maharashtra and Karnataka oncology centers pilot post-surgical edema prevention protocols.
Japan
Aging demographics and rising venous insufficiency prevalence expand the addressable patient base for compression therapy. PMDA regulatory pathways require clinical evidence demonstrations for programmable cycle controllers. Osaka-based medical textile specialists serve chronic care populations through pharmacy channels.
United Kingdom
NHS procurement consortia consolidate supplier panels and demand outcome guarantees for pneumatic therapy programs. MHRA post-Brexit regulatory alignment with EU MDR standards extends clearance timelines. London and Southeast England cancer rehabilitation centers prioritize rental-ready pneumatic units.
Compression Therapy Devices Market Vendor Landscape
Global majors compete with regional champions across reimbursement access and textile manufacturing depth. The vendor base stratifies between pneumatic system specialists with FDA 510(k) clearance portfolios and graduated compression houses with circular knitting scale. Three archetypes dominate: vertically integrated European textile manufacturers, US-based reimbursement-driven pump developers, and Asian contract manufacturers serving private-label pharmacy channels. Competitive moves center on group purchasing organization contract capture and EU MDR compliance infrastructure consolidation.
Within the vertically integrated tier, Essity Aktiebolag and Medi GmbH & Co. KG exemplify European supply chain control, while SIGVARIS Group occupies a position bridging physician-direct distribution with textile manufacturing heritage. These entities represent contrasting strategic anchors: hygiene-to-medical supply chain breadth, captive knitting operations, and bypass-channel market access respectively.
| Leading Market Players |
|---|
| Essity Aktiebolag |
| Medi GmbH & Co. KG |
| SIGVARIS Group |
| 3M |
| Cardinal Health |
| Tactile Systems Technology |
| Arjo |
| Julius Zorn GmbH |
| Bio Compression Systems |
| Others |
Supply Flow & Price Mechanics
Group purchasing organization concentration among Texas and Florida integrated delivery networks enforces contract-based long-term offtake pricing for pneumatic controllers, while Medicare reimbursement bands cap patient out-of-pocket exposure for homecare sequential pumps.
Pricing Analysis
Medical-grade elastomer and polyurethane bladder material costs pass through to pneumatic system manufacturers with 3-6 month lags, compressing margin stability when petrochemical feedstocks spike. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and Bluetooth-enabled remote monitoring capabilities. Cost pressure stems from EU MDR documentation burdens extending clearance timelines for new entrants. Hospital procurement committees exhibit lowest price sensitivity due to outcome-based reimbursement metrics, while direct-to-consumer compression stocking buyers on Amazon and pharmacy platforms drive aggressive price competition.
Supply Chain Analysis
FDA 510(k) and EU MDR quality system certifications gate supplier qualification for pneumatic controller assemblies, concentrating approved component sourcing among German textile engineers and Taiwanese precision pump manufacturers. Raw material dependencies center on medical-grade elastomers, circular knitting machines for gradient garments, and biosensor microcontrollers. Single-source vulnerability runs through specialized knitting equipment suppliers in Baden-Württemberg. Distribution runs through group purchasing organization contracts for institutional volumes and durable medical equipment dealers for homecare rentals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compression therapy device manufacturing arbitrage favors India and Southeast Asian assembly for export to regulated markets, exploiting wage differentials against EU MDR compliance costs that anchor European production.
For Market Incumbents: To counter portable pneumatic entrants from Asian contract manufacturers, Essity and Medi should deepen backward integration into medical-grade elastomer compounding and secure exclusive group purchasing organization contracts across Texas and Florida integrated delivery networks. FDA 510(k) predicate device libraries serve as defensive moats against fast-follower entrants. For New Entrants and Emerging Players: The mid-tier price gap between premium programmable pumps and economy compression stockings opens white-space targeting for Bluetooth-enabled sequential systems at rehabilitation centers and oncology outpatient clinics. India's tier-2 city private hospital networks present the most penetrable geography, with CDSCO regulatory consulting as the critical go-to-market enabler. For Investors and Strategic Acquirers: Medical device conglomerates with wound care portfolios are the most active acquirers in this space, seeking pneumatic controller capabilities to complement negative pressure wound therapy platforms. Acquisition targets should display ISO 13485 certification and existing Medicare reimbursement codes. The signal to watch is CMS reimbursement parity expansion for at-home lymphedema pumps, which would accelerate ambulatory volume migration and revalue homecare-focused assets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks Medicare reimbursement eligibility for sequential pneumatic systems at US cancer centers. |
| CE Marking Under EU MDR | Enables market access across Germany, France, and UK hospital procurement consortia with traceability compliance. |
| Hospital System Partnership | MD Anderson and Memorial Sloan Kettering protocols establish clinical evidence for lymphedema pump adoption. |
| Software Companion Development | Bluetooth-enabled pressure monitoring attracts health system investment in connected device infrastructure. |
| Reimbursement Strategy | Medicare Improvements for Patients and Providers Act coverage sustains homecare demand migration. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and lymphedema clinic directors with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation, and hospital procurement records. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored market size estimates.
Segment-weighting across product architecture, care setting, clinical indication, and distribution channel shaped the analytical framework over the projection horizon. CAGRs derived from patient population growth trajectories, reimbursement policy elasticity, and technology substitution curves for smart textile integration. Modeled inputs included post-mastectomy lymphedema incidence rates and venous insufficiency prevalence by age cohort.
Caveats apply where EU MDR enforcement intensity, polymer feedstock volatility, or CMS reimbursement band adjustments could materially shift the outlook. A model refresh is warranted upon material change in Medicare homecare parity policy or FDA 510(k) predicate device recall events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Prosthetics Market
Medical Devices
Medical Thermometer Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Catheter Introducer Sheaths Market