
 Global Cryotherapy Market | 2026-2036
Global Cryotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryotherapy Market Foresight
Hospital procurement departments is bifurcating between capital-intensive integrated cryotherapy suites and modular localized units for outpatient expansion. Zimmer MedizinSysteme leverages decades of German engineering heritage in thermal therapy systems to dominate European hospital tenders. Medtronic competes through deep catheter-based cryoablation expertise tied to cardiac electrophysiology workflows. Brymill Cryogenic Systems specializes in handheld dermatology cryosurgery instruments for private practice penetration.
Cryotherapy deploys extreme cold—typically liquid nitrogen at minus 196 degrees Celsius or refrigerated cold air—to destroy abnormal tissue, reduce inflammation, or induce therapeutic vasoconstriction, with primary commercial purpose spanning oncologic intervention, musculoskeletal recovery, and aesthetic skin resurfacing. Cryoablation equipment leads capital expenditure allocation among product types as interventional radiology departments expand tumor ablation services. Aesthetic therapy applications command premium pricing within deployment categories, where spa and wellness centers drive recurring revenue against clinic-installed systems that amortize through procedure volume.
FDA breakthrough device designation pathways compress cryoablation approval timelines, while EU MDR compliance requirements force device manufacturers to rebuild clinical evidence packages for CE-marked thermal therapy systems. ISO 13485 quality management standards govern manufacturing consistency across export-oriented German and US production facilities. Stakeholders must monitor reimbursement code consolidation for office-based cryosurgery versus hospital outpatient ablation as payer cost-control measures reshape site-of-service economics.
Market Dynamics
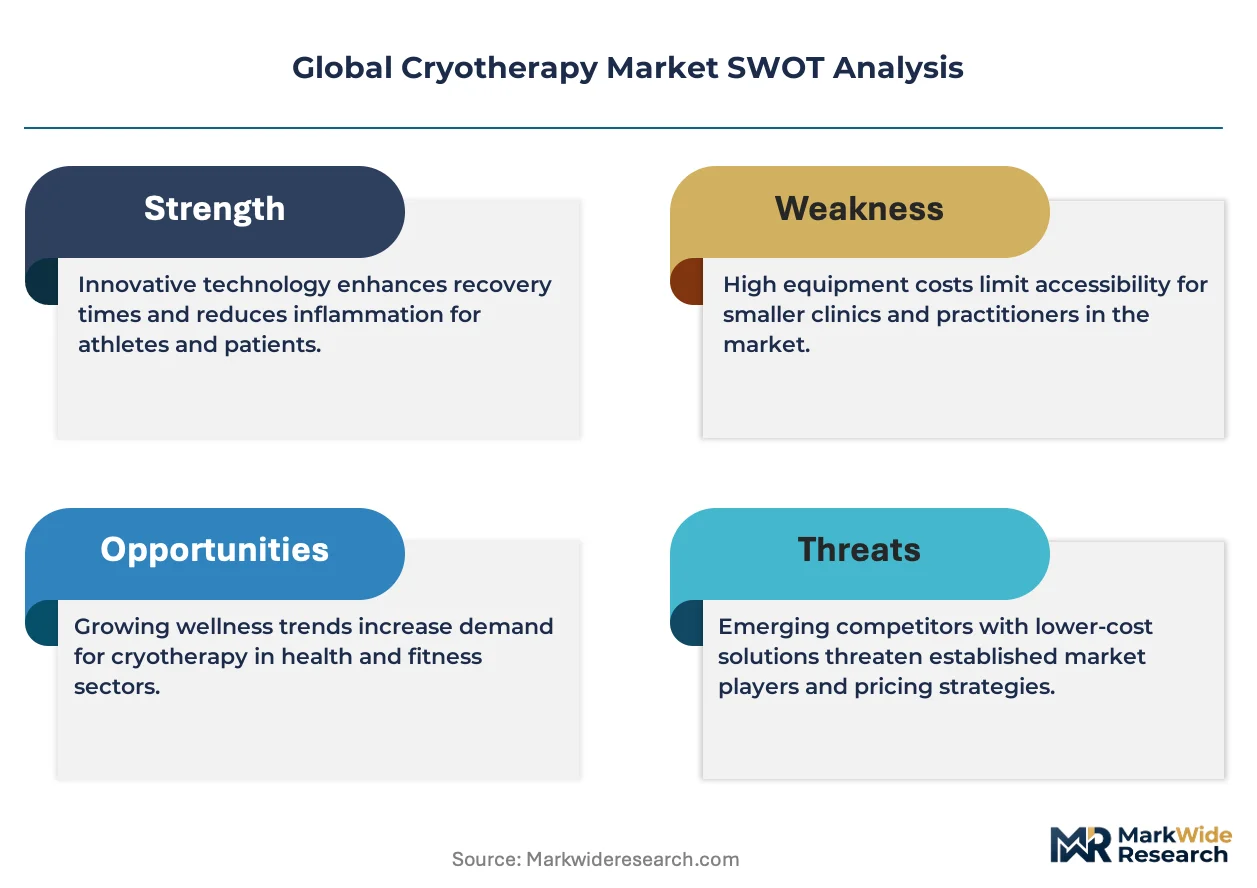
Hospital procurement departments are bifurcating capital allocation between integrated cryotherapy suites and modular localized units, reshaping vendor competitive dynamics across oncology, sports medicine, and aesthetic verticals.
Growth Catalysts
- FDA breakthrough pathways:Compressed review timelines for cryoablation devices accelerate interventional radiology department expansion into tumor ablation services.
- Sports medicine protocols:University hospital athletic departments are formalizing cold therapy regimens for post-surgical recovery and acute injury management.
- German manufacturing clusters:Concentrated engineering expertise in thermal therapy systems anchors European supply reliability and export capacity.
Market Restraints
- Liquid nitrogen supply volatility:Cryogen logistics and storage infrastructure costs constrain outpatient clinic adoption outside hospital systems.
- EU MDR compliance burden:Rebuilt clinical evidence requirements for CE-marked thermal therapy systems delay product refresh cycles.
- Radiofrequency ablation substitution:Competing thermal ablation modalities capture share in cardiac and hepatic intervention segments.
Strategic Opportunities
- India outpatient expansion:Underpenetrated dermatology and pain management clinics present first-mover positioning for localized cryosurgery units.
- Wellness channel integration:Spa and recovery center networks are creating recurring revenue streams distinct from capital-intensive hospital sales.
- ISO 13485 certification harmonization:Unified quality management standards reduce friction for German and US manufacturers entering mutual export markets.
Industry Challenges
- Interventional radiologist training pipelines:Specialized cryoablation credentialing requirements outpace fellowship program expansion.
- Reimbursement code fragmentation:Divergent payer classification for office-based versus hospital outpatient procedures complicates pricing strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryotherapy Market |
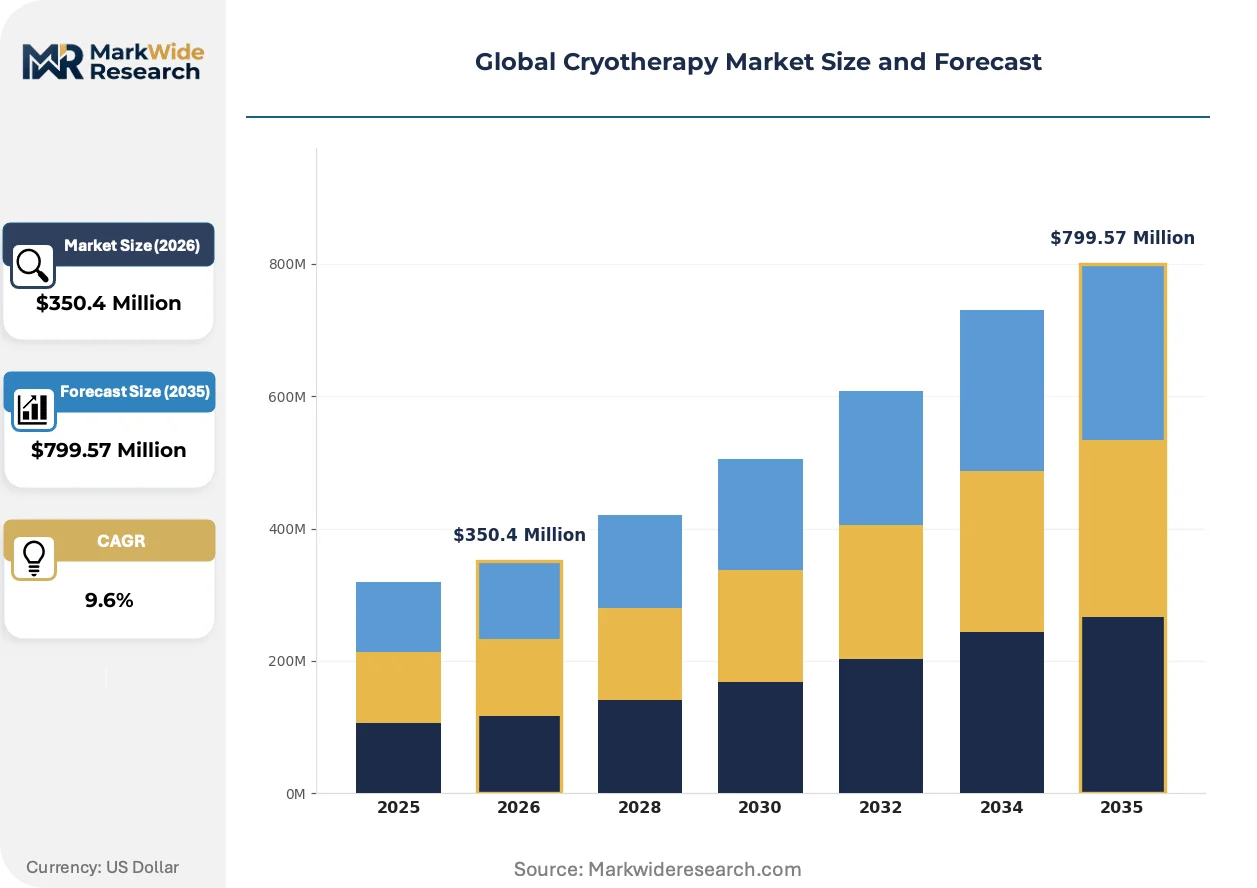
| Market Size in 2026 | $350.4 Million |
| Market Size in 2035 | $799.57 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Body Cryotherapy, Localized Cryotherapy, Cosmetic Cryotherapy, Cryosurgical Devices, Cryoablation Equipment Application: Pain Management, Sports Recovery, Dermatology Treatments, Neurological Disorders, Rheumatology, Aesthetic Therapy End User: Rehabilitation Centers, Sports Clinics, Dermatology Centers, Neurology Facilities, Rheumatology Practices Deployment: Standalone Units, Integrated Systems, Mobile Cryotherapy Units, Clinic Installed, Spa & Wellness Centers |
| Companies Covered | Zimmer MedizinSysteme, Medtronic, Impact Cryotherapy, Boston Scientific Corporation, Erbe Elektromedizin GmbH, MECOTEC GmbH, CryoBuilt, CRYO Science, Brymill Cryogenic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryotherapy Market Shifts & Advancements
Device miniaturization and closed-loop temperature control are compressing the performance gap between hospital-grade and portable systems, enabling site-of-service migration that reshapes competitive positioning.
Closed-loop cryogen delivery systems with integrated temperature feedback are displacing open-loop liquid nitrogen spray devices in dermatology practices. Outpatient clinics in Germany and the US are adopting these platforms to reduce tissue damage variance and standardize lesion treatment protocols. The shift is compressing demand for high-volume cryogen storage infrastructure at smaller practice sites.
EU MDR clinical evidence requirements are forcing manufacturers to rebuild post-market surveillance frameworks for legacy thermal therapy devices. German notified bodies are prioritizing cryoablation system reviews amid backlog congestion, delaying CE mark renewals for mid-tier competitors. Cardiac electrophysiology catheter systems face the steepest compliance cost escalation.
After-sales service unbundling is separating equipment maintenance contracts from consumable supply agreements. Hospital procurement teams in France and Japan are negotiating standalone technical service tiers while sourcing cryogen and probes through group purchasing organizations. The disaggregation is most advanced in academic medical center networks with centralized biomedical engineering departments.
Global Cryotherapy Market Segmentation
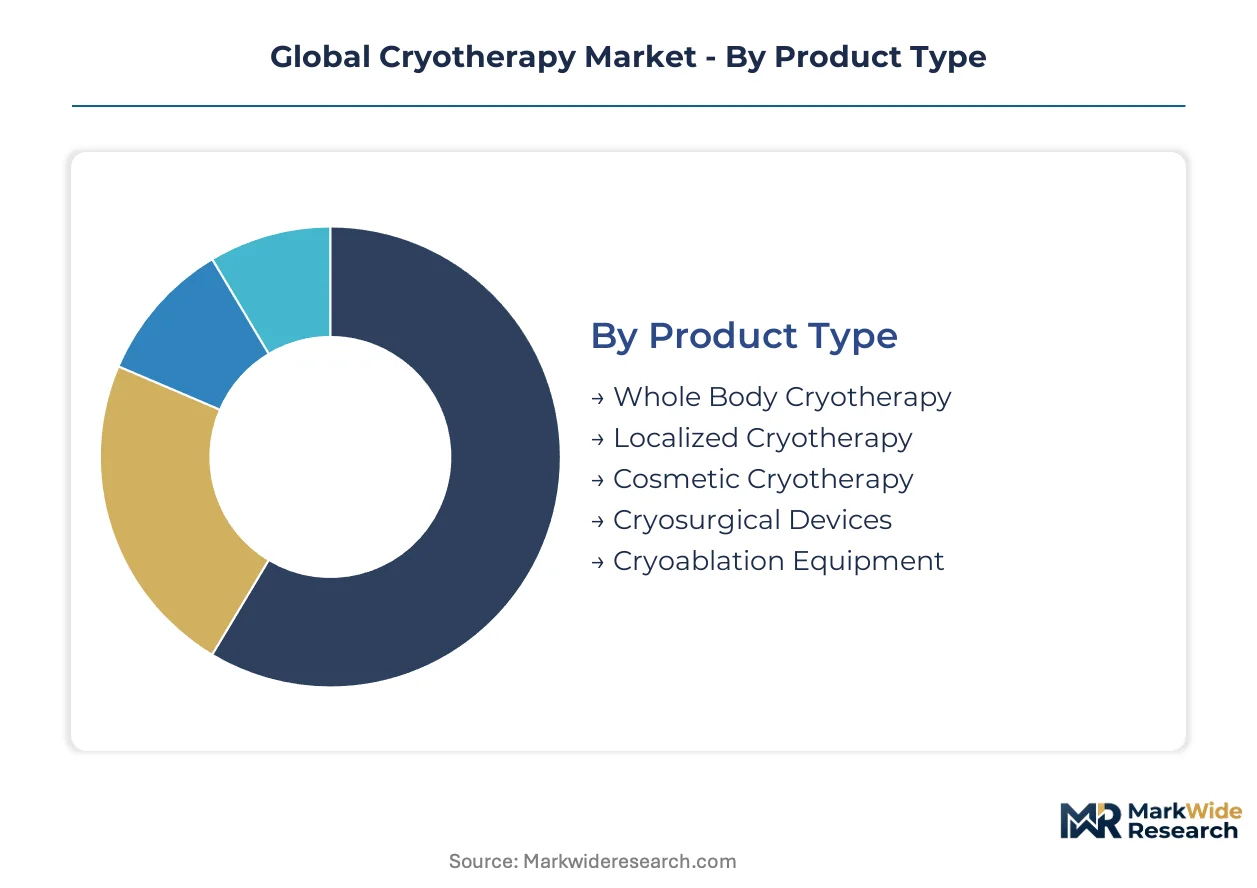
Cryotherapy equipment flows through distinct procurement channels shaped by capital intensity, site-of-service economics, and reimbursement pathways. Understanding segment-channel alignment reveals where margin concentrates and where volume expansion accelerates.
Product Type:
Hospital procurement teams route high-value cryoablation systems through integrated capital budgets, while outpatient channels favor modular localized units with lower infrastructure requirements.
- Cryoablation Equipment:Tumor-destroying systems deploy pressurized argon-helium gas cycles to create precise freeze-thaw zones for interventional radiology. Demand concentrates in US academic medical centers expanding ablation services under FDA breakthrough pathways.
- Localized Cryotherapy:Targeted cold air or contact devices treat musculoskeletal injuries without whole-body exposure. German sports medicine departments and US physical therapy chains drive procurement for post-surgical recovery protocols.
- Whole Body Cryotherapy:Chamber-based systems exposing patients to minus 110 to minus 140 degrees Celsius for systemic anti-inflammatory response. Wellness networks and elite athletic facilities dominate uptake.
- Cryosurgical Devices:Handheld liquid nitrogen spray or probe instruments for dermatologic lesion destruction. Private dermatology practices across France and Japan favor portable units with minimal cryogen storage footprints.
- Cosmetic Cryotherapy:Facial and body contouring platforms leveraging cold-induced vasoconstriction for aesthetic applications. Med-spa chains in Dubai and Seoul deploy these for recurring revenue streams distinct from clinical reimbursement.
By volume, Cryosurgical Devices leads through high unit turnover in dermatology. By growth pace, Cryoablation Equipment is climbing fastest as interventional radiology expands oncology services.
Application:
Reimbursement codes and site-of-service economics split applications between hospital outpatient departments and independent clinic settings, with aesthetic therapy operating entirely outside payer frameworks.
- Pain Management:Cold therapy protocols for chronic and acute pain reduction, including post-operative recovery and neuropathic conditions. US pain clinics and German rehabilitation centers integrate localized cryotherapy into multimodal treatment plans.
- Sports Recovery:Cryogenic protocols for muscle repair, inflammation reduction, and return-to-play acceleration. Professional athletic organizations and university sports medicine programs in Australia and the UK standardize these regimens.
- Dermatology Treatments:Lesion destruction for actinic keratosis, warts, and benign skin growths using liquid nitrogen or nitrous oxide. High procedure volumes in outpatient dermatology practices across Italy and Spain sustain equipment refresh cycles.
- Aesthetic Therapy:Non-medical cold applications for skin tightening, cellulite reduction, and facial rejuvenation. Wellness centers in Thailand and Brazil monetize through membership models rather than fee-for-service.
- Rheumatology:Cryogenic interventions for inflammatory joint conditions and autoimmune symptom management. Hospital-based rheumatology departments in Switzerland and the Netherlands pilot whole-body protocols for refractory cases.
- Neurological Disorders:Experimental and established cold therapies for migraine, spasticity, and neuroinflammation. Academic neurology centers in Canada and Sweden conduct protocol development with limited commercial scale.
By patient volume, Dermatology Treatments dominates through high-frequency outpatient procedures. By revenue per encounter, Aesthetic Therapy commands premium pricing outside reimbursement constraints.
End User:
Facility type determines equipment specifications, with hospital-affiliated sites prioritizing interoperability and independent clinics emphasizing space efficiency and operational flexibility.
- Sports Clinics:Dedicated athletic recovery facilities and team medical centers. Australian Rules Football and English Premier League medical departments drive specification requirements for rapid cooling protocols.
- Dermatology Centers:Specialized skin care facilities ranging from solo practices to multi-site groups. French and Italian dermatology networks consolidate procurement through group purchasing organizations.
- Rehabilitation Centers:Post-acute and chronic care facilities integrating cryotherapy into physical therapy workflows. German medical rehabilitation clinics (Medizinische Reha-Kliniken) represent concentrated demand.
- Neurology Facilities:Hospital departments and specialized institutes exploring cryogenic applications for movement disorders and headache management. Academic centers in Stockholm and Montreal lead protocol development.
- Rheumatology Practices:Outpatient clinics and hospital departments treating autoimmune and inflammatory joint disease. Swiss rheumatology networks coordinate equipment trials for cryotherapy adjuncts.
By installed base, Dermatology Centers holds the largest footprint. By expansion velocity, Sports Clinics is gaining share fastest as professional and amateur athletic organizations formalize recovery infrastructure.
Deployment:
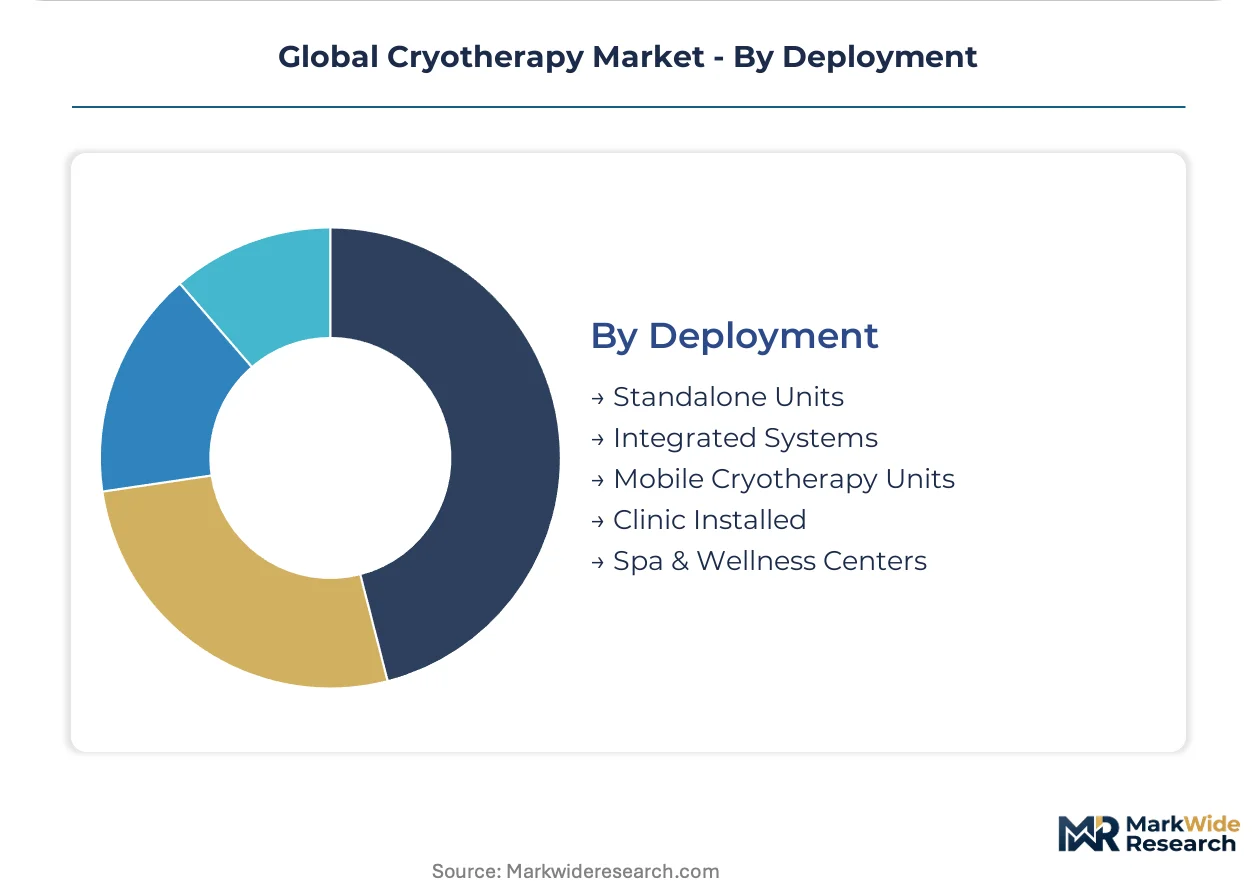
Physical configuration options reflect site constraints, patient throughput requirements, and capital availability across hospital, clinic, and wellness environments.
- Standalone Units:Self-contained cryotherapy systems requiring minimal facility modification. Independent pain clinics and small dermatology practices in Poland and Mexico prioritize these for rapid deployment.
- Integrated Systems:Built-in installations with dedicated cryogen supply, ventilation, and safety infrastructure. US hospital outpatient departments and German university hospitals specify these for high-volume oncology and sports medicine services.
- Mobile Cryotherapy Units:Transportable chambers or localized devices for event-based or multi-site service delivery. Elite athletic teams and wellness tour operators in the UAE and Singapore deploy these for flexible access.
- Clinic Installed:Permanent equipment integrated into medical office buildouts with appropriate electrical and ventilation specifications. Multi-site dermatology groups in Japan and South Korea standardize these configurations.
- Spa & Wellness Centers:Non-medical installations emphasizing aesthetic and recovery experiences rather than clinical outcomes. Hotel wellness programs in Maldives and Bali integrate these into premium amenity packages.
By unit shipments, Standalone Units leads through accessibility and lower capital barriers. By revenue concentration, Integrated Systems captures the highest per-installation value through comprehensive infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cryotherapy equipment exports flow primarily into US hospital systems and Japanese aesthetic clinic networks, establishing a transatlantic-Pacific trade corridor that channels precision thermal therapy manufacturing toward high-margin procurement channels.
United States
FDA breakthrough device designations compress cryoablation approval timelines for interventional radiology departments expanding tumor ablation services. The agency's streamlined review pathways for thermal therapy systems accelerate capital deployment in academic medical centers. Boston and Houston anchor hospital procurement clusters where integrated cryotherapy suites command premium installation contracts.
Germany
EU MDR compliance requirements force device manufacturers to rebuild clinical evidence packages for CE-marked thermal therapy systems. German notified bodies prioritize cryoablation system reviews amid regulatory backlog congestion. Tübingen and Munich manufacturing clusters concentrate engineering expertise in closed-loop cryogen delivery platforms.
Japan
PMDA regulatory harmonization with ISO 13485 standards reduces friction for German and US manufacturers entering the market. METI industrial policy supports medical device export capacity through precision manufacturing subsidies. Tokyo and Osaka dermatology center networks drive localized cryosurgery unit procurement for high-frequency lesion treatment protocols.
Australia
TGA medical device registration pathways align with international quality management standards to streamline import clearance for thermal therapy equipment. Professional athletic organizations formalize recovery infrastructure spending under national sports performance programs. Melbourne and Sydney sports medicine departments standardize cold therapy regimens for post-surgical recovery.
India
CDSCO medical device regulations classify cryotherapy equipment under import licensing frameworks that prioritize quality-certified manufacturing origins. Underpenetrated dermatology and pain management clinics present positioning opportunities for localized cryosurgery units. Mumbai and Bangalore outpatient networks consolidate procurement through group purchasing organizations.
Global Cryotherapy Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with cryotherapy as a vertical segment, alongside specialized thermal therapy engineering firms with decades of focused manufacturing heritage. Market structure exhibits tiered consolidation where premium-tier integrated systems concentrate among three to four established vendors, while portable and aesthetic segments fragment across mid-scale specialists. Strategic archetypes span catheter-based cryoablation specialists, German precision engineering houses, and handheld dermatology instrument fabricators. Competitive moves center on regulatory pre-clearance positioning for breakthrough designations and service contract unbundling to capture recurring revenue streams.
Within the German engineering heritage tier, Zimmer MedizinSysteme and MECOTEC GmbH occupy positions reflecting concentrated thermal therapy system expertise. Among diversified medical technology conglomerates, Medtronic represents the catheter-based cryoablation archetype tied to cardiac electrophysiology workflows. Brymill Cryogenic Systems exemplifies the handheld instrument specialist segment serving private dermatology practice penetration.
| Leading Market Players |
|---|
| Zimmer MedizinSysteme |
| Medtronic |
| Impact Cryotherapy |
| Boston Scientific Corporation |
| Erbe Elektromedizin GmbH |
| MECOTEC GmbH |
| CryoBuilt |
| CRYO Science |
| Brymill Cryogenic Systems |
| Others |
Supply & Pricing Matrix
Long-term cryogen supply contracts with take-or-pay clauses lock in liquid nitrogen access for German and US hospital systems while freezing price volatility for interventional radiology departments expanding tumor ablation services. These arrangements tether equipment vendors to regional gas distributors, compressing margin flexibility for outpatient clinics lacking procurement scale.
Pricing Analysis
Next-generation closed-loop cryogen delivery systems command substantial premiums over open-loop liquid nitrogen spray devices, while legacy handheld dermatology instruments face cost compression from modular localized units. Three-tier pricing structure across premium integrated suites, standard clinic-installed systems, and economy standalone devices reflects FDA breakthrough designation status and ISO 13485 certification tier. Pricing pressure stems from EU MDR compliance cost pass-through and radiofrequency ablation substitution in cardiac segments. Outpatient dermatology practices exhibit highest price sensitivity due to consumable dependency, while academic medical centers prioritize interoperability over unit economics.
Supply Chain Analysis
Inventory buffers for pressurized argon-helium gas cylinders stretch lead times for cryoablation equipment manufacturers serving US hospital networks. Manufacturing concentrates in Germany, the United States, and Japan, drawing from specialized cryogenic valve components, precision temperature sensors, and medical-grade stainless steel feedstock. Single-source vulnerability in liquid nitrogen regional distribution creates bottlenecks for spa and wellness center deployments. Distribution runs through hospital group purchasing organizations in North America and specialized medical device distributors in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from cryogen replenishment contracts and preventive maintenance agreements expands faster than capital equipment sales, repositioning vendor economics toward recurring income streams.
For Market Incumbents: Shield installed base share by embedding closed-loop temperature control as standard across mid-tier localized cryotherapy platforms, countering portable device erosion from emerging miniaturization specialists. Deepen backward integration into cryogen logistics infrastructure to capture margin currently surrendered to regional gas distributors, particularly in German manufacturing clusters facing EU MDR compliance cost escalation. For New Entrants and Emerging Players: Differentiate on closed-loop precision and reduced tissue damage variance to penetrate India's underpenetrated dermatology clinic networks, where CDSCO import licensing favors quality-certified manufacturing origins. Target standalone unit configurations for Polish and Mexican outpatient pain clinics prioritizing rapid deployment over integrated infrastructure, leveraging distributor partnerships with group purchasing organizations to bypass direct hospital procurement complexity. For Investors and Strategic Acquirers: Capital is best deployed toward German precision engineering houses with decades of thermal therapy heritage and established ISO 13485 quality management frameworks, positioned to navigate EU MDR clinical evidence rebuilds. Watch FDA breakthrough designation award velocity as inflection indicator for interventional radiology capital deployment cycles and cryoablation equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Cryogen Platform Development | Reduces tissue damage variance for dermatology practices adopting standardized lesion protocols. |
| EU MDR Clinical Evidence Rebuild | Delays CE mark renewals for mid-tier competitors while German notified bodies prioritize cryoablation reviews. |
| Service Contract Unbundling | Separates equipment maintenance from consumable supply, responding to French and Japanese hospital procurement demands. |
| India Outpatient Network Penetration | Positions localized cryosurgery units for first-mover advantage in CDSCO-regulated import channels. |
| Wellness Channel Integration | Captures recurring revenue through spa and recovery center membership models outside reimbursement constraints. |
Research Methodology
A standing panel of interventional radiologists, hospital biomedical engineers, dermatology practice administrators, and group purchasing organization contract managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database extracts. Primary fieldwork with German thermal therapy equipment manufacturers and US academic medical center supply chain directors combined with customs trade data and ISO 13485 certification registries. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys across oncology, sports medicine, and aesthetic verticals.
Consistency checks validated volume and value outputs against external benchmarks including medical device trade associations and precision manufacturing export statistics across the projection horizon. Segmentation modeling incorporated product type, application, end user facility, and deployment configuration dimensions with regional regulatory cluster differentiation. CAGRs derived from equipment replacement cycles, procedure volume growth, and site-of-service migration patterns, with specific inputs from cryogen logistics infrastructure expansion and interventional radiologist fellowship pipeline capacity.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough pathway momentum or liquid nitrogen supply stability would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code consolidation and EU MDR review backlog resolution. Regulatory delay, cryogen price volatility, or radiofrequency ablation technological leapfrogging could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Blood Irradiator Device Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Hip Kits Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Adult Water Flosser Market