
 Chronic Spontaneous Urticaria Market | 2026-2036
Chronic Spontaneous Urticaria Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Spontaneous Urticaria Market Analysis
Project finance for late-stage biologics development is fragmenting competitive access, as venture-backed platforms and royalty-backed structures now let mid-cap developers retain program control without full balance-sheet commitment. Novartis leverages its established immunology infrastructure to sustain commercial scale across multiple biologic indications. Sanofi anchors its position through deep primary care reach and formulary relationships that extend into specialist networks.
Chronic spontaneous urticaria denotes a persistent inflammatory skin condition characterized by recurrent wheals and angioedema lasting six weeks or more without identifiable trigger, driven by mast cell activation and IgE-mediated or autoimmune pathways; its primary purpose in commercial terms is to define a reimbursable patient population for targeted immunomodulatory therapy. Biologics command the dominant margin pool as omalizumab and next-generation monoclonals displace chronic corticosteroid dependence, while subcutaneous delivery modes are gaining fastest as self-administration protocols reduce infusion center burden. Oral antihistamines remain the volume backbone but face generic compression that limits innovation returns.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines for biologics addressing uncontrolled disease, while the EU AI Act and GDPR impose algorithmic transparency requirements on companion diagnostic tools that stratify treatment response. Japan's PMDA Sakigake designation adds a third regulatory lever for developers prioritizing Asian market entry. Stakeholders must monitor how payer evidence requirements for sustained response evolve against emerging IL-5 and BTK inhibitor data packages.
Market Dynamics
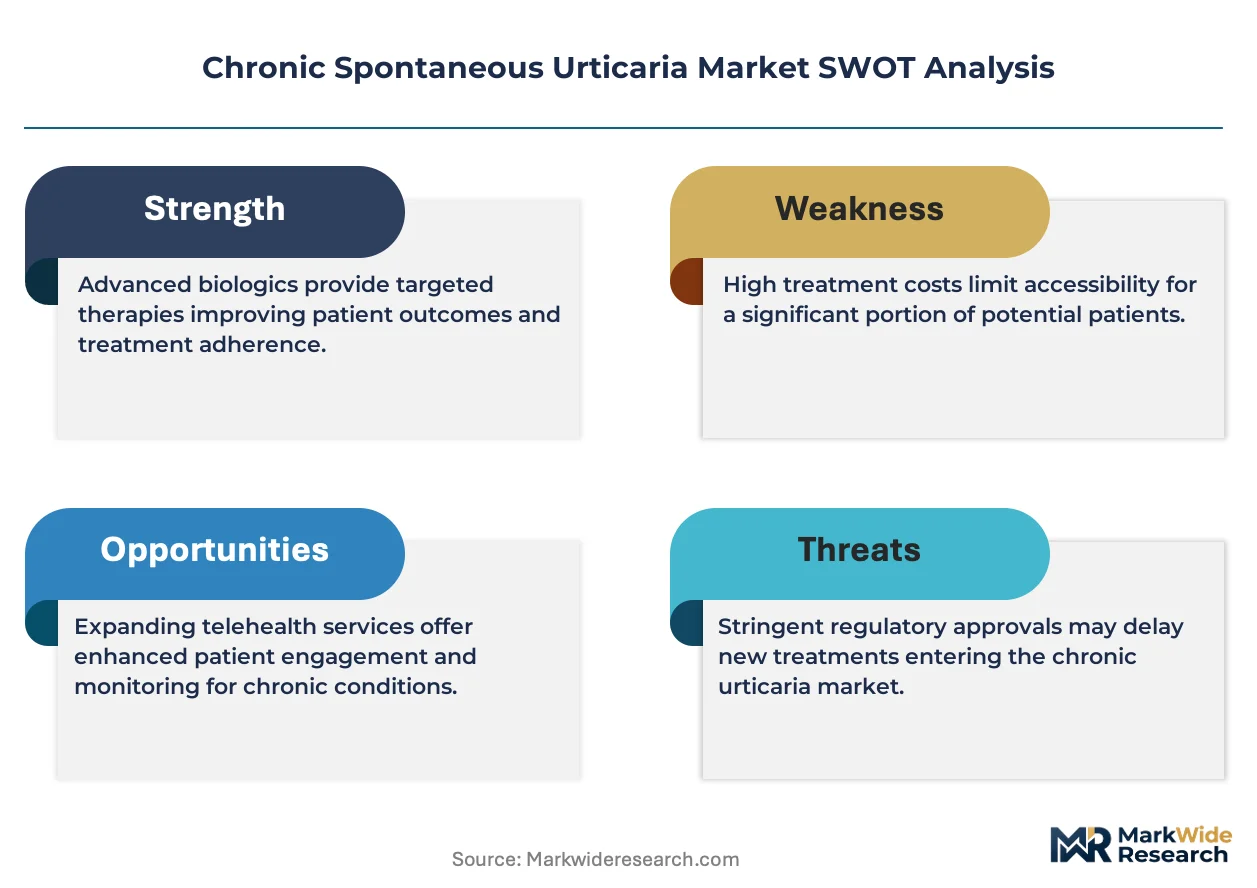
FDA accelerated approval and EMA conditional marketing authorization frameworks compress biologic development timelines, while reimbursement hierarchies for IL-5 inhibitors and BTK modulators recast competitive positioning across specialty dermatology networks.
Growth Catalysts
- EMA Conditional Marketing Authorization:European developers gain compressed timelines for biologics targeting refractory populations, accelerating commercial entry for mast cell-targeted therapies.
- Specialty Dermatology Clinic Expansion:Dedicated urticaria centers in the United States and Germany build biologic prescribing infrastructure that channels refractory patients toward immunomodulatory protocols.
- Subcutaneous Self-Administration:Injection device innovation reduces infusion center dependency, expanding addressable populations beyond urban tertiary care catchments.
Market Restraints
- Plasma-Derived IgG Supply Concentration:Fractionation capacity constraints in North American and European collection networks limit upstream material security for Fc-fusion biologics.
- Japan PMDA Sakigake Data Requirements:Bridging study mandates for Asian ethnicity subsets extend registration timelines by 18-24 months versus Western markets.
- Chronic Corticosteroid Substitution:Generic prednisone and methylprednisolone retain formulary preference in cost-constrained payer environments despite inferior long-term safety profiles.
Strategic Opportunities
- Brazil ANVISA Fast-Track:Latin America's largest reimbursed market offers accelerated review for biologics with prior FDA or EMA approval, enabling mid-cap developers to establish regional manufacturing partnerships.
- Companion Diagnostic Stratification:Basophil activation test integration with IL-5 inhibitor prescribing protocols creates service-based revenue streams for laboratory networks.
- Telemedicine Protocol Integration:Remote monitoring platforms for wheal severity scoring enable direct-to-patient distribution models that bypass traditional specialty pharmacy intermediaries.
Industry Challenges
- Biologic Manufacturing Talent Scarcity:Cell culture and aseptic fill-finish expertise concentrates at established CDMOs, constraining mid-cap developers seeking in-house production capabilities.
- Real-World Evidence Collection Infrastructure:Payer demands for sustained response documentation require prospective registry investment that strains post-marketing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Spontaneous Urticaria Market |
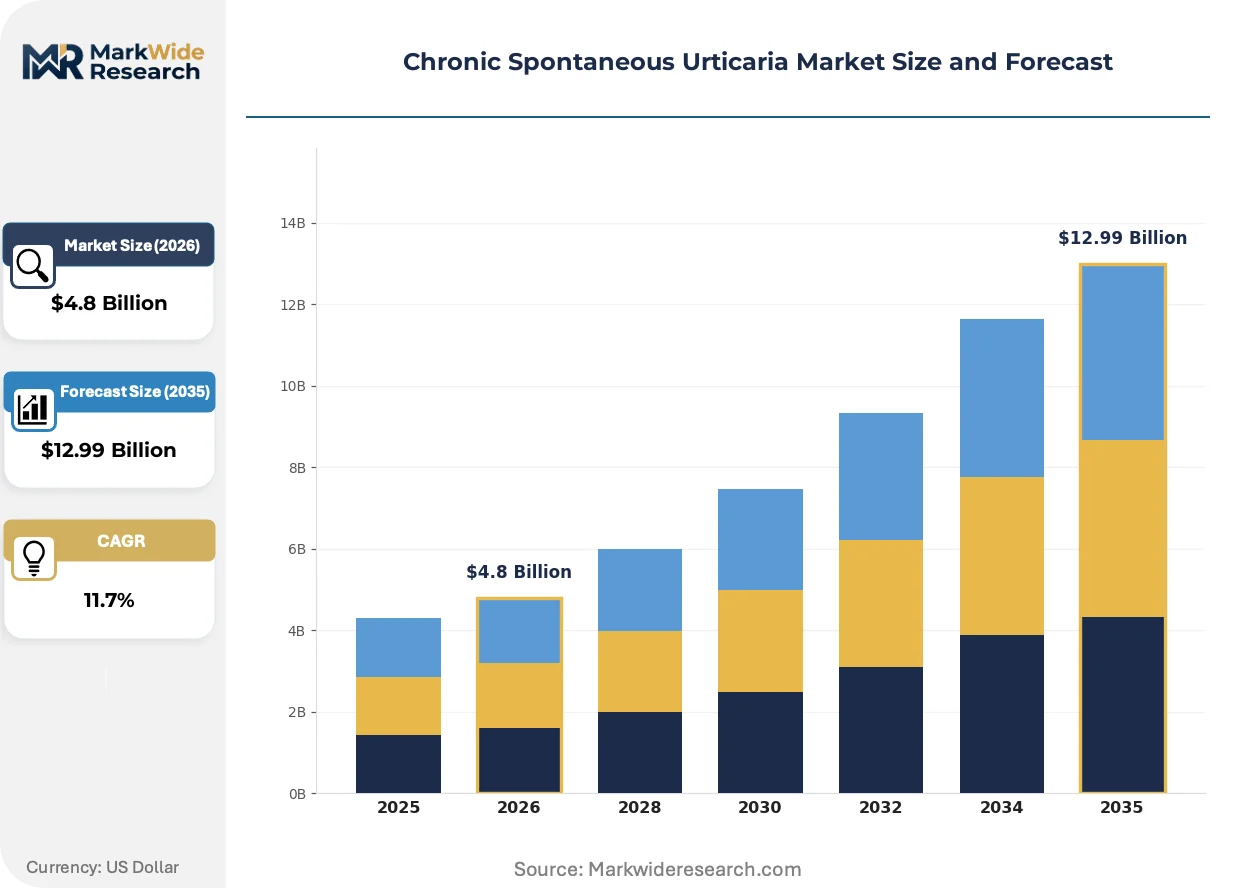
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Biologics, Immunosuppressants Delivery Mode: Oral, Injectable, Topical, Subcutaneous Therapy Area: Dermatology, Immunology, Allergy, General Medicine End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Celldex Therapeutics, GlaxoSmithKline, Novartis, Pfizer, AstraZeneca, Sanofi, Genentech (Roche Group), Merck & Co., Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Spontaneous Urticaria Market Emerging Trajectories
Next-generation mast cell signaling inhibitors and digital therapeutic protocols are compressing treatment response measurement cycles while reshaping how specialty clinics allocate biologic inventory.
Bruton's tyrosine kinase (BTK) inhibitors targeting FcεRI-mediated mast cell activation are rendering obsolete the six-month corticosteroid taper protocols that previously defined refractory patient management. Early-adopter dermatology centers in Germany and the United States are integrating BTK modulators into step-care algorithms ahead of full label expansion. The structural consequence is a contraction in chronic steroid dispensing volumes that reallocates pharmacy benefit budgets toward biologic tiers.
The EU AI Act's risk-classification framework for clinical decision-support algorithms imposes documentation burdens on machine-learning tools that stratify anti-IgE response probability. Developers must now maintain algorithmic audit trails that satisfy notified body scrutiny alongside traditional clinical data packages. Dermatology networks deploying predictive analytics for omalizumab candidacy face the steepest compliance adaptation costs.
Patient-reported outcome (PRO) integration into reimbursement contracts is compressing traditional episode-based payment structures for chronic urticaria management. United States payers are piloting outcomes-adjusted contracts that tie biologic coverage to validated urticaria activity score thresholds, displacing prior authorization volume caps. This shift is most visible in Medicare Advantage plans and large employer-sponsored benefit designs where specialty pharmacy spend concentration justifies administrative investment.
Chronic Spontaneous Urticaria Market Segmentation
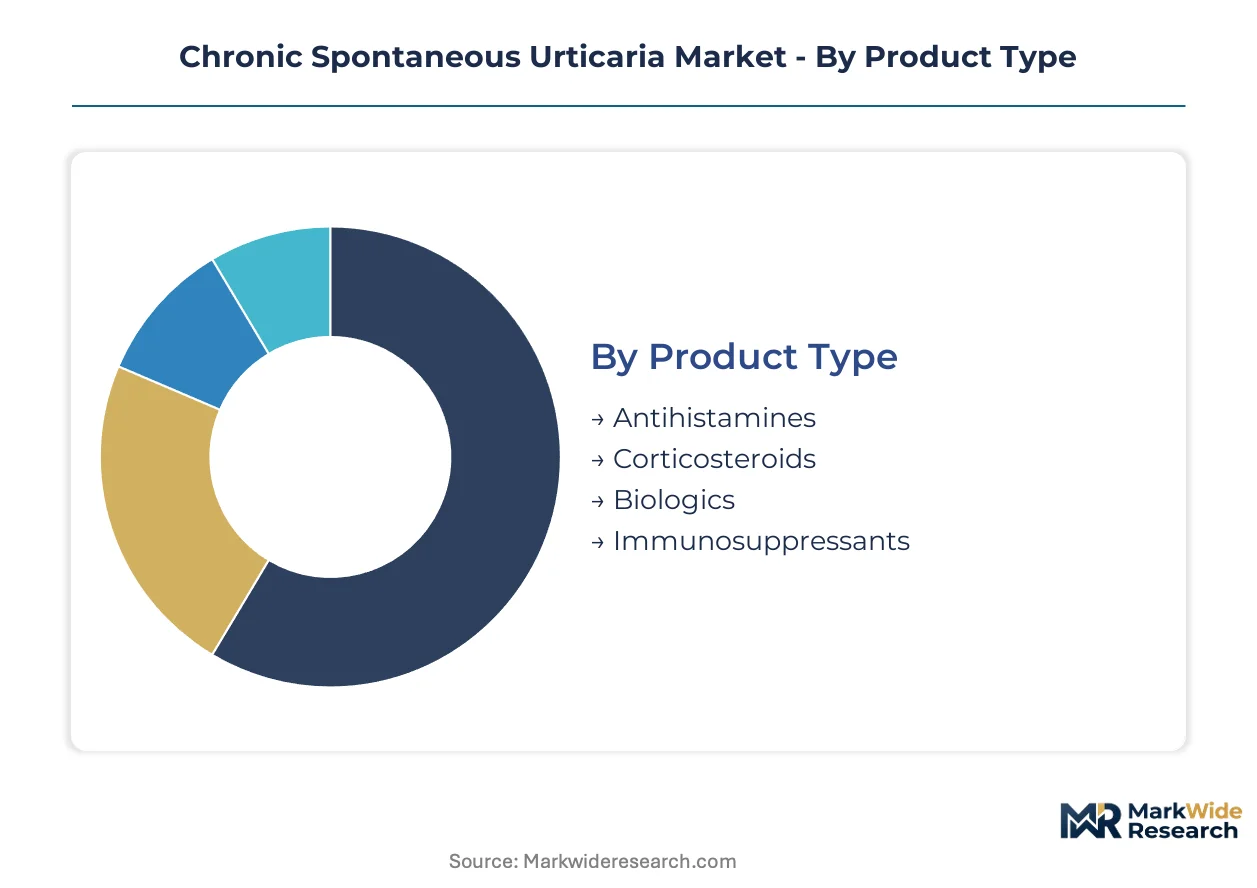
Chronic spontaneous urticaria treatment selection hinges on disease severity stratification, reimbursement tier alignment, and patient self-administration capability. Segmentation reveals how biologics command premium positioning while oral therapies sustain volume foundations across diverse care settings.
Product Type:
Use-case spectrum spans acute symptom suppression through chronic disease modification, with each therapeutic class addressing distinct points in the treatment algorithm.
- Biologics:Monoclonal antibodies targeting IgE or IL-5 pathways deliver sustained urticaria control for refractory patients who fail standard-of-care regimens. Demand concentrates in United States specialty dermatology networks and German university hospitals where prior authorization pathways for omalizumab and emerging alternatives have matured.
- Antihistamines:Second-generation H1 antagonists constitute first-line maintenance therapy with established safety profiles supporting long-term daily administration. Volume concentrates in primary care prescribing across Japan and United States retail pharmacy channels, though generic price erosion constrains manufacturer margins.
- Corticosteroids:Short-course systemic steroids bridge acute flares in step-care protocols.
- Immunosuppressants:Cyclosporine and methotrexate reserve roles address biologic-ineligible refractory cases.
Established volume favors antihistamines; emerging adoption favors biologics.
Delivery Mode:
Cost tier differentiation separates hospital-administered infusion from self-managed subcutaneous protocols.
- Subcutaneous:Prefilled syringe and autoinjector formats enable home administration of biologics, reducing infusion center capacity constraints and expanding addressable geography beyond urban tertiary centers. United States and German payers increasingly mandate self-administration for maintenance dosing to lower site-of-care costs.
- Oral:Tablet and liquid formulations dominate daily maintenance prescribing with lowest per-dose cost and broadest pharmacy distribution. Japan's aging patient population drives sustained demand for oral convenience, while pediatric formulations expand addressable demographics.
- Injectable:Intravenous biologic induction requires specialized administration settings.
- Topical:Limited efficacy for systemic urticaria restricts use to adjunctive symptomatic relief.
Patient preference is shifting toward subcutaneous; institutional procurement still favors oral.
Therapy Area:
Application concentration determines prescriber specialty and formulary placement depth.
- Dermatology:Specialty clinics in the United States and Germany anchor biologic prescribing infrastructure, with dedicated urticaria centers building referral networks that channel refractory patients toward immunomodulatory protocols. Dermatologists command highest per-patient revenue for advanced therapies.
- Immunology:Academic medical centers integrate urticaria within broader mast cell disorder portfolios, leveraging shared biologic procurement across indications. United States immunology departments increasingly co-manage severe cases with dermatology.
- Allergy:IgE-mediated disease expertise supports diagnostic workup and antihistamine optimization.
- General Medicine:Primary care gatekeeping functions concentrate in Japan and cost-constrained European systems.
Margin concentration favors dermatology; volume access favors general medicine.
End User:
Customer type dictates procurement sophistication and inventory management requirements.
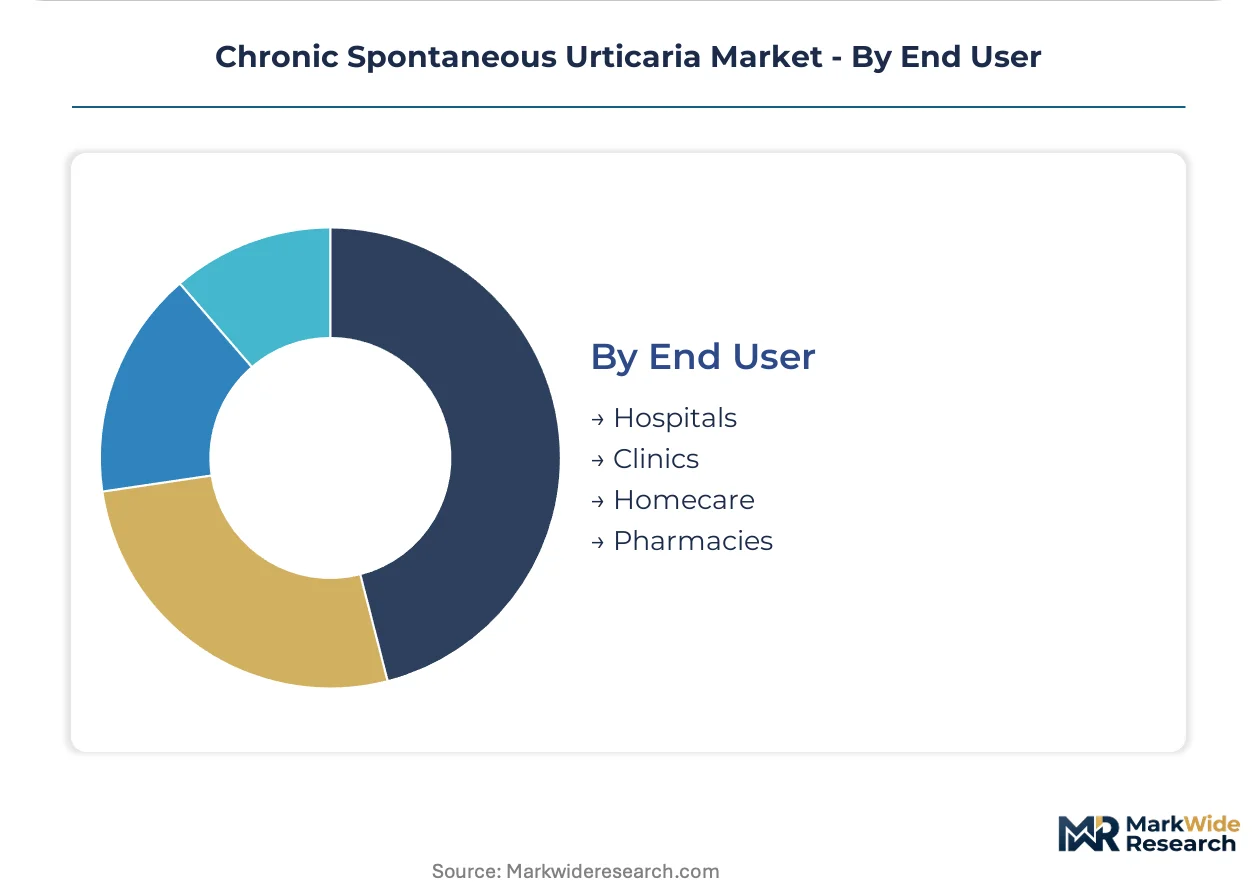
- Clinics:Specialty dermatology and allergy practices in the United States and Germany build biologic dispensing infrastructure with cold-chain capabilities and prior authorization expertise. These settings capture highest-value prescribing for refractory patient populations.
- Hospitals:Tertiary centers manage acute angioedema presentations and biologic induction protocols, with formulary committees exercising centralized control over high-cost immunomodulatory access.
- Homecare:Subcutaneous self-administration expansion is redirecting maintenance therapy from institutional to direct-to-patient distribution.
- Pharmacies:Retail and specialty pharmacy networks handle oral antihistamine volume and biologic fulfillment.
Revenue per patient climbs from pharmacy to clinic to hospital; homecare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic import dependency shapes market access patterns, with concentrated manufacturing in North American and European fractionation networks feeding specialist clinic demand across high-reimbursement territories. Export flows of subcutaneous autoinjector formats now dominate cross-border trade in maintenance therapies.
United States
Specialty dermatology networks in Boston and New York Metro anchor biologic prescribing infrastructure, with Medicare Advantage plans piloting outcomes-adjusted contracts for omalizumab. FDA accelerated approval pathways compress development timelines for mast cell-targeted therapies entering refractory patient protocols.
Germany
University hospitals in Bavaria and North Rhine-Westphalia build dedicated urticaria centers channeling patients toward immunomodulatory step-care. EMA conditional marketing authorization frameworks enable earlier commercial entry for IL-5 inhibitors, while statutory health insurance funds mandate self-administration for maintenance dosing to reduce site-of-care costs.
Japan
Aging demographics in Kanto and Kansai regions sustain oral antihistamine volume, though PMDA Sakigake designation accelerates biologic review for developers prioritizing Asian market entry. Bridging study requirements for ethnicity subsets extend registration timelines by 18-24 months versus Western markets.
Brazil
ANVISA fast-track pathways enable accelerated review for biologics with prior FDA or EMA approval, positioning São Paulo and Rio de Janeiro as regional manufacturing partnership hubs. Reimbursement expansion in private health plans drives adoption of subcutaneous protocols beyond tertiary hospital catchments.
Chronic Spontaneous Urticaria Market Vendor Landscape
On the supply side, the industry is consolidating around established immunology infrastructures that sustain commercial scale across multiple biologic indications. Large-cap pharmaceutical groups anchor market structure through deep formulary relationships and specialist network penetration, while mid-cap developers leverage venture-backed platforms and royalty structures to retain program control. Two strategic archetypes dominate: diversified immunology majors with cross-indication procurement leverage, and precision biologic specialists targeting mast cell signaling pathways. Competitive moves center on M&A for pipeline augmentation and capacity expansion into aseptic fill-finish capabilities.
Among Swiss-based diversified majors, Novartis occupies a position exemplifying immunology infrastructure scale, while Sanofi represents the primary care-to-specialist network extension model. Genentech anchors the precision biologic archetype within the Roche Group structure. These three entities collectively illustrate how commercial reach, manufacturing depth, and signaling pathway specialization stratify competitive positioning in refractory patient segments.
| Leading Market Players |
|---|
| Celldex Therapeutics |
| GlaxoSmithKline |
| Novartis |
| Pfizer |
| AstraZeneca |
| Sanofi |
| Genentech (Roche Group) |
| Merck & Co. |
| Regeneron Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Plasma-derived IgG supply concentration in North American and European fractionation networks determines both biologic pricing tier spreads and supply chain resilience architecture for mast cell-targeted therapies. Developers face compressed margin pools when fractionation capacity constraints trigger input cost volatility, while payers enforce site-of-care cost controls that reshape downstream distribution economics.
Pricing Analysis
Specialty pharmacy benefit managers anchor three-tier pricing structure across premium, standard, and economy levels for chronic spontaneous urticaria therapies. Price differentiation rests on administration route complexity and prior authorization burden, with subcutaneous autoinjector formats commanding premium positioning against infusion-center alternatives. Cost compression in oral antihistamine tiers intensifies because generic erosion eliminates branded pricing power. Retail pharmacy channels exhibit highest price sensitivity; specialty dermatology clinics demonstrate lowest sensitivity due to outcomes-based contracting acceptance.
Supply Chain Analysis
Tariff exposure between United States and Chinese manufacturing zones for injection device components dominates supply chain risk calculus for biologic developers. Cell culture capacity concentrates in United States, Switzerland, and Ireland, while aseptic fill-finish expertise clusters at established contract manufacturing organizations in Germany and Singapore. Raw material dependencies include recombinant protein feedstocks, single-use bioreactor systems, and pharmaceutical-grade silicone for syringe plungers. Single-source vulnerability for Fc-fusion protein production creates concentration risk. Distribution runs through cold-chain specialty pharmacy networks with patient hub services for prior authorization support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic spontaneous urticaria market sits at a post-patent cliff cyclical recovery phase, with omalizumab biosimilar entry and next-generation IL-5 inhibitor launches driving portfolio rebalancing among immunology majors.
For Market Incumbents: Build formulary lock-in moats through real-world evidence registry investments that satisfy payer demands for sustained response documentation. Novartis and Sanofi should deepen backward integration into aseptic fill-finish capabilities to reduce CDMO dependency for mast cell-targeted biologics. Threat from BTK inhibitor substitution requires defensive indication expansion into atopic dermatitis and other mast cell disorders to retain prescriber share.
For New Entrants and Emerging Players: Mid-market biologic candidates with subcutaneous administration profiles in Brazil and Mexico represent the most penetrable entry point for developers lacking United States formulary relationships. ANVISA fast-track pathways enable accelerated commercial entry for therapies with prior FDA or EMA approval. Go-to-market angle should emphasize direct-to-patient distribution partnerships that bypass entrenched specialty pharmacy intermediaries.
For Investors and Strategic Acquirers: The market sits at a pipeline transition phase that favors precision biologic specialists with mast cell signaling expertise over diversified immunology platforms. Long-term viability over the next decade hinges on successful BTK inhibitor label expansion and companion diagnostic integration. Acquisition target archetype: mid-cap developers with phase-ready IL-5 or BTK assets and existing Asian bridging study data. Signal to watch is Medicare Advantage outcomes-based contract adoption velocity as inflection indicator for reimbursement model durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses timelines for mast cell-targeted biologics entering refractory protocols. |
| Manufacturing Scale-Up | Aseptic fill-finish capacity expansion in Singapore reduces single-source dependency for subcutaneous autoinjector supply. |
| Clinical Trial Advancement | Phase III BTK inhibitor programs in Germany and United States reshape step-care algorithm positioning. |
| Reimbursement Strategy | Outcomes-adjusted contracts with Medicare Advantage plans validate urticaria activity score thresholds for coverage. |
| Pipeline Diversification | Mast cell signaling asset acquisition extends indication reach into atopic dermatitis and eosinophilic esophagitis. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic administrators, specialty pharmacy procurement directors, payer formulary managers, biologic manufacturing executives, and regulatory affairs leads at immunology-focused developers. Secondary validation drew from FDA biologics license application filings, EMA conditional marketing authorization decisions, ClinicalTrials.gov protocol registries, and statutory health insurance reimbursement databases in Germany and Japan. Bottom-up patient flow modeling and top-down pharmaceutical spend analysis were triangulated to anchor volume estimates.
Calibration against historical biologic launch curves and analog indication penetration patterns informed trajectory assumptions across the analysis window. Segmentation dimensions modeled include product class, delivery mode, prescriber specialty, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting adjusted for patent expiry and biosimilar entry effects. Forecast inputs incorporated bridging study timeline differentials for Asian markets and site-of-care cost shift assumptions for self-administration adoption.
Stress conditions across fractionation capacity constraints, payer prior authorization tightening, and BTK inhibitor substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement hierarchy stability and biologic manufacturing talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Scar Treatment Oils Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Australia Skin Treatment Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Impetigo Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Global Dermatology Cro Market
Dermatology
Acne Vulgaris Market
Dermatology
Folliculitis Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Global Rosacea Market