
 Global Dermatological Therapeutics Market | 2026-2036
Global Dermatological Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatological Therapeutics Market Foresight
Biologics-grade efficacy standards is redrawing competitive boundaries in dermatological therapeutics. AbbVie Inc. leverages its immunology platform to sustain leadership in psoriasis biologics. Galderma S.A. anchors the premium topical segment through dermatologist-channel control. Sun Pharmaceutical Industries Ltd. competes on cost-engineered generics across emerging markets.
Dermatological therapeutics encompasses pharmaceutical and device-based interventions formulated to treat inflammatory, infectious, neoplastic, and autoimmune conditions of the integumentary system, with biologics typically requiring cold-chain distribution at 2-8°C and topical formulations demanding specific viscosity profiles for stratum corneum penetration. Injectable biologics command the highest margin pools due to manufacturing complexity and patent protection, while topical creams retain volume leadership in eczema and fungal infection management. Phototherapy devices represent the fastest-expanding delivery mode segment, driven by home-use approvals and LED wavelength optimization.
The FDA maintains stringent BLA requirements for biologics targeting IL-17 and IL-23 pathways, while the EMA's MDR framework tightens clinical evidence standards for phototherapy devices, and Japan's PMDA accelerates sakigake-designated dermatology drugs through priority review. These regulatory architectures shape R&D allocation, manufacturing location decisions, and market access timelines across development portfolios. Stakeholders must monitor evolving biosimilar interchangeability designations and real-world evidence requirements as determinants of portfolio defensibility.
Market Dynamics
Biologics manufacturing complexity and cold-chain infrastructure requirements are concentrating competitive advantage among firms with integrated immunology platforms and distribution networks capable of maintaining 2-8°C integrity across extended supply chains.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy designation for IL-23 inhibitors compresses clinical development timelines, enabling faster commercialization of novel autoimmune therapeutics.
- Phototherapy Device Home-Use Expansion:LED wavelength optimization and portable device approvals shift treatment delivery from clinical settings to patient homes, expanding addressable patient populations.
- Japan's Sakigake Priority Review:The PMDA's expedited designation for dermatology drugs reduces regulatory review periods, attracting R&D investment toward Japan's reimbursement-protected market.
Market Restraints
- Biologics Cold-Chain Cost Structure:Continuous 2-8°C temperature monitoring and specialized logistics inflate distribution costs by 15-25% versus small-molecule pharmaceuticals.
- EMA MDR Clinical Evidence Requirements:The EU's Medical Device Regulation tightens phototherapy device approval standards, extending certification timelines and increasing clinical trial burdens.
- Biosimilar Substitution Pressure:Interchangeability designations for adalimumab and infliximab biosimilars compress originator pricing power in mature markets.
Strategic Opportunities
- India's Biosimilar Manufacturing Base:Cost-engineered production capabilities and CDSCO regulatory alignment position Indian facilities as global supply hubs for emerging market access.
- Real-World Evidence Integration:Post-market surveillance data requirements from the FDA and EMA create competitive differentiation for firms with robust pharmacovigilance infrastructure.
- Topical Nanoparticle Delivery Convergence:Lipid-based penetration enhancers combined with microfluidic manufacturing enable stratum corneum targeting previously achievable only through systemic administration.
Industry Challenges
- Specialized Biologics Manufacturing Talent Scarcity:Cell culture scale-up expertise and aseptic processing capabilities concentrate among limited contract development and manufacturing organizations.
- Multi-Jurisdiction BLA Coordination:Divergent FDA, EMA, and PMDA evidentiary standards for IL-17 and IL-23 pathway inhibitors fragment regulatory submission strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatological Therapeutics Market |
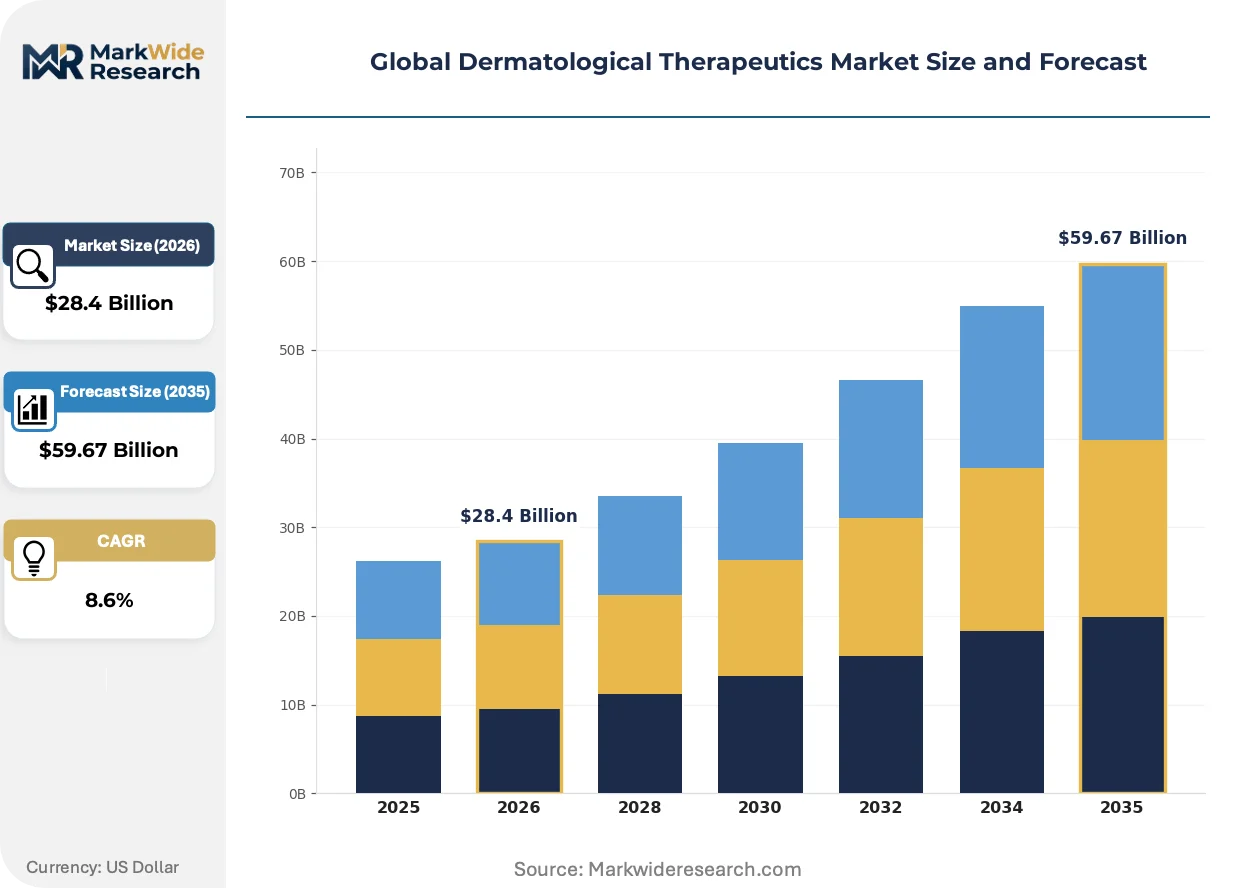
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Medications, Injectable Biologics, Phototherapy Devices, Dermal Gels Therapy Area: Psoriasis, Acne Vulgaris, Eczema, Rosacea, Vitiligo, Fungal Infections End User: Dermatology Clinics, Cosmetic Centers, Research Laboratories, Outpatient Care Centers Delivery Mode: Topical Application, Systemic Administration, Laser Treatment, Cryotherapy, Injection |
| Companies Covered | Galderma S.A., Novartis AG, AbbVie Inc., GSK plc, Eli Lilly and Company, Johnson & Johnson, Sun Pharmaceutical Industries Ltd., LEO Pharma, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatological Therapeutics Market Shifts & Advancements
Novel biologic modalities and digital therapeutics integration are compressing traditional treatment paradigms while expanding the addressable scope of dermatological intervention beyond pharmaceutical monotherapy.
IL-23 pathway inhibitors are displacing TNF-alpha blockers as first-line systemic therapy for moderate-to-severe psoriasis. Dermatology clinics in the United States and Germany are transitioning patient cohorts to risankizumab and guselkumab within 18-24 month switching cycles. This displacement is compressing TNF inhibitor market share in autoimmune dermatology while elevating efficacy benchmarks for pipeline candidates.
The EMA's MDR framework for phototherapy devices tightens clinical evidence requirements for home-use LED systems. Manufacturers must now demonstrate equivalence to clinical-grade devices through randomized controlled trials. German and French notified bodies are enforcing stricter biocompatibility testing, delaying market entry for Asian-origin device exporters by 12-18 months.
Patient self-administration preferences are fragmenting traditional clinic-based phototherapy delivery. Home-use device prescriptions through dermatologist channels are replacing hospital-based treatment regimens in the United States and Japan. This behavioral shift concentrates demand among device manufacturers with direct-to-clinic distribution capabilities and remote monitoring software integration.
Global Dermatological Therapeutics Market Segmentation
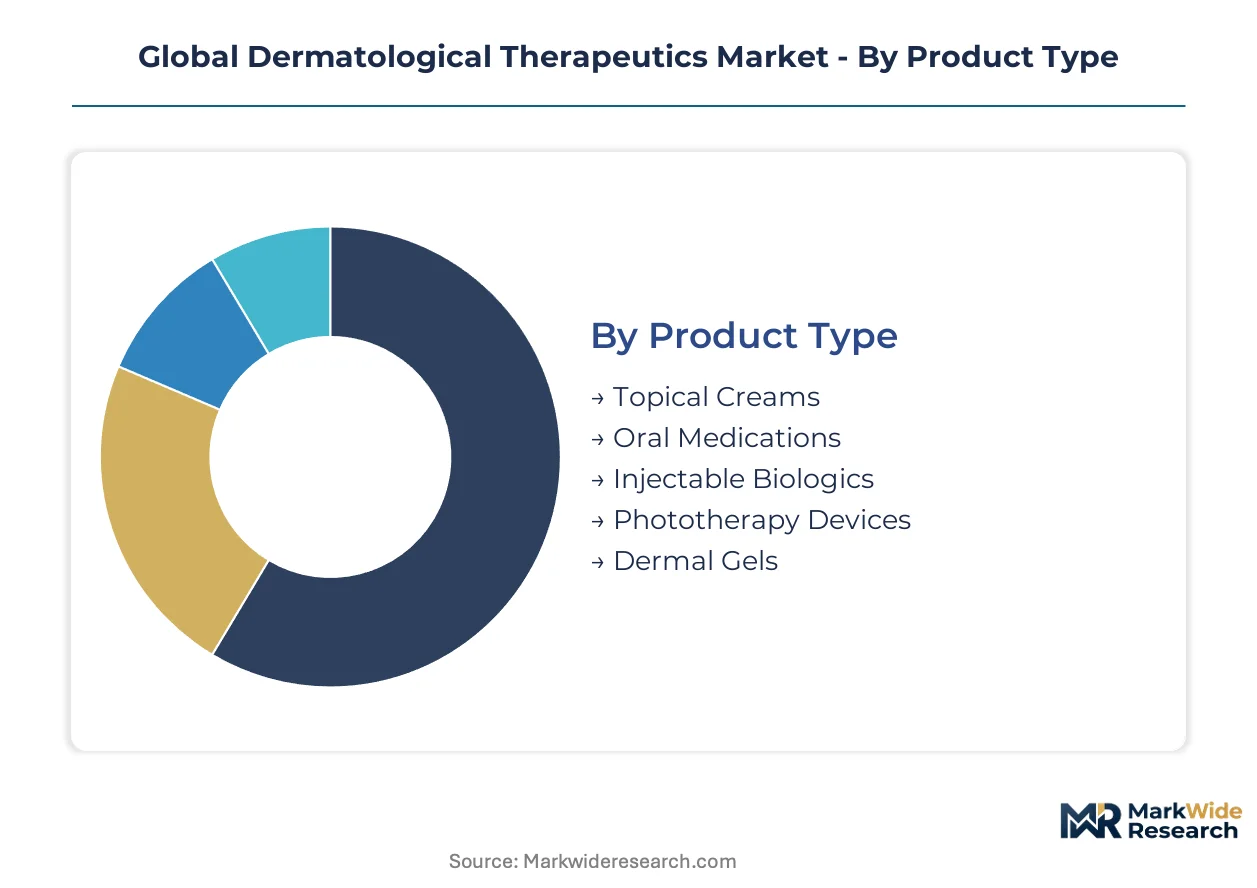
Segmentation in dermatological therapeutics maps how formulation complexity, disease severity, and care setting intersect to determine channel economics. Each dimension reveals distinct margin structures and regulatory pathways that shape portfolio allocation decisions.
Product Type:
Channel distribution varies sharply by formulation—topicals flow through retail pharmacy and direct clinic dispensing, while biologics require specialty pharmacy networks with cold-chain integrity.
- Topical Creams:Oil-in-water emulsions with 500-5000 cP viscosity optimize stratum corneum penetration for corticosteroid and calcineurin inhibitor delivery. Demand clusters in Germany and Japan where dermatologist-directed prescribing dominates eczema and psoriasis maintenance protocols.
- Injectable Biologics:Monoclonal antibodies targeting IL-17 and IL-23 pathways require aseptic fill-finish and 2-8°C distribution infrastructure. The United States absorbs the majority of volume through specialty pharmacy channels that manage prior authorization and patient adherence programs.
- Oral Medications:Small-molecule immunomodulators and retinoids serve moderate disease severity through standard retail distribution.
- Phototherapy Devices:LED and excimer laser systems shift between clinic-based and home-use delivery depending on regulatory clearance.
- Dermal Gels:Hydrogel and organogel vehicles enable active ingredient suspension for acne and rosacea applications.
Injectable biologics dominate installed base value. Phototherapy devices are where expansion concentrates.
Therapy Area:
Cost tier stratification separates chronic autoimmune conditions with lifetime therapy from acute infectious presentations with episodic treatment patterns.
- Psoriasis:Chronic plaque psoriasis drives systemic therapy escalation from topicals through phototherapy to biologics based on body surface area involvement. The United States and Germany concentrate biologic penetration where IL-23 inhibitors displace earlier TNF-alpha blockers.
- Acne Vulgaris:Retinoid-benzoyl peroxide combinations and hormonal therapies span OTC through prescription tiers. Emerging markets in India and Brazil generate volume through cost-engineered generic isotretinoin and clindamycin formulations.
- Eczema:Atopic dermatitis management combines emollient maintenance with intermittent corticosteroid flares.
- Rosacea:Chronic facial erythema and papulopustular variants sustain topical metronidazole and azelaic acid demand.
- Vitiligo:Depigmentation disorders utilize topical calcineurin inhibitors and targeted phototherapy.
- Fungal Infections:Dermatophyte and candidal presentations drive azole and allylamine topical consumption.
Psoriasis commands premium pricing tiers. Acne vulgaris generates the steepest volume expansion trajectory.
End User:
Customer type determines reimbursement pathway complexity and device capital expenditure authorization.
- Dermatology Clinics:Physician-owned and hospital-affiliated practices combine diagnostic services with in-office procedure revenue. Germany's Kassenärztliche Vereinigung reimbursement structures and Japan's clinic-based biologic administration sustain this channel's centrality.
- Cosmetic Centers:Aesthetic dermatology and medical spa settings drive photorejuvenation and laser resurfacing device placement. The United States absorbs premium device shipments through cash-pay aesthetic procedures outside insurance networks.
- Research Laboratories:Academic medical centers and contract research organizations conduct Phase II-III dermatology trials.
- Outpatient Care Centers:Ambulatory infusion sites enable biologic administration for patients lacking home injection capability.
Dermatology clinics anchor prescription volume. Cosmetic centers are gaining share fastest in device segments.
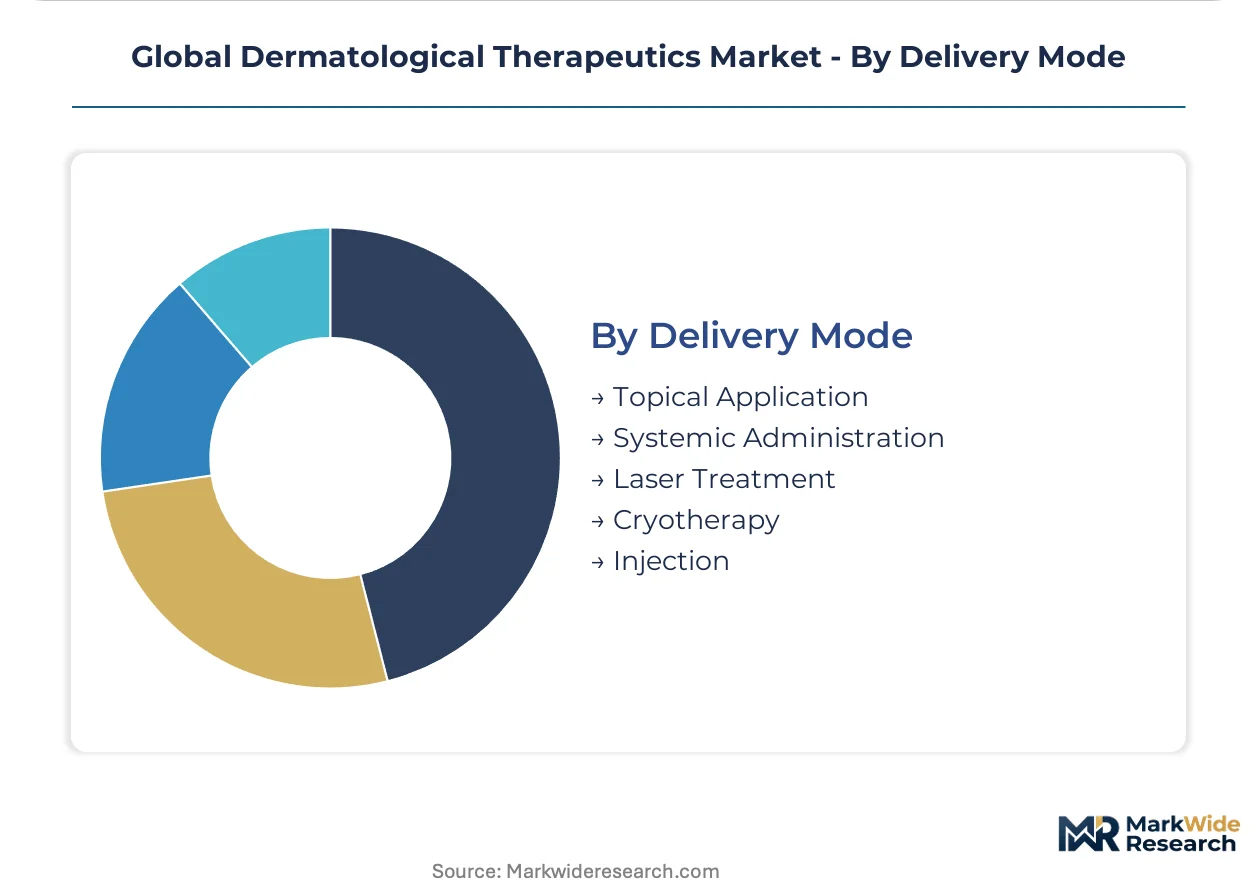
Delivery Mode:
Application method governs manufacturing scale economies and patient adherence monitoring infrastructure.
- Topical Application:Semisolid and liquid formulations demand specific rheological properties for skin retention. India's CDSCO-regulated manufacturers supply cost-optimized excipient bases for emerging market access.
- Injection:Subcutaneous and intravenous biologic delivery requires pen device or infusion infrastructure. The United States concentrates self-injection training programs that reduce clinic visit burden.
- Systemic Administration:Oral bioavailability challenges shape small-molecule development pipelines.
- Laser Treatment:Coherent light delivery for vascular and pigmented lesions requires calibrated wavelength selection.
- Cryotherapy:Liquid nitrogen application for benign and pre-malignant lesions sustains point-of-care procedural revenue.
Topical application retains volume leadership. Injection modalities concentrate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports biologics-grade active pharmaceutical ingredients to the United States and Japan, anchoring transatlantic and transpacific trade corridors in dermatological therapeutics. Cold-chain distribution networks from Frankfurt and Munich sustain 2-8°C integrity across intercontinental routes. Regulatory harmonization efforts between the EMA and FDA accelerate cross-border product registrations.
United States
Specialty pharmacy networks and prior authorization infrastructure concentrate biologic dispensing in the United States, with IL-23 inhibitors displacing earlier TNF-alpha blockers in psoriasis protocols. The FDA's breakthrough therapy designation compresses clinical development timelines for novel immunomodulators. Boston and San Francisco biotech clusters drive pipeline innovation through academic-industry partnerships.
Germany
Dermatologist-directed prescribing and Kassenärztliche Vereinigung reimbursement structures sustain premium topical demand in Germany, particularly for eczema maintenance protocols. The EMA's centralized marketing authorization procedure enables simultaneous EU-wide access for novel biologics. Frankfurt anchors continental distribution networks with integrated cold-chain logistics serving Central and Eastern European markets.
Japan
Clinic-based biologic administration and aging demographics sustain systemic therapy escalation in Japan's psoriasis and atopic dermatitis segments. The PMDA's sakigake priority review designation reduces regulatory review periods for dermatology drugs. Tokyo and Osaka medical centers concentrate real-world evidence generation for post-market surveillance requirements.
India
Cost-engineered generic manufacturing and CDSCO regulatory alignment position India as a supply hub for emerging market access in topical corticosteroids and antifungals. The PLI scheme incentivizes domestic biologics manufacturing capacity expansion. Hyderabad and Ahmedabad pharmaceutical clusters specialize in biosimilar development for export to Africa and Southeast Asia.
Switzerland
Specialty biologics manufacturing and Swissmedic regulatory precision sustain Switzerland's position in high-value dermatological exports. Bilateral recognition agreements with the FDA and EMA streamline multi-jurisdiction approvals. Basel and Zurich host integrated immunology platforms with captive fill-finish capabilities for European and North American markets.
Global Dermatological Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across immunology platform depth and channel control dimensions. The vendor base separates into three tiers: integrated pharmaceutical conglomerates with immunology franchises, dermatology-focused specialists with dermatologist-channel relationships, and cost-engineered generic manufacturers with emerging market penetration. Strategic archetypes include platform diversifiers extending biologic modalities across autoimmune indications, channel capturers controlling point-of-care dispensing, and geography optimizers leveraging regulatory arbitrage for price-tiered access. M&A activity concentrates on biologics manufacturing capabilities and phototherapy device portfolios.
Within the integrated platform tier, AbbVie Inc., Novartis AG, and Eli Lilly and Company exemplify archetypes of immunology-centered diversification. AbbVie Inc. occupies a position representing sustained biologics leadership through pipeline succession strategies. Novartis AG anchors a position exemplifying multi-indication immunology platform deployment. Eli Lilly and Company sits within a tier representing rapid scaling of dermatology-specific indications through accelerated regulatory pathways.
| Leading Market Players |
|---|
| Galderma S.A. |
| Novartis AG |
| AbbVie Inc. |
| GSK plc |
| Eli Lilly and Company |
| Johnson & Johnson |
| Sun Pharmaceutical Industries Ltd. |
| LEO Pharma |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
IL-23 inhibitor substitution for TNF-alpha blockers redraws supply geography toward Swiss and German fill-finish facilities while compressing pricing premiums for legacy biologics. This therapeutic-class displacement simultaneously elevates cold-chain infrastructure costs and concentrates margin capture among integrated immunology platforms with captive manufacturing.
Pricing Analysis
Next-generation IL-23 inhibitors command substantial premiums over prior-generation TNF-alpha blockers, while oral small-molecule immunomodulators undercut both on per-dose economics. Pricing stratifies across premium biologics, standard topicals, and economy generics based on manufacturing complexity and patent status. Cost compression in mature biologics intensifies as adalimumab and infliximab biosimilars erode originator pricing power. Dermatology clinics exhibit lowest price sensitivity for biologics with demonstrated PASI-90 efficacy, while retail pharmacy channels for topical corticosteroids show highest sensitivity to generic substitution.
Supply Chain Analysis
Switzerland and Germany anchor biologics-grade active pharmaceutical ingredient production for North American and Asia-Pacific markets. Switzerland's Swissmedic-regulated facilities draw from specialized cell culture media and single-use bioreactor components. Single-source vulnerability concentrates in aseptic fill-finish capacity controlled by limited contract development organizations. Distribution runs through Frankfurt and Basel cold-chain hubs maintaining 2-8°C integrity across intercontinental routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where immunology platform breadth determines competitive survival, accelerated by the FDA and EMA convergence on real-world evidence standards that favor integrated data infrastructure.
For Market Incumbents: Secure biologics manufacturing talent pools through captive training programs and backward integration into cell culture media supply. Defend against biosimilar substitution by embedding patient adherence monitoring into specialty pharmacy partnerships. Prioritize IL-23 pathway pipeline succession to maintain premium positioning as TNF-alpha blockers commoditize.
For New Entrants and Emerging Players: Japan's sakigake priority review creates accelerated regulatory access for novel dermatology assets. Target home-use phototherapy devices as the most penetrable segment, exploiting EMA MDR compliance gaps among Asian-origin manufacturers. Pursue direct-to-clinic distribution bypassing hospital procurement committees.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology specialists lacking biologics manufacturing scale. Long-term viability favors platforms with immunology franchise breadth spanning multiple autoimmune indications. Watch FDA interchangeability designations for adalimumab biosimilars as the signal for originator pricing collapse timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses IL-23 inhibitor development timelines versus standard BLA review. |
| Manufacturing Scale-Up | Swiss and German fill-finish capacity expansion secures cold-chain integrity for biologics export to Japan. |
| Pipeline Diversification | Topical nanoparticle delivery platforms extend immunology assets into atopic dermatitis without systemic exposure. |
| Licensing Agreement | Indian CDSCO-aligned manufacturers license biosimilar cell lines for emerging market cost-tier access. |
| Strategic Partnership | Phototherapy device manufacturers partner with dermatology software platforms for remote treatment monitoring. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases established baseline market sizing. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span treatment line, dosage form, administration route, and regional regulatory cluster across the analysis window. CAGRs derived from therapeutic-class adoption curves, biosimilar penetration scenarios, and device home-use transition rates. Forecast inputs incorporated real-world evidence requirements and cold-chain infrastructure expansion timelines.
Underlying assumptions cover regulatory pathway stability and reimbursement continuity, with deviation risk concentrated in biosimilar interchangeability designations and EMA MDR enforcement intensity. Recalibration cycles align with material shifts in FDA accelerated approval criteria and PMDA sakigake designation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Radiodermatitis Market
Dermatology
Derma Rollers Market
Dermatology
Global Hirsutism Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Skin Cancer Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Darier Disease Drugs Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermabrasion Market
Dermatology
China Scar Treatment Market
Dermatology
Telogen Effluvium Treatment Market