
 Dental Fittings Market | 2026-2036
Dental Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fittings Market Analysis
Dental service organization consolidation is pivoting procurement authority away from solo practitioners toward centralized buying desks. Straumann Group leverages its vertically integrated implant-to-abutment portfolio to capture recurring revenue from these aggregated buyers. Glidewell anchors North American laboratory throughput with its in-house milling capacity, while Osstem Implant competes on cost-engineered implant systems tailored to emerging clinic chains.
Dental fittings are custom-fabricated prosthetic components—crowns, bridges, dentures, and implants—designed to restore masticatory function and aesthetic alignment within a patient's existing dentition, typically manufactured from biocompatible ceramics, titanium alloys, or hybrid resins to withstand intraoral forces exceeding 150 MPa. Implant segments draw the deepest margin pools due to surgical placement requirements and long-term maintenance protocols, whereas CAD/CAM technology displaces traditional milling as laboratories prioritize same-day turnaround and digital impression accuracy. Ceramic materials command premium positioning in anterior restorations where translucency matching becomes critical.
FDA 510(k) premarket notifications govern Class II dental device clearance, while ISO 13485 quality management standards shape supplier eligibility for original equipment partnerships. The EU Medical Device Regulation imposes clinical evidence thresholds on implantable fittings, tightening market access for non-European manufacturers. Stakeholders must monitor how regulatory divergence between FDA streamlined pathways and EMA clinical evaluation requirements fragments global product registration strategies.
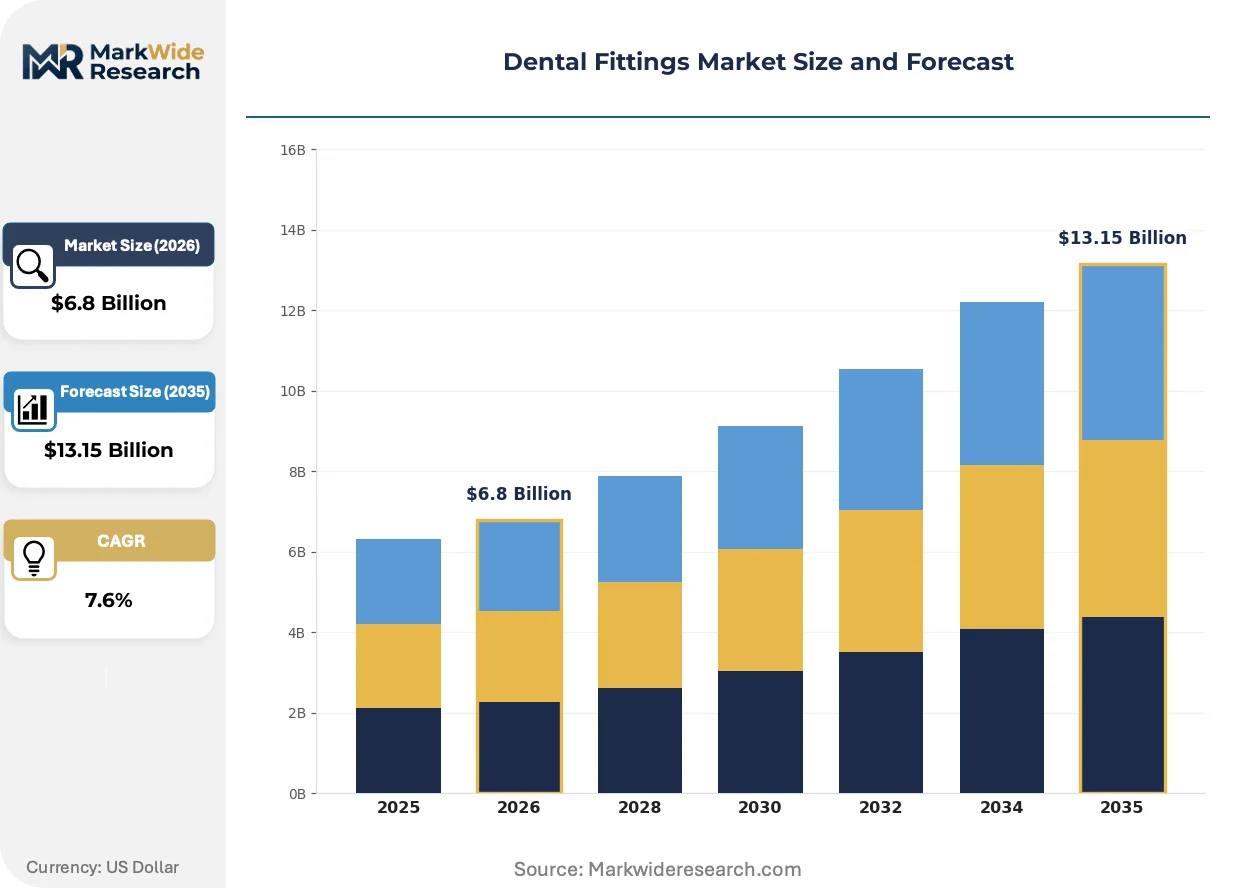
Market Dynamics
Dental laboratories are absorbing patient volume surges through digital workflow adoption, while centralized procurement desks at dental service organizations rewrite supplier engagement terms.
Growth Catalysts
- FDA 510(k) Streamlined Pathway:Expedited clearance for CAD/CAM-manufactured restorations compresses product commercialization timelines for Class II dental devices.
- Same-Day Milling Demand:Chairside digital impression systems enable single-visit crown delivery, pulling laboratory capacity toward 24-hour turnaround models.
- Titanium Alloy Biocompatibility:Osseointegration performance in implant abutments drives surgical adoption across oral surgery practices.
Market Restraints
- Zirconia Powder Cost Volatility:Ceramic raw material price swings squeeze margin pools for anterior restoration manufacturers.
- EU MDR Clinical Evidence Thresholds:Implantable fitting submissions face tightened evaluation requirements, delaying European market access for non-EU manufacturers.
- Hybrid Resin Substitution Pressure:Polymer-based provisional restorations capture price-sensitive denture segments, compressing permanent ceramic volumes.
Strategic Opportunities
- India Clinic Chain Expansion:Cost-engineered implant systems align with emerging dental chain procurement budgets in tier-2 cities.
- AI-Assisted Design Convergence:Machine learning algorithms integrated with intraoral scanners automate margin detection and occlusal mapping.
- Direct-to-Laboratory Digital Platforms:Cloud-based case management portals disintermediate traditional dental supply distributors.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital design and milling operation skills outpace vocational training program output.
- Legacy Practice Management Integration:New digital impression hardware conflicts with installed practice software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fittings Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridges, Crowns, Dentures, Implants Material: Ceramic, Metal, Resin, Composite End User: Clinics, Hospitals, Dental Laboratories, Private Practices Technology: CAD/CAM, 3D Printing, Traditional Milling, Injection Molding |
| Companies Covered | Dentsply Sirona, 3M Company, Zimmer Biomet Holdings, Align Technology, Straumann Group, Osstem Implant, Danaher Corporation, Glidewell, Argen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fittings Market Emerging Trajectories
Intraoral scanning accuracy improvements and regulatory pathway rationalization are compressing restoration delivery cycles while reshaping laboratory-practice relationships.
Artificial intelligence is integrating into digital impression workflows to automate die trimming and contact point optimization. Mid-sized dental laboratories in the United States and Germany are deploying these tools to offset technician staffing gaps. The technology is integrating design-phase automation with milling scheduling systems, collapsing case turnaround from days to hours.
The EU Medical Device Regulation imposes post-market surveillance mandates on implantable dental fittings, requiring manufacturers to maintain clinical follow-up registries. European notified bodies have extended review timelines for ceramic crown submissions lacking biocompatibility documentation. Implant segment suppliers are responding by pre-submission engagement with EMA parallel scientific advice pathways.
Aggregated buying desks at dental service organizations now centralize implant and crown procurement decisions previously made by individual practitioners. This concentration shifts supplier negotiation leverage toward volume-based pricing frameworks and exclusive distribution agreements. The phenomenon is most visible across the United States, where DSOs control procurement for over 10,000 affiliated practice locations.
Dental Fittings Market Segmentation
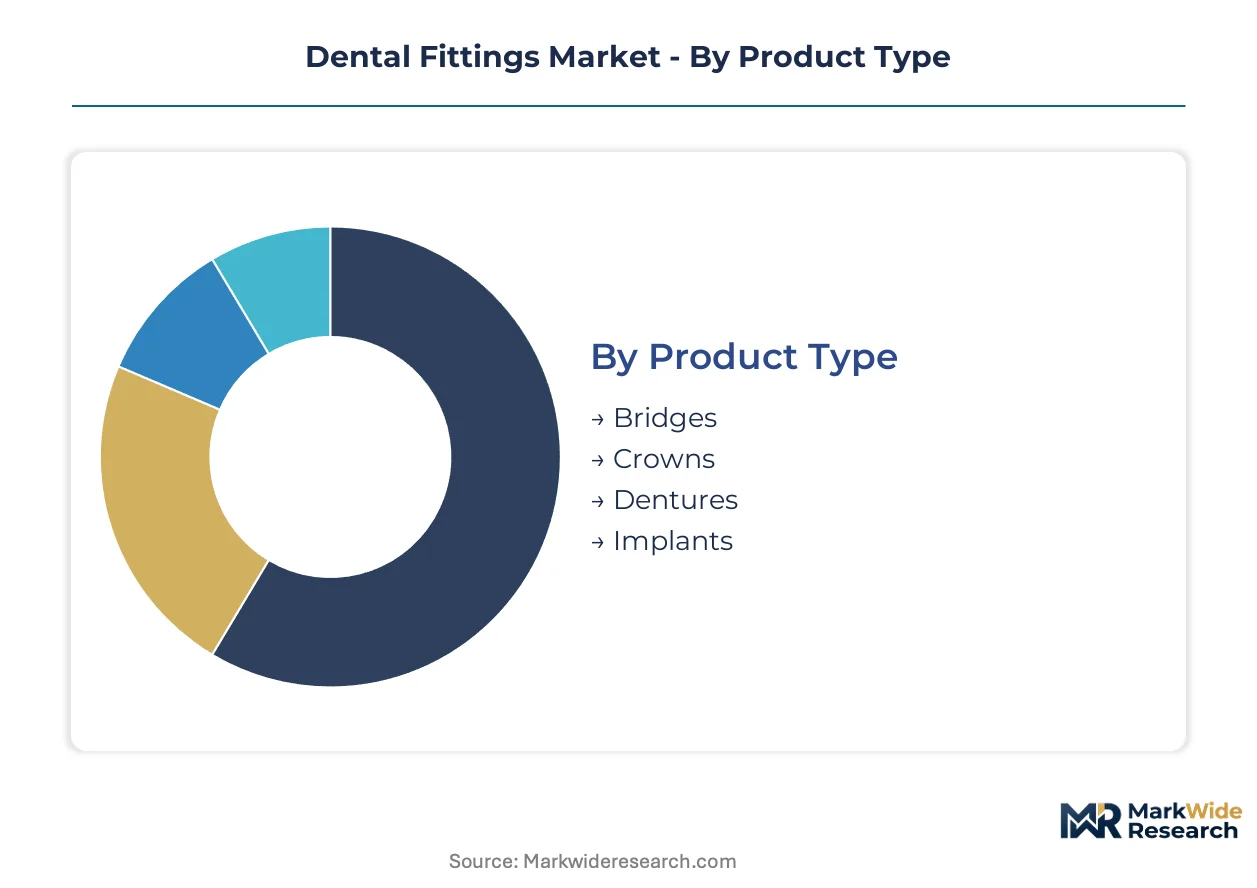
Dental fittings segmentation reveals how material science, manufacturing technology, and procurement authority interact to shape margin pools. Upgrade cycles vary dramatically across product categories, with surgical implants demanding decade-long patient monitoring while CAD/CAM restorations compress replacement timelines to single-visit intervals.
Product Type:
Replacement urgency defines procurement patterns across prosthetic categories, from emergency trauma repairs to elective aesthetic upgrades.
- Implants:Titanium-alloy fixtures with osseointegrated abutments require surgical placement and peri-implant maintenance protocols spanning 10-15 years. Demand concentrates in DSO-affiliated oral surgery practices across the United States, where centralized procurement locks in multi-year supply agreements for implant-to-abutment systems.
- Crowns:Single-tooth restorations manufactured from zirconia or lithium disilicate ceramics restore masticatory function while matching anterior translucency. Same-day milling demand in German and US metropolitan markets compresses laboratory turnaround from weeks to hours, pulling capacity toward chairside CAD/CAM integration.
- Bridges:Multi-unit fixed prostheses span edentulous spaces using pontic frameworks bonded to adjacent abutment teeth. Belgian and Dutch prosthodontic clinics favor monolithic zirconia constructions for posterior durability.
- Dentures:Removable acrylic or hybrid resin appliances replace full or partial arch dentition. India's tier-2 clinic chains procure cost-engineered options from domestic laboratories serving price-sensitive patient bases.
Volume placements concentrate in Crowns; the faster expansion belongs to Implants.
Material:
Cost tiers stratify raw material selection, with premium ceramics commanding 3-4x resin pricing and driving laboratory margin structure.
- Ceramic:Zirconia and glass-ceramic formulations deliver 900-1200 MPa flexural strength for anterior aesthetic zones. Japanese prosthodontic practices specify layered zirconia for incisal translucency matching, while US DSOs negotiate volume contracts for monolithic alternatives.
- Metal:Cobalt-chromium and titanium alloys provide substructure frameworks for porcelain-fused-to-metal restorations. Brazilian dental laboratories continue specifying non-precious metal cores for posterior bridges despite ceramic substitution pressure.
- Resin:PMMA and composite polymers fabricate provisional restorations and economy dentures. South Korean clinic chains deploy 3D-printed resin try-ins for same-day patient approval workflows.
- Composite:Fiber-reinforced hybrid materials bridge temporary and definitive restoration categories. Italian laboratories experiment with bulk-fill composites for in-house milled posterior crowns.
Margin capture peaks in Ceramic; steepest expansion trajectory belongs to Composite as fiber-reinforced formulations mature.
End User:
Customer type determines specification authority, with centralized procurement desks rewriting supplier engagement terms versus individual practitioner discretion.
- Dental Laboratories:Full-service manufacturing facilities absorb digital workflow investments to serve multiple practice clients. German Mittelstand laboratories anchor European throughput with in-house milling centers serving cross-border clients.
- Clinics:Outpatient facilities with chairside CAD/CAM capability bypass traditional laboratory relationships. US DSO-affiliated locations now exceed 10,000 sites with standardized implant procurement protocols.
- Private Practices:Solo and small-group practitioners retain individual supplier relationships despite DSO consolidation pressure. French countryside practices maintain loyalty to regional artisan laboratories.
- Hospitals:Academic medical centers and trauma units handle complex maxillofacial reconstructions. Saudi Arabia's MOHAP-licensed hospital dental departments coordinate with external laboratories for post-surgical prosthetics.
Procurement volume concentrates in Dental Laboratories; patient-facing capability is climbing fastest in Clinics.
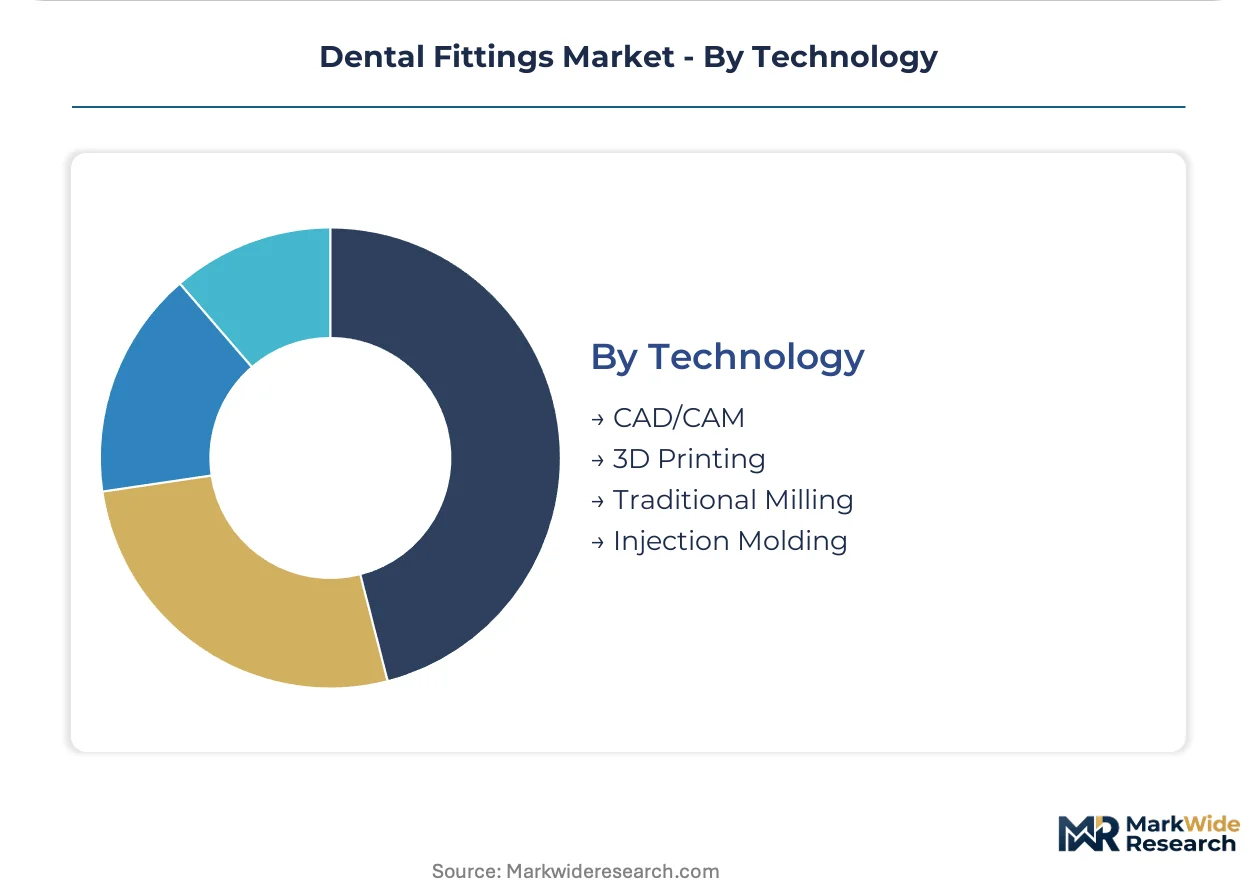
Technology:
Manufacturing maturity separates established milling workflows from emerging additive methods, with regulatory clearance timelines varying by technique.
- CAD/CAM:Computer-aided design and subtractive milling dominate crown and bridge fabrication. FDA 510(k) clearances for intraoral scanner-milling unit pairings accelerate US commercialization for Straumann and Dentsply Sirona systems.
- 3D Printing:Photopolymerization and selective laser sintering enable complex geometries for surgical guides and provisional restorations. Israeli dental startups deploy AI-nested build platforms to maximize printer throughput overnight.
- Traditional Milling:Manual waxing and casting persists for custom implant abutments requiring artisan adjustment. Swiss precision machining houses serve luxury prosthodontic segments.
- Injection Molding:Heated resin injection produces denture bases with standardized dimensional accuracy. Chinese manufacturers supply cost-optimized equipment to Southeast Asian laboratory chains.
Installed base concentrates in CAD/CAM; capability expansion is gaining share fastest in 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DSO-affiliated practices in the United States centralize procurement for over ten thousand locations, while German laboratories anchor European milling capacity and Indian clinic chains drive cost-engineered implant demand across tier-2 cities.
United States
FDA 510(k) clearances for CAD/CAM-manufactured restorations compress commercialization timelines, attracting intraoral scanner manufacturers to establish regulatory submission hubs near Washington DC. Dental service organizations now control procurement for Straumann and Dentsply Sirona implant-to-abutment systems across consolidated practice networks. The Greater Boston corridor hosts precision machining houses serving luxury prosthodontic segments.
Germany
Mittelstand laboratories in Baden-Württemberg and Bavaria operate in-house milling centers serving cross-border clients from Switzerland and Austria. The EU Medical Device Regulation imposes post-market surveillance mandates on implantable fittings, extending notified body review timelines for ceramic crown submissions. Stuttgart anchors European throughput for monolithic zirconia posterior constructions.
India
Domestic laboratories in Gujarat and Maharashtra supply cost-engineered dentures and provisional restorations to emerging clinic chains in tier-2 cities like Pune and Ahmedabad. The Central Drugs Standard Control Organization regulates implantable dental devices under medical device rules, creating compliance pathways for Korean and Chinese manufacturers. Telangana's Hyderabad corridor attracts dental technology training institutes feeding technician demand.
South Korea
Osstem Implant competes on cost-engineered systems tailored to price-sensitive clinic chains across Seoul Capital Area and Busan-Ulsan. The Ministry of Food and Drug Safety maintains abbreviated review pathways for CAD/CAM restorations with predicate device equivalence. Daegu-Gyeongbuk hosts 3D-printed resin try-in facilities serving same-day patient approval workflows.
Switzerland
Swissmedic regulates high-risk implantable fittings with clinical evidence requirements that shape premium-tier market access. Geneva and Zurich precision machining houses maintain artisan workflows for custom implant abutments requiring manual adjustment. The country's dental laboratories serve cross-border demand from French and Italian private practices seeking specialized prosthodontic work.
Dental Fittings Market Vendor Landscape
United States producers anchor the premium-tier implant and CAD/CAM equipment segment; European specialists hold the precision-milled ceramic restoration tier. The vendor base stratifies across three archetypes: vertically integrated implant-to-abutment systems providers, high-throughput laboratory service networks, and cost-engineered emerging-market suppliers. Dominant competitive moves include exclusive distribution agreements with DSO procurement desks and backward integration into zirconia powder supply.
Within the integrated systems tier, Straumann Group and Dentsply Sirona exemplify the implant-to-abutment portfolio approach that captures recurring revenue from aggregated buyers. Osstem Implant occupies a position among cost-engineered suppliers targeting price-sensitive clinic chain expansion in Asia-Pacific and Latin American markets. Glidewell anchors North American laboratory throughput capacity through in-house milling infrastructure serving multi-site dental service organizations.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M Company |
| Zimmer Biomet Holdings |
| Align Technology |
| Straumann Group |
| Osstem Implant |
| Danaher Corporation |
| Glidewell |
| Argen |
| Others |
Supply Flow & Price Mechanics
Zirconia powder costs cascade through three distinct pricing tiers as raw material volatility from Chinese and Japanese suppliers compresses margin pools for anterior restoration manufacturers while rewarding laboratories with captive milling capacity.
Pricing Analysis
Volume placements concentrate in monolithic zirconia crowns at standard-tier price points, while layered ceramic constructions for incisal translucency matching capture premium-tier margins. Price differentiation hinges on ISO 13485 certification status and DSO contract scale, with FDA 510(k) clearance tier commanding additional positioning leverage. Cost compression in economy resin dentures is intensifying because Korean and Chinese manufacturers are flooding Southeast Asian laboratory chains with injection-molded alternatives. Tier-2 Indian clinic chains exhibit highest price sensitivity; Swiss precision machining houses serving luxury prosthodontic segments show least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese zirconia powder refineries and German precision milling equipment suppliers, exposing manufacturers to input cost shocks and extended lead times. Production gravity centers on China for raw ceramic powders, Germany for CAD/CAM milling centers, and Switzerland for custom implant abutment machining. Supply chains draw from titanium alloy feedstock, photopolymer resins, and cobalt-chromium frameworks. Tariff exposure on Chinese ceramic imports threatens margin structures for US-based laboratories. Distribution runs through dental supply distributors being disintermediated by direct-to-laboratory digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
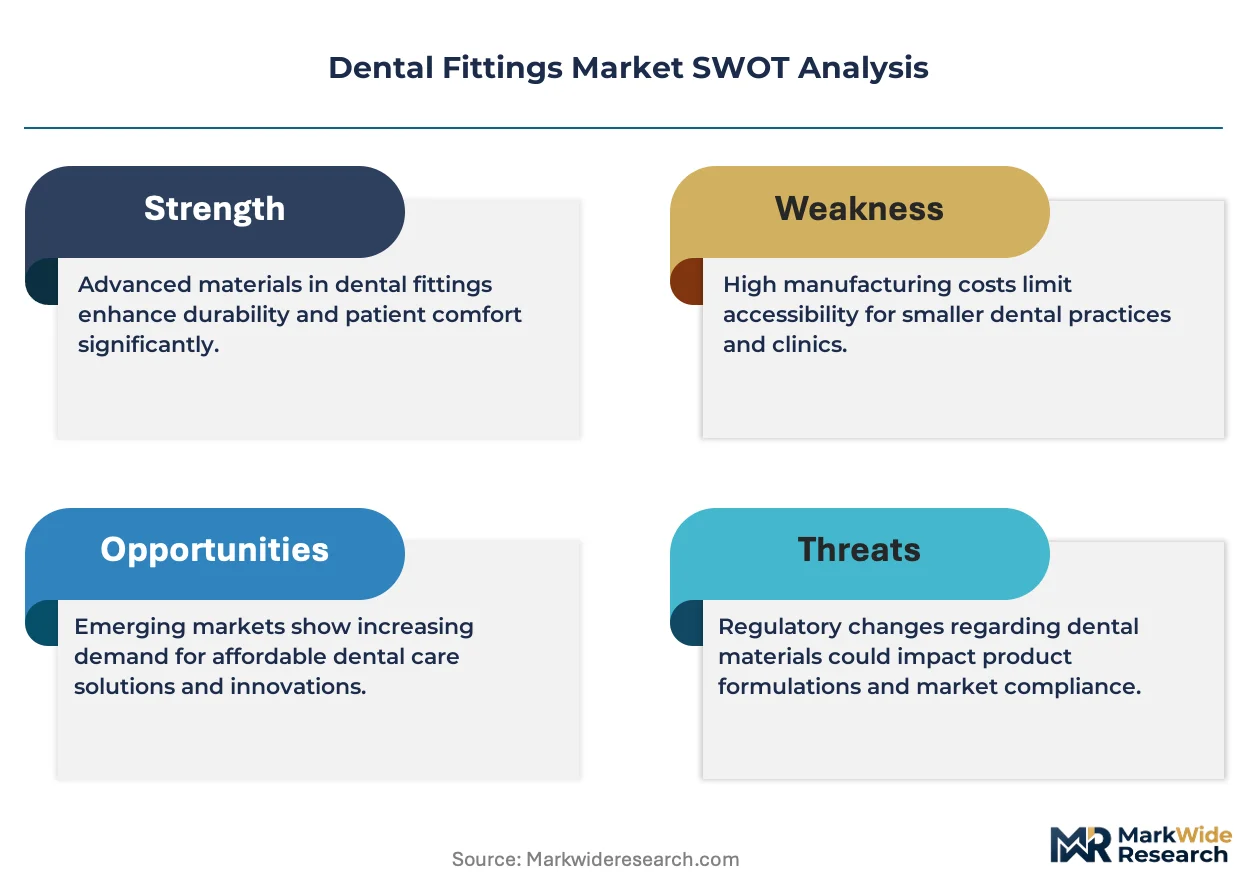
The EU Medical Device Regulation's clinical evidence thresholds for implantable fittings create a cost-of-compliance moat that filters out undercapitalized competitors while cementing incumbent positioning for ISO 13485-certified manufacturers with notified body relationships.
For Market Incumbents: Anticipate Korean and Chinese cost-engineered implant systems penetrating Latin American and Southeast Asian clinic chains by hardening exclusive distribution agreements with US DSO procurement desks and accelerating backward integration into zirconia powder supply to defend margin structures against raw material volatility. For New Entrants and Emerging Players: Solo practitioners in French and Italian countryside markets remain underserved by digital workflow providers, presenting white-space entry through chairside CAD/CAM leasing models that bypass capital-intensive laboratory infrastructure and leverage AI-assisted design tools to offset technician scarcity constraints. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for intraoral scanner-milling unit pairings is the leading indicator that digital workflow consolidation is entering its terminal phase, suggesting a 5-10 year window where mid-cap laboratories with installed milling capacity represent prime acquisition targets before DSO vertical integration eliminates independent supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined clearance compresses commercialization timelines for CAD/CAM restoration manufacturers competing for DSO contracts. |
| Backward Integration into Zirconia Supply | Captive powder sourcing insulates margin pools from Chinese raw material price volatility affecting anterior ceramic producers. |
| AI-Assisted Design Platform Deployment | Machine learning integration with intraoral scanners automates margin detection for laboratories facing technician staffing gaps. |
| Direct-to-Laboratory Digital Platform Launch | Cloud-based case management portals disintermediate traditional dental supply distributors serving German Mittelstand laboratories. |
| Exclusive DSO Distribution Agreements | Multi-year supply contracts with centralized procurement desks lock out competitors from Straumann and Dentsply Sirona's core revenue base. |
Methodological Framework
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and ISO 13485 certification registries, complemented by interviews with dental laboratory operations directors, DSO procurement managers, biomedical engineers at implant manufacturers, and notified body auditors. Secondary validation drew from customs trade data on zirconia powder imports, hospital procurement databases tracking GPO contract awards, and CMS Medicare utilization statistics for prosthodontic procedures. Bottom-up and top-down triangulation reconciled laboratory throughput capacity estimates with patient volume projections across metropolitan and tier-2 markets.
Segment-level outputs across the analysis window reflect modeled interactions between product type, material tier, end-user category, and manufacturing technology adoption curves. The analytical framework incorporated implant-to-abutment system upgrade cycles, CAD/CAM restoration replacement frequencies, and denture procurement patterns by clinic chain versus independent practice. CAGRs were derived from regression analysis of historical laboratory equipment shipments correlated with patient visit data and digital impression system installations. Industry-specific inputs included osseointegration protocol adherence rates and ceramic crown biocompatibility documentation completeness.
Revisions become necessary when EU notified bodies extend ceramic crown review timelines, when Chinese environmental regulations disrupt zirconia powder refining capacity, or when DSO consolidation accelerates beyond current affiliation trajectories. Forecasts reflect documented assumptions about regulatory pathway stability, raw material supply continuity, and technician training program output. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Crown Removal Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Orthodontics Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Laboratories Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Nano Dentistry Market