
 North America Aligner Sheet Market | 2026-2036
North America Aligner Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aligner Sheet Market Analytics
Modular aligner packaging is restructuring how orthodontic groups configure treatment bundles for patients. Align Technology, Inc. leverages its integrated scanner-to-aligner workflow to control digital case submission channels across North America. Dentsply Sirona anchors its position through chairside CAD/CAM ecosystems that streamline same-day aligner fittings. Henry Schein, Inc. competes via distribution scale that reaches independent practices in secondary U.S. markets.
North America Aligner Sheet refers to thin, thermoformed polymer membranes engineered from medical-grade polyurethane, polycarbonate, or multilayer thermoplastic composites, typically ranging from 0.3 to 1.0 mm in thickness, fabricated through pressure-thermoforming or direct 3D printing processes to deliver sequential orthodontic tooth movement. Clear aligners dominate volume due to adult aesthetic demand and direct-to-consumer marketing channels, while custom aligners command premium positioning through AI-driven treatment planning software integrated with intraoral scanning. Thermoforming technology sustains manufacturing scale for high-volume producers, though 3D printing is gaining traction for same-day and remote-fabrication models.
FDA 510(k) premarket notification requirements and Health Canada Medical Device License standards govern biocompatibility, mechanical testing, and clinical validation for aligner sheet materials sold across the United States and Canada. OSHA workplace exposure limits and state-level dental board regulations additionally shape manufacturing facility location and laboratory technician certification requirements. Stakeholders must monitor evolving FDA guidance on custom device exemptions and Health Canada transitions toward enhanced post-market surveillance frameworks.
Market Dynamics
Dental service organization consolidation across the United States and Canada is compressing procurement channels and forcing aligner sheet manufacturers to reconfigure volume pricing frameworks around multi-location contract structures.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification procedures for thermoformed polymer devices accelerate commercialization timelines for new aligner sheet formulations entering the United States market.
- Intraoral Scanner Penetration:Chairside digital impression systems in California and Texas orthodontic corridors eliminate physical mold logistics and compress case turnaround intervals.
- Adult Aesthetic Demand:Patients aged 25-45 in metropolitan dental markets prioritize clear aligner therapies over traditional fixed appliances, expanding addressable case volumes.
Market Restraints
- Medical-Grade Polyurethane Supply Concentration:Raw material sourcing depends on a limited supplier base concentrated in the northeastern United States, creating input cost volatility during polymer feedstock disruptions.
- Health Canada Licensing Friction:Medical Device License application timelines for new aligner materials extend commercialization windows for manufacturers targeting Ontario and British Columbia markets.
- Direct 3D Printing Substitution:Same-day fabrication technologies threaten thermoforming equipment utilization rates in high-volume production facilities.
Strategic Opportunities
- Secondary U.S. Market Penetration:Independent practices in Michigan, Ohio, and Arizona remain underpenetrated by integrated scanner-to-aligner workflows, presenting distribution expansion potential.
- AI-Driven Treatment Planning Convergence:Machine learning algorithms paired with predictive biomechanics software enable complex malocclusion cases previously reserved for fixed appliances.
- Remote Monitoring Channel Innovation:Tele-dentistry platforms integrated with patient-facing mobile applications reduce chair time requirements and expand rural Canada access.
Industry Challenges
- Orthodontic Technician Certification Complexity:State-level dental board regulations in Texas and New York impose divergent laboratory technician licensing requirements, fragmenting workforce mobility.
- CAD/CAM Integration Capex:Chairside digital ecosystems require substantial capital deployment for intraoral scanners, design software licenses, and milling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aligner Sheet Market |
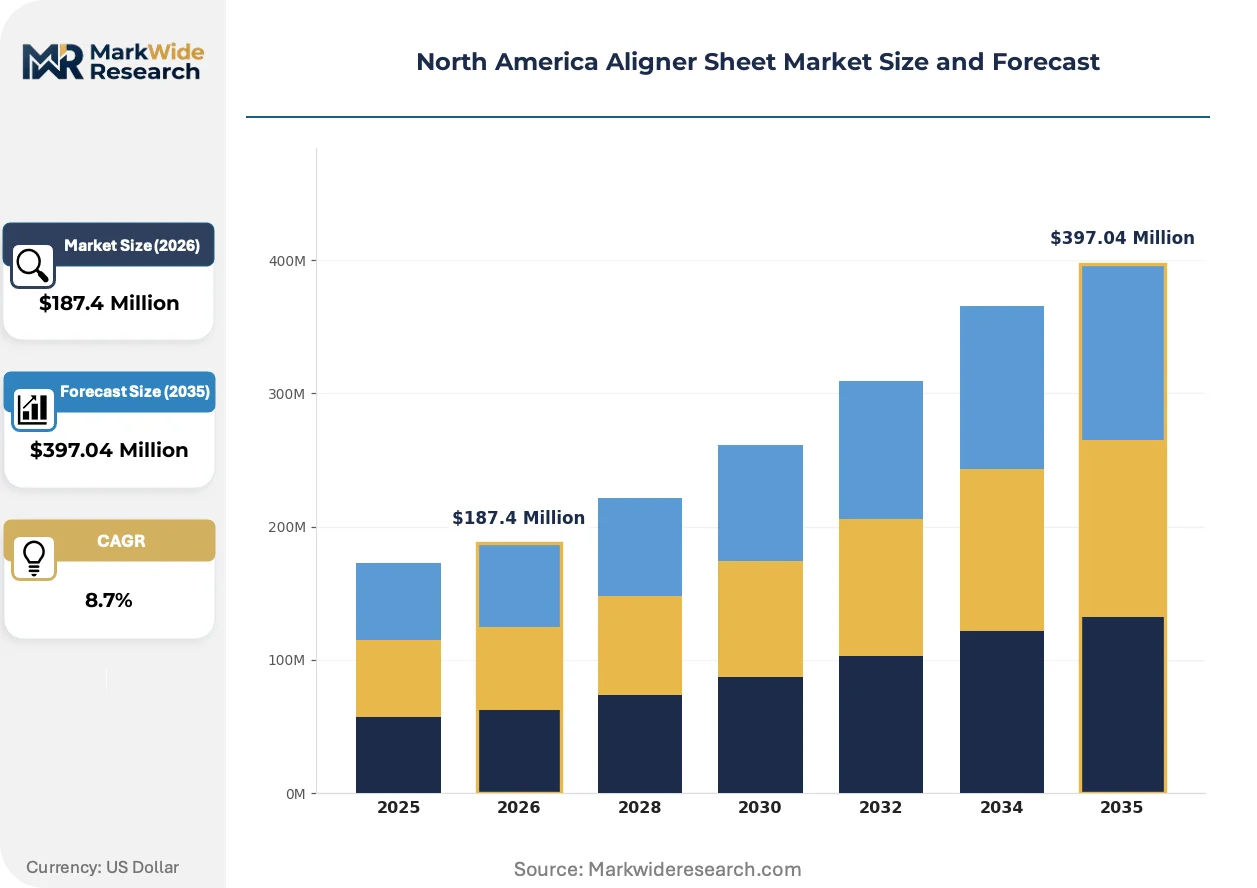
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Aligners, Clear Aligners, Retainers, Dual-Arch End User: Orthodontic Clinics, Dental Hospitals, Private Practices, Home Care Technology: 3D Printing, CAD/CAM, Injection Molding, Thermoforming Material: Polyurethane, Polycarbonate, Thermoplastic, Composites |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Ormco Corporation, Bay Materials, LLC, MAXFLEX CO, Ltd, Tru-Tain, G&H Orthodontics, 3M Company, Henry Schein, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aligner Sheet Market Evolving Landscape
Chairside fabrication technologies and AI-integrated treatment planning are collapsing traditional laboratory intermediaries while reshaping how orthodontic groups configure patient service bundles across North America.
Direct 3D printing of aligner sheets from biocompatible photopolymer resins is decentralizing production authority away from centralized manufacturing facilities toward individual practice locations. Multi-location orthodontic groups in California and Texas are piloting same-day aligner fitting workflows that compress delivery from weeks to hours. This technology is decentralizing the traditional scanner-to-laboratory-to-patient supply chain into localized closed-loop systems.
Health Canada is tightening post-market surveillance frameworks for custom medical devices, requiring enhanced adverse event reporting from aligner manufacturers operating in Ontario and Quebec. The regulatory shift elevates compliance documentation burdens and accelerates quality management system investments. Small-to-mid-sized manufacturers serving the Canadian market face disproportionate adaptation costs relative to integrated multinational systems.
Adult patients are unbundling treatment planning from appliance procurement, seeking standalone diagnostic services before selecting aligner providers. Direct-to-consumer platforms and dental service organization membership programs are displacing traditional referral-based patient acquisition in New York and Illinois metropolitan corridors. This behavioral shift concentrates negotiating leverage with large buyers and compresses margins for independent practitioners lacking scale purchasing agreements.
North America Aligner Sheet Market Segmentation
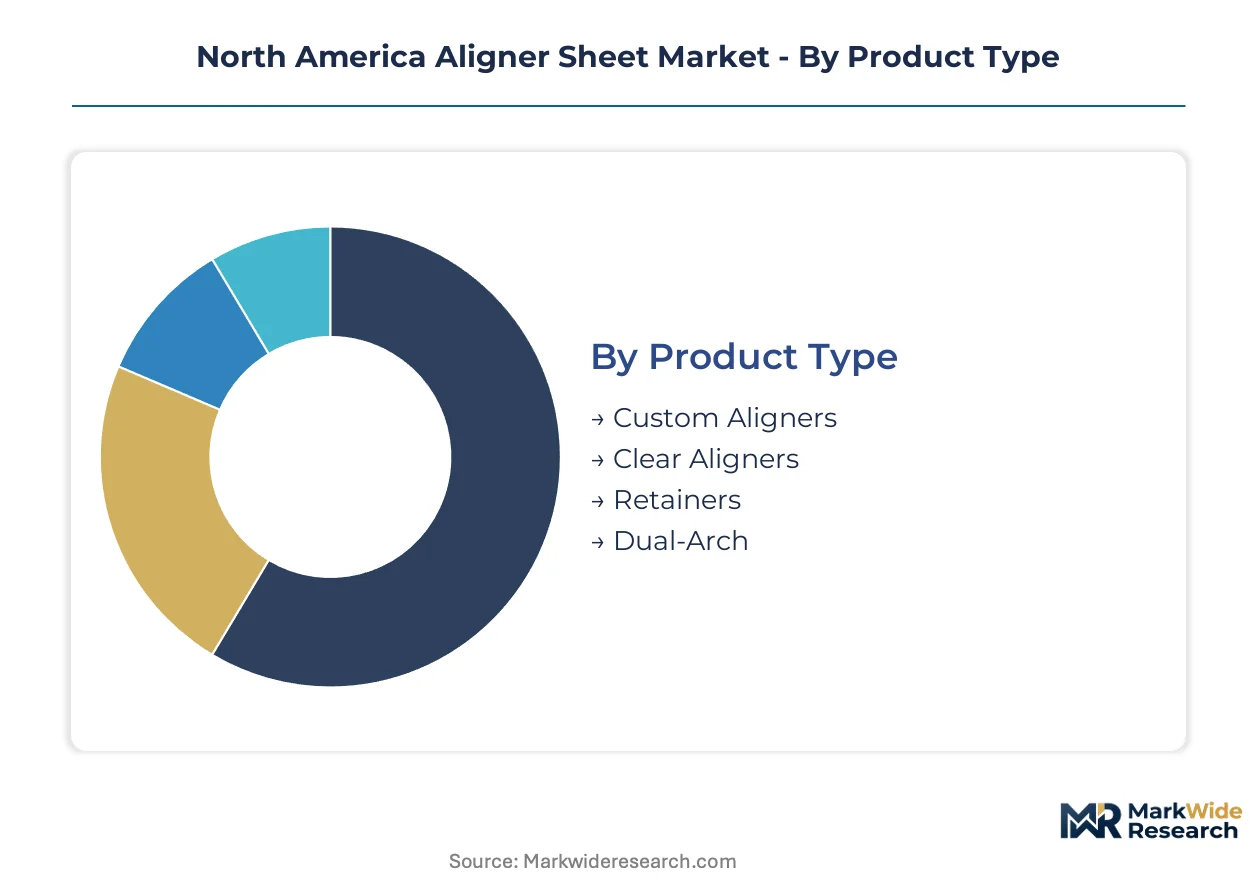
Segmentation reveals how treatment modality, fabrication technology, and material selection partition purchasing power across orthodontic service delivery models. Understanding these divisions exposes where margin compression concentrates and where premium positioning remains defensible.
Product Type:
Replacement cycles for aligner systems vary sharply by product category, with some segments demanding annual refresh while others extend across multi-year retention phases.
- Clear Aligners:Thermoformed polyurethane or multilayer composite sheets deliver sequential tooth movement through transparent, removable appliances. Adult aesthetic demand in California and Texas metropolitan corridors drives volume concentration, though direct-to-consumer channel expansion is eroding traditional orthodontic gatekeeper control.
- Custom Aligners:Patient-specific appliances fabricated from AI-driven treatment planning software paired with intraoral scanning workflows command premium pricing through individualized biomechanical optimization. Dental service organizations in Ontario and New York prioritize these systems for complex malocclusion cases previously reserved for fixed appliances.
- Retainers:Post-treatment retention devices utilize thinner gauge materials for passive stabilization.
- Dual-Arch:Simultaneous upper and lower arch treatment configurations streamline case management for comprehensive therapy.
Clear Aligners sits at the top of the volume ranking, with Custom Aligners climbing the fastest.
End User:
Customer type determines procurement scale, with consolidated buyers extracting volume concessions unavailable to fragmented purchasers.
- Orthodontic Clinics:Dedicated malocclusion treatment facilities generate the highest per-practice aligner sheet consumption through specialized case volume. Multi-location groups in Texas and California negotiate enterprise pricing tiers that independent operators cannot replicate.
- Private Practices:Solo and small-group general dental practitioners represent dispersed demand requiring distribution intermediaries. Michigan, Ohio, and Arizona secondary markets show underpenetration by integrated scanner-to-aligner workflows, constraining volume growth relative to coastal corridors.
- Dental Hospitals:Academic and institutional settings drive research-oriented procurement with extended validation timelines.
- Home Care:Direct-to-consumer models bypass traditional clinical intermediaries through remote impression kits and tele-dentistry platforms.
Orthodontic Clinics capture the dominant share of purchasing volume, while Home Care demonstrates the steepest expansion trajectory.
Technology:
Fabrication method dictates capital intensity, throughput economics, and geographic feasibility of distributed production networks.
- Thermoforming:Pressure-molded polymer sheet processing sustains manufacturing scale for high-volume producers serving dental service organization contracts. Equipment utilization rates face pressure from same-day fabrication alternatives in California pilot programs.
- 3D Printing:Direct photopolymer resin curing enables chairside production at individual practice locations, collapsing traditional laboratory intermediaries. Texas and California multi-location groups deploy these systems for same-day aligner fitting workflows compressing delivery from weeks to hours.
- CAD/CAM:Digital design-to-manufacture integration streamlines case planning and appliance production coordination.
- Injection Molding:High-throughput polymer forming serves standardized component production with limited customization.
Thermoforming retains volume leadership, with 3D Printing gaining share fastest through decentralized deployment.
Material:
Raw material selection governs biocompatibility certification, mechanical performance, and supply security across FDA and Health Canada jurisdictions.
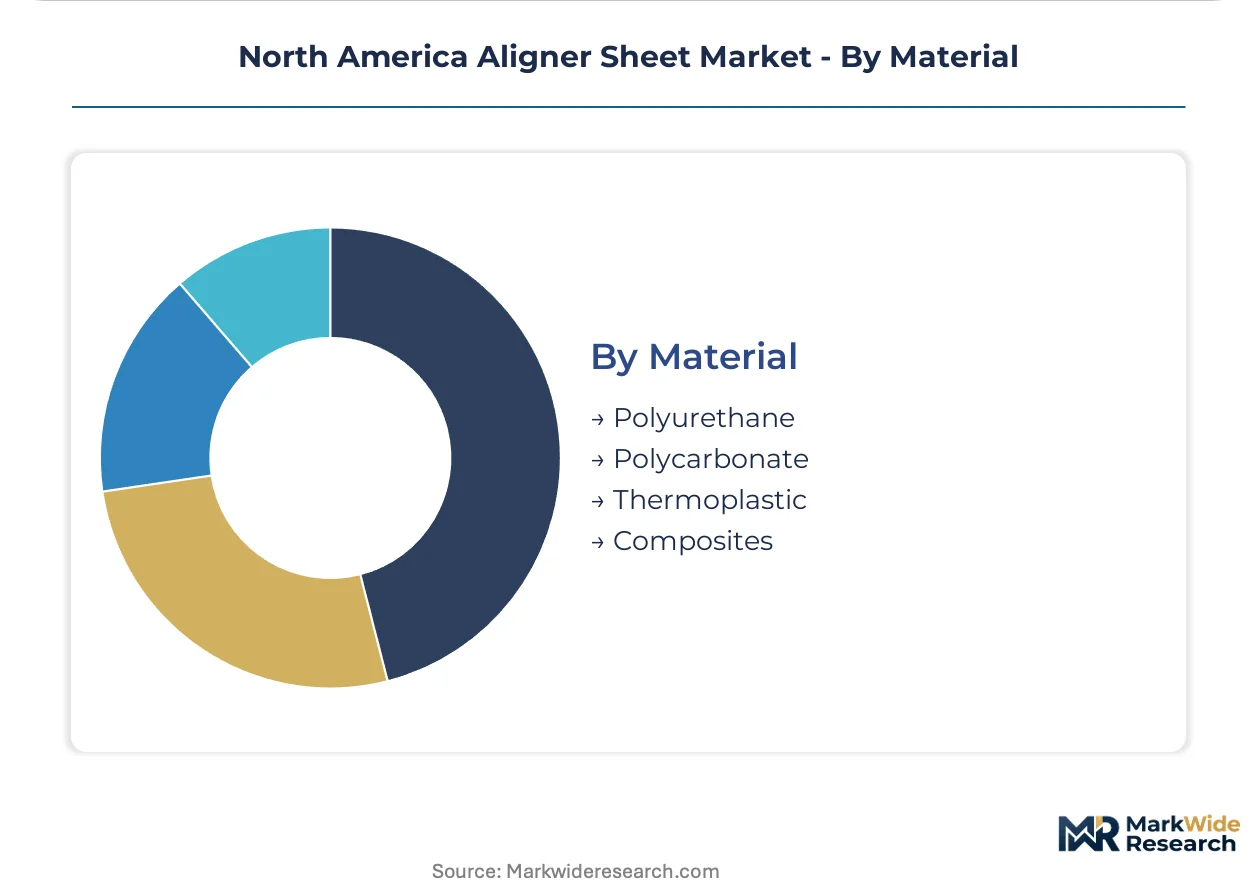
- Polyurethane:Medical-grade elastomeric polymers dominate clear aligner fabrication through optical clarity, stain resistance, and controlled force delivery. Northeastern United States supplier concentration creates input cost volatility during polymer feedstock disruptions.
- Polycarbonate:High-strength thermoplastic alternatives serve applications demanding enhanced rigidity and impact resistance. Health Canada Medical Device License requirements for new material formulations extend commercialization timelines for manufacturers targeting Ontario markets.
- Thermoplastic:General-purpose moldable polymers support cost-sensitive appliance categories.
- Composites:Multilayer or fiber-reinforced configurations address specialized biomechanical requirements.
Polyurethane maintains the highest consumption base, with Polycarbonate expanding most quickly in premium positioning segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Aligner Sheet Market traces its commercial lineage to the San Jose corridor, where digital orthodontic workflows first scaled from laboratory prototypes to mass-market clear aligner systems during the late 1990s.
United States
California and Texas metropolitan dental corridors concentrate the highest aligner sheet consumption through dense orthodontic clinic networks. FDA 510(k) premarket notification pathways govern biocompatibility certification for polyurethane and polycarbonate formulations entering interstate commerce. The Dallas-Fort Worth metroplex hosts multi-location orthodontic groups piloting same-day 3D printing workflows that compress appliance delivery timelines.
Canada
Ontario and British Columbia drive Canadian demand through dental service organization consolidation in Toronto and Vancouver metropolitan areas. Health Canada Medical Device License requirements extend commercialization timelines for new aligner materials relative to FDA pathways. Montreal's dental technology corridor sustains specialized thermoforming operations serving Quebec's provincial orthodontic market.
California
Los Angeles and San Francisco Bay Area clusters anchor the highest per-capita clear aligner adoption rates among U.S. states. OSHA workplace exposure limits for polymer processing facilities shape manufacturing site selection decisions in inland industrial zones. San Diego's biotech corridor incubates next-generation photopolymer resin formulations for chairside fabrication systems.
Texas
Houston and Austin orthodontic markets exhibit steep growth curves for adult aesthetic treatment demand among patients aged 25-45. State-level dental board regulations impose laboratory technician certification requirements that fragment workforce mobility across metropolitan boundaries. The Dallas medical district hosts integrated scanner-to-aligner distribution hubs serving southwestern U.S. secondary markets.
New York
New York City and surrounding metropolitan counties concentrate premium-priced custom aligner demand through high-income patient demographics. Empire State dental board regulations diverge from neighboring jurisdictions in laboratory technician licensing standards. Buffalo-Rochester industrial zones sustain thermoforming equipment manufacturing for aligner sheet production systems.
North America Aligner Sheet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across digital workflow integration depth, with scanner-to-aligner ecosystem control separating pricing power tiers. The vendor base concentrates around integrated multinationals with chairside CAD/CAM infrastructure and specialized material suppliers serving regional fabrication laboratories. Three archetypes dominate: ecosystem-integrated device manufacturers, standalone aligner sheet material specialists, and dental distribution intermediaries with private-label positioning. Competitive moves center on backward integration into intraoral scanning hardware and strategic partnerships with dental service organizations for multi-location contract capture.
Within the ecosystem-integrated tier, Align Technology, Inc. and Dentsply Sirona occupy positions defined by end-to-end digital workflow control from impression capture through appliance delivery. Henry Schein, Inc. represents the distribution-scale archetype, leveraging procurement reach into independent practices across secondary U.S. markets. These three entities exemplify how competitive positioning in the North America Aligner Sheet Market derives from channel architecture rather than material formulation alone.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Ormco Corporation |
| Bay Materials, LLC |
| MAXFLEX CO, Ltd |
| Tru-Tain |
| G&H Orthodontics |
| 3M Company |
| Henry Schein, Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA 510(k) cleared materials and uncertified alternatives splits pricing power across the North America Aligner Sheet Market, with premium tiers commanding leverage through Health Canada Medical Device License documentation while commodity-grade polyurethane suppliers compete on volume discounts to dental service organizations. This bifurcation concentrates margin capture among integrated manufacturers with captive regulatory affairs capabilities, while independent laboratories absorb pricing compression through distributor intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated custom aligner systems from thermoformed clear aligners and basic retention devices. Price differentiation hinges on FDA 510(k) clearance tier and volume scale, with orthodontic clinic groups extracting enterprise concessions unavailable to solo practitioners. Cost compression in the standard tier intensifies because direct-to-consumer platforms displace traditional clinical gatekeepers. Home care direct-to-consumer models exhibit the highest price sensitivity, while dental service organizations demonstrate the lowest due to multi-location contract leverage.
Supply Chain Analysis
Dual-sourcing requirements from major orthodontic groups mandate polyurethane qualification across at least two medical-grade polymer suppliers, forcing manufacturers to maintain redundant relationships despite northeastern United States supplier concentration. Raw material sourcing draws from medical-grade polyurethane, polycarbonate resin, and photopolymer resin inputs. Single-source vulnerability concentrates in polyurethane feedstock suppliers clustered in the northeastern United States. Distribution runs through Henry Schein, Inc. and regional dental supply intermediaries reaching independent practices in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Aligner Sheet Market reads as a late-cycle quality story where adult patients aged 25-45 shift demand toward AI-integrated custom aligner systems with predictive biomechanical optimization, rewarding manufacturers with end-to-end digital workflow control.
For Market Incumbents: Deploy backward integration into intraoral scanning hardware to defend against chairside 3D printing substitution threatening thermoforming equipment utilization. Secure multi-location dental service organization contracts in Texas and California before same-day fabrication technologies collapse traditional laboratory intermediaries. FDA 510(k) clearance velocity serves as the critical lever for premium tier retention. For New Entrants and Emerging Players: Enter via remote monitoring platform partnerships targeting rural Canada access gaps where tele-dentistry infrastructure remains underdeveloped. Michigan, Ohio, and Arizona independent practices represent the most penetrable geography for scanner-to-aligner workflow displacement. Direct-to-consumer channel positioning with patient-facing mobile applications offers the clearest go-to-market angle against entrenched distribution networks. For Investors and Strategic Acquirers: Consolidation pressure builds where Health Canada post-market surveillance framework compliance costs disproportionately burden small-to-mid-sized manufacturers lacking integrated quality management systems. Long-term viability favors acquisition targets with captive polyurethane supply relationships and Ontario market licensing authority. Watch for FDA guidance evolution on custom device exemptions as the signal indicating regulatory arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification efficiency compresses commercialization timelines for new polyurethane formulations entering interstate commerce. |
| Health Canada Medical Device License Investment | Enhanced post-market surveillance compliance secures Ontario and British Columbia market access against regulatory friction. |
| Dental Service Organization Partnership | Multi-location contract capture concentrates volume purchasing power and extracts pricing concessions from distributor intermediaries. |
| Chairside 3D Printing Deployment | Same-day fabrication workflows in Texas and California pilot programs collapse traditional scanner-to-laboratory delivery timelines. |
| AI-Driven Treatment Planning Integration | Machine learning algorithms paired with intraoral scanning enable complex malocclusion cases previously reserved for fixed appliances. |
Research Methodology
Direct dialogue with orthodontic clinic procurement managers, dental laboratory technicians, intraoral scanner manufacturers, and Health Canada regulatory affairs specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) premarket notification databases, Health Canada Medical Device License records, dental service organization financial disclosures, and OSHA workplace exposure compliance filings. Bottom-up case volume modeling and top-down polymer consumption estimates were triangulated against distributor shipment data.
Market sizing outputs trace demand across product type, fabrication technology, material composition, and end-user archetype throughout the forecast period. CAGRs were derived from regression analysis of historical case submission volumes correlated with intraoral scanner installation rates and adult demographic expansion. Modeled inputs include orthodontic clinic consolidation trajectories, polyurethane feedstock price indices, and regulatory pathway efficiency differentials between FDA and Health Canada jurisdictions.
Inputs from orthodontic group purchasing organizations and regional dental supply distributors were available through the study window; gaps in real-time chairside 3D printing adoption metrics introduce uncertainty bands around decentralized production forecasts. Deviation in FDA custom device exemption guidance or Health Canada post-market surveillance enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Dental Forceps Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Europe Dental Implants Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Dental Handpieces Market
Dental Devices
North America Dental Lab Market