
 Dental Delivery System Market | 2026-2036
Dental Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Delivery System Market Outlook
Digital integration into chairside workflows is fragmenting the traditional mechanical delivery architecture across dental operatories. A-dec Inc. leverages its manufacturing scale to sustain dominance in premium mechanical systems for high-volume practices. DENTALEZ, Inc. anchors the mid-market with pneumatic configurations that balance cost and reliability. Midmark competes through specialized ergonomic designs that reduce clinician fatigue during extended procedures.
A dental delivery system comprises the mobile or fixed cabinet, hoses, handpiece controls, and utility management interfaces that supply air, water, suction, and power to dental instruments during patient treatment. These systems integrate pressure regulators operating at 80 psi for air and 40 psi for water lines to ensure consistent instrument performance across procedure types. Electric delivery systems now lead product type segmentation as practices prioritize torque consistency and reduced noise over pneumatic alternatives. Dental clinics represent the largest end user segment by installed base, though hospitals are expanding their dental service lines and driving incremental demand for hybrid configurations. CAD/CAM solutions within technology segmentation command premium positioning due to their integration with digital impression workflows and same-day restoration fabrication.
FDA 510(k) clearance requirements govern electromechanical dental equipment safety, while ISO 13485 quality management standards shape supplier certification and market access protocols for international manufacturers. The EPA regulates amalgam separator compliance within delivery system waste management, directly influencing product configuration requirements for US installations. Stakeholders must monitor evolving MDR requirements in Europe and the convergence of AI-driven diagnostic tools with delivery system interfaces as regulatory frameworks adapt to software-enabled medical devices.
Market Dynamics
Electric handpiece technology is collapsing the legacy pneumatic infrastructure that has dominated dental operatories for decades, forcing manufacturers to reconfigure delivery architectures around torque precision and digital control interfaces rather than air-driven mechanical systems.
Growth Catalysts
- CDC Infection Control Guidelines:Updated waterline sterilization mandates in the United States are accelerating replacement cycles for aging delivery units in outpatient dental clinics.
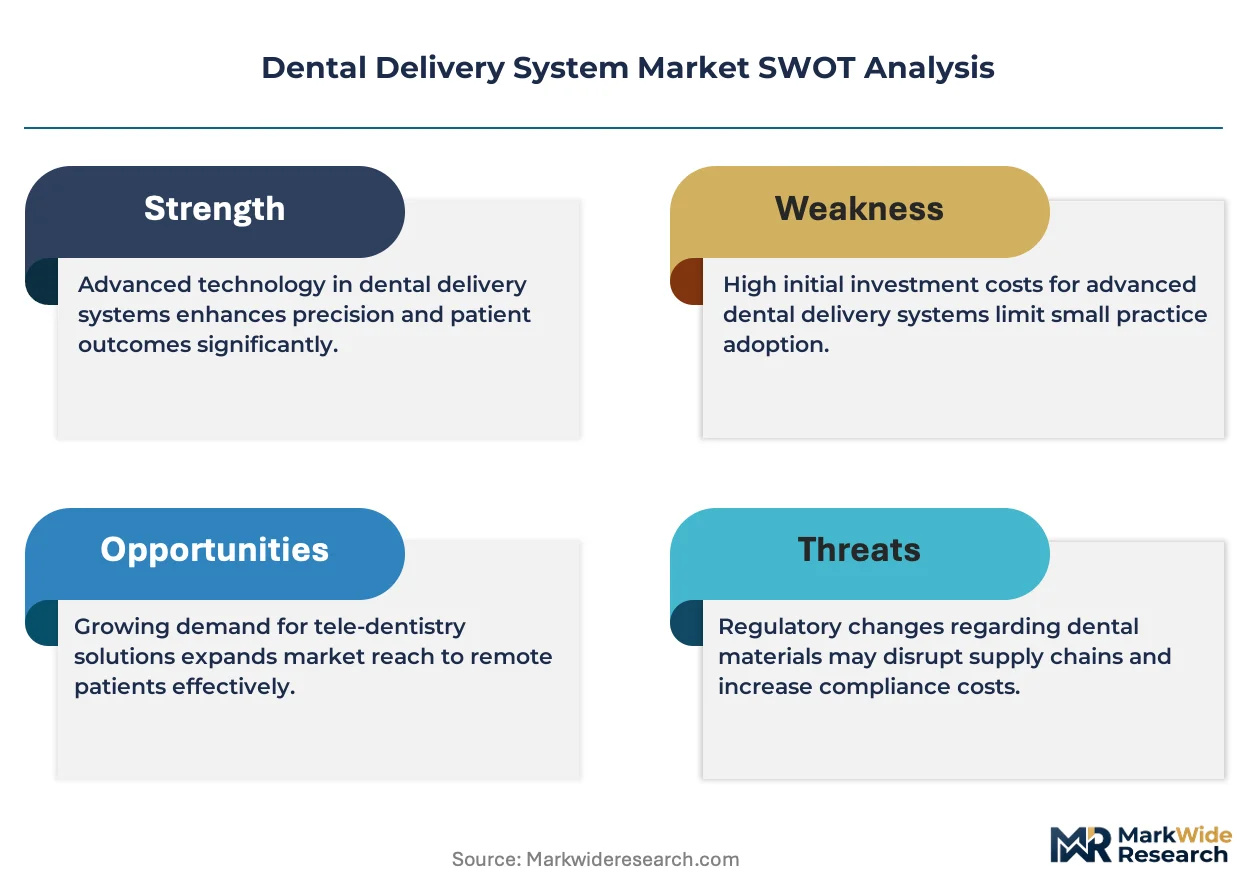
- Japan's Aging Practice Infrastructure:Over 40% of Japanese dental facilities operate equipment exceeding 15 years of service life, creating concentrated demand for modernized delivery systems with integrated digital workflows.
- Electric Motor Technology:Brushless DC motors delivering consistent torque output are displacing pneumatic turbines in high-volume restorative procedures across German university hospitals.
Market Restraints
- Copper and Aluminum Input Volatility:Raw material price swings for pneumatic hose sheathing and cabinet housings compress margin stability for mid-tier manufacturers.
- ISO 13485 Certification Burden:Quality management system audits impose 12-18 month market entry delays for Asian suppliers seeking European distribution.
- Chairside CAD/CAM Substitution:Same-day milling units with self-contained utility management reduce dependency on centralized delivery infrastructure in premium practices.
Strategic Opportunities
- India's Tier-2 City Expansion:Underpenetrated dental service networks in Pune, Jaipur, and Lucknow present first-mover positioning for modular delivery configurations.
- EU MDR Software Classification:AI-enabled diagnostic interfaces integrated into delivery system touchscreens qualify as Class IIa medical devices, creating regulatory differentiation for compliant suppliers.
- Subscription-Based Equipment Models:Leasing structures bundling maintenance and upgrade pathways are displacing capital purchase patterns among US dental service organizations.
Industry Challenges
- Biomedical Equipment Technician Shortage:Specialized training for electromechanical calibration and pressure regulation troubleshooting lags behind electric system deployment rates in community health centers.
- Legacy Pneumatic Integration:Hybrid retrofit kits for existing chair-mounted units create compatibility failures with third-party handpiece couplings, generating service call escalations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Delivery System Market |
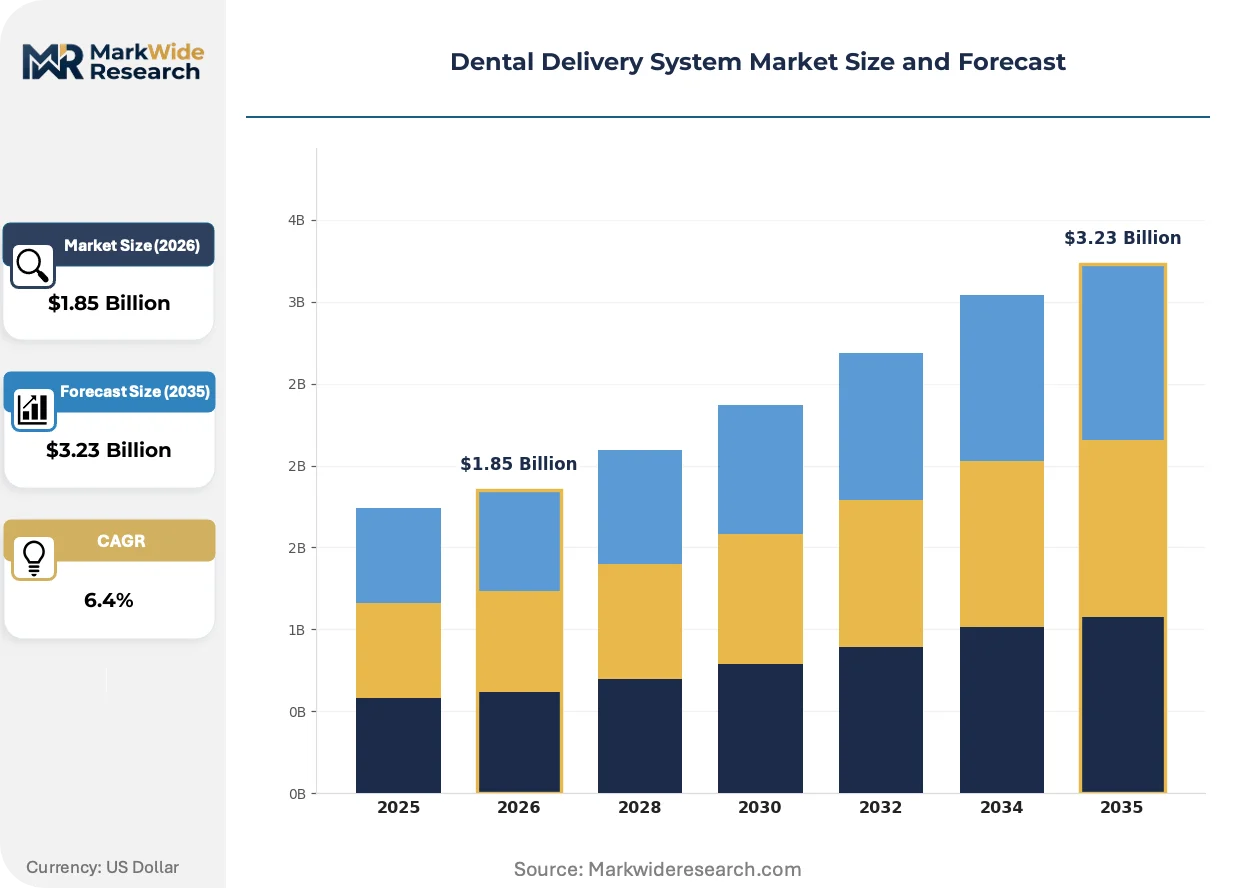
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Delivery Systems, Pneumatic Delivery Systems, Electric Delivery Systems, Hybrid Delivery Systems End User: Dental Clinics, Hospitals, Dental Laboratories, Educational Institutions Application: General Dentistry, Orthodontics, Periodontics, Cosmetic Dentistry Technology: Digital Imaging, Laser Systems, CAD/CAM Solutions, 3D Printing |
| Companies Covered | A-dec Inc., DENTALEZ, Inc., Aseptico Inc., Midmark, ADS Dental System, MGI Healthcare, Dental International, Olsen, Beaverstate Dental Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Delivery System Market Strategic Shifts
Digital convergence is dissolving the boundary between mechanical utility delivery and diagnostic data processing, transforming the dental operatory from a passive equipment housing into an active node in integrated patient care workflows.
Ultrasonic scaler technology with variable frequency modulation is collapsing the distinction between periodontal debridement and implant maintenance procedures, enabling multi-function instruments that reduce cabinet footprint requirements. Large dental service organizations in the United States are standardizing procurement around these consolidated platforms, compressing supplier diversity in high-volume accounts. The structural consequence is margin pressure on single-function device manufacturers unable to integrate into unified delivery architectures.
EPA amalgam separator mandates under the Clean Water Act are forcing waste management retrofits into existing delivery system configurations, requiring separator units with 95% mercury capture efficiency. Installers must reconfigure suction line routing and add secondary containment, increasing project complexity for clinic renovations. California and New York enforcement actions are accelerating compliance timelines beyond original federal deadlines.
Group purchasing organizations are consolidating procurement authority for independent dental practices, displacing direct manufacturer relationships with aggregated contract structures. Dental supply cooperatives in Germany and purchasing alliances in the American Midwest are extracting volume discounts that individual practices cannot replicate. This concentration is most visible in replacement part and consumable categories, where GPO formulary restrictions limit brand selection for member clinics.
Dental Delivery System Market Segmentation
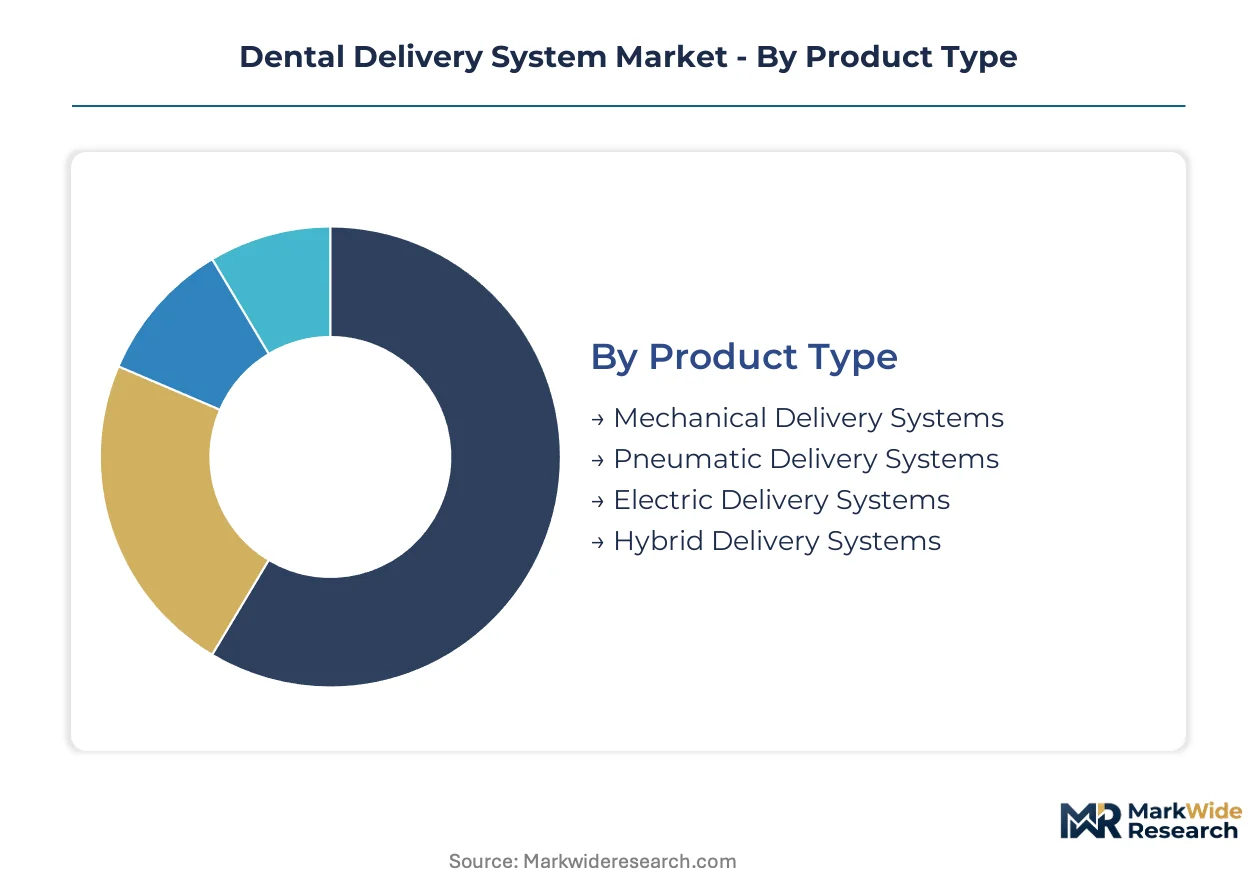
Delivery system architectures diverge sharply in service lifecycle requirements, with electric platforms demanding specialized technician networks that reshape regional distribution strategies. Segmentation reveals how technology transitions fragment procurement patterns across practice types and clinical applications.
Product Type:
After-sales service intensity varies dramatically across propulsion architectures, with electric and hybrid systems requiring certified biomedical technicians that constrain field service coverage in secondary markets.
- Mechanical Delivery Systems:Legacy cam-driven utility management with manual pressure regulation dominates aging installed bases in rural Japanese practices. Replacement parts availability concentrates through original equipment networks as third-party alternatives diminish.
- Electric Delivery Systems:Brushless DC motor platforms deliver torque precision through digital control interfaces with integrated diagnostic feedback. German university hospitals prioritize these configurations for restorative volume, though calibration complexity extends service intervals.
- Pneumatic Delivery Systems:Compressed air turbine infrastructure retains cost advantages for startup clinics in India's tier-2 cities where maintenance ecosystems remain pneumatic-focused.
- Hybrid Delivery Systems:Dual-propulsion architectures bridge pneumatic legacy with electric precision, attracting US dental service organizations seeking phased upgrade pathways without full operatory replacement.
Mechanical systems hold the largest share; momentum sits with electric configurations.
End User:
Procurement authority concentrates differently across customer types, with dental service organizations extracting enterprise pricing that independent clinics cannot replicate.
- Dental Clinics:Outpatient operatories represent the dominant installed base, with infection control mandates from the FDA and CDC accelerating replacement cycles for waterline-compliant configurations. Group purchasing organizations consolidate vendor selection for independent practices.
- Hospitals:Academic medical centers and community hospitals expand dental service lines, driving demand for hybrid systems with centralized utility management. Biomedical engineering departments handle maintenance internally, altering supplier service contract structures.
- Dental Laboratories:Off-site fabrication facilities require delivery systems for model work and prosthetic adjustment, with lower duty cycles than clinical environments.
- Educational Institutions:Dental schools in Japan and Germany prioritize training-platform compatibility with multiple handpiece interfaces, extending equipment refresh timelines.
Dental clinics dominate volume; hospitals are climbing the fastest as service line expansion accelerates.
Application:
Procedure-specific torque and spray requirements fragment platform standardization, with cosmetic workflows demanding precision that justifies premium electric configurations.
- General Dentistry:Restorative and preventive procedures constitute the core utility demand across all delivery architectures, with high-volume practices prioritizing noise reduction and ergonomic hose positioning.
- Cosmetic Dentistry:Veneer preparation and shade-matching workflows require consistent high-speed performance with minimal vibration, concentrating electric system preference in premium US and German practices.
- Orthodontics:Bonding and debonding procedures utilize lower torque ranges, with pneumatic systems remaining viable where orthodontic volume does not justify electric investment.
- Periodontics:Ultrasonic integration and subgingival access drive demand for specialized delivery configurations with enhanced illumination and irrigation control.
General dentistry anchors installed base; cosmetic applications gain share fastest as patient-funded procedures expand.
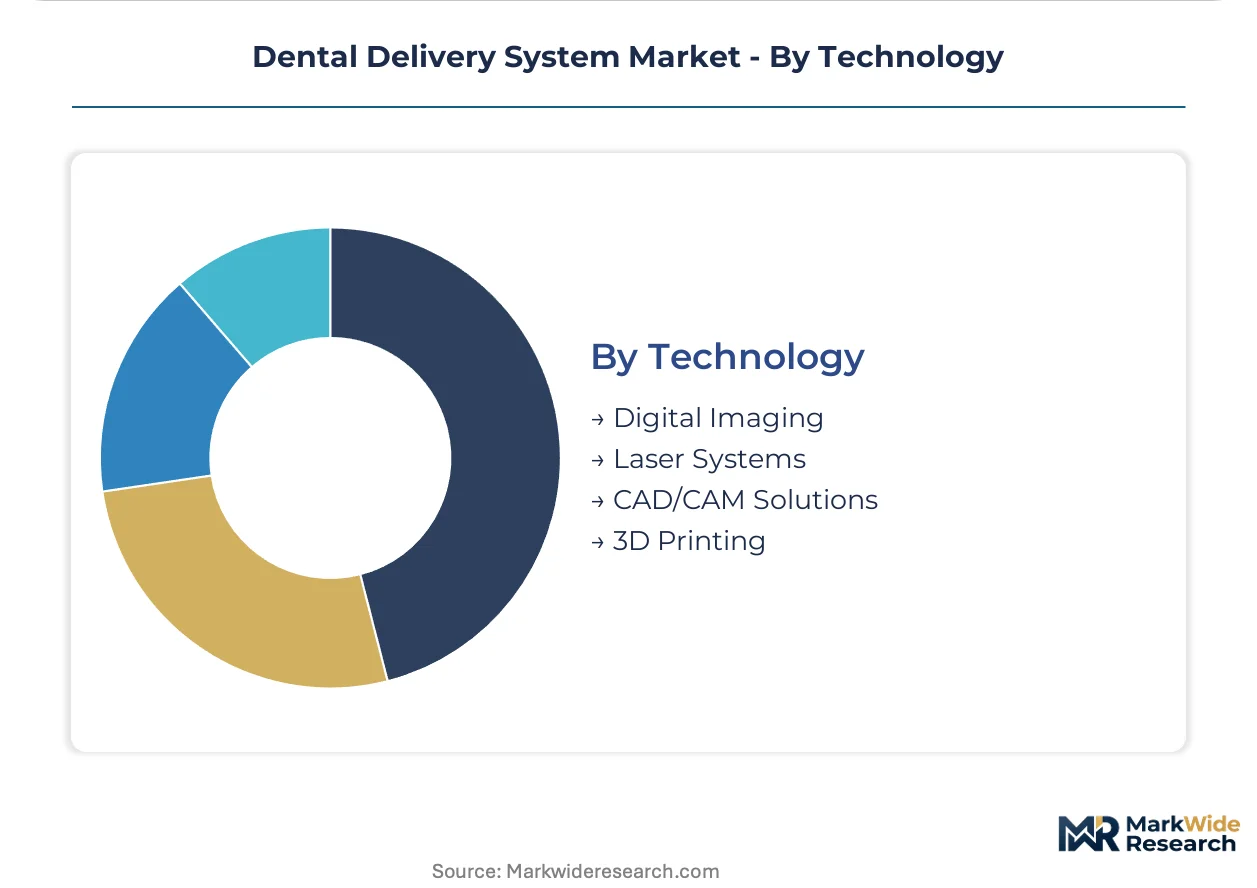
Technology:
Digital convergence dissolves boundaries between utility delivery and diagnostic processing, with CAD/CAM integration commanding premium positioning through same-day restoration workflows.
- CAD/CAM Solutions:Chairside milling and digital impression systems integrate directly with delivery system touchscreens, collapsing traditional mechanical boundaries. German and Japanese practices lead adoption where labor costs justify capital intensity.
- Digital Imaging:Intraoral scanner connectivity requires data ports and display integration that legacy pneumatic cabinets cannot accommodate, forcing renovation decisions.
- Laser Systems:Hard and soft tissue laser handpieces demand specialized electrical and cooling infrastructure, with delivery systems serving as utility nodes for power management and fiber delivery.
- 3D Printing:In-office fabrication for surgical guides and provisional restorations requires resin handling and post-processing utilities that extend delivery system functionality beyond traditional scope.
CAD/CAM solutions command premium positioning; 3D printing represents the steepest expansion trajectory as point-of-care fabrication matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered electric delivery systems to Japanese dental service organizations, establishing a trade corridor that channels advanced torque-control technology into Asia-Pacific upgrade cycles.
United States
FDA 510(k) clearance timelines and CDC waterline sterilization mandates accelerate replacement demand across outpatient dental clinics. The EPA enforces amalgam separator compliance under Clean Water Act provisions, requiring mercury capture retrofits. California and New York enforcement actions compress installation schedules beyond federal deadlines.
Germany
University hospitals in Baden-Württemberg prioritize brushless DC motor platforms for high-volume restorative procedures. The EU MDR framework reclassifies software-enabled diagnostic interfaces as Class IIa medical devices, extending certification burdens. Stuttgart-area fabrication clusters supply precision pressure regulation components to domestic and export markets.
Japan
Over 40% of dental facilities operate equipment exceeding 15 years of service life, concentrating replacement demand in Tokyo and Osaka metropolitan areas. METI industrial standards govern electromechanical safety certification for imported systems. Nagoya-based dental schools extend equipment refresh timelines to maintain training-platform compatibility.
India
Tier-2 cities including Pune, Jaipur, and Lucknow present underpenetrated dental service networks for modular delivery configurations. The country's national medical device regulator enforces quality management protocols that delay market entry for Asian suppliers. Karnataka's medical device manufacturing corridor near Bangalore attracts component sourcing for pneumatic system assembly.
China
Domestic production of compressed air turbine infrastructure retains cost advantages for startup clinics in secondary urban markets. NMPA medical device registration requirements shape import substitution patterns for premium electric configurations. The Yangtze River Delta cluster concentrates final assembly operations for export-oriented manufacturers.
Dental Delivery System Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base organizes around manufacturing scale, ergonomic specialization, and pneumatic legacy expertise. Three archetypes dominate: integrated platform builders, mid-market reliability specialists, and regional fabrication houses. Consolidation pressure intensifies as group purchasing organizations aggregate procurement authority and compress supplier diversity.
Within the integrated platform tier, A-dec Inc. and DENTALEZ, Inc. occupy positions that exemplify divergent strategic vectors. A-dec Inc. anchors premium mechanical system supply for high-volume North American practices. DENTALEZ, Inc. represents mid-market pneumatic configurations that balance acquisition cost against operational reliability. Midmark sits within the ergonomic specialization archetype, reducing clinician fatigue through purpose-built hose positioning and control interface design.
| Leading Market Players |
|---|
| A-dec Inc. |
| DENTALEZ, Inc. |
| Aseptico Inc. |
| Midmark |
| ADS Dental System |
| MGI Healthcare |
| Dental International |
| Olsen |
| Beaverstate Dental Systems |
| Others |
Value Chain & Pricing Dynamics
Copper and aluminum input volatility determines both pricing tier spreads and supply chain shape across dental delivery system manufacturing, compressing margin stability for pneumatic hose sheathing and cabinet housing suppliers while forcing tier-1 manufacturers toward captive sourcing arrangements.
Pricing Analysis
The technology-generation pricing gap separates legacy pneumatic configurations from brushless DC electric platforms and emerging hybrid architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling intensity. Pricing pressure stems from group purchasing organization formulary restrictions that extract volume discounts from independent dental practices. Startup clinics in India's tier-2 cities exhibit highest price sensitivity, while German university hospitals prioritize torque precision over acquisition cost.
Supply Chain Analysis
Upstream feedstock flows for copper sheathing, aluminum housings, and precision pressure regulation components draw from Germany, Japan, and China's Yangtze River Delta manufacturing clusters. Brushless DC motors and digital control interfaces rest on semiconductor sourcing from Taiwan and South Korea. Single-source vulnerability concentrates in precision pressure regulation component fabrication around Stuttgart-area supplier networks. Distribution runs through dental supply cooperatives in Germany and purchasing alliances in the American Midwest that aggregate procurement authority for member clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental delivery system market sits at a platform-economics inflection where CAD/CAM integration and AI-enabled diagnostic interfaces are collapsing traditional mechanical boundaries into unified patient care workflows.
For Market Incumbents: Build certification moats around EU MDR Class IIa software classification for AI-integrated delivery system touchscreens. Deepen backward integration into precision pressure regulation component fabrication to offset Stuttgart-area supplier concentration risk. Anchor hospital system partnerships through biomedical engineering department service contracts that displace traditional field technician networks. For New Entrants and Emerging Players: Mid-market hybrid configurations for US dental service organizations represent the most penetrable entry point, offering phased electric upgrade pathways without full operatory replacement. India's tier-2 cities including Pune and Lucknow present underpenetrated demand for modular pneumatic systems where maintenance ecosystems remain compressed-air focused. Pursue subscription-based equipment leasing structures that bundle maintenance and upgrade pathways to bypass capital purchase friction. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors service-contract-anchored platform builders over single-function device manufacturers. Long-term viability hinges on digital workflow integration depth rather than mechanical utility delivery scale. Monitor EPA enforcement action intensity in California and New York as early signal for amalgam separator retrofit demand inflection. Cross-checking against hospital dental service line expansion rates is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Software Classification Pathway | Positions AI-integrated delivery interfaces as Class IIa medical devices ahead of competitor filings. |
| Hospital System Partnership Program | Captures academic medical center procurement through biomedical engineering department service contracts. |
| Subscription Equipment Leasing Model | Displaces capital purchase patterns among US dental service organizations seeking bundled upgrade pathways. |
| Backward Integration into Motors | Secures brushless DC motor supply against Taiwan and South Korea semiconductor sourcing volatility. |
| Tier-2 City Distribution Buildout | Establishes first-mover positioning in Pune, Jaipur, and Lucknow before competitor network expansion. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement managers, biomedical engineering directors, GPO contracts specialists, and aftermarket service technicians; and secondary validation against FDA 510(k) filings, EPA Clean Water Act enforcement records, EU MDR classification databases, and hospital procurement contract repositories. Bottom-up installation base modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Forecast inputs considered electric-pneumatic technology transition velocity, infection control mandate implementation timelines, and dental service organization consolidation trajectories across the projection horizon. Segmentation dimensions modeled include propulsion architecture, end-user facility type, procedure application, and technology integration level. CAGRs were derived from replacement cycle acceleration patterns and upgrade pathway adoption curves rather than linear extrapolation.
Practitioners should monitor EPA enforcement escalation in additional states, EU MDR software classification precedent rulings, and copper-aluminum commodity volatility for early signals of forecast revision. Cross-checking against dental school equipment refresh timelines and Japanese METI industrial standard updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Units Market
Dental Devices
Dental Curing Lights Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Carpule Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Orthodontics Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Dental Implant Motors Market