
 Dental Aligners Market | 2026-2036
Dental Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Aligners Market Analysis
Premium-grade thermoplastic polyurethane formulations is rotating the Dental Aligners Market toward higher-margin clinical applications. Align Technology leverages proprietary SmartTrack material science to sustain its technology leadership in precision staging. Straumann Group anchors its position through backward integration into intraoral scanning and CAD/CAM software ecosystems. Angelalign Technology dominates Asia-Pacific volume with manufacturing scale and orthodontist-dedicated channel control.
Dental aligners are removable orthodontic appliances fabricated from medical-grade multilayer thermoplastic polymers, typically 0.5–1.0 mm thick, engineered to deliver controlled sequential tooth movement through calibrated force application. Clear aligners command the largest revenue pool as aesthetic preference drives patient self-selection, while hybrid aligners capture margin from complex malocclusion cases requiring auxiliary fixed components. Subscription model delivery is expanding fastest among direct-to-consumer entrants, though in-office delivery sustains higher clinical oversight and reimbursement capture. Adult age group demand outpaces teenagers in developed markets where discretionary orthodontic spending rises with disposable income.
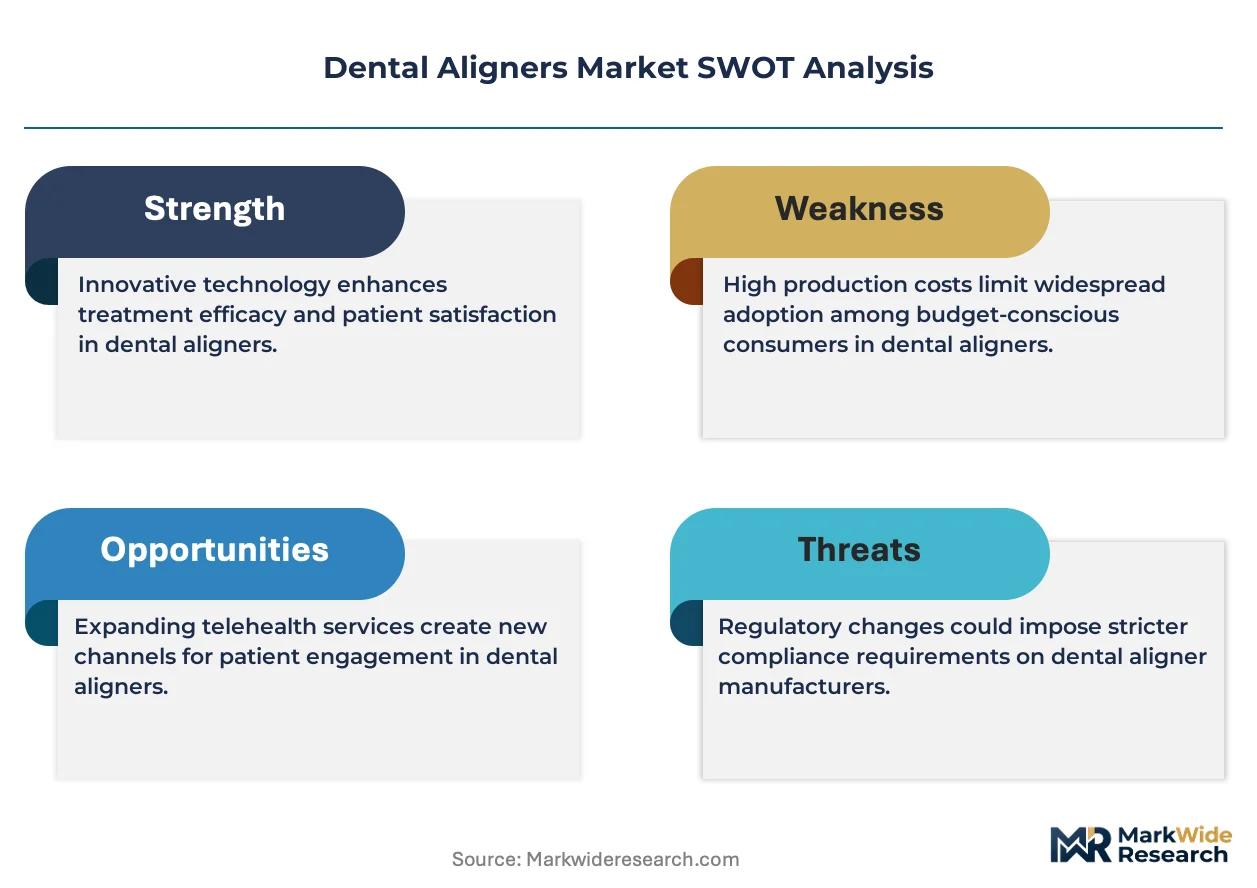
FDA 510(k) premarket notification and EU MDR Class IIa conformity requirements shape product development timelines and clinical evidence thresholds for aligner manufacturers. ISO 13485 quality management systems and state dental board regulations in the United States govern manufacturing consistency and direct-to-patient distribution legality. Stakeholders must monitor evolving teledentistry licensure rules and reimbursement code expansions as virtual treatment planning displaces traditional chair-hour economics.
Market Dynamics
The dental aligners market is being restructured by the tension between orthodontist-controlled in-office delivery and direct-to-consumer teledentistry platforms, with regulatory arbitrage determining which channel captures patient volume.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for thermoplastic orthodontic devices reduces time-to-market for new entrants, expanding manufacturer participation in the United States.
- Adult cosmetic dentistry demand:Discretionary orthodontic spending among professionals aged 25-45 drives premium clear aligner adoption as workplace appearance standards intensify.
- Polymer science advances:Multilayer thermoplastic polyurethane formulations enable more precise force calibration, improving clinical outcomes for complex malocclusion cases.
Market Restraints
- Raw material concentration:Medical-grade TPU resin supply concentrates among German and US specialty chemical producers, creating input cost volatility for aligner fabricators.
- Clinical scope limitations:Severe skeletal discrepancies and certain vertical dimension cases remain outside aligner biomechanical capability, forcing hybrid treatment with fixed appliances.
- EU MDR compliance burden:Class IIa device conformity assessment under the Medical Device Regulation extends certification timelines and elevates clinical evidence requirements for European market access.
Strategic Opportunities
- India orthodontic underpenetration:Low aligner adoption relative to malocclusion prevalence creates volume expansion potential as disposable income rises in metropolitan centers.
- AI-driven treatment planning:Machine learning convergence with intraoral scanning automates staging algorithms, reducing orthodontist chair time per case.
- Subscription direct-to-consumer models:Remote monitoring platforms bypass traditional clinic infrastructure, capturing price-sensitive segments in Germany and Australia.
Industry Challenges
- Orthodontist workforce constraints:Limited residency training slots in the United States and United Kingdom create specialist bottlenecks for in-office aligner delivery scaling.
- Teledentistry licensure fragmentation:State-level dental board regulations in the United States create compliance complexity for interstate virtual treatment platforms.
- ISO 13485 audit intensity:Quality management system maintenance demands continuous manufacturing documentation, straining mid-cap aligner producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Aligners Market |
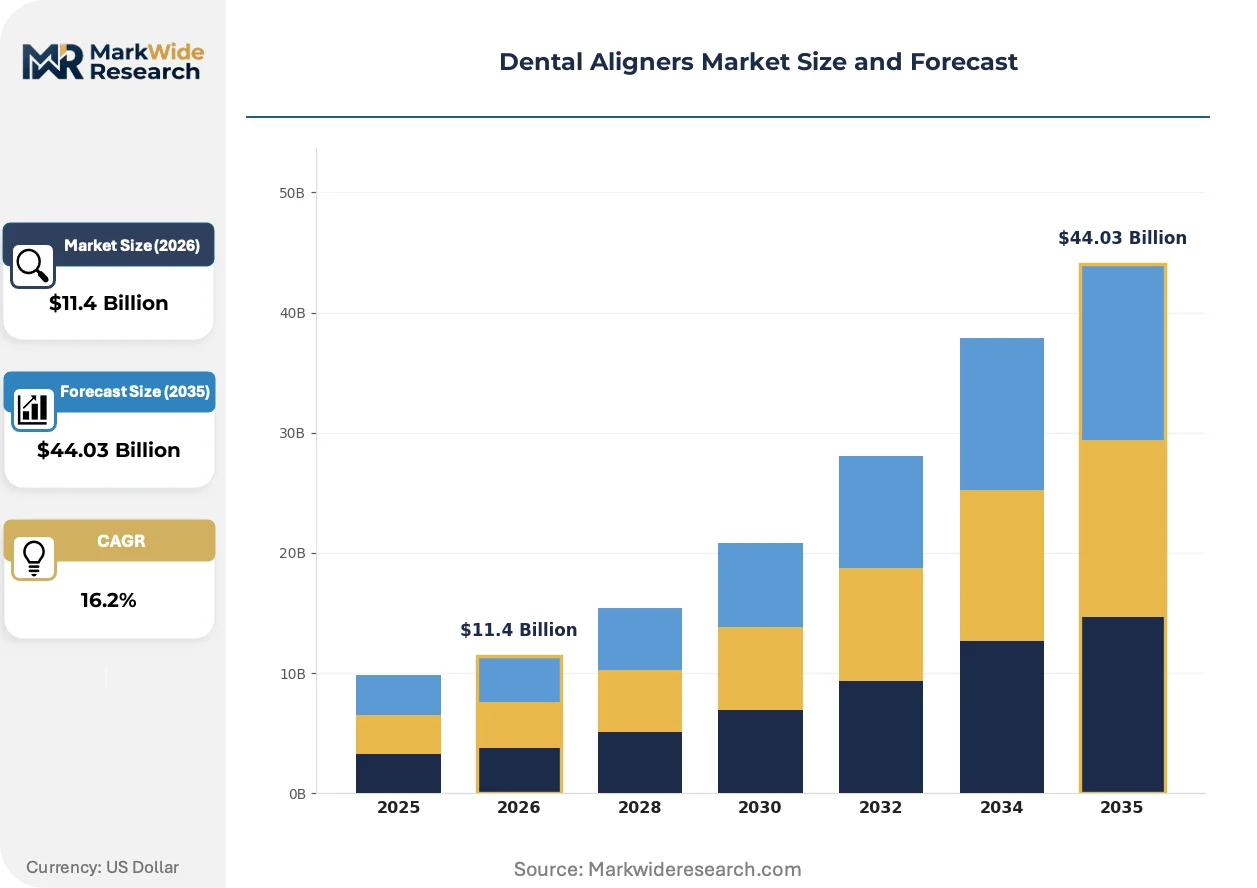
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $44.03 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Removable Aligners, Fixed Aligners, Hybrid Aligners End User: Orthodontists, General Dentists, Cosmetic Dentists, Clinics Delivery Mode: Direct Shipping, In-Office Delivery, Online Order, Subscription Model Age Group: Teenagers, Adults, Seniors, Others |
| Companies Covered | Straumann Group, Angelalign Technology, Align Technology, Argen Corporation, Ormco Corporation, Dentsply Sirona, 3Shape, TP Orthodontics, Envista Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Aligners Market Emerging Trajectories
Digital workflow integration is compressing the traditional orthodontic supply chain, with software-defined treatment planning displacing analog impression and manual staging processes.
AI-powered predictive biomechanics is fragmenting the aligner fabrication landscape. Machine learning models simulate tooth movement trajectories across millions of prior cases, reducing reliance on orthodontist intuition for staging design. Clear aligner manufacturers in the United States and China are deploying these tools to accelerate case throughput. The technology is fragmenting competitive advantage away from clinical experience toward data asset scale.
EU MDR post-market surveillance requirements are tightening clinical evidence obligations for orthodontic device manufacturers. Manufacturers must now maintain systematic complaint databases and periodic safety update reports across their product portfolios. German and French notified bodies are enforcing stricter biocompatibility testing protocols for thermoplastic materials. Mid-sized aligner producers are responding by consolidating regulatory affairs functions and outsourcing clinical evaluation to specialized CROs.
Patient acquisition economics are compressing as direct-to-consumer brands unbundle after-sales monitoring from initial treatment packages. Subscription models in Australia and Canada now separate aligner fabrication from remote progress tracking, allowing patients to purchase monitoring services à la carte. This unbundling is most visible among millennial demographics seeking cost transparency. Traditional orthodontist practices are countering with bundled lifetime retention guarantees to defend patient lifetime value.
Dental Aligners Market Segmentation
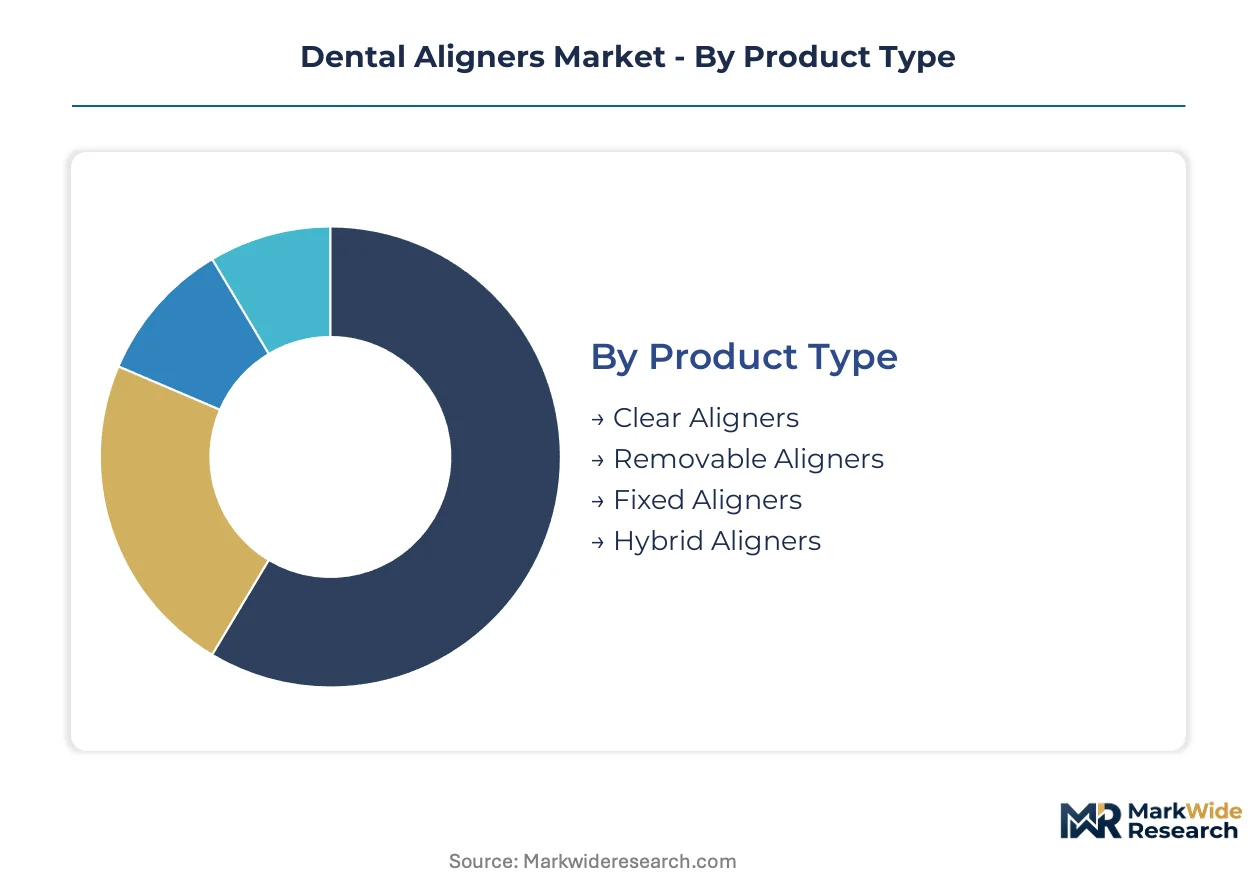
Dental aligner segmentation reveals how clinical complexity, channel economics, and patient demographics fragment purchasing behavior. Manufacturers must calibrate material science investments and regulatory compliance across divergent use cases.
Product Type:
Clear aligners face the most intense substitution pressure from hybrid systems as orthodontists seek biomechanical solutions for previously intractable malocclusions.
- Clear Aligners:Medical-grade multilayer thermoplastic polyurethane constructs deliver sequential force application through transparent 0.5–1.0 mm shells. Demand concentrates among adult professionals in the United States and Germany where workplace appearance standards drive aesthetic self-selection, though polymer resin supply volatility from German specialty chemical producers creates margin pressure.
- Hybrid Aligners:Combined fixed-removable systems integrate temporary anchorage devices or auxiliary brackets with clear aligner staging for skeletal discrepancy cases. Orthodontists in China and the United States deploy these for vertical dimension challenges, capturing premium pricing from complex malocclusion patients outside pure aligner capability.
- Removable Aligners:Single-material thermoplastic appliances without fixed components serve mild-to-moderate crowding cases.
- Fixed Aligners:Bonded ceramic or lingual systems with limited removability address compliance-resistant teenagers.
Clear aligners anchor the volume base while hybrid aligners gain share at the steepest rate.
End User:
Cost tier stratification separates high-touch orthodontic specialists from volume-oriented general practitioners.
- Orthodontists:Residency-trained specialists control complex case staging and retention protocols, commanding premium fees for in-office delivery with direct intraoral scanning. FDA 510(k) pathway familiarity and CE marking fluency enable faster adoption of next-generation materials.
- General Dentists:Primary care providers with limited orthodontic training capture mild malocclusion cases through simplified treatment planning software, expanding aligner access in underserved United States metropolitan markets where specialist density remains low.
- Cosmetic Dentists:Aesthetic-focused practitioners bundle aligners with whitening and veneer procedures.
- Clinics:Multi-chair corporate dentistry chains standardize aligner protocols across locations.
Orthodontists dominate revenue per case while general dentists expand the addressable patient pool most rapidly.
Delivery Mode:
Channel maturity divides established in-office workflows from emerging direct-to-consumer platforms.
- In-Office Delivery:Chair-side intraoral scanning, physical impression taking, and direct orthodontist oversight sustain higher reimbursement capture and clinical liability control. German and United States practices defend this model through bundled retention guarantees.
- Subscription Model:Remote monitoring platforms separate aligner fabrication from progress tracking, allowing à la carte service selection. Australian and Canadian millennials drive adoption through cost transparency preferences.
- Direct Shipping:Mail-order impression kits bypass clinical infrastructure entirely.
- Online Order:E-commerce platforms with teledentistry consultation layers.
In-office delivery retains the highest patient lifetime value while subscription models are climbing the fastest among price-sensitive segments.
Age Group:
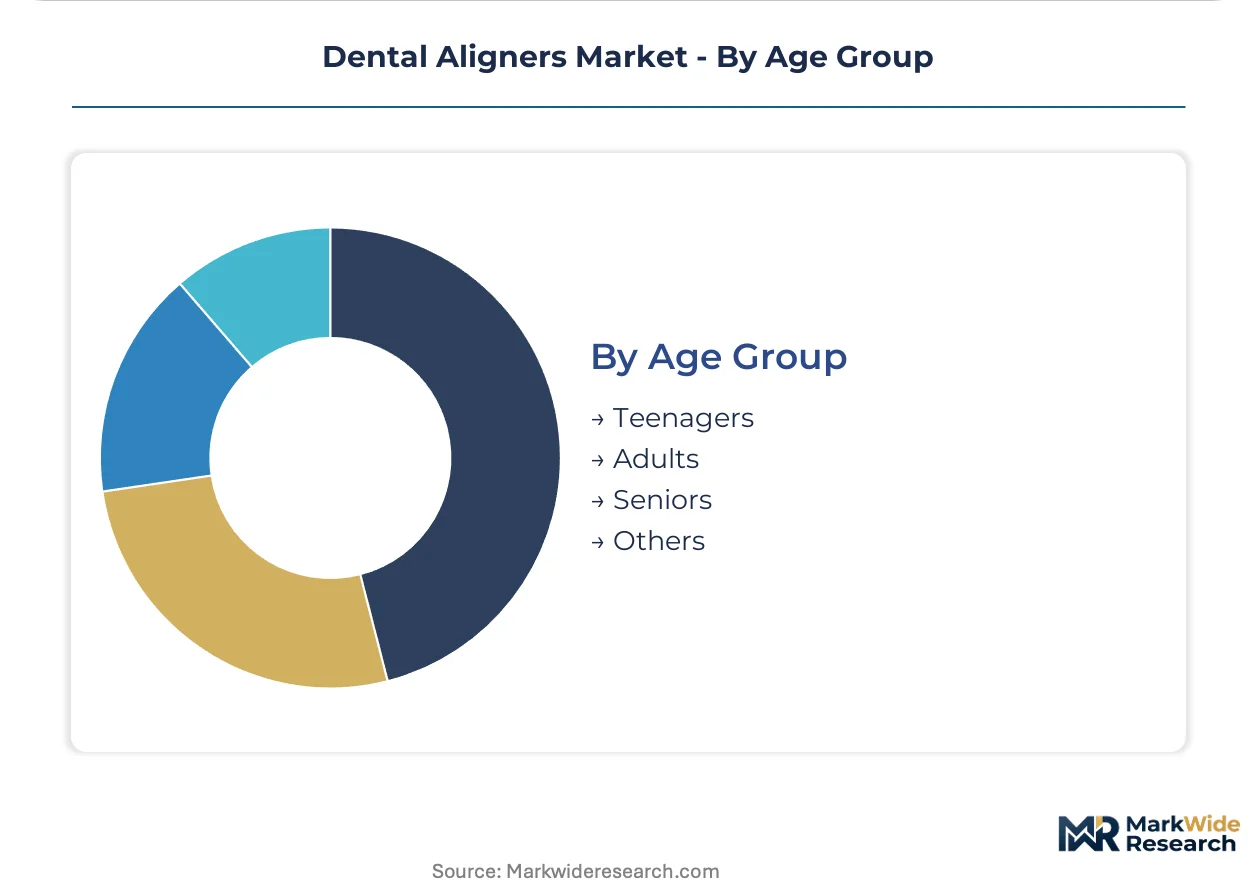
Customer type segmentation aligns treatment complexity with physiological constraints and compliance capacity.
- Adults:Professionals aged 25-45 with discretionary orthodontic spending drive premium clear aligner demand in developed markets, particularly where workplace appearance standards intensify and disposable income supports out-of-pocket cosmetic investment.
- Teenagers:Compliance-dependent patients with active growth modification potential require parental consent frameworks and school-schedule accommodation, concentrating demand in United States suburban markets with high orthodontic specialist density.
- Seniors:Periodontally compromised patients with restorative needs.
- Others:Pediatric pre-orthodontic interceptive cases and transitional mixed dentition.
Adults generate the highest revenue per patient while teenagers represent the largest untreated malocclusion population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade thermoplastic resin supply chains concentrate among German and US specialty chemical producers, while aligner fabrication and clinical delivery gravitate toward markets with dense orthodontic specialist networks and favorable direct-to-consumer regulatory frameworks.
United States
FDA 510(k) premarket notification pathways accelerate product commercialization timelines for domestic manufacturers. State dental board regulations govern teledentistry licensure and direct-to-patient distribution legality, creating compliance complexity for interstate virtual treatment platforms. Orthodontic specialist density peaks in suburban metropolitan corridors across California, Texas, and the Northeast Corridor, where discretionary cosmetic spending sustains premium in-office delivery models.
Germany
EU MDR Class IIa conformity assessment requirements extend certification timelines and elevate clinical evidence thresholds for European market access. Notified bodies in Berlin and Munich enforce stricter biocompatibility testing protocols for thermoplastic materials. The Rhine-Ruhr and Bavarian industrial clusters host precision polymer processing capabilities that feed aligner fabrication supply chains across the continent.
China
Angelalign Technology anchors Asia-Pacific volume through manufacturing scale and orthodontist-dedicated channel control. NMPA medical device registration requirements shape product development timelines for domestic and imported aligner systems. The Yangtze River Delta and Pearl River Delta concentrate intraoral scanning device production and CAD/CAM software development talent pools.
India
Low aligner adoption relative to malocclusion prevalence creates volume expansion potential as disposable income rises in Mumbai, Delhi, and Bangalore metropolitan centers. CDSCO medical device regulations govern import and domestic manufacturing compliance for clear aligner systems. Orthodontic specialist training programs in Maharashtra and Karnataka are scaling residency slots to address workforce constraints for in-office delivery.
Australia
TGA medical device conformity requirements align with EU MDR standards for thermoplastic orthodontic appliance market access. Subscription direct-to-consumer models separate aligner fabrication from remote progress tracking, capturing millennial demand through cost transparency preferences. Sydney and Melbourne orthodontic practices defend patient lifetime value through bundled retention guarantees against remote monitoring platforms.
Dental Aligners Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary material science and manufacturing scale separating premium positioning from volume capture. The vendor base consolidates around integrated software-hardware ecosystems and specialized polymer fabrication capabilities. Three archetypes dominate: vertically integrated platform owners controlling scanning-to-aligner workflows, regional volume manufacturers leveraging orthodontist channel relationships, and component suppliers feeding third-party fabricators. Competitive moves concentrate on backward integration into intraoral scanning and strategic partnerships with orthodontic specialist networks.
Among US-based platform owners, Align Technology exemplifies technology leadership through proprietary material science investments, while Straumann Group anchors the integrated ecosystem archetype through scanning and CAD/CAM software control. Angelalign Technology represents the Asia-Pacific volume manufacturer archetype, occupying a position defined by manufacturing scale and dedicated orthodontist channel relationships rather than technology licensing.
| Leading Market Players |
|---|
| Straumann Group |
| Angelalign Technology |
| Align Technology |
| Argen Corporation |
| Ormco Corporation |
| Dentsply Sirona |
| 3Shape |
| TP Orthodontics |
| Envista Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German specialty chemical producers and major aligner fabricators lock in medical-grade thermoplastic polyurethane resin access while anchoring price visibility against raw material volatility. These contractual structures concentrate procurement power among scaled manufacturers while forcing mid-tier players into spot-market exposure.
Pricing Analysis
FDA 510(k) and EU MDR Class IIa certification tiers dictate the pricing tier structure across the Dental Aligners Market. Three-tier pricing structure across premium, standard, and economy levels separates orthodontist-supervised in-office delivery from remote-monitored subscriptions and direct-to-consumer mail-order kits. Price differentiation stems from clinical oversight intensity and polymer formulation complexity. Cost compression in the subscription tier is intensifying because direct-to-consumer brands unbundle monitoring from fabrication. Price-sensitive millennials in Australia and Canada drive economy-tier volume, while US and German professionals aged 25-45 show lowest sensitivity to premium positioning.
Supply Chain Analysis
Inventory cycles for medical-grade TPU resin run 8-12 weeks from German and US specialty chemical producers to aligner fabrication facilities in China and the United States. Raw material inputs draw from Bayer Covestro and Lubrizol polymer science divisions, intraoral scanning hardware from 3Shape and Align Technology, and CAD/CAM software licenses from dental technology platforms. Single-source vulnerability concentrates in thermoplastic polyurethane resin supply, where three producers control global medical-grade output. Distribution runs through orthodontist-dedicated channel partners in developed markets and direct-to-consumer logistics platforms in price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dental Aligners Market sits at a platform-economics inflection where software-defined treatment planning ecosystems are displacing analog orthodontic workflows. Interoperability between intraoral scanning hardware and AI-driven staging algorithms now determines competitive viability more than clinical experience accumulation.
For Market Incumbents: Consolidate backward integration into intraoral scanning hardware and CAD/CAM software stacks to defend against pure-play teledentistry platforms unbundling clinical oversight. Lock in exclusive orthodontist channel partnerships through bundled retention guarantees and continuing education sponsorships. Prioritize ISO 13485 quality system investments to maintain certification tier advantages as EU MDR post-market surveillance tightens. For New Entrants and Emerging Players: Anchor in India's metropolitan orthodontic markets where specialist density remains low and disposable income trajectories favor premium positioning. Target general dentist practices in underserved US suburban corridors with simplified treatment planning interfaces that reduce training burden. Pursue white-label manufacturing partnerships with established polymer fabricators to bypass resin supply bottlenecks. For Investors and Strategic Acquirers: AI-augmented treatment planning specialists with proprietary biomechanical simulation datasets represent the most defensible acquisition archetype. Platform economics favor scaled data assets over clinical brand equity across the projection horizon. Monitor teledentistry licensure harmonization across US state dental boards as the signal indicating direct-to-consumer channel viability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SmartTrack Material Licensing | Proprietary thermoplastic formulations sustain margin capture against commodity resin competitors. |
| AI Treatment Planning Integration | Machine learning staging algorithms reduce orthodontist chair time per case throughput. |
| Orthodontist Channel Partnerships | Dedicated specialist networks defend patient lifetime value against remote monitoring platforms. |
| EU MDR Certification Investment | Class IIa conformity assessment enables premium positioning in German and French markets. |
| Direct-to-Consumer Subscription Launch | Remote monitoring platforms capture price-sensitive segments in Australia and Canada. |
Methodological Framework
A standing panel of orthodontic practice owners, dental laboratory technicians, polymer procurement managers, and regulatory affairs specialists provided ongoing calibration across primary fieldwork and secondary validation. Orthodontic residency program directors and GPO contracts managers supplemented clinical delivery perspectives. Secondary sources included FDA 510(k) premarket notification databases, EU MDR notified body conformity assessments, CMS Medicare orthodontic reimbursement filings, and hospital procurement database extracts. Bottom-up case volume estimates triangulated against top-down market sizing from polymer resin consumption patterns.
Outputs were validated against external benchmarks including orthodontic specialist workforce density surveys, intraoral scanning device shipment disclosures, and teledentistry platform patient acquisition metrics. Segmentation modeling spanned product type, delivery mode, end user credentialing, and age group demographics across the projection horizon. CAGRs derived from polynomial trend fitting to historical case volume data, calibrated against disposable income elasticity estimates and regulatory approval timeline distributions.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) pathway timelines and unaltered EU MDR Class IIa requirements; material deviation in teledentistry licensure or polymer supply concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Dental Floss Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Dental Needle Market
Dental Devices
Dental CAD Market
Dental Devices
Dental Contouring Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Apex Locator Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Units Market
Dental Devices
Dental Etching Liquid Market