
 Demerol (Meperidine) Market | 2026-2036
Demerol (Meperidine) Market Size, Share, and Industry Trends Forecast 2026-2036
Demerol (Meperidine) Market Analysis
The manufacturing scale gap between large sterile injectable producers and regional compounders is unwinding competitive stability in parenteral opioid supply. Pfizer Inc. leverages vertical integration across active pharmaceutical ingredient synthesis and finished dosage form production to sustain contract reliability with institutional purchasers. Hikma Pharmaceuticals USA Inc. anchors its position through dedicated sterile manufacturing infrastructure and US-based distribution networks. Mallinckrodt Pharmaceuticals competes via specialized controlled-substance handling capabilities and DEA quota access.
Demerol (meperidine hydrochloride) is a synthetic opioid analgesic of the phenylpiperidine class, formulated as an injectable solution at concentrations of 25 mg/mL and 50 mg/mL, with tablet and oral solution variants, primarily indicated for moderate to severe pain management in monitored clinical settings. Injectable formulations dominate volume throughput in hospital pharmacies due to rapid onset requirements in perioperative and obstetric applications, while tablet and oral solution segments serve limited ambulatory transitions. The therapy area segmentation reveals postoperative pain management as the mature revenue core, with labor pain applications representing a contracting niche amid safety concerns and alternative analgesic protocols.
FDA scheduling under Controlled Substances Act Schedule II shapes distribution architecture, prescribing limits, and inventory tracking obligations for all market participants. DEA quota allocations for raw meperidine production directly constrain manufacturing output and create supply rigidity that amplifies procurement risk for hospital formularies. Stakeholders must monitor evolving opioid stewardship guidelines and institutional protocol shifts that continue to displace meperidine with alternative analgesics in standard order sets.
Market Dynamics
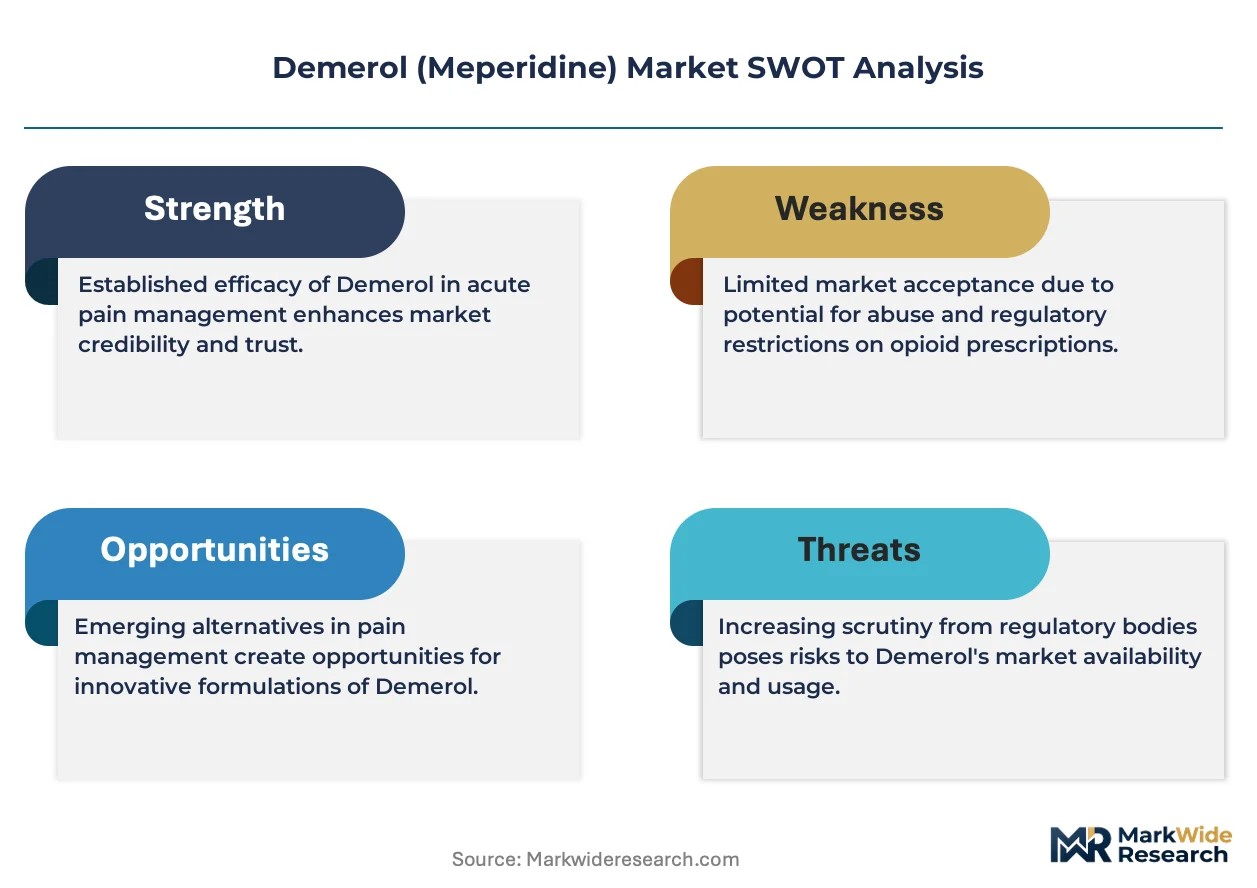
DEA quota allocations for raw meperidine production create rigid supply ceilings that amplify procurement volatility for hospital formularies dependent on this Schedule II controlled substance.
Growth Catalysts
- Postoperative analgesia protocol persistence:Surgical units in US hospital systems continue to stock meperidine for patients with documented morphine intolerance, sustaining baseline demand despite protocol evolution.
- Obstetric anesthesia niche retention:Labor and delivery departments specify meperidine for specific maternal pain profiles where rapid onset and short duration align with delivery timelines.
- Controlled substance infrastructure utilization:Existing DEA-registered vaults, dual-lock storage systems, and waste tracking protocols in institutional pharmacies lower incremental compliance costs for meperidine stocking.
Market Restraints
- API supply concentration:Synthesis of meperidine precursor chemicals concentrates among a limited set of specialized chemical manufacturers, creating single-source vulnerability.
- Serotonergic toxicity liability:The risk of serotonin syndrome when combined with MAO inhibitors or SSRIs restricts prescribing flexibility and elevates malpractice exposure.
- Morphine and fentanyl protocol dominance:These alternatives occupy standard order sets in perioperative pain management, compressing meperidine to rescue-line indications.
Strategic Opportunities
- Specialty compounding partnerships:Hospital networks can secure volume-commitment contracts with 503B outsourcing facilities for patient-specific concentrations unavailable from commercial manufacturers.
- Palliative care formulary expansion:Hospice settings present untapped utility for meperidine's favorable profile in renal impairment cases where active metabolite accumulation threatens morphine safety.
- DEA quota trading mechanisms:Formalized transfer protocols between registered manufacturers could redistribute unused production allowances to match regional demand spikes.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians with controlled-substance handling clearances command premium wages and experience elevated turnover.
- Legacy EHR integration friction:Electronic health record systems require manual workaround configurations to accommodate meperidine's unique dosing alerts and drug interaction flags.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demerol (Meperidine) Market |
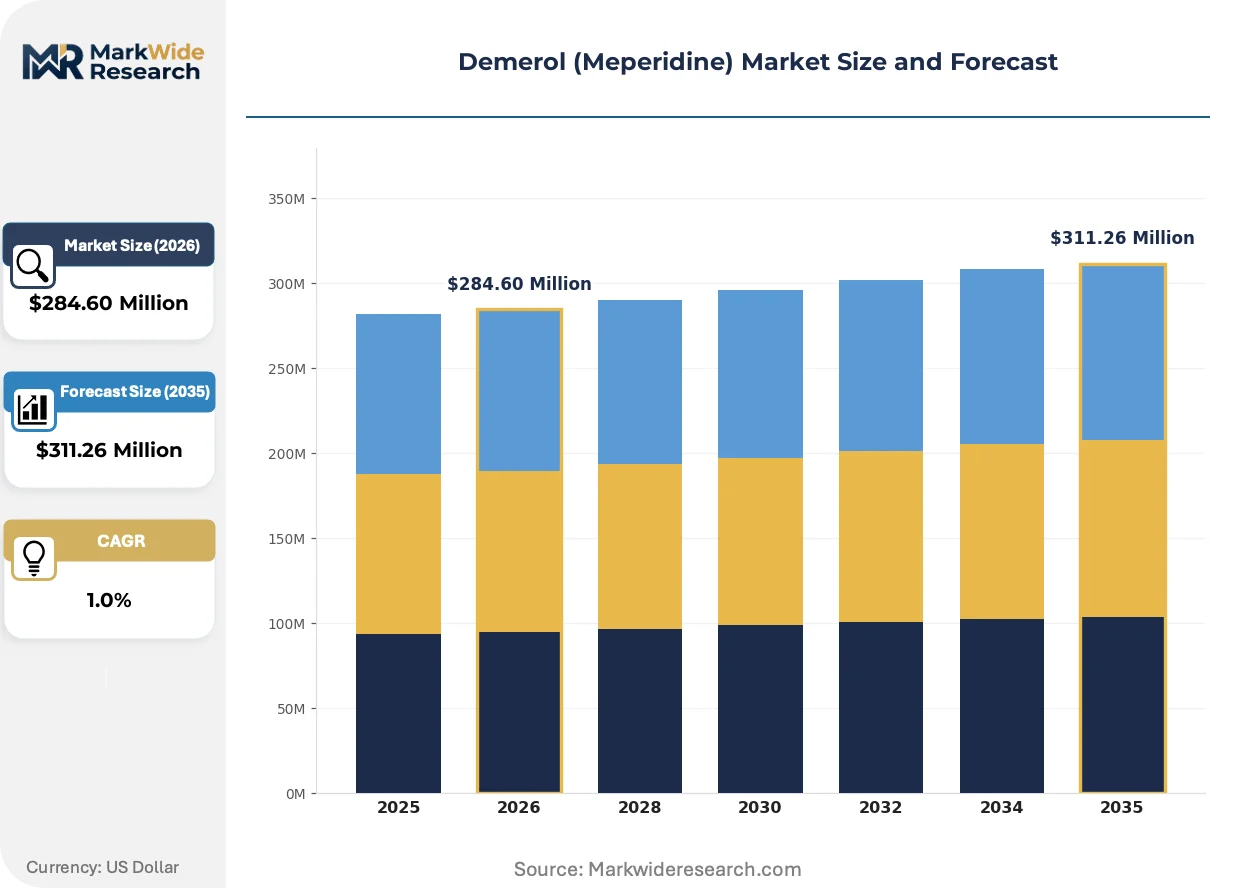
| Market Size in 2026 | $284.60 Million |
| Market Size in 2035 | $311.26 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Tablet, Oral Solution, Concentrate Therapy Area: Postoperative Pain, Acute Pain, Chronic Pain, Labor Pain Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Clinics, Home Care, Palliative Care |
| Companies Covered | Hikma Pharmaceuticals USA Inc., Pfizer Inc., Vintage Pharmaceuticals Inc., Epic Pharma Inc., Boehringer Ingelheim, Sanofi, Mallinckrodt Pharmaceuticals, Sun Pharmaceutical, Sandoz (Novartis AG), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demerol (Meperidine) Market Emerging Trajectories
Institutional opioid stewardship programs are actively rewriting analgesic protocols, creating structural pressure on legacy synthetic opioids while opening avenues for specialized manufacturing partnerships.
Multi-modal analgesia protocols incorporating regional nerve blocks and non-opioid adjuvants are supplanting meperidine in standard perioperative order sets. Academic medical centers in the US Northeast have accelerated this transition, completing formulary reviews that relegate meperidine to restricted-access status. The shift compresses volume throughput for sterile injectable manufacturers while elevating contract importance for remaining institutional purchasers.
FDA's enhanced Risk Evaluation and Mitigation Strategy requirements for extended-release opioids have tightened documentation standards across all Schedule II analgesics. Manufacturers now face expanded pharmacovigilance obligations that extend to distributor and dispenser reporting chains. Hospital pharmacies are responding by consolidating controlled-substance suppliers to reduce audit complexity and streamline compliance documentation.
Hospital purchasing cooperatives are consolidating opioid procurement through single-source agreements that bundle meperidine with higher-volume fentanyl and hydromorphone contracts. Group purchasing organizations negotiate these arrangements, displacing direct manufacturer relationships for independent community hospitals. The concentration is most visible in the US Midwest and Southeast, where regional health systems have merged pharmacy operations under unified formularies.
Demerol (Meperidine) Market Segmentation
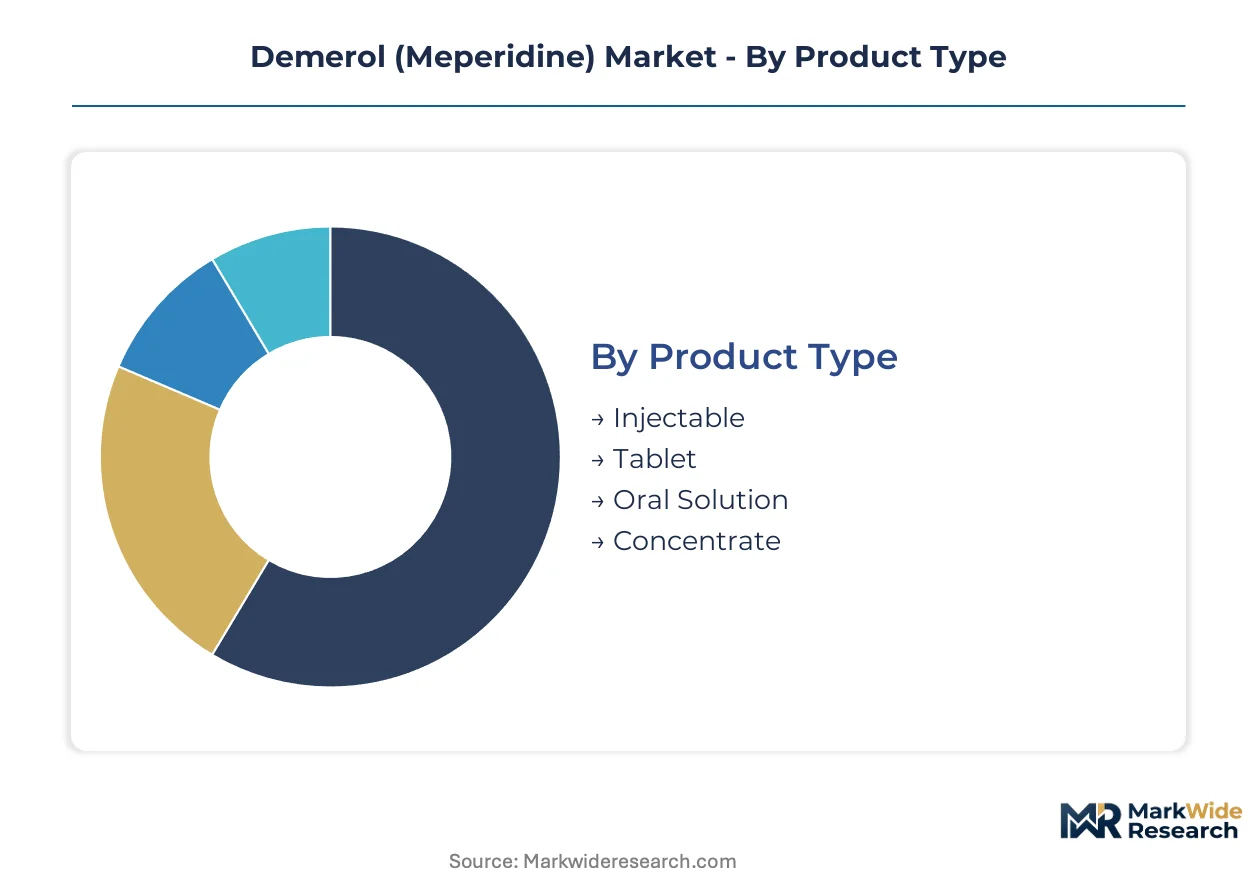
Demerol market segmentation reveals how regulatory constraints and clinical utility reshape procurement patterns across formulation types and care settings. Hospital formularies drive volume concentration toward injectable formats, while therapy area fragmentation exposes meperidine's narrowing therapeutic niche.
Product Type:
Injectable formulations dominate US hospital procurement, while tablet and oral variants serve limited ambulatory discharge protocols.
- Injectable:Sterile solutions at 25 mg/mL and 50 mg/mL concentrations enable rapid onset for perioperative and obstetric applications. Hospital pharmacies in the US Northeast and Southeast concentrate procurement here due to protocol persistence for morphine-intolerant patients.
- Tablet:Oral solid dosage forms facilitate short-term ambulatory transitions from inpatient care. Demand clusters in Medicare-served populations where cost-conscious discharge planning favors oral over parenteral routes.
- Oral Solution:Liquid formulations address swallowing difficulties in geriatric and palliative populations.
- Concentrate:High-potency preparations require dilution prior to administration for precise titration in critical care.
Injectable holds the largest share; momentum sits with oral solution as palliative formulary expansion accelerates.
Therapy Area:
Cost tier differentiation separates mature postoperative applications from emerging palliative opportunities where reimbursement structures favor alternative analgesics.
- Postoperative Pain:Surgical recovery protocols represent the established revenue base for meperidine despite displacement by multimodal regimens. US academic medical centers retain restricted-access stocking for documented morphine allergies.
- Labor Pain:Obstetric anesthesia applications are contracting as safety concerns and fentanyl protocol adoption reshape maternal analgesia standards.
- Acute Pain:Emergency department and trauma settings utilize meperidine for rapid-onset requirements in monitored environments.
- Chronic Pain:Long-term prescribing faces heightened scrutiny under CDC opioid guidelines and DEA diversion monitoring.
Postoperative pain commands current volume; palliative care represents the steepest expansion trajectory as renal impairment protocols evolve.
Delivery Mode:
Volume throughput concentrates in parenteral routes where hospital infrastructure and controlled-substance handling protocols create switching costs.
- Intravenous:Direct vascular administration achieves peak plasma concentrations within minutes for perioperative and critical care applications. US hospital systems standardize IV meperidine in automated dispensing cabinets.
- Intramuscular:Deep muscle injection serves settings lacking IV access or requiring prolonged absorption profiles.
- Subcutaneous:Continuous infusion pumps in hospice settings exploit meperidine's favorable pharmacokinetics in renal impairment.
- Oral:Gastrointestinal absorption exhibits significant first-pass metabolism, limiting bioavailability for ambulatory pain management.
Intravenous delivery anchors institutional procurement; subcutaneous infusion gains share fastest in palliative care network expansion.
End User:
Customer type segmentation exposes the infrastructure gap between capital-equipped hospital systems and resource-constrained outpatient settings.
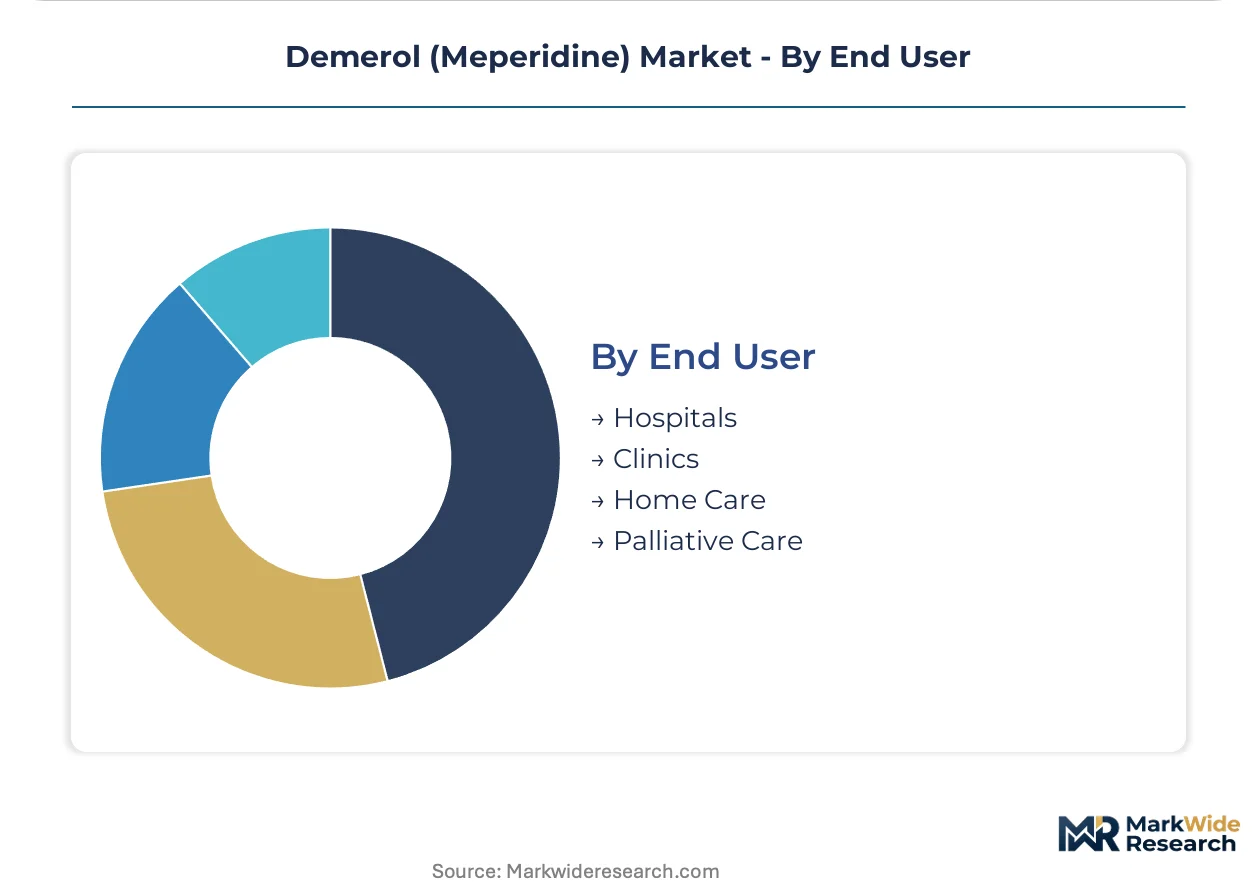
- Hospitals:Integrated delivery networks command procurement volume through DEA-registered vaults, waste tracking systems, and formulary committees. US health systems in the Midwest and Southeast consolidate purchasing through group contracting.
- Palliative Care:Hospice agencies exploit meperidine's short half-life and renally cleared metabolite profile for end-of-life pain management.
- Clinics:Ambulatory surgical centers face DEA registration burdens and inventory tracking costs that limit controlled-substance stocking.
- Home Care:Residential administration requires specialized nursing oversight and secure storage protocols that constrain market penetration.
Hospitals retain dominant procurement share; palliative care climbs fastest as hospice formulary protocols recognize meperidine's renal safety advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in the United States exhibit the lowest price elasticity, absorbing premium sterile injectable costs to secure DEA-compliant supply chains, while Canadian institutional buyers demonstrate greater sensitivity to cross-border pricing arbitrage opportunities.
United States
Academic medical centers in Massachusetts and New York sustain meperidine stocking for morphine-intolerant surgical protocols. FDA Schedule II requirements under the Controlled Substances Act mandate dual-lock vault infrastructure and real-time inventory tracking through the Automated Reports and Consolidated Orders System. The Philadelphia-Baltimore corridor concentrates sterile manufacturing capacity where Pfizer and Hikma anchor parenteral opioid production.
Canada
Provincial health authorities in Ontario and Quebec negotiate meperidine procurement through centralized tender processes that prioritize cost containment over brand loyalty. Health Canada scheduling under the Narcotic Control Regulations aligns with international controlled-substance standards but permits greater formulary flexibility than US protocols. The Greater Toronto Area hosts distribution hubs serving hospital networks across the Prairie Provinces.
Germany
University hospitals in Bavaria and North Rhine-Westphalia retain meperidine for specialized anesthesia applications where rapid metabolite clearance benefits renal-compromised patients. EMA pharmacovigilance requirements under the Good Manufacturing Practice framework impose batch-level traceability obligations on sterile injectable importers. The Frankfurt-Rhine-Main logistics cluster facilitates controlled-substance distribution throughout Central Europe.
Switzerland
Cantonal hospital systems in Zurich and Geneva maintain restricted-access meperidine formularies for obstetric and palliative indications. Swissmedic oversight of narcotic pharmaceuticals emphasizes prescriber certification renewal and patient-specific dispensing documentation. The Basel pharmaceutical corridor connects sterile manufacturing expertise with Alpine region distribution networks.
United Kingdom
NHS Trusts in London and the Southeast face formulary pressure from opioid stewardship programs that relegate meperidine to second-line status. The Misuse of Drugs Act 1971 and subsequent regulations enforce Home Office licensing for Schedule II substance handling. The Manchester-Leeds corridor concentrates hospital pharmacy procurement decisions for Northern England networks.
Demerol (Meperidine) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with three to four manufacturers commanding institutional contract volume through DEA quota access and sterile infrastructure scale. The specialist tier comprises regional compounders and 503B outsourcing facilities serving patient-specific concentration requirements. Dominant archetypes include vertically integrated pharmaceutical conglomerates, dedicated sterile injectable specialists, and controlled-substance handling experts. Competitive dynamics center on quota security through manufacturing partnerships and formulary consolidation via group purchasing organization alignment.
Among US-based manufacturers, Hikma Pharmaceuticals USA Inc., Pfizer Inc., and Mallinckrodt Pharmaceuticals occupy positions reflecting distinct strategic emphases. Hikma exemplifies the dedicated sterile infrastructure archetype through US-based manufacturing and distribution network concentration. Pfizer represents integrated pharmaceutical scale with backward control over active pharmaceutical ingredient synthesis. Mallinckrodt sits within the controlled-substance specialization tier, leveraging DEA registration depth and quota management expertise. Vintage Pharmaceuticals Inc., Epic Pharma Inc., and Sun Pharmaceutical anchor mid-tier positions through generic portfolio breadth and regional contract penetration.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals USA Inc. |
| Pfizer Inc. |
| Vintage Pharmaceuticals Inc. |
| Epic Pharma Inc. |
| Boehringer Ingelheim |
| Sanofi |
| Mallinckrodt Pharmaceuticals |
| Sun Pharmaceutical |
| Sandoz (Novartis AG) |
| Others |
Supply Flow & Price Mechanics
Take-or-pay contracts between hospital group purchasing organizations and sterile injectable manufacturers lock in multi-year supply access while capping annual price escalations at single-digit rates. These arrangements bind DEA-registered institutional buyers to Pfizer and Hikma production schedules, creating pricing visibility that shields hospital formularies from spot-market volatility in controlled-substance markets.
Pricing Analysis
After-sales revenue from controlled-substance waste tracking services and DEA compliance consulting drives lifetime value for sterile injectable suppliers beyond unit pricing. Contract-based long-term offtake agreements dominate, with price differentiation hinging on FDA cGMP certification tier and volume scale commitments from integrated delivery networks. Pricing pressure stems from formulary consolidation as academic medical centers restrict meperidine to rescue-line indications. Community hospitals in the US Southeast exhibit highest price sensitivity due to thinner operating margins, while academic medical centers absorb premium costs to secure audit-ready supply chains.
Supply Chain Analysis
Strategic stockpiling of raw meperidine precursor chemicals prevails over just-in-time approaches due to DEA quota rigidity and synthesis lead times. API production concentrates in the United States, India, and Germany, with finished dosage form manufacturing anchored in US-based sterile facilities. The supply chain draws from specialized phenylpiperidine precursor suppliers and USP-grade excipient providers, facing single-source vulnerability in precursor chemical synthesis. Distribution runs through DEA-registered wholesale distributors with controlled-substance vault infrastructure, primarily McKesson and AmerisourceBergen networks serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity where regulatory entrenchment creates durable barriers. DEA quota access and Schedule II handling infrastructure constitute irreplicable assets that protect incumbent positions from displacement.
For Market Incumbents: Fortify DEA quota security through backward integration into precursor chemical synthesis and captive sterile manufacturing capacity in the US Northeast. Morphine and fentanyl protocol dominance threatens volume erosion; counter by embedding meperidine into palliative care formularies through renal-safety clinical data investments. Vertical integration into API production represents the critical lever for margin defense. For New Entrants and Emerging Players: Anchor in 503B outsourcing facility partnerships with hospital networks seeking patient-specific concentrations unavailable from commercial manufacturers. Palliative care networks present the most penetrable segment, where subcutaneous infusion protocols favor meperidine's pharmacokinetic profile. A go-to-market angle emphasizing DEA compliance burden reduction for hospice agencies unlocks contracted revenue streams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with dedicated sterile infrastructure and long-term GPO contracts. Five-to-ten-year viability hinges on formulary consolidation trends and opioid stewardship program evolution. Acquisition targets should display DEA registration depth, quota history, and institutional contract density. The signal to watch is palliative care formulary expansion velocity as renal-impairment protocols mature.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Trading Mechanism Development | Formalized transfer protocols between registered manufacturers redistribute unused production allowances to match regional demand spikes. |
| Palliative Care Formulary Partnership | Hospice network contracts exploit meperidine's renally cleared metabolite profile for end-of-life pain management. |
| Sterile Manufacturing Workforce Investment | Aseptic processing technician pipelines with controlled-substance clearances reduce turnover-driven supply interruptions. |
| 503B Outsourcing Facility Alliance | Hospital volume-commitment contracts secure patient-specific concentrations unavailable from commercial manufacturers. |
| EHR Integration Standardization | Automated dispensing cabinet configurations accommodate meperidine's unique dosing alerts and drug interaction flags. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital pharmacy directors, DEA-registered wholesale distributors, sterile manufacturing executives, and palliative care formulary committees; and secondary validation through FDA Orange Book filings, DEA ARCOS data, CMS Medicare hospital cost reports, and controlled-substance import records. Bottom-up triangulation across institutional procurement volumes and top-down reconciliation against sterile injectable production capacity yielded segment-level estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories through treatment line stratification, dosage form segmentation, administration route differentiation, and regional regulatory cluster variation. CAGRs emerged from logistic adoption curves applied to hospital formulary penetration rates and palliative care network expansion patterns. Forecast inputs incorporated DEA quota allocation trends, opioid stewardship program adoption velocity, and sterile manufacturing capacity utilization thresholds.
Material uncertainties — DEA quota reallocation decisions, FDA scheduling modifications, and institutional protocol shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and clinical utility persistence. Revision becomes warranted when palliative care formulary adoption crosses institutional penetration thresholds or when DEA implements quota trading mechanisms altering supply elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Influenza Antiviral Market