
 Dipeptide Peptidase 4 Inhibitors Market | 2026-2036
Dipeptide Peptidase 4 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Dipeptide Peptidase 4 Inhibitors Market Analytics
Combination therapy bundling is repositioning prescribing patterns across the DPP-4 inhibitor category. Merck & Co., Inc. leverages its sitagliptin franchise to anchor hospital formularies in North America. Eli Lilly and Company differentiates through dual-therapy portfolios that pair DPP-4 agents with SGLT-2 inhibitors. Boehringer Ingelheim International GmbH competes on cardiovascular outcome data, sustaining preference among cardiologist prescribers.
Dipeptide peptidase 4 inhibitors are oral hypoglycemic agents that block the DPP-4 enzyme to prolong incretin hormone activity, thereby stimulating glucose-dependent insulin secretion and suppressing glucagon release. These small-molecule compounds typically exhibit plasma half-lives of 12-24 hours, enabling once-daily dosing regimens that improve adherence in type 2 diabetes management. Sitagliptin dominates prescription volume among product types due to its first-mover position and extensive real-world safety database. Combination therapy formulations command premium positioning as physicians seek simplified regimens for patients with multiple cardiometabolic comorbidities. Extended-release tablets represent the fastest-growing formulation segment, driven by manufacturing investments that reduce dosing frequency and improve pharmacokinetic profiles.
FDA cardiovascular outcome trial requirements and EMA glycemic variability guidelines jointly shape clinical trial design and label expansion strategies for DPP-4 developers. Japan's PMDA maintains distinct pharmacovigilance reporting thresholds that influence post-market surveillance investment by manufacturers operating across multiple regulatory jurisdictions. China's NMPA bioequivalence standards for generic DPP-4 agents are tightening market access for domestic producers seeking to displace originator products. Stakeholders must monitor evolving cardiology society guidelines that increasingly favor glucose-lowering agents with proven heart failure benefit, potentially reallocating demand across mechanism classes regardless of historical DPP-4 positioning.
Market Dynamics
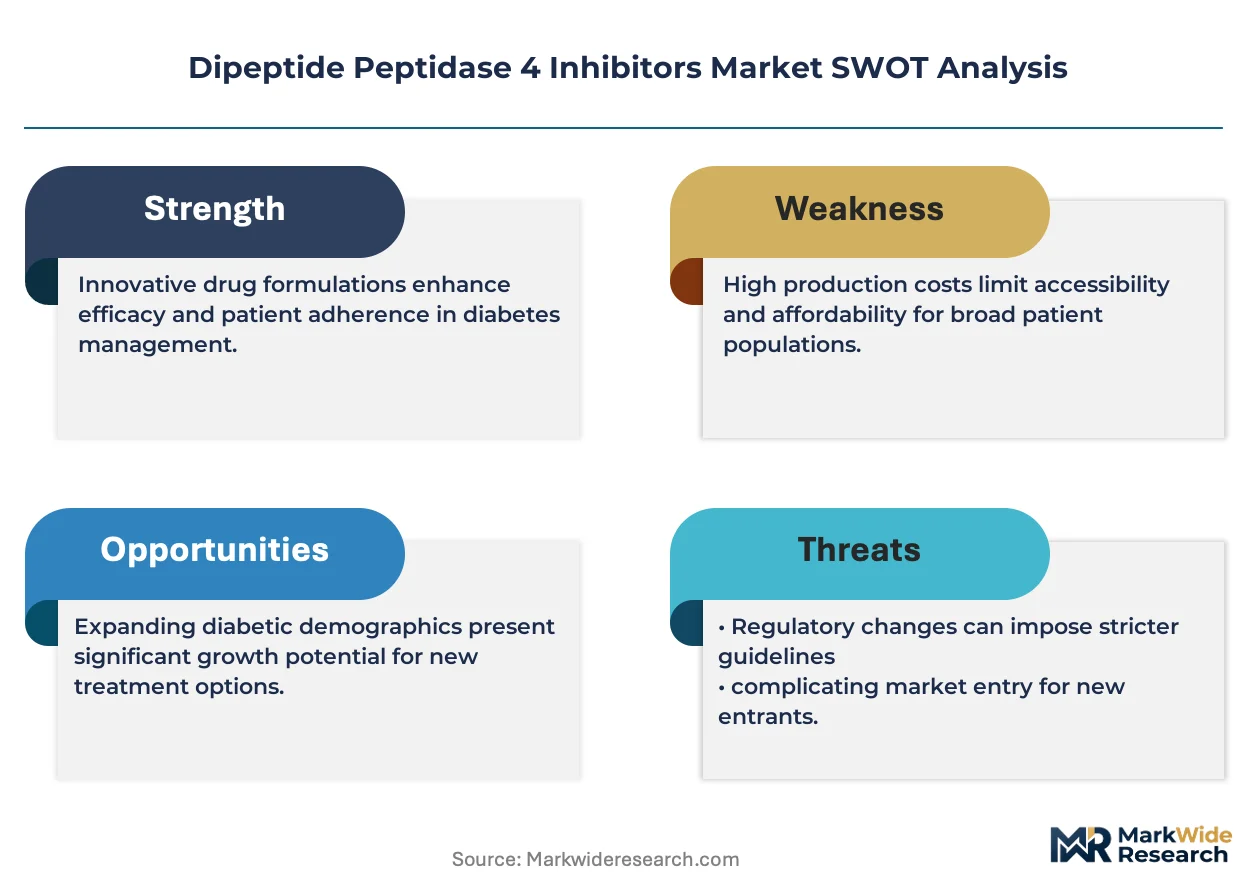
FDA cardiovascular outcome trial mandates are compressing development timelines for new molecular entities while simultaneously elevating the evidentiary bar for label expansion, forcing developers to front-load cardiology endpoint investments before commercial launch.
Growth Catalysts
- Japan's PMDA pharmacovigilance thresholds:Post-market surveillance investments by multinational manufacturers accelerate real-world safety database accumulation, reinforcing physician confidence in long-term glycemic control.
- Hospital outpatient glycemic management:Payer prioritization of discharge-to-home transitions expands formulary placement for oral antidiabetic therapies with demonstrated adherence profiles.
- Extended-release tablet manufacturing:Capital deployment into modified-release formulations reduces dosing frequency and improves pharmacokinetic predictability for polypharmacy patients.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of DPP-4 inhibitor core structures depends on specialized contract manufacturers concentrated in select Asian supply clusters.
- EMA glycemic variability guidelines:Evidentiary requirements for continuous glucose monitoring correlation studies extend regulatory review timelines for combination therapy submissions.
- SGLT-2 inhibitor substitution:Cardiologist prescribing patterns increasingly favor sodium-glucose cotransporter-2 agents with proven heart failure mortality benefit.
Strategic Opportunities
- Germany's Diabetologe specialist network:Underpenetrated ambulatory care integration creates white space for dual-therapy bundling with established cardiology referral pathways.
- China's NMPA bioequivalence tightening:Originator manufacturers can defend positioning as domestic generic producers face elevated technical barriers to market entry.
- Digital therapeutics convergence:Integration of continuous glucose monitoring data streams with dosing algorithms enables personalized titration protocols for DPP-4 regimens.
Industry Challenges
- Cardiovascular outcome trial recruitment:Competing demands for event-driven endpoint accrual strain site activation timelines across multiple concurrent diabetes drug development programs.
- Legacy formulation technology integration:Modified-release manufacturing platforms require revalidation of stability-indicating methods originally developed for immediate-release reference products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipeptide Peptidase 4 Inhibitors Market |
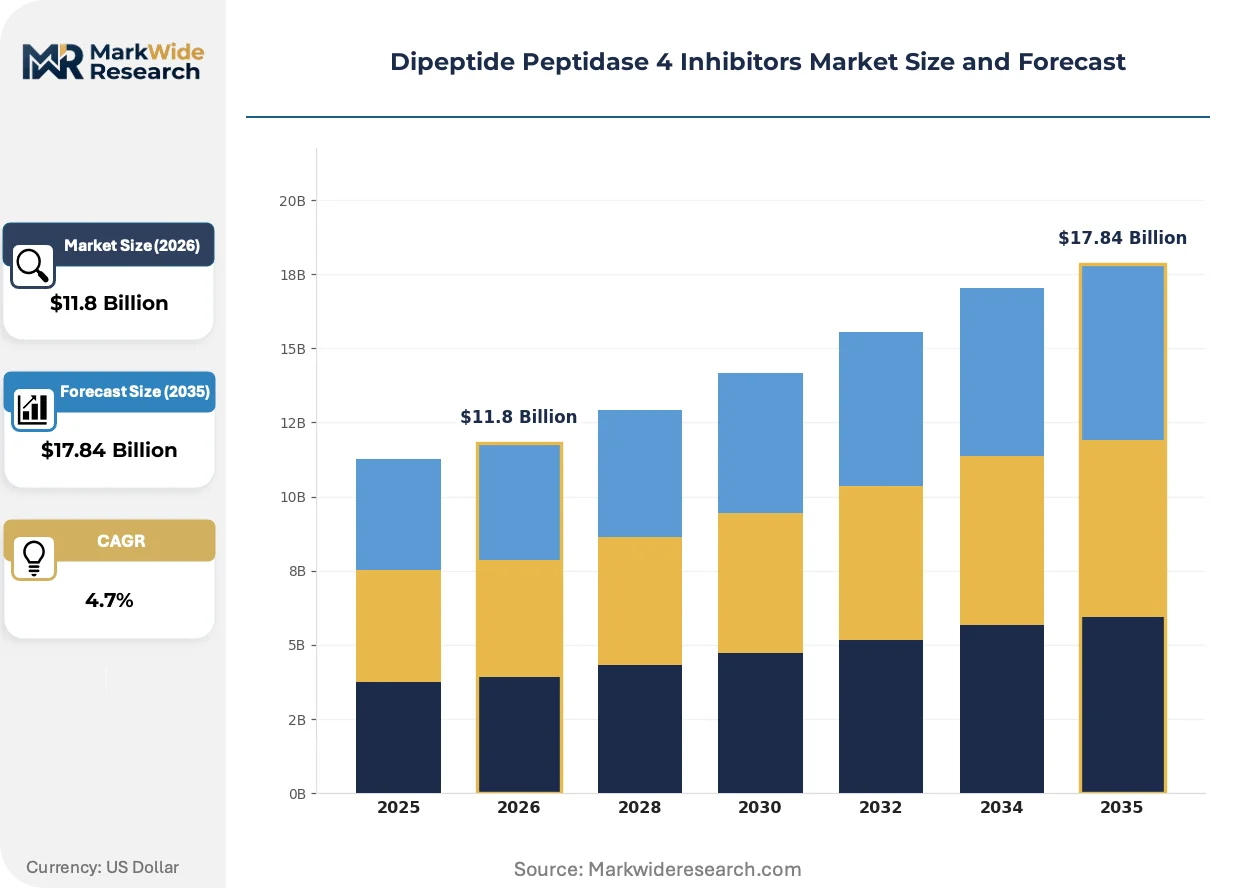
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Application: Type 2 Diabetes, Cardiovascular Disease, Obesity Management, Chronic Kidney Disease Formulation: Tablets, Injections, Extended-Release, Combination Therapy End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Merck & Co., Inc., AstraZeneca plc, Boehringer Ingelheim International GmbH, Eli Lilly and Company, Novartis AG, Takeda Pharmaceuticals Company Limited, Bristol Myers Squibb Company, Pfizer, Inc., Mitsubishi Tanabe Pharma Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipeptide Peptidase 4 Inhibitors Market Evolving Landscape
Combination therapy architectures are displacing monotherapy prescribing across the DPP-4 inhibitor category, while regulatory frameworks increasingly reward cardiovascular outcome differentiation over pure glycemic efficacy.
Fixed-dose combination tablets pairing DPP-4 inhibitors with SGLT-2 antagonists are modularizing hospital formulary decision-making by collapsing multiple therapeutic targets into single-pill adherence protocols. Cardiology departments in the United States are adopting these combinations at accelerated rates to simplify discharge medication reconciliation. This convergence is compressing the traditional step-therapy escalation pathway that historically separated mechanism classes into sequential treatment lines.
EMA's evolving glycemic variability guidelines are reshaping clinical trial endpoint selection by mandating continuous glucose monitoring correlation studies alongside traditional HbA1c reduction metrics. Developers must now demonstrate intra-day glucose fluctuation control to secure label claims for combination formulations. The fixed-dose segment faces the most acute compliance burden as dual-mechanism products require separate validation for each component's contribution to variability reduction.
Hospital procurement committees are consolidating oral antidiabetic purchasing through therapeutic class contracts that bundle DPP-4 agents with cardiovascular-protective alternatives. United States health systems are displacing individual physician preference with formulary-driven protocols that prioritize agents with American College of Cardiology guideline endorsement. This concentration is most visible in integrated delivery networks where pharmacy benefit design and clinical pathway standardization have merged under single governance structures.
Dipeptide Peptidase 4 Inhibitors Market Segmentation
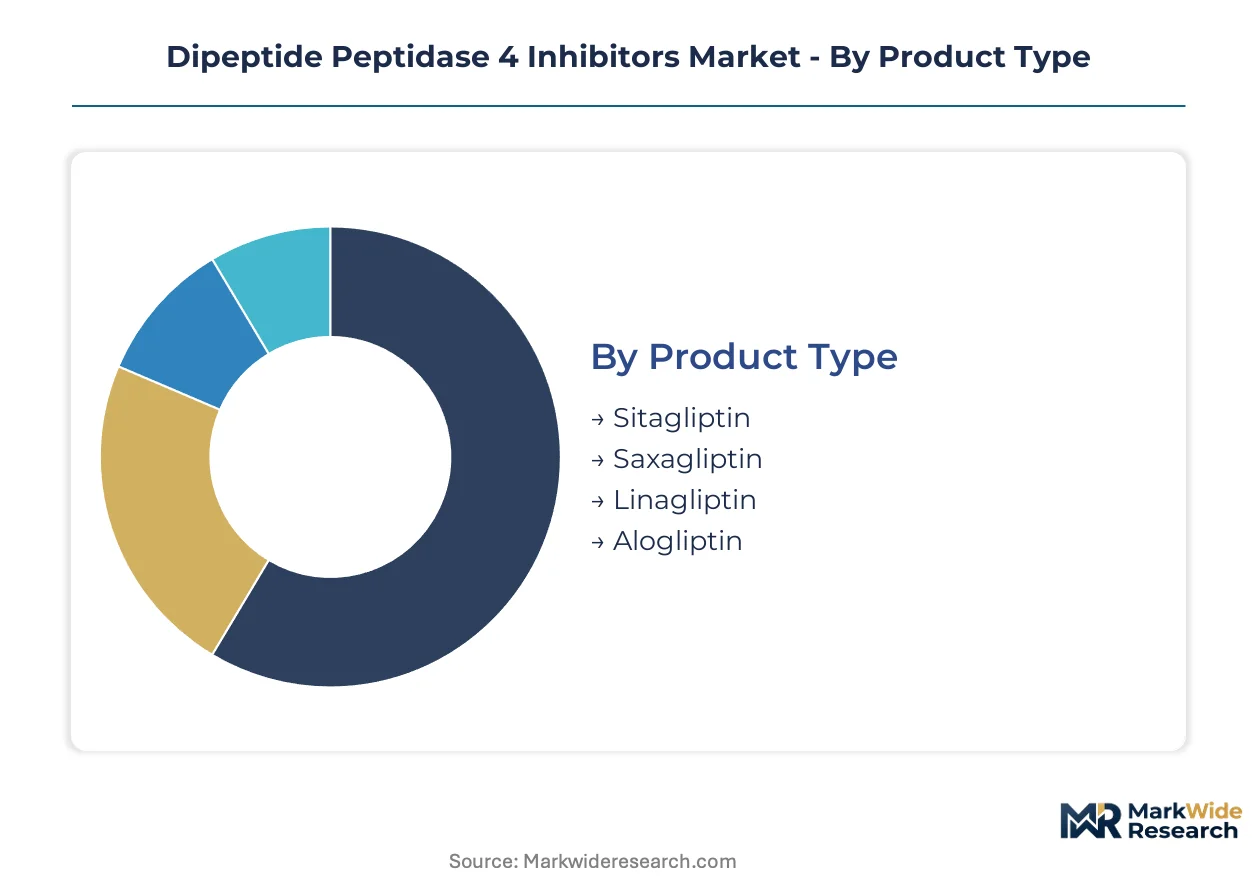
DPP-4 inhibitor segmentation reveals divergent commercial strategies across molecular architectures and care settings. Prescribing patterns fragment between established oral agents and emerging combination formats, while end-user concentration shifts from hospital-centric toward ambulatory and home-based administration.
Product Type:
Volume leadership concentrates in first-to-market molecules with extensive cardiovascular outcome databases, while premium positioning accrues to agents with differentiated metabolic profiles.
- Sitagliptin:The first DPP-4 inhibitor approved maintains dominant prescription volume through a decade of accumulated real-world safety data and streamlined FDA cardiovascular outcome trial completion. Hospital formularies in the United States retain sitagliptin as the preferred step-therapy anchor for oral glycemic control.
- Linagliptin:Hepatic metabolism without renal clearance requirements drives preference among nephrologists managing diabetic patients with declining kidney function. Germany's Diabetologe specialist network has elevated linagliptin positioning within chronic kidney disease treatment protocols.
- Saxagliptin:Extensive heart failure outcome data supports cardiology department adoption despite neutral mortality signals.
- Alogliptin:Concentrated Japanese prescribing reflects PMDA pharmacovigilance familiarity and domestic post-market surveillance infrastructure.
Mature deployment sits with sitagliptin. Newer deployment is concentrated in linagliptin.
Application:
Indication expansion beyond glycemic control is reshaping clinical trial investment and label pursuit strategies across the therapeutic class.
- Type 2 Diabetes:Core indication commanding baseline reimbursement across all major markets with HbA1c reduction as the primary endpoint for regulatory approval. Japan's aging demographic profile sustains volume concentration in this segment.
- Cardiovascular Disease:FDA and EMA mandates for cardiovascular outcome trials have elevated this application to equal strategic priority with glycemic efficacy. Cardiologist co-prescribing in the United States increasingly favors DPP-4 agents with documented heart failure safety profiles.
- Obesity Management:Adjunctive use alongside GLP-1 receptor agonists is gaining traction in integrated metabolic clinics.
- Chronic Kidney Disease:Renoprotective claims require dedicated outcome studies that extend development timelines.
Established revenue concentrates in type 2 diabetes. Pipeline investment is shifting toward cardiovascular disease.
Formulation:
Manufacturing complexity separates immediate-release commoditized supply from modified-release platforms requiring specialized equipment and process validation.
- Extended-Release:Modified-release tablet technology reduces dosing frequency to improve adherence among polypharmacy patients. Capital deployment into osmotic pump and matrix diffusion platforms is climbing fastest as manufacturers seek pharmacokinetic differentiation.
- Combination Therapy:Fixed-dose tablets pairing DPP-4 inhibitors with SGLT-2 antagonists collapse multiple therapeutic targets into single-pill regimens. Hospital discharge protocols in the United States are accelerating adoption to simplify medication reconciliation.
- Tablets:Immediate-release formulations face generic erosion pressure across European markets.
- Injections:Parenteral delivery remains limited to research settings and specific combination architectures.
Volume manufacturing sits with standard tablets. Value expansion is concentrated in extended-release and combination formats.
End User:
Care setting migration from inpatient to ambulatory environments is redistributing procurement authority and reimbursement pathways.
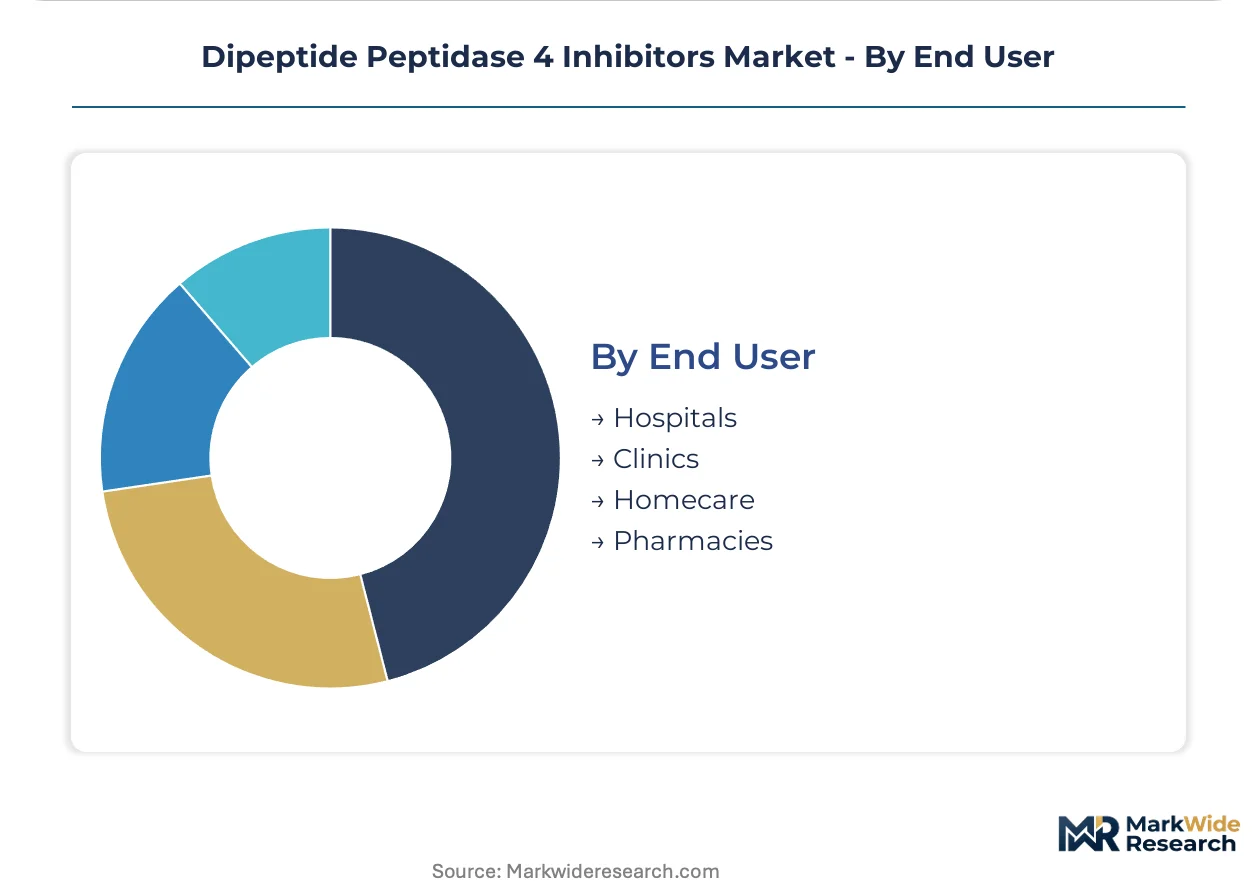
- Hospitals:Integrated delivery networks in the United States are consolidating oral antidiabetic purchasing through therapeutic class contracts that bundle DPP-4 agents with cardiovascular-protective alternatives. Formulary committees now override individual physician preference with protocol-driven selection.
- Homecare:Post-acute and long-term care facilities are expanding DPP-4 utilization as payers prioritize discharge-to-home glycemic management. Japan's community-based care integration supports volume concentration in this channel.
- Clinics:Outpatient endocrinology practices maintain independent prescribing autonomy in less consolidated markets.
- Pharmacies:Retail dispensing faces margin compression from generic substitution mandates.
Procurement consolidation sits with hospitals. Volume expansion is concentrated in homecare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and China's coastal provinces concentrate active pharmaceutical ingredient manufacturing for DPP-4 inhibitor core structures. Tax incentives in these zones attract multinational contract manufacturers seeking cost-optimized synthesis capacity. Regulatory harmonization initiatives between FDA, EMA, and Japan's PMDA streamline clinical trial protocols across these production hubs.
United States
Hospital outpatient glycemic management programs drive formulary placement for oral antidiabetic therapies. FDA cardiovascular outcome trial mandates reshape clinical development priorities, forcing developers to front-load cardiology endpoint investments. The Research Triangle Park cluster in North Carolina anchors contract research organization activity for diabetes drug trials.
Germany
The Diabetologe specialist network creates structured referral pathways for dual-therapy bundling with cardiology departments. EMA glycemic variability guidelines extend regulatory review timelines for combination therapy submissions. The Rhine-Main pharmaceutical corridor around Frankfurt sustains manufacturing investment for extended-release tablet platforms.
Japan
Aging demographics and reimbursement stability support sustained prescription volume for DPP-4 inhibitors. PMDA pharmacovigilance reporting thresholds influence post-market surveillance investment by multinational manufacturers. The Kansai region around Osaka hosts concentrated domestic post-market surveillance infrastructure for alogliptin.
China
NMPA bioequivalence standards for generic DPP-4 agents tighten market access for domestic producers seeking to displace originator products. The Yangtze River Delta pharmaceutical manufacturing belt concentrates specialized contract manufacturers for DPP-4 inhibitor core structures. Shanghai-based regulatory consulting firms facilitate multiregional clinical trial design for cardiovascular outcome studies.
Dipeptide Peptidase 4 Inhibitors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the DPP-4 inhibitor category. The market structure consolidates around established pharmaceutical majors with cardiovascular outcome trial capabilities and hospital formulary anchoring power. Three archetypes dominate: originator manufacturers with decade-long safety databases, dual-therapy portfolio builders pairing DPP-4 agents with SGLT-2 inhibitors, and regional specialists with pharmacovigilance familiarity. Dominant competitive moves include fixed-dose combination tablet launches and therapeutic class contracting with integrated delivery networks.
Among diversified pharmaceutical conglomerates, Merck & Co., Inc. and Eli Lilly and Company exemplify contrasting strategic positions. Merck anchors hospital formularies in North America through extensive real-world safety data accumulation. Eli Lilly occupies a position emphasizing dual-therapy portfolios that pair DPP-4 mechanisms with complementary cardiovascular agents. Boehringer Ingelheim International GmbH sits within the cardiology-focused tier, competing on outcome data that sustains preference among specialist prescribers.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca plc |
| Boehringer Ingelheim International GmbH |
| Eli Lilly and Company |
| Novartis AG |
| Takeda Pharmaceuticals Company Limited |
| Bristol Myers Squibb Company |
| Pfizer, Inc. |
| Mitsubishi Tanabe Pharma Corporation |
| Others |
Value Network & Pricing Analysis
Originator-generic bifurcation in the DPP-4 inhibitor category manifests in divergent pricing architectures and supply chain configurations. Premium pricing for branded sitagliptin and linagliptin rests on cardiovascular outcome trial investments and hospital formulary anchoring, while commodity-grade generics compete on spot inventory availability and contract manufacturing cost curves concentrated in Asian production clusters.
Pricing Analysis
Short lead-time premiums distinguish hospital procurement contracts from spot market generic transactions in the DPP-4 inhibitor category. Three-tier pricing structure across premium originator, authorized generic, and economy pure-generic levels reflects FDA bioequivalence certification tiers and real-world safety database depth. Price differentiation stems from cardiovascular outcome trial completion status and EMA glycemic variability guideline compliance. Cost compression in the economy tier is intensifying as China's NMPA tightens bioequivalence standards for domestic producers. Hospital procurement committees demonstrate lowest price sensitivity due to bundled therapeutic class contracting, while retail pharmacy dispensing faces highest sensitivity from mandatory generic substitution protocols.
Supply Chain Analysis
Reverse-logistics flows for DPP-4 inhibitors remain minimal given oral solid dosage stability and absence of cold-chain requirements, though batch recall protocols and pharmacovigilance sample returns create limited refurbishment pathways for quality investigation. Active pharmaceutical ingredient manufacturing concentrates in India, China, and select European specialized producers. Synthesis of DPP-4 inhibitor core structures draws from fluorinated aromatic intermediates, chiral amine building blocks, and specialized enzymatic reagents. Single-source vulnerability characterizes the contract manufacturing landscape for modified-release tablet platforms. Distribution runs through hospital procurement consortia, wholesale distributors, and direct-to-pharmacy channels for generic substitution mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DPP-4 inhibitor market functions as a vertical-integration race where backward control over active pharmaceutical ingredient synthesis and forward integration into continuous glucose monitoring data platforms determine competitive durability.
For Market Incumbents: Extend cardiovascular outcome trial data into digital therapeutics convergence by integrating dosing algorithms with continuous glucose monitoring streams. Anchor hospital formulary positioning through therapeutic class contracting that bundles DPP-4 agents with SGLT-2 inhibitor combinations, defending against cardiologist prescribing shifts toward sodium-glucose cotransporter-2 alternatives with proven heart failure mortality benefit. For New Entrants and Emerging Players: The price-point gap between premium originator sitagliptin and economy generic alogliptin creates entry space for mid-tier players with differentiated renal clearance profiles. Target Germany's Diabetologe specialist network for dual-therapy bundling with established cardiology referral pathways. Pursue go-to-market positioning through nephrology department adoption given unmet need in chronic kidney disease populations. For Investors and Strategic Acquirers: Re-rating potential sits with dual-therapy portfolio builders given FDA and EMA cardiovascular outcome trial mandates reshaping clinical development priorities. Long-term viability over the projection horizon favors manufacturers with captive active pharmaceutical ingredient supply and extended-release manufacturing platforms. Watch cardiologist prescribing pattern shifts toward heart failure benefit documentation as the inflection indicator for mechanism class reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Completion | FDA and EMA mandates elevate cardiology endpoint investments before commercial launch authorization. |
| Extended-Release Manufacturing Scale-Up | Modified-release tablet platforms reduce dosing frequency and improve pharmacokinetic predictability for polypharmacy patients. |
| Dual-Therapy Portfolio Construction | Fixed-dose combinations with SGLT-2 inhibitors collapse multiple therapeutic targets into single-pill adherence protocols. |
| Digital Therapeutics Integration | Continuous glucose monitoring data streams enable personalized DPP-4 dosing titration algorithms. |
| Active Pharmaceutical Ingredient Backward Integration | Captive synthesis capacity for fluorinated aromatic intermediates mitigates single-source contract manufacturing risk. |
Research Methodology
Document review covered FDA cardiovascular outcome trial filings, EMA marketing authorization applications, Japan PMDA pharmacovigilance databases, and ClinicalTrials.gov registries, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from SEC 10-K pharmaceutical disclosures, hospital procurement database extracts, and GPO contract repositories. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation anchored market size estimation.
Cross-reference between historical prescription audit trajectories and expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include molecular architecture, formulation technology, administration setting, patient comorbidity profile, and regional regulatory cluster. CAGRs were derived from event-driven endpoint accrual timelines and cardiovascular outcome trial completion schedules. Forecast inputs incorporated EMA glycemic variability guideline evolution and PMDA pharmacovigilance reporting threshold adjustments.
Inputs from hospital procurement committees and formulary directors were available through the study window; gaps in real-world adherence data for extended-release formulations introduce uncertainty bands around volume projections. Forecasts reflect assumptions regarding cardiologist prescribing pattern stability and SGLT-2 inhibitor substitution velocity. Material deviation in cardiovascular outcome trial readouts or heart failure guideline updates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Cerumenolytic Agents Market