
 US Compounding Pharmacies Market | 2026-2036
US Compounding Pharmacies Market Size, Share, and Industry Trends Forecast 2026-2036
US Compounding Pharmacies Market Analysis
Multi-source API procurement is consolidating across the US compounding pharmacies landscape as quality assurance costs rise. Fagron leverages its vertically integrated supply network to secure raw material consistency for sterile formulations. Fresenius Kabi anchors hospital channel relationships through its parenteral nutrition compounding capabilities. Empower Pharmacy differentiates via direct-to-patient distribution models that bypass traditional wholesale intermediaries.
Compounding pharmacies prepare customized medications by altering, combining, or mixing pharmaceutical ingredients to meet patient-specific prescriptions, with sterile injectables requiring ISO Class 5 cleanroom environments and endotoxin testing below 0.5 EU/mL. These facilities serve therapeutic niches where mass-manufactured drugs fail—pediatric dosing, allergen-free formulations, and discontinued therapies. Oral medications maintain the largest volume share due to chronic disease management needs, while hormone replacement therapy commands premium pricing through personalized titration protocols. Pain management formulations face margin compression as DEA scheduling scrutiny intensifies for controlled-substance compounds.
FDA enforcement of 503A versus 503B facility classifications directly determines which compounders may produce sterile products at scale without new drug approval pathways. USP Chapter 797 and USP Chapter 800 standards govern personnel training, environmental monitoring, and hazardous drug handling across all fifty states. State boards of pharmacy retain inspection authority that creates compliance fragmentation between jurisdictions like California's stricter sterile compounding rules and Texas's more permissive oversight. Stakeholders must monitor whether Congress expands FDA authority to mandate adverse event reporting from 503A traditional compounders currently exempt from such requirements.
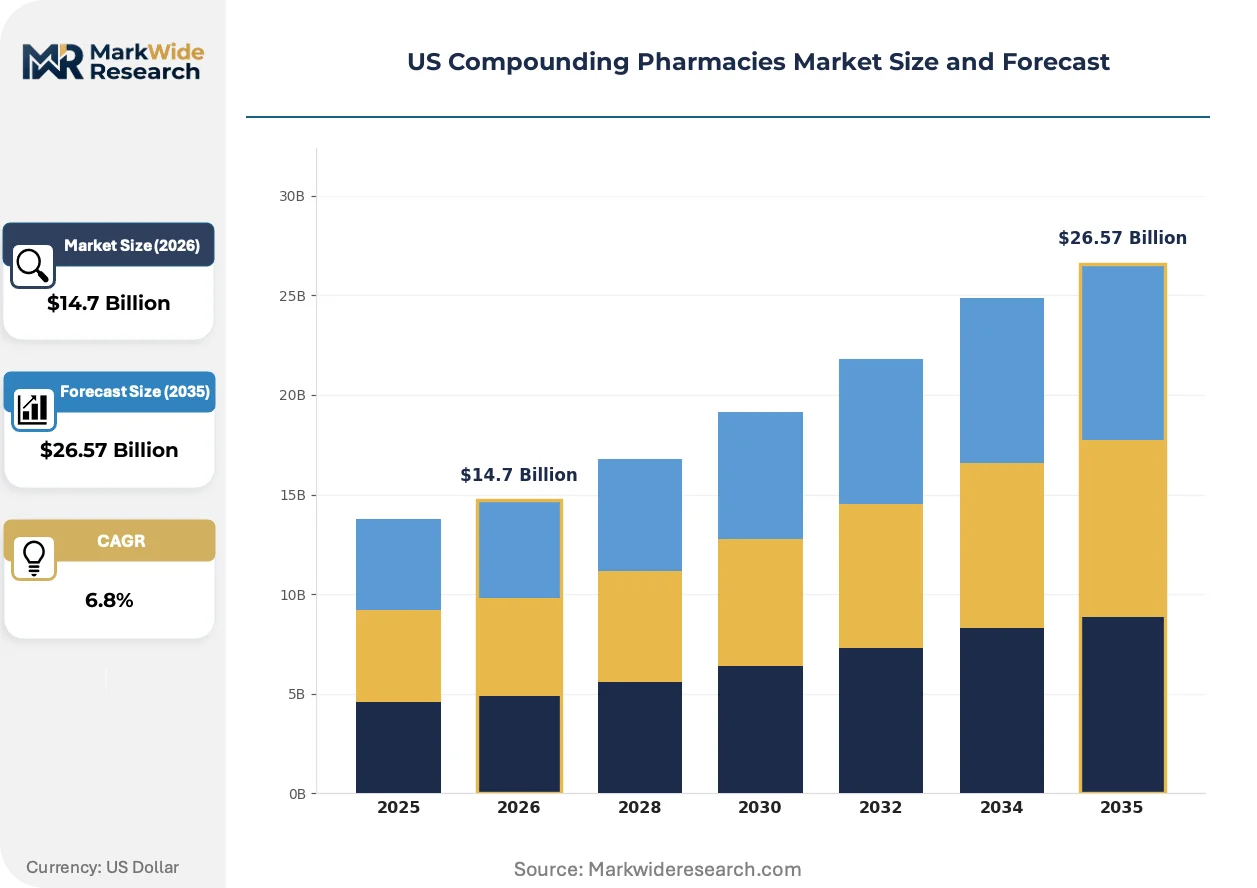
Market Dynamics
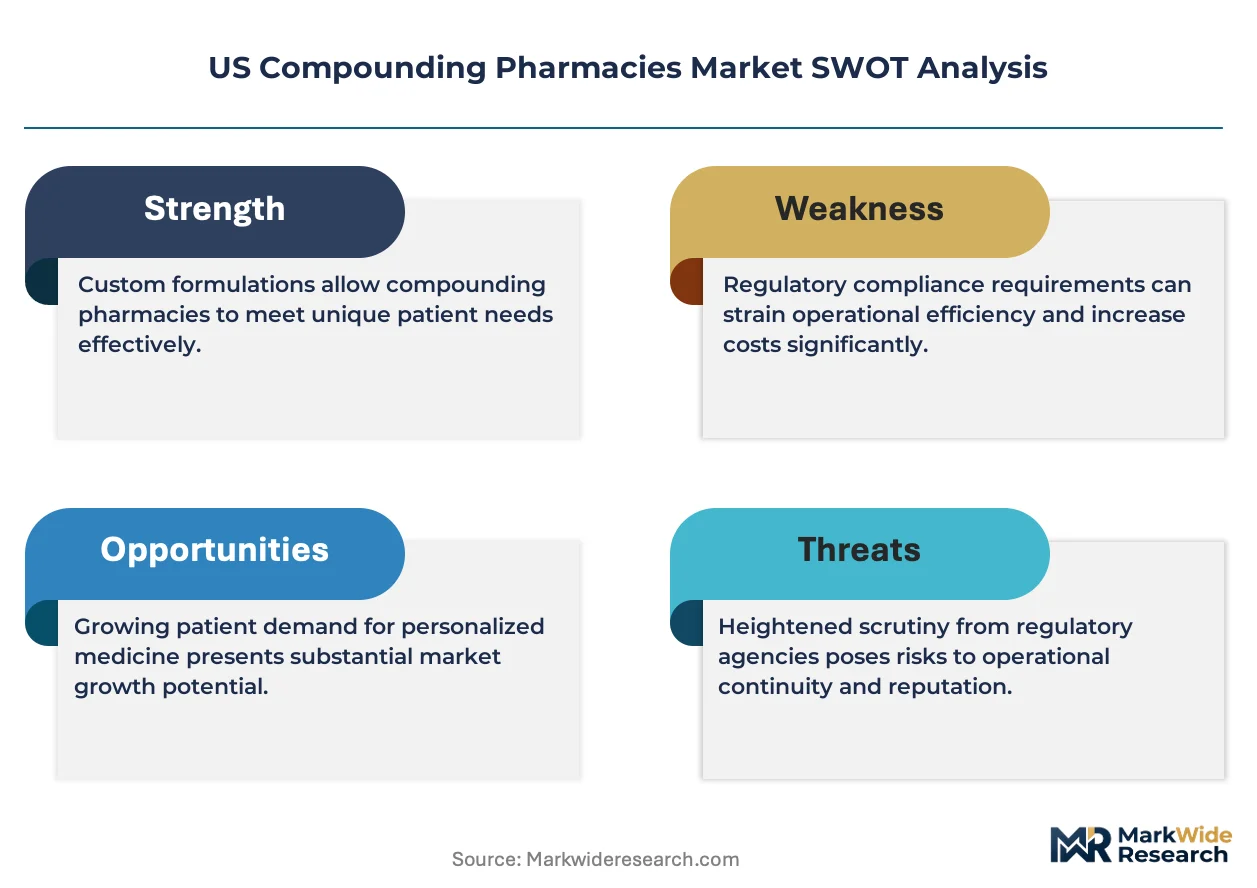
FDA's bifurcated 503A/503B facility classification system creates a dual-track compliance burden that fragments production economics between hospital-scale sterile compounders and traditional patient-specific pharmacies. This regulatory architecture forces capital allocation decisions that reshape competitive boundaries across state lines.
Growth Catalysts
- DEA Scheduling Flexibility:Controlled-substance compounding exemptions allow veterinarians and pain specialists to access customized dosing schedules unavailable through commercial manufacturers.
- Pediatric Formulation Gaps:Mass-market drug discontinuations and age-inappropriate excipients drive hospital pediatric units toward compounded alternatives for neonatal and rare disease patients.
- Texas and Florida Cluster Density:Independent compounders concentrate around Houston Methodist and Tampa General networks, creating regional supply hubs that reduce sterile product transport times.
Market Restraints
- API Supply Concentration:Quality-assurance failures at overseas active pharmaceutical ingredient suppliers trigger batch rejections that idle US cleanroom capacity.
- USP Chapter 797 Compliance Costs:Environmental monitoring systems and personnel certification programs absorb 15-20% of operating budgets at mid-sized sterile facilities.
- Biologic Substitution Threat:Recombinant hormone therapies and monoclonal antibody platforms displace traditional compounded preparations in endocrinology practices.
Strategic Opportunities
- Home Infusion Channel Expansion:Direct-to-patient distribution models bypass hospital outpatient pharmacies and capture margin from specialty pharmacy intermediaries.
- Companion Animal Dermatology:Veterinary clinics in Arizona and Colorado seek allergen-specific immunotherapy compounds unavailable through commercial veterinary formularies.
- IRA Drug Pricing Negotiation Exemptions:Compounded alternatives to Medicare-negotiated small-molecule drugs retain pricing autonomy for cash-pay patients.
Industry Challenges
- ISO Class 5 Cleanroom Technician Scarcity:Aseptic processing certification programs produce fewer qualified operators than Texas and Florida facility expansions require.
- Legacy Pharmacy Management System Integration:503B outsourcing facilities struggle to reconcile batch record systems with hospital electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Compounding Pharmacies Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Medications, Topicals, Inhalation Solutions Therapy Area: Pain Management, Hormone Replacement Therapy, Veterinary, Dermatology End User: Hospitals, Clinics, Home Healthcare, Pharmacies Delivery Mode: Intravenous, Oral, Transdermal, Subcutaneous |
| Companies Covered | Fagron, Fresenius Kabi, B. Braun Melsungen, Baxter International, Empower Pharmacy, Vertisis Custom Pharmacy, Triangle Compounding Pharmacy, Avella Specialty Pharmacy, PenCol Compounding Pharmacy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Compounding Pharmacies Market Emerging Trajectories
Point-of-care sterile compounding technologies are collapsing the distance between production and administration, eliminating cold-chain logistics that previously constrained hospital formulary flexibility. This shift reconfigures supplier relationships and inventory economics across acute care networks.
Automated compounding devices with integrated gravimetric verification are decentralizing sterile preparation from central hospital pharmacies to satellite infusion centers and ambulatory surgery suites. Oncology clinics in California and New York adopt these systems to reduce patient wait times for chemotherapy admixtures. The technology is decentralizing purchasing authority from pharmacy directors to individual department managers who control capital budgets under $500,000.
FDA's 2023 revised 503B guidance on bulk drug substance lists narrows the permissible starting materials for outsourcing facilities producing office-use sterile products. Compounders must reformulate or discontinue preparations based on nominated substances that failed the FDA's clinical need demonstration. Hospital 503B facilities in Pennsylvania and Ohio face the steepest reformulation burdens as their historical bulk APIs lack the documented shortage evidence required for list inclusion.
Specialty pharmacy benefit managers are unbundling compounded medication reimbursement from traditional drug tiers, creating separate prior authorization pathways that favor 503B facilities with dedicated payer contracting staff. Rheumatology and endocrinology practices in North Carolina and Georgia route more prescriptions through these contracted channels. The Southeast exhibits the most pronounced channel migration as regional health plans consolidate their specialty pharmacy networks.
US Compounding Pharmacies Market Segmentation
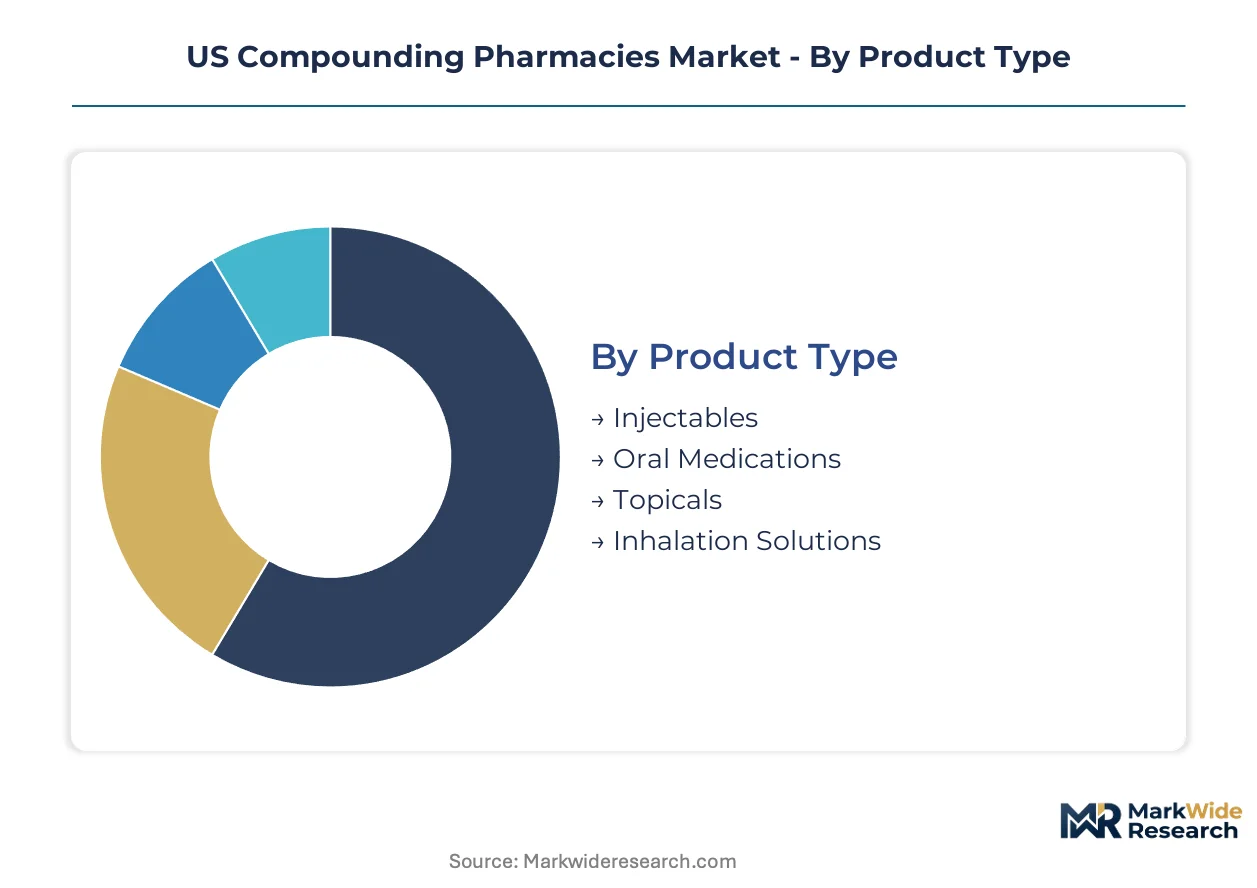
Regulatory classification under FDA 503A versus 503B determines which compounding segments can scale sterile production without new drug approval burdens. Each segment carries distinct certification requirements that reshape capital allocation and margin structures across the value chain.
Product Type:
ISO Class 5 cleanroom certification and USP Chapter 797 compliance requirements vary sharply across dosage forms, with sterile injectables demanding the most intensive environmental monitoring and personnel training protocols.
- Injectables:Parenteral formulations require endotoxin testing below 0.5 EU/mL and continuous viable particle monitoring. Hospital 503B outsourcing facilities in Texas and Florida concentrate demand here as they serve metropolitan infusion networks with same-day sterile preparation needs.
- Oral Medications:Capsules, suspensions, and lozenges dominate chronic disease management volumes with simpler USP Chapter 795 non-sterile compounding standards. Texas independent compounders cluster around Houston Methodist and Tampa General networks, reducing transport times for patient-specific pediatric and geriatric dosing.
- Topicals:Creams, gels, and ointments for dermatology and pain management require less stringent environmental controls than sterile products.
- Inhalation Solutions:Nebulized preparations for respiratory therapy face specialized stability testing and container closure integrity requirements.
Oral medications sit at the top of the volume ranking, with injectables climbing the fastest as hospital outsourcing expands.
Therapy Area:
Margin structures diverge across therapeutic categories based on DEA scheduling scrutiny, biologic substitution threats, and the availability of commercial alternatives.
- Pain Management:Controlled-substance formulations face intensifying DEA compliance costs and scheduling restrictions that compress margins. Arizona and Colorado veterinary clinics seek customized dosing schedules unavailable through commercial manufacturers, creating regional demand pockets.
- Hormone Replacement Therapy:Personalized titration protocols command premium pricing through cash-pay models that bypass traditional pharmacy benefit manager tiers. Recombinant biologic alternatives are displacing traditional compounded preparations in endocrinology practices, threatening long-term volume.
- Veterinary:Companion animal dermatology and allergen-specific immunotherapy drive fastest-growing demand as pet owners seek customized dosing.
- Dermatology:Pediatric allergen-free excipient formulations serve niche populations with commercial product gaps.
Hormone replacement therapy commands the highest pricing tier, with veterinary applications expanding most quickly as clinic adoption accelerates.
End User:
Customer type determines distribution channel complexity and whether compounders must maintain 503B outsourcing facility status with dedicated adverse event reporting systems.
- Hospitals:Acute care networks require 503B-certified suppliers capable of batch production for office-use sterile products without patient-specific prescriptions. Pennsylvania and Ohio facilities face steep reformulation burdens as FDA bulk drug substance list revisions eliminate historical starting materials.
- Clinics:Rheumatology and endocrinology practices in North Carolina and Georgia route increasing volumes through specialty pharmacy benefit manager contracted channels. Prior authorization unbundling creates separate reimbursement pathways favoring compounders with dedicated payer contracting staff.
- Home Healthcare:Direct-to-patient distribution models bypass hospital outpatient pharmacies and capture margin from specialty pharmacy intermediaries.
- Pharmacies:Traditional 503A patient-specific compounders serve individualized prescriptions with lighter regulatory burdens but scale limitations.
Hospitals anchor the largest volume share, with home healthcare gaining share fastest as infusion technology decentralizes.
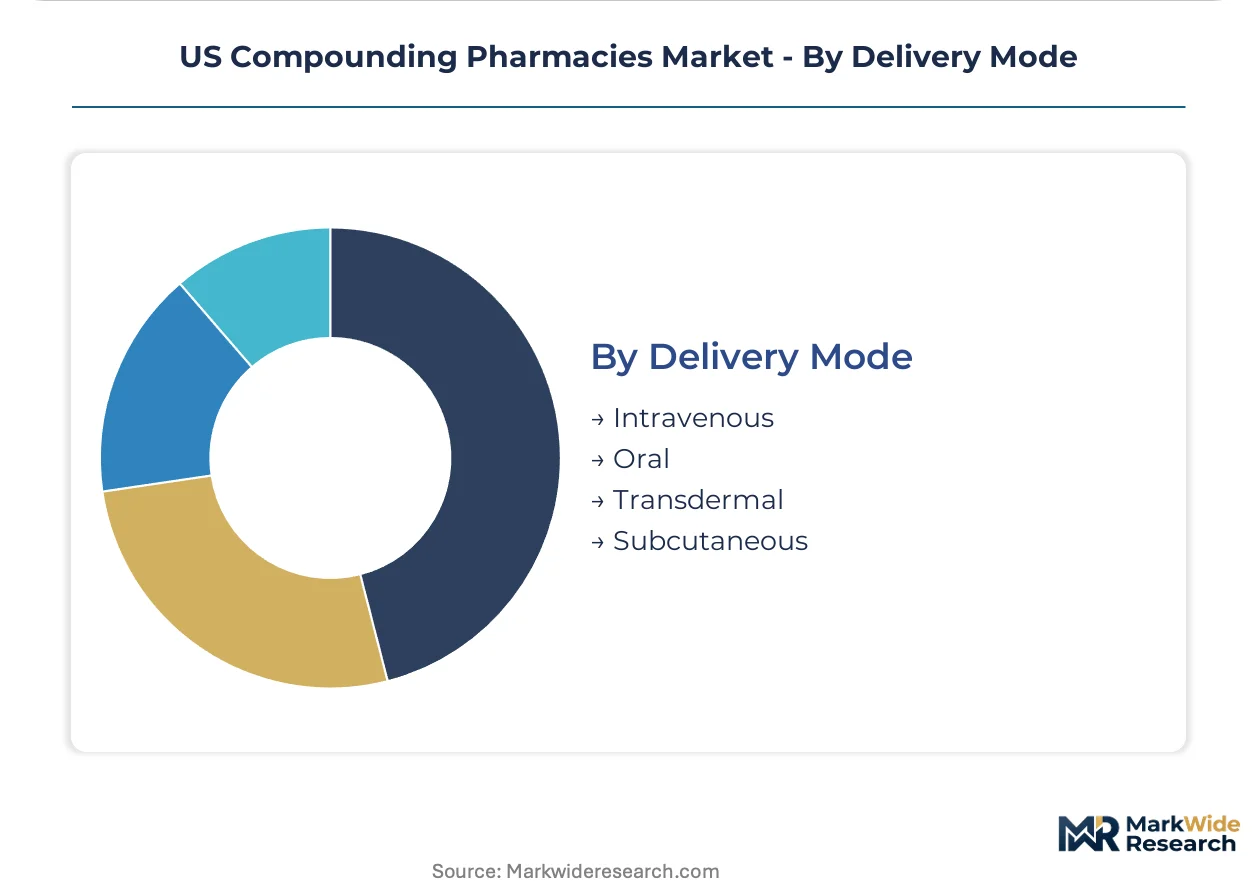
Delivery Mode:
Route of administration dictates supply chain configuration, with intravenous preparations requiring cold-chain logistics that transdermal and oral alternatives avoid.
- Intravenous:Parenteral nutrition and chemotherapy admixtures demand immediate-use stability windows that collapse production-to-administration timelines. California and New York oncology clinics adopt automated compounding devices with gravimetric verification to reduce patient wait times.
- Oral:Solid and liquid dosage forms offer longest stability profiles and simplest patient self-administration, supporting mail-order distribution models.
- Transdermal:Patch and gel formulations for hormone and pain therapy require specialized penetration enhancer compatibility testing.
- Subcutaneous:Self-injection devices for biologic mimics and hormone therapy balance patient convenience with moderate sterility requirements.
Intravenous delivery maintains volume leadership, with subcutaneous routes showing steepest expansion trajectory as home injection training programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Tampa corridor anchors US compounding pharmacy infrastructure, with independent compounders clustering around Methodist and Tampa General networks to minimize sterile product transport windows. Texas and Florida together concentrate more than one-third of national 503B outsourcing capacity. State-level regulatory fragmentation creates competitive arbitrage opportunities between jurisdictions.
Texas
Metropolitan Houston and Dallas-Fort Worth host the densest concentration of hospital-affiliated 503B facilities serving same-day sterile preparation needs. The Texas State Board of Pharmacy maintains more permissive oversight standards than coastal counterparts, attracting capital from multi-state operators seeking lower compliance burdens. San Antonio and Austin satellite operations extend reach into South Texas border markets.
Florida
Tampa General and Miami-area hospital networks drive demand for parenteral nutrition and chemotherapy admixtures requiring immediate-use stability. Florida's pharmacy board aligns closely with USP Chapter 797 federal minimums rather than imposing California-style supplemental requirements. Jacksonville and Orlando compounders specialize in veterinary dermatology formulations for the state's large companion animal population.
California
Los Angeles and San Francisco Bay Area oncology clinics adopt automated compounding devices with gravimetric verification to reduce patient wait times. The California State Board of Pharmacy enforces stricter sterile compounding rules than federal baselines, elevating operating costs for 503B facilities. San Diego operations serve cross-border demand from Tijuana medical tourism corridors.
Pennsylvania
Philadelphia and Pittsburgh hospital systems face steep reformulation burdens as FDA bulk drug substance list revisions eliminate historical starting materials. The state's pharmacy board coordinates inspection protocols with neighboring Ohio and New York to reduce multi-jurisdictional compliance friction. Central Pennsylvania compounders specialize in hormone replacement therapy cash-pay models.
North Carolina
Raleigh-Durham and Charlotte rheumatology and endocrinology practices route increasing volumes through specialty pharmacy benefit manager contracted channels. The North Carolina Board of Pharmacy participates in regional compacts to standardize 503A versus 503B facility inspections. Wilmington operations target home infusion channel expansion along the I-95 corridor.
US Compounding Pharmacies Market Vendor Landscape
Global majors compete with regional champions across API procurement and hospital channel access, producing a tiered structure where capital scale separates outsourcing facility operators from traditional patient-specific compounders. Vertically integrated suppliers with captive raw material sourcing occupy the premium tier, while independent compounders cluster in price-sensitive oral medication segments. Strategic moves concentrate on multi-state licensing expansion and automated compounding technology deployment.
Within the hospital outsourcing tier, Fresenius Kabi and Baxter International exemplify capital-scale operators with parenteral nutrition and sterile injectable capabilities. Among independent compounders, Empower Pharmacy and Triangle Compounding Pharmacy occupy positions emphasizing direct-to-patient distribution models that bypass traditional wholesale intermediaries.
| Leading Market Players |
|---|
| Fagron |
| Fresenius Kabi |
| B. Braun Melsungen |
| Baxter International |
| Empower Pharmacy |
| Vertisis Custom Pharmacy |
| Triangle Compounding Pharmacy |
| Avella Specialty Pharmacy |
| PenCol Compounding Pharmacy |
| Others |
Supply Flow & Price Mechanics
API price indices for sterile-grade excipients cascade through US compounding pharmacy supply chains into three distinct pricing tiers. Hospital 503B outsourcing facilities absorb upstream volatility through long-term offtake contracts, while independent 503A compounders face spot-market exposure that compresses margins on oral medications.
Pricing Analysis
Input-cost pass-through from active pharmaceutical ingredient suppliers operates unevenly across facility classifications. Three-tier pricing structure across premium, standard, and economy levels separates 503B-certified hospital suppliers from independent compounders and cash-pay hormone therapy boutiques. Price differentiation hinges on ISO Class 5 certification status and DEA controlled-substance licensing tiers. Cost compression in standard-tier oral medications is intensifying because pediatric formulation demand outpaces insurance reimbursement adjustments. Hospital procurement committees exhibit lowest price sensitivity, while independent veterinary clinics in Arizona and Colorado face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for expired sterile injectables and recalled hormone preparations create specialized handling requirements that reshape distribution economics. Active pharmaceutical ingredient supply concentrates in India, China, and Italy for non-sterile inputs, with US domestic sourcing dominant for sterile-grade materials. Raw material dependencies center on USP-grade solvents, endotoxin-free water systems, and specialized elastomeric closures. Single-source vulnerability at overseas API suppliers triggers batch rejections that idle Texas and Florida cleanroom capacity. Distribution runs through hospital central pharmacy networks for 503B products, with direct-to-patient mail order gaining share in cash-pay hormone replacement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US compounding pharmacies market represents a late-cycle quality story as veterinary clinics and home infusion channels shift demand toward ISO-certified sterile formulations with documented chain-of-custody protocols.
For Market Incumbents: Cement hospital channel lock-in through USP Chapter 797 certification investments that 503A competitors cannot replicate. Expand captive API sourcing from Indian suppliers to buffer quality-assurance failure risks at overseas vendors. Biologic substitution in endocrinology practices threatens hormone therapy volumes, making backward integration into sterile packaging the priority defensive lever. For New Entrants and Emerging Players: Enter via companion animal dermatology in Colorado and Arizona, where allergen-specific immunotherapy demand outstrips veterinary formulary supply. Target home healthcare infusion channels in North Carolina's I-95 corridor, where prior authorization unbundling creates reimbursement pathways for 503B-certified entrants. Go-to-market execution should emphasize direct-to-patient distribution models that bypass specialty pharmacy benefit manager intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where state regulatory fragmentation creates compliance arbitrage opportunities between Texas's permissive oversight and California's stricter rules. Long-term viability favors vertically integrated operators with captive API sourcing and multi-state 503B licensing. Acquisition targets should display hospital system partnership density and automated compounding device deployment. The signal to watch is FDA expansion of adverse event reporting requirements to 503A traditional compounders currently exempt from such mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State 503B Licensing Expansion | Captures hospital outsourcing volume across Texas-Florida corridor with unified compliance protocols. |
| Automated Compounding Device Deployment | Reduces patient wait times at California and New York oncology clinics through point-of-care gravimetric verification. |
| Captive API Sourcing Investment | Buffers batch rejection risks from Indian and Chinese suppliers through in-house quality assurance. |
| Direct-to-Patient Channel Buildout | Bypasses specialty pharmacy benefit manager tiers in hormone replacement cash-pay segments. |
| Veterinary Dermatology Formulary Development | Addresses allergen-specific immunotherapy gaps in Arizona and Colorado companion animal markets. |
Methodological Framework
Bottom-up hospital and clinic demand modeling reconciled against top-down API supply tracking forms the analytical core of this study. Primary interviews with 503B facility directors, state board of pharmacy inspectors, hospital procurement managers, and veterinary clinic owners combined with secondary validation from FDA 483 inspection databases, USP Chapter revision notices, and DEA controlled-substance quota filings. Triangulation across these sources ensures segmentation integrity across the 503A versus 503B facility classification divide.
Historical trendline analysis of sterile compounding capacity expansion and oral medication volume trajectories informed projection frameworks. Segmentation dimensions modeled include regulatory facility classification, dosage form sterility requirements, therapy area DEA scheduling tiers, end-user channel type, and regional state regulatory cluster patterns. CAGRs were derived from fitted growth curves applied to base-year market sizing, with veterinary application expansion and home infusion channel migration serving as key demand-side inputs.
The model holds under current FDA 503A/503B bifurcation and state-level inspection fragmentation; deviation in federal preemption of state pharmacy board authority or bulk drug substance list revisions would shift competitive boundaries. Forecasts incorporate assumptions regarding continued DEA scheduling flexibility for compounded controlled substances and stable API trade flows from India and China. Practitioners should monitor FDA guidance on 503A adverse event reporting mandates and USP Chapter 797 revision timelines for early signals of regulatory inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Czech Republic Pharmaceutical Market