
 Meperidine Market | 2026-2036
Meperidine Market Size, Share, and Industry Trends Forecast 2026-2036
Meperidine Market Analysis
The gap between premium branded formulations and commodity generics is shifting as procurement officers at hospital networks renegotiate contracts on total-cost-of-care metrics. Pfizer Inc. leverages its injectable manufacturing infrastructure to sustain supply security for institutional buyers. Mallinckrodt Pharmaceuticals anchors its position through DEA quota allocations and controlled-substance distribution licenses. Hikma Pharmaceuticals competes on cost-engineered oral tablets for acute pain protocols in emerging markets.
Meperidine, a synthetic phenylpiperidine opioid analgesic with a chemical formula of C15H21NO2, functions primarily as a short-acting mu-opioid receptor agonist for moderate-to-severe pain relief in perioperative and obstetric settings; its manufacturing involves N-alkylation of pyridine derivatives followed by esterification to yield the hydrochloride salt. Injectable formulations dominate current revenue pools due to perioperative standard-of-care protocols, while extended-release delivery systems represent the fastest-growing segment as clinicians seek alternatives to frequent dosing in labor pain management. Combination formulations containing antiemetics command premium positioning in hospital formularies.
The FDA, DEA, and state-level prescription drug monitoring programs collectively shape market access through production quotas, scheduling classifications, and dispensing surveillance. The Controlled Substances Act and subsequent amendments create barriers to entry that protect incumbent manufacturers with established compliance infrastructure. Stakeholders must monitor evolving opioid litigation settlements and their downstream effects on formulary placement and liability exposure.
Market Dynamics
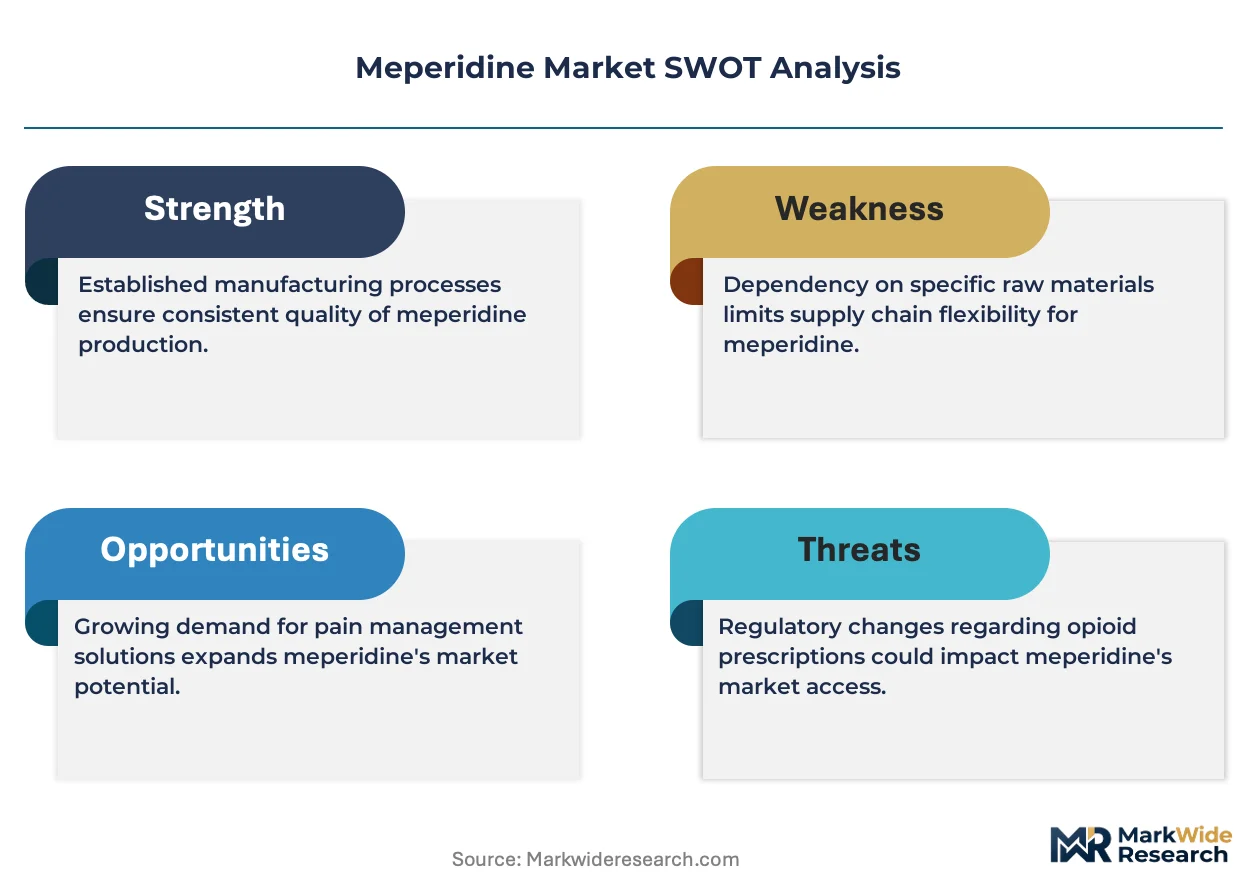
DEA production quotas and FDA scheduling classifications create artificial scarcity that protects incumbent manufacturers while constraining supply elasticity for hospital formularies dependent on perioperative protocols.
Growth Catalysts
- Post-operative pain protocols:Hospital surgical volume recovery drives consistent institutional demand for injectable formulations in perioperative settings.
- Controlled Substances Act framework:Regulatory barriers limit new entrants, preserving margin structures for established quota holders with compliance infrastructure.
- Obstetric analgesia applications:Labor pain management protocols sustain demand for short-acting synthetic opioids where rapid onset and offset prove clinically advantageous.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in China and India, exposing buyers to geopolitical friction and customs delays.
- Norpethidine metabolite toxicity:Accumulation of the toxic metabolite limits dosing duration in renal-impaired patients, narrowing addressable patient populations.
- DEA quota ceilings:Annual production limits cap volume expansion regardless of demand signals from hospital networks.
Strategic Opportunities
- Extended-release delivery systems:Sustained-release formulations for labor analgesia reduce dosing frequency and capture premium positioning in maternity wards.
- Combination antiemetic formulations:Fixed-dose combinations with ondansetron or promethazine command formulary preference by reducing polypharmacy complexity.
- Emerging market oral tablet demand:Cost-engineered solid dosage forms address acute pain protocols in India, Brazil, and Southeast Asia where injectable infrastructure remains limited.
Industry Challenges
- Controlled-substance compliance talent:Qualified personnel for DEA record-keeping, vault security, and audit preparation command premium wages and experience high turnover.
- Opioid litigation liability exposure:State attorney general settlements and civil litigation create unpredictable balance-sheet risk for manufacturers and distributors.
- Prescription drug monitoring program integration:Real-time data exchange requirements with state PDMPs demand continuous IT investment and interoperability maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meperidine Market |
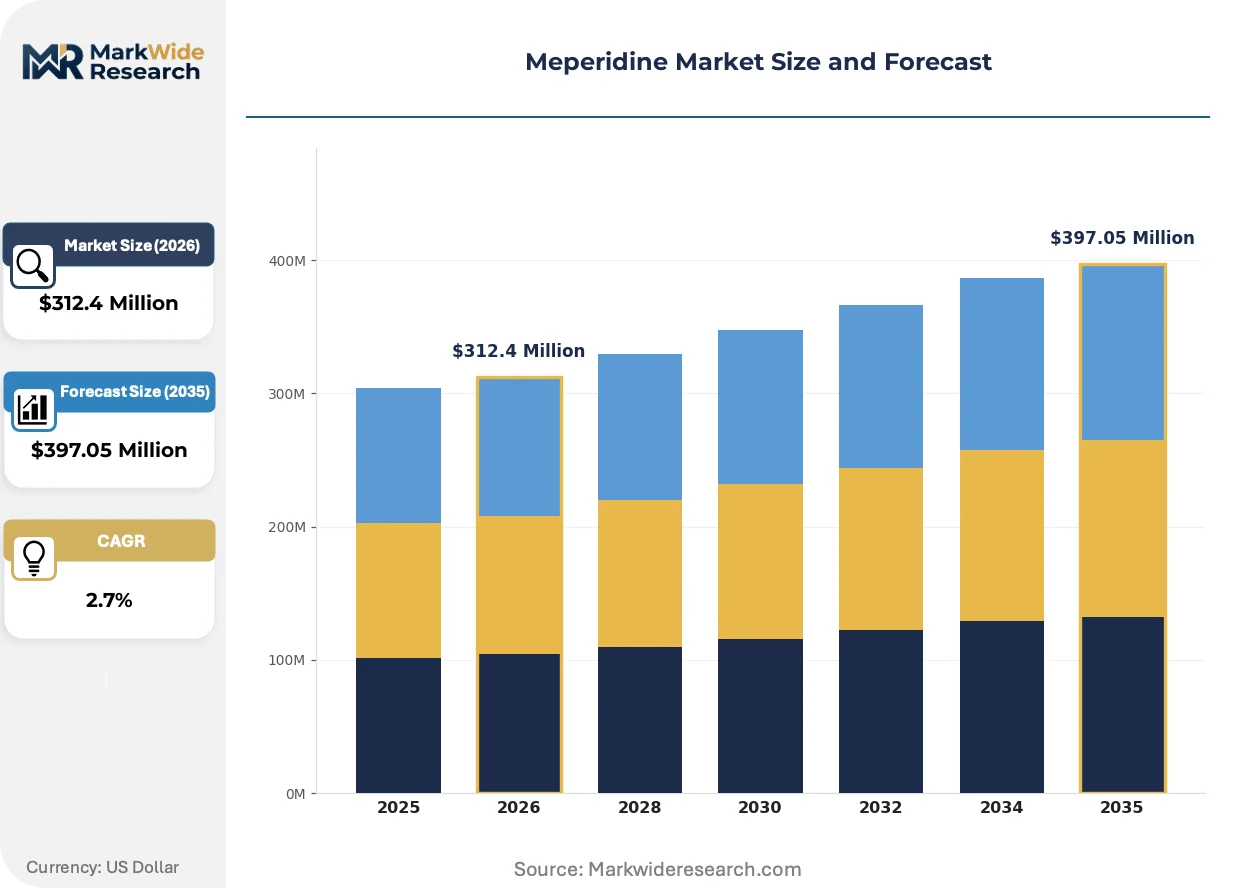
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $397.05 Million |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Extended-Release, Combination Formulations Application: Post-Operative Pain, Acute Pain Management, Labor Pain Relief, Anesthesia End User: Hospitals, Clinics, Home Healthcare, Research Institutions Delivery Mode: Injection, Tablet, Pre-filled Syringe, Nasal Spray |
| Companies Covered | Pfizer Inc., Sanofi, Mallinckrodt Pharmaceuticals, Boehringer Ingelheim International GmbH, Hikma Pharmaceuticals, Sandoz (Novartis AG), Epic Pharma LLC, Sun Pharmaceuticals, Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meperidine Market Emerging Trajectories
Formulation science and regulatory surveillance technology are converging to reshape how synthetic opioids reach clinical settings and how their distribution is tracked.
Liposomal encapsulation technology is unifying extended-release performance with rapid onset characteristics for obstetric applications. Maternity wards at tertiary hospitals in the United States and Germany are piloting these formulations to reduce nursing burden during prolonged labor. The technology is compressing dosing intervals from hourly to every four to six hours without sacrificing titratability.
EMA's strengthened pharmacovigilance requirements under the Medical Device Regulation and updated GMP Annex 1 guidelines are mandating real-time temperature monitoring across the cold chain. European distributors must now deploy IoT-enabled logistics platforms that transmit continuous data to national competent authorities. Hospital pharmacies in France and Italy are rejecting shipments lacking complete temperature excursion documentation.
Consolidated purchasing by hospital networks is displacing fragmented procurement at individual facility level. Group purchasing organizations now negotiate multi-year meperidine contracts on total-cost-of-care metrics that bundle drug, delivery, and waste disposal. This concentration is most visible in the United States, where Catholic health systems and for-profit chains have centralized formulary decisions to regional pharmacy committees.
Meperidine Market Segmentation
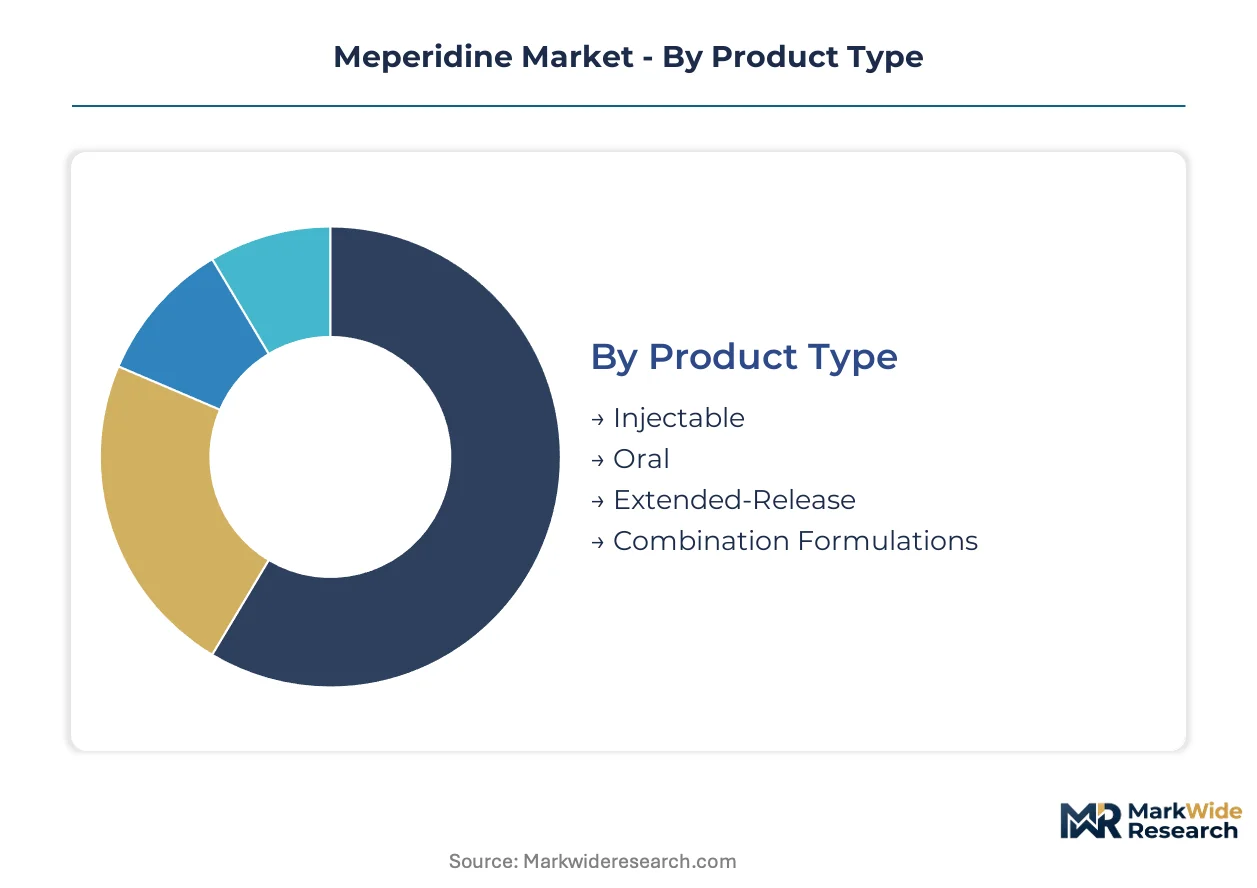
Meperidine procurement decisions split across four dimensions that determine pricing power and compliance burden. Hospital formulary committees weigh delivery mode against metabolite toxicity profiles, while regulatory scheduling constrains product type availability.
Product Type:
Upgrade cycles in synthetic opioid manufacturing favor formulations that reduce nursing burden and extend dosing intervals.
- Injectable:Hydrochloride salt solutions in ampoules and vials dominate perioperative protocols due to rapid bioavailability and precise titration. Demand concentrates in United States tertiary hospitals where DEA quota holders maintain supply security for institutional buyers constrained by Controlled Substances Act requirements.
- Extended-Release:Liposomal encapsulation and polymer-based matrix systems compress dosing frequency from hourly to four-to-six-hour intervals. Maternity wards in Germany and United States pilot these formulations for labor analgesia where prolonged duration reduces nursing workload without sacrificing offset control.
- Oral:Immediate-release tablets serve step-down protocols and ambulatory settings where injectable infrastructure is absent.
- Combination Formulations:Fixed-dose pairing with ondansetron or promethazine addresses opioid-induced nausea in single-administration protocols.
Injectable formulations sit at the top of the volume ranking, with Extended-Release climbing the fastest.
Application:
Clinical adoption patterns follow surgical volume recovery and obstetric protocol standardization across health systems.
- Post-Operative Pain:Perioperative protocols in hospital surgical suites drive consistent institutional demand where meperidine's short half-life permits rapid post-anesthesia recovery. United States hospital networks negotiate multi-year contracts on total-cost-of-care metrics bundling drug, delivery, and waste disposal.
- Labor Pain Relief:Obstetric analgesia applications exploit rapid onset and offset characteristics where neuraxial techniques are contraindicated or refused. Tertiary maternity wards in France and Italy favor formulations with complete cold-chain documentation under EMA pharmacovigilance requirements.
- Acute Pain Management:Emergency departments and trauma centers deploy for renal colic and acute musculoskeletal injury where morphine alternatives are preferred.
- Anesthesia:Adjunctive use in balanced anesthesia protocols where histamine release properties are clinically manageable.
Post-Operative Pain captures the largest revenue pool, with Labor Pain Relief expanding most quickly.
End User:
Procurement concentration determines contract structure and compliance infrastructure requirements.
- Hospitals:Consolidated purchasing by Catholic health systems and for-profit chains in the United States has centralized formulary decisions to regional pharmacy committees. Group purchasing organizations negotiate on bundled metrics that include controlled-substance vault security and DEA audit preparedness.
- Clinics:Ambulatory surgical centers and pain management clinics face tighter PDMP integration requirements and real-time prescription surveillance.
- Home Healthcare:Limited adoption due to norpethidine metabolite accumulation risks in unsupervised settings with renal impairment.
- Research Institutions:Academic medical centers and contract research organizations source for pharmacokinetic studies and comparator trials under DEA research registrations.
Hospitals dominate procurement volume, with Clinics gaining share fastest.
Delivery Mode:
Supply chain configuration and cold-chain requirements shape distribution economics across dosage forms.
- Injection:Intravenous and intramuscular routes via standard syringe or infusion pump remain the perioperative default. Hospital pharmacies in France and Italy now reject shipments lacking complete temperature excursion documentation under EMA strengthened GMP Annex 1 guidelines.
- Pre-filled Syringe:Ready-to-administer units reduce compounding burden and dosing error risk in high-acuity settings. United States manufacturers leverage injectable infrastructure to supply institutional buyers with lot-level traceability.
- Tablet:Oral solid dosage forms address cost-engineered protocols in India and Brazil where injectable infrastructure remains limited.
- Nasal Spray:Mucosal absorption formulations in early clinical evaluation for breakthrough pain in palliative settings.
Injection leads by volume, with Pre-filled Syringe showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmacists and controlled-substance compliance officers concentrate in hospital pharmacy clusters across major surgical hubs, anchoring demand geography to tertiary care centers with DEA quota access and perioperative volume.
United States
Hospital surgical volume recovery and consolidated purchasing by Catholic health systems drive institutional demand for injectable formulations. The DEA's annual production quotas and FDA scheduling requirements under the Controlled Substances Act constrain supply expansion regardless of demand signals. Tertiary hospitals in the Northeast Corridor and Midwest maintain dedicated vault security infrastructure for quota-holder distribution.
Germany
Maternity wards at university hospitals pilot liposomal extended-release formulations for labor analgesia protocols. EMA strengthened pharmacovigilance requirements under updated GMP Annex 1 guidelines mandate real-time temperature monitoring across the cold chain. Industrial pharmaceutical clusters in North Rhine-Westphalia and Bavaria host specialized opioid formulation manufacturers with established compliance infrastructure.
India
Cost-engineered oral tablet demand addresses acute pain protocols where injectable infrastructure remains limited in secondary cities. CDSCO manufacturing licensing and state-level drug control administration oversight shape market access for domestic producers. API production concentrates in Gujarat and Maharashtra, exposing buyers to customs friction and geopolitical supply risk.
Brazil
Emerging market expansion for solid dosage forms targets step-down pain management in ambulatory settings. ANVISA's controlled-substance tracking requirements and prescription monitoring program integration demand continuous IT investment from distributors. São Paulo and Rio de Janeiro anchor procurement concentration through hospital network consolidation and regional pharmacy committee centralization.
France
Hospital pharmacies reject shipments lacking complete temperature excursion documentation under EMA cold-chain mandates. ANSM oversight of narcotic distribution and CNIL data protection requirements for prescription monitoring create dual compliance burdens. The Île-de-France region concentrates tertiary maternity wards favoring formulations with rapid onset-offset characteristics for obstetric protocols.
Meperidine Market Vendor Landscape
Capital-heavy producers with injectable manufacturing infrastructure compete with asset-light formulation specialists licensing API supply. The market structure consolidates around incumbent quota holders protected by DEA production ceilings and controlled-substance distribution licensing. Three archetypes dominate: integrated pharmaceutical conglomerates with global manufacturing footprints, mid-cap specialists in generic opioid production, and emerging market cost-engineered tablet manufacturers. Competitive moves concentrate on multi-year hospital contract renegotiation and extended-release delivery system development.
Among established quota holders, Pfizer Inc. and Mallinckrodt Pharmaceuticals exemplify the integrated infrastructure archetype with DEA-secured supply chains for institutional buyers. Hikma Pharmaceuticals occupies a position representing cost-engineered oral solid dosage specialization for price-sensitive acute pain protocols. These three anchors illustrate how regulatory barriers preserve margin structures for incumbents with compliant vault security, audit preparedness, and cold-chain logistics capabilities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Mallinckrodt Pharmaceuticals |
| Boehringer Ingelheim International GmbH |
| Hikma Pharmaceuticals |
| Sandoz (Novartis AG) |
| Epic Pharma LLC |
| Sun Pharmaceuticals |
| Janssen Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
EMA cold-chain documentation mandates gate qualified supply access and premium-tier pricing for European hospital buyers, while DEA quota scarcity in the United States protects incumbent margin structures regardless of procurement pressure.
Pricing Analysis
Bundled total-cost-of-care contracts now dominate hospital network negotiations, displacing unbundled per-unit transactional pricing. Pricing stratifies across DEA quota-secured injectable formulations, extended-release liposomal premiums, and cost-engineered oral tablets for emerging markets. Price differentiation rests on compliance infrastructure certification and cold-chain assurance documentation. Procurement officers at Catholic health systems and for-profit chains exhibit highest price sensitivity, whereas tertiary maternity wards in Germany and France prioritize rapid onset-offset characteristics over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive liposomal formulations compress margin structures for distributors serving European maternity wards under EMA GMP Annex 1 guidelines. Active pharmaceutical ingredient production clusters in India and China, with formulation finishing in the United States and Germany. Supply chain risk centers on single-source vulnerability for pyridine derivative precursors subject to customs friction. Distribution runs through DEA-licensed controlled-substance wholesalers with vault security infrastructure for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States DEA quota scarcity and Indian CDSCO manufacturing cost advantages creates margin expansion opportunities for producers with dual-hemisphere compliance infrastructure.
For Market Incumbents: Deploy extended-release formulation R&D to capture labor analgesia premium positioning before patent cliffs erode injectable margins. Consolidate DEA quota allocations through strategic API supply agreements with Gujarat and Maharashtra producers to defend against Hikma Pharmaceuticals cost-engineered tablet competition. Reinforce cold-chain logistics partnerships with IoT-enabled European distributors to satisfy EMA pharmacovigilance mandates. For New Entrants and Emerging Players: Ambulatory surgical centers in Brazil's secondary cities represent the most penetrable buyer archetype, as ANVISA tracking requirements deter established quota holders from resource-intensive market development. Cost-engineered oral tablets for step-down acute pain protocols bypass injectable infrastructure constraints. Pursue licensing partnerships with domestic Brazilian distributors possessing existing controlled-substance IT integration capabilities. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap generic opioid specialists because DEA production ceilings prevent organic capacity expansion and force volume consolidation through acquisition. Five-to-ten year viability depends on extended-release pipeline depth and emerging market oral tablet registration portfolios. Monitor opioid litigation settlement precedents as balance-sheet risk inflection indicators for target screening.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Encapsulation Scale-Up | EMA maternity ward pilots in Germany validate four-to-six-hour dosing intervals for labor analgesia protocols. |
| DEA Quota Portfolio Consolidation | Mallinckrodt Pharmaceuticals and Pfizer Inc. acquisitions of smaller quota holders secure institutional supply security. |
| Combination Formulation Development | Fixed-dose ondansetron pairings command formulary preference by reducing polypharmacy complexity in perioperative settings. |
| Emerging Market Oral Tablet Registration | CDSCO and ANVISA approvals unlock cost-engineered demand in Indian and Brazilian ambulatory settings. |
| Cold-Chain IoT Logistics Deployment | Real-time temperature monitoring satisfies EMA GMP Annex 1 requirements for European hospital pharmacy acceptance. |
Methodological Framework
Multiple input streams — hospital formulary directors, DEA compliance officers, controlled-substance distribution executives, and API procurement managers — were reconciled against FDA scheduling databases, EMA pharmacovigilance filings, and CDSCO manufacturing license records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to validate segment-level estimates.
Historical surgical volume recovery patterns were cross-referenced against panel input from group purchasing organization contract managers to anchor demand assumptions across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and delivery mode, with regional regulatory cluster overlays for DEA, EMA, and CDSCO jurisdictions. CAGRs were derived from surgical procedure forecasting and obstetric protocol standardization trends.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than home healthcare adoption estimates where norpethidine toxicity limits addressable populations. Forecasts incorporate assumptions regarding DEA quota stability, opioid litigation settlement trajectories, and API supply chain resilience that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Disease-Modifying Agents Market