
 Influenza Antiviral Market | 2026-2036
Influenza Antiviral Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Antiviral Market Outlook
The EU Green Deal's pharmaceutical sustainability criteria is repositioning procurement standards across European healthcare systems, favoring manufacturers with reduced carbon footprints in active pharmaceutical ingredient synthesis. GSK leverages its established neuraminidase inhibitor portfolio to sustain contract volumes with national stockpile programs. Roche anchors its position through integrated diagnostic-to-treatment workflows that link influenza testing directly to antiviral prescribing protocols.
Influenza antivirals comprise synthetic small-molecule compounds targeting viral replication machinery, primarily neuraminidase inhibitors, cap-dependent endonuclease inhibitors, and polymerase acidic protein inhibitors, formulated as oral capsules, inhalation powders, or intravenous solutions for therapeutic intervention against influenza A and B strains. Oseltamivir dominates prescription volumes due to its oral bioavailability and established pediatric labeling, while baloxavir captures expanding share through single-dose convenience and novel mechanism of action against resistant variants. The route of administration dimension shows oral formulations commanding the largest patient-access footprint, though intravenous peramivir occupies a critical niche in hospitalized severe cases where enteral absorption is compromised.
The FDA, EMA, and WHO's prequalification program collectively shape market access through divergent evidentiary standards for antiviral efficacy endpoints and resistance surveillance requirements. Regulatory pressure for post-market resistance monitoring is intensifying manufacturing obligations for real-world pharmacovigilance data collection. Stakeholders must monitor how shifting pandemic threat levels recalibrate government stockpile rotation schedules and tender specifications.
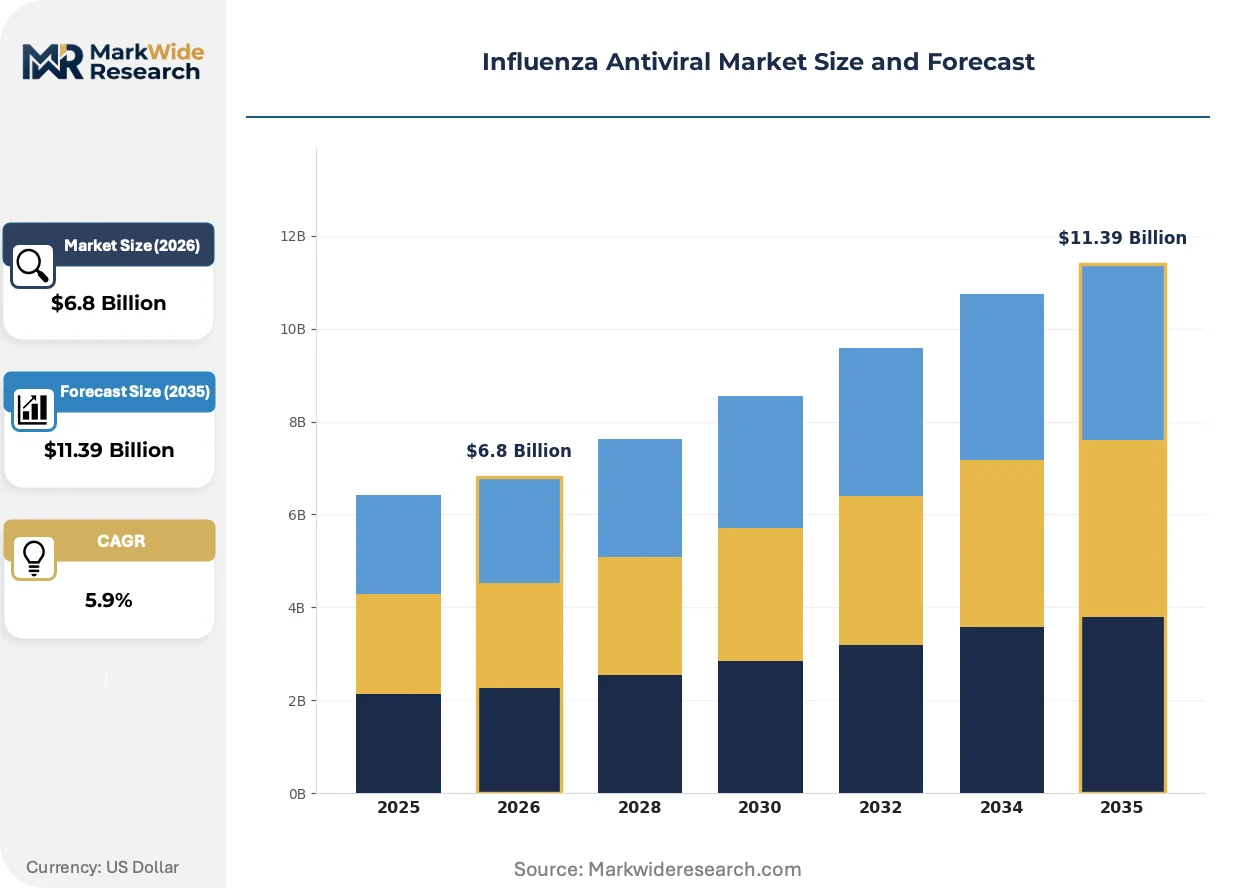
Market Dynamics
Hospital pharmacy formularies are expanding their antiviral coverage as seasonal influenza burden intensifies and diagnostic-to-treatment workflows compress prescribing timelines. The FDA's accelerated approval pathways for infectious disease therapies are reshaping competitive entry dynamics for novel mechanism agents.
Growth Catalysts
- Pandemic Preparedness Programs:National stockpiling agreements in the United States sustain procurement volumes through multi-year tender cycles. These programs create predictable demand anchors for manufacturers with established supply relationships.
- EMA Post-Market Resistance Surveillance:Regulatory pressure for real-world pharmacovigilance data collection is intensifying manufacturing obligations. This framework rewards sponsors with robust resistance monitoring infrastructure.
- Single-Dose Formulation Innovation:Novel cap-dependent endonuclease inhibitors are capturing share through reduced pill burden. Hospital pharmacies prioritize these agents for patient compliance and discharge efficiency.
Market Restraints
- API Synthesis Carbon Intensity:The EU Green Deal's pharmaceutical sustainability criteria is repositioning procurement standards across European healthcare systems. Manufacturers with elevated carbon footprints in active pharmaceutical ingredient production face tender disqualification.
- Neuraminidase Inhibitor Generic Saturation:Oseltamivir's patent expiration has compressed margins for originator compounds. Price erosion limits R&D reinvestment capacity across established product categories.
- Resistance Surveillance Infrastructure Costs:Real-world data collection requirements impose persistent operational overhead. Smaller sponsors struggle to sustain pharmacovigilance systems at regulatory scale.
Strategic Opportunities
- Integrated Diagnostic-Treatment Protocols:Point-of-care influenza testing linked directly to antiviral prescribing is streamlining hospital workflows. This convergence creates channel control opportunities for sponsors with companion diagnostic partnerships.
- Pediatric Formulation Gaps:Underpenetrated labeling for infants and neonates represents white space for novel agents with established safety profiles. Regulatory incentives for pediatric studies accelerate development timelines.
- Stockpile Rotation Modernization:Government programs are refreshing aging inventories with next-generation agents possessing extended shelf stability. Tender specifications increasingly favor thermostable formulations.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of virology, regulatory science, and health economics expertise remains thinly staffed. Sponsors compete for professionals capable of navigating accelerated approval pathways.
- Legacy Manufacturing Reconfiguration:Transitioning from batch to continuous processing for antiviral APIs demands substantial capital deployment. Facility upgrades must proceed without disrupting supply to stockpile programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Antiviral Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oseltamivir, Zanamivir, Baloxavir, Peramivir Route of Administration: Oral, Injection, Intranasal, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Retail, Wholesale, E-commerce, Direct |
| Companies Covered | Sanofi, Daiichi Sankyo Company, GSK, AstraZeneca, BioCryst Pharmaceuticals, Roche, Novartis, Seqirus, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Antiviral Market Strategic Shifts
Antiviral development is pivoting toward mechanism diversity as resistance surveillance reveals neuraminidase inhibitor vulnerabilities. Three structural shifts are compressing development timelines and reshaping competitive positioning.
Polymerase acidic protein inhibitors are overtaking neuraminidase inhibitors in late-stage pipelines through superior efficacy against resistant variants. Hospital systems in the United States are prioritizing these agents for severe influenza admissions. The mechanism's broader strain coverage is enabling sponsors to command premium positioning in national stockpile tenders.
The FDA's accelerated approval pathway for infectious disease therapies is compressing evidentiary requirements for novel antiviral agents. Sponsors now pursue smaller pivotal trials with surrogate endpoints. This regulatory flexibility most benefits developers of first-in-class mechanisms targeting pandemic threat strains.
Hospital procurement committees are consolidating antiviral purchasing through integrated diagnostic-to-treatment contracts. This bundled model displaces standalone pharmaceutical tenders. The shift is most visible in United States health systems where value-based reimbursement aligns prescribing with total episode costs.
Influenza Antiviral Market Segmentation
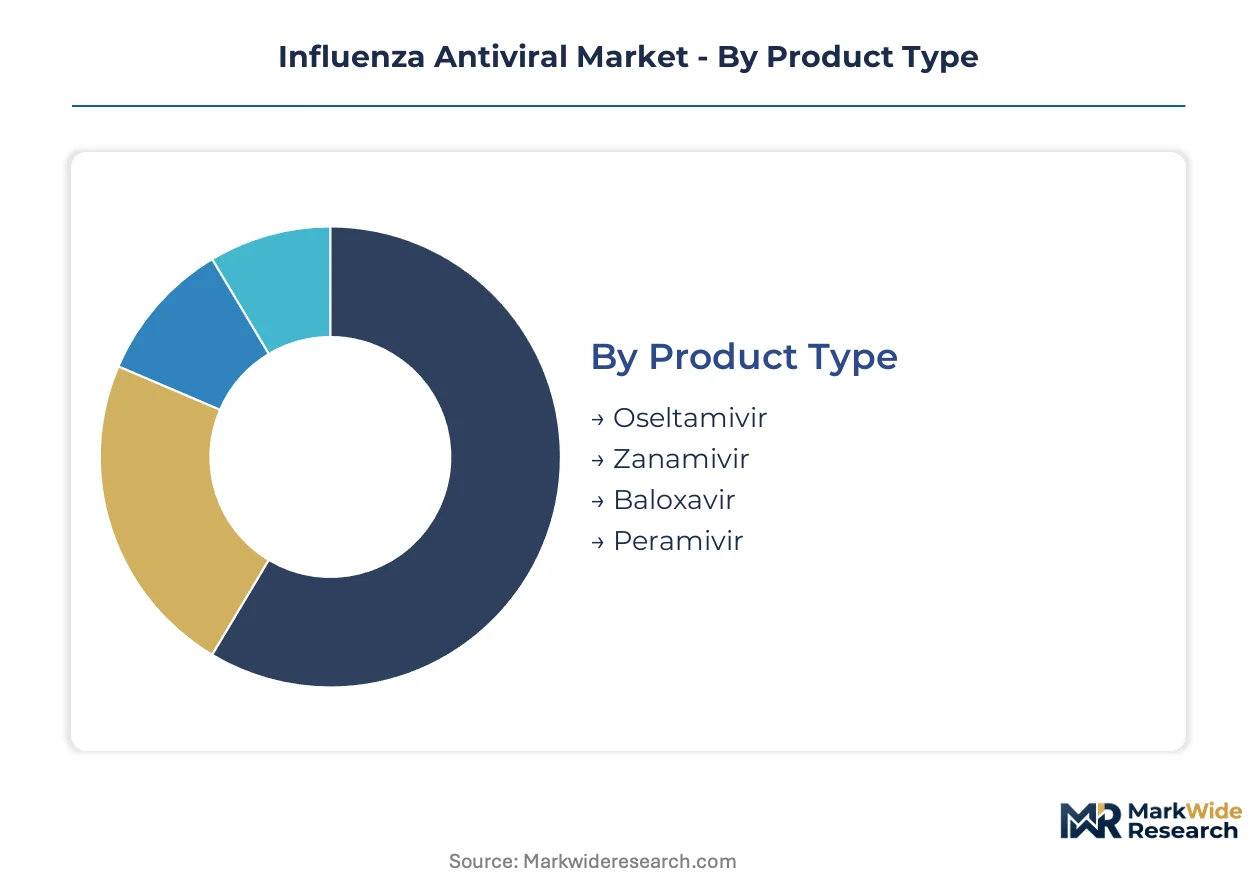
Segmentation in influenza antivirals reveals divergent capital requirements across synthesis complexity, formulation technology, and distribution infrastructure. Each dimension carries distinct investment profiles that shape competitive entry barriers and margin structures.
Product Type:
Capital intensity peaks with novel mechanism development, where synthesis pathways and resistance surveillance infrastructure demand sustained R&D deployment.
- Oseltamivir:Mature neuraminidase inhibitor produced through established catalytic hydrogenation routes. Hospital pharmacies in the United States anchor procurement through stockpile rotation contracts, though generic saturation has compressed originator margins.
- Baloxavir:Cap-dependent endonuclease inhibitor requiring complex polycyclic synthesis with stereoselective control. Single-dose convenience commands premium positioning in Japanese and US hospital formularies where discharge efficiency drives selection.
- Zanamivir:Neuraminidase inhibitor delivered via dry powder inhaler, demanding specialized micronization and device integration capabilities.
- Peramivir:Intravenous neuraminidase inhibitor for hospitalized severe cases, requiring aseptic manufacturing suites and cold-chain distribution.
Oseltamivir absorbs the bulk of installed capacity; baloxavir is expanding most quickly.
Route of Administration:
Formulation technology determines facility investment thresholds, with sterile injectable suites commanding multiples of oral solid dosage capital outlays.
- Oral:Capsule and tablet formulations dominate prescription volumes through manufacturing flexibility and patient self-administration. US retail pharmacies prioritize oral agents for seasonal influenza outpatient management.
- Injection:Intravenous solutions require isolator technology and terminal sterilization validation. Hospital intensive care units in Germany and France concentrate demand for IV peramivir in severe admissions.
- Intranasal:Mucosal delivery systems face formulation stability challenges and limited commercial penetration.
- Inhalation:Dry powder devices demand specialized engineering and patient training infrastructure.
Oral formulations capture the largest production footprint; injection routes gain share fastest in severe disease protocols.
End User:
Customer type shapes service intensity and contracting complexity, with hospital systems requiring the most sophisticated logistics and clinical support infrastructure.
- Hospitals:Integrated health systems consolidate antiviral purchasing through diagnostic-to-treatment contracts. US health networks bundle influenza testing with antiviral procurement to align with value-based reimbursement.
- Clinics:Outpatient facilities concentrate seasonal demand with rapid prescribing protocols.
- Homecare:Self-administered oral agents serve recovering patients with limited mobility.
- Pharmacies:Community and hospital dispensaries manage inventory rotation for seasonal surge patterns.
Hospitals anchor procurement volume; clinics demonstrate the steepest expansion trajectory in point-of-care diagnostic integration.
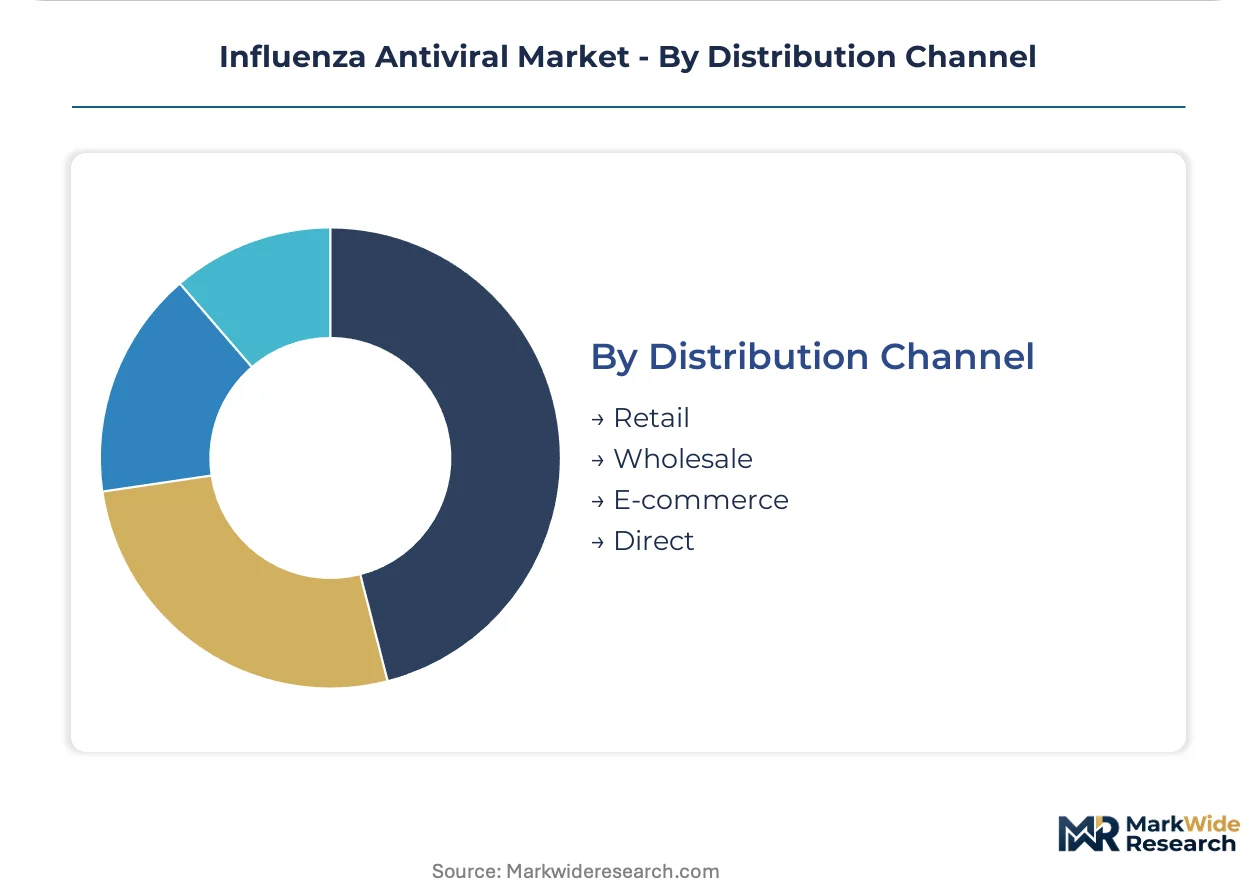
Distribution Channel:
Channel selection reflects product stability requirements and customer concentration, with direct tenders to government stockpile programs representing the most capital-efficient path to scale.
- Retail:Pharmacy chains and independent dispensaries manage seasonal demand fluctuation through inventory buffers.
- Wholesale:Distributors aggregate demand across fragmented endpoints with temperature-controlled logistics.
- E-commerce:Direct-to-patient platforms expand access for oral antivirals with established safety profiles.
- Direct:Manufacturers supply national stockpile programs through multi-year tenders with shelf-life specifications. The US Strategic National Stockpile contracts directly with GSK and Roche for neuraminidase inhibitor reserves.
Direct channels concentrate the highest contract values; e-commerce climbs fastest in post-pandemic patient preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American influenza antiviral development through its dense cluster of biotech research institutions and contract manufacturing organizations serving stockpile programs.
United States
The Strategic National Stockpile sustains multi-year procurement contracts for neuraminidase inhibitors and next-generation polymerase inhibitors. FDA accelerated approval pathways compress development timelines for novel mechanism agents. Maryland's BioHealth Capital Corridor concentrates manufacturing infrastructure for pandemic preparedness supplies.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia prioritize single-dose antivirals for discharge efficiency in seasonal influenza protocols. EMA post-market resistance surveillance requirements intensify pharmacovigilance obligations for German manufacturers. Frankfurt's pharmaceutical logistics hub coordinates distribution across Central European stockpile networks.
Japan
PMDA fast-track designations for pandemic threat countermeasures accelerate domestic approval timelines for cap-dependent endonuclease inhibitors. Tokyo's metropolitan hospital networks bundle influenza diagnostics with antiviral procurement contracts. Osaka's chemical synthesis corridor supplies active pharmaceutical ingredients for regional formulation facilities.
United Kingdom
NHS England's centralized procurement framework consolidates antiviral purchasing through integrated diagnostic-to-treatment contracts. MHRA resistance monitoring programs mandate real-world data collection from UK prescribing networks. London's biomedical research quarter hosts clinical trial infrastructure for novel antiviral development.
Switzerland
Swissmedic's streamlined review processes attract sponsors seeking rapid market authorization for innovative antiviral mechanisms. Basel's pharmaceutical cluster integrates polymerase inhibitor research with global distribution headquarters. Geneva's health security institutions coordinate international stockpile standardization protocols.
Influenza Antiviral Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established infectious disease franchises. Originators of novel mechanism agents command premium positioning through resistance profile differentiation. Two strategic archetypes dominate: integrated diagnostic-to-treatment platform operators and specialized antiviral developers with accelerated regulatory pathways. Capacity expansion in continuous API manufacturing and strategic partnerships for companion diagnostic integration represent the dominant competitive moves.
Among diversified pharmaceutical conglomerates, GSK and Roche occupy positions exemplifying the integrated platform archetype, while BioCryst Pharmaceuticals represents the specialized development model. These entities anchor competitive dynamics through contrasting approaches to stockpile contracting and hospital formulary access.
| Leading Market Players |
|---|
| Sanofi |
| Daiichi Sankyo Company |
| GSK |
| AstraZeneca |
| BioCryst Pharmaceuticals |
| Roche |
| Novartis |
| Seqirus |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's pharmaceutical sustainability criteria gates qualified supply access and premium-tier pricing authorization for influenza antiviral manufacturers. Carbon-intensive API synthesis routes face tender disqualification across European hospital systems, compressing margins for non-compliant producers while rewarding green chemistry investments with formulary preference.
Pricing Analysis
Value-based contracts anchored to patient discharge efficiency and resistance-profile outcomes command premium positioning in United States health system procurement. Three-tier pricing structure across premium novel mechanisms, standard neuraminidase inhibitors, and economy generic oseltamivir segments the market by clinical differentiation and regulatory exclusivity. Price erosion runs through the generic oseltamivir tier due to patent expiration and multi-source competition, while single-dose baloxavir maintains pricing power through convenience premiums. Hospital pharmacy committees demonstrate lowest price sensitivity for severe-case IV formulations where therapeutic urgency overrides cost considerations.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and Memphis coordinate hub-and-spoke patterns for temperature-sensitive antiviral finished goods. Active pharmaceutical ingredient production draws from India, China, and Switzerland for key intermediate synthesis and final crystallization stages. Supply chain vulnerability centers on single-source dependencies for cap-dependent endonuclease inhibitor polycyclic building blocks and specialized neuraminidase inhibitor catalytic hydrogenation catalysts. Distribution runs through direct government stockpile tenders for strategic reserves alongside wholesale channels for seasonal commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The influenza antiviral market operates as a cost-of-compliance arena where EMA post-market resistance surveillance requirements erect substantial barrier-to-entry moats. Regulatory infrastructure investment separates viable competitors from marginal players.
For Market Incumbents: Deepen backward integration into continuous API manufacturing to secure supply continuity for stockpile contracts while lowering carbon intensity scores for EU tender eligibility. Consolidate diagnostic-to-treatment platform control through companion testing partnerships that lock hospital formulary positioning against polymerase inhibitor entrants. Prioritize pediatric label expansion to capture white-space prescribing in neonatal intensive care units.
For New Entrants and Emerging Players: Hospital pharmacy benefit managers represent the most accessible channel partner type for novel mechanism agents seeking rapid formulary placement. Target underpenetrated clinic-based point-of-care diagnostic integration where prescribing protocols remain less consolidated than hospital networks. Pursue pandemic threat strain fast-track designations to compress development timelines and command premium stockpile positioning.
For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization for infectious disease therapies is the leading indicator that development-stage assets possess viable commercialization trajectories. Focus acquisition screening on specialized antiviral developers with robust resistance surveillance infrastructure and established pharmacovigilance systems. Watch for government stockpile rotation schedule announcements as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Links influenza testing directly to antiviral prescribing protocols in US health systems. |
| Pediatric Label Expansion | Captures neonatal and infant prescribing white space with regulatory incentive acceleration. |
| Continuous API Manufacturing Transition | Reduces carbon footprint for EU Green Deal compliance and tender qualification. |
| Stockpile Rotation Contract Renewal | Secures multi-year revenue anchors through US Strategic National Stockpile agreements. |
| Resistance Surveillance Infrastructure Buildout | Satisfies EMA post-market obligations and differentiates against generic competitors. |
Study Parameters
Multi-period observation of formulary placement trends, stockpile tender awards, and resistance surveillance reporting anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and national stockpile program disclosures. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation ensured cross-verified demand estimation.
Input-output matrix framing connected patient population segmentation, route of administration technology tiers, and regional regulatory clusters to value projections across the analysis window. CAGRs were derived from segmented growth rate blending and epidemiological burden modeling. Forecast inputs incorporated seasonal influenza severity indices, pandemic preparedness funding appropriations, and generic entry timing assumptions for patent-expired compounds.
Caveats apply where pandemic threat level recalibrations, accelerated approval pathway policy shifts, or API synthesis carbon accounting standard changes could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Antimalarial Drugs Market