
 Defense Aircraft Aviation Fuel Market | 2026-2036
Defense Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Aircraft Aviation Fuel Market Insights
Specialized refinery engineering talent is rotating toward military-specification fuel production as commercial aviation demand softens and defense budgets expand. Exxon Mobil Corp. leverages its integrated upstream-to-downstream infrastructure to secure long-term supply agreements with Pentagon procurement channels. Shell plc sustains its position through dedicated military fuel blending capabilities that meet stringent thermal stability requirements for supersonic platforms. BP Plc anchors its defense portfolio with NATO-aligned logistics networks spanning multiple continental European airbases.
Defense aircraft aviation fuel encompasses refined petroleum formulations engineered to deliver specific energy density, freeze point, and thermal stability parameters for military turbine engines, typically requiring flash points above thirty-eight degrees Celsius and sulfur content below three thousand parts per million to ensure operational reliability across extreme altitudes and temperatures. Jet A and JP-8 dominate current procurement volumes due to established logistics infrastructure and broad engine compatibility, while JP-5 maintains specialized demand from carrier-based naval aviation where flash point safety thresholds exceed sixty degrees Celsius to mitigate shipboard fire risks. Fighter jet applications command premium pricing relative to transport plane segments due to higher performance specifications and lower batch volumes.
The United States Environmental Protection Agency and the Federal Aviation Administration jointly shape fuel formulation standards through emissions testing protocols and alternative fuel certification pathways, while NATO's single fuel policy mandates interoperability standards across allied air forces. The European Union F-Gas Regulation and REACH framework increasingly influence additive package compositions for fuels supplied to European defense ministries. Stakeholders must monitor sustainable aviation fuel blending mandates as military branches evaluate drop-in biofuel compatibility without compromising mission-critical performance thresholds.
Market Dynamics
NATO's single fuel policy mandate is compressing formulation diversity across allied air forces while simultaneously accelerating additive package standardization requirements for interoperability. Defense ministries now face procurement trade-offs between thermal performance optimization and logistics simplification.
Growth Catalysts
- JP-8 logistics standardization:NATO's single fuel policy eliminates multi-fuel storage complexity across allied European airbases, streamlining cross-border operational coordination.
- Carrier aviation safety thresholds:Naval aviation's JP-5 flash point requirements above sixty degrees Celsius sustain specialized refinery capacity investments for shipboard fire risk mitigation.
- Thermal efficiency protocols:Tightening jet engine emissions standards under EPA and FAA joint certification pathways force continuous reformulation investments in high-performance turbine fuels.
Market Restraints
- Crude feedstock volatility:Defense fuel producers face margin compression from unhedged sweet crude price swings, with kerosene yield constraints limiting production flexibility.
- Specialized refinery concentration:Military-specification hydroprocessing capacity clusters disproportionately along the US Gulf Coast, creating geographic supply vulnerability.
- Drop-in biofuel compatibility limits:Current sustainable aviation fuel blends fail to meet supersonic platform thermal stability thresholds, blocking alternative feedstock adoption.
Strategic Opportunities
- EU F-Gas Regulation alignment:European defense ministries must reformulate additive packages to comply with fluorinated gas restrictions, opening reformulation service contracts.
- Synthetic fuel pathway development:Power-to-liquid processes using captured carbon and renewable hydrogen converge with military drop-in fuel certification requirements.
- Strategic reserve privatization:NATO member states are outsourcing strategic petroleum reserve management to integrated oil majors with existing storage infrastructure.
Industry Challenges
- Hydroprocessing engineering scarcity:Military-specification fuel production requires specialized catalytic reforming expertise that commercial aviation downsizing has depleted.
- Multi-jurisdictional certification timelines:Simultaneous EPA, FAA, and NATO fuel qualification protocols extend product approval cycles beyond operational planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Aircraft Aviation Fuel Market |
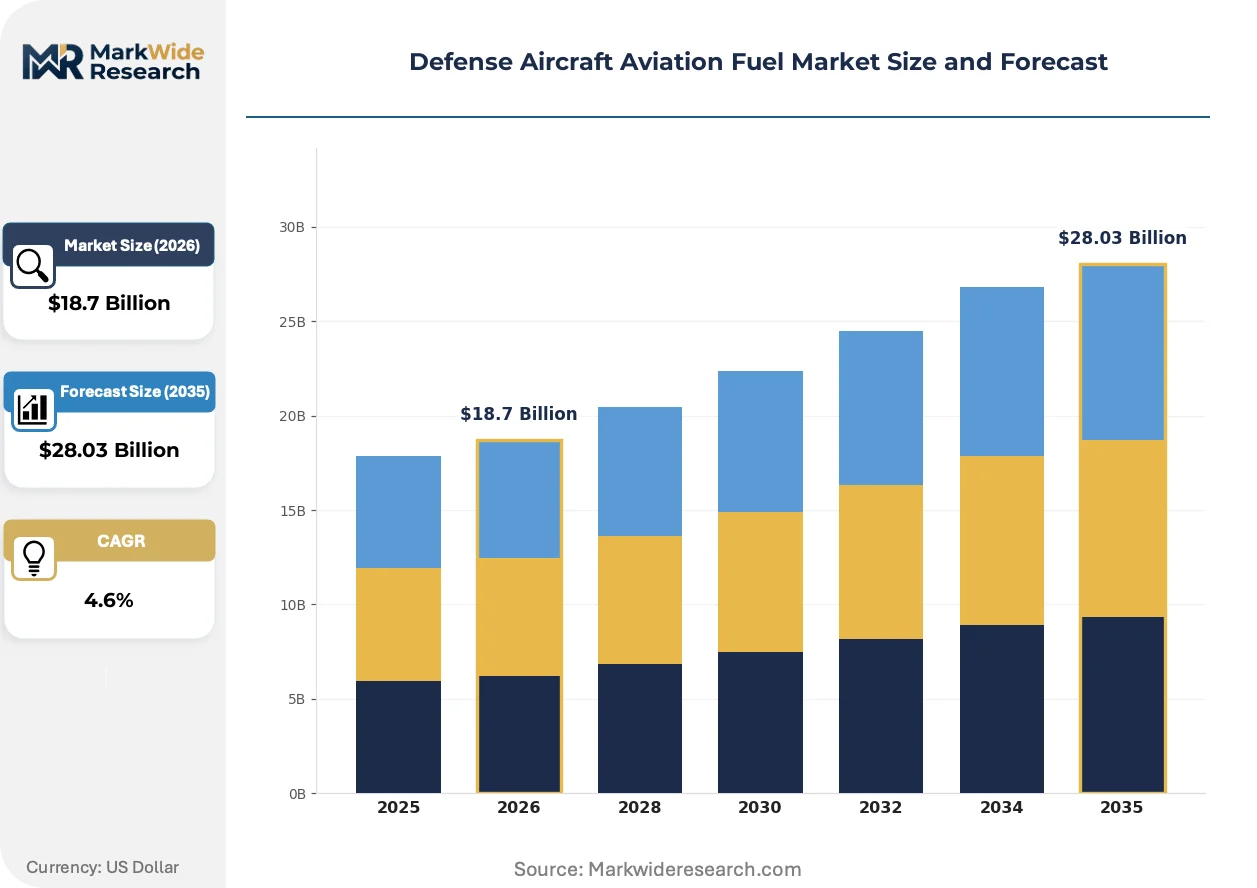
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet B, JP-5, JP-8, TS-1 Application: Fighter Jets, Surveillance Aircraft, Transport Planes, Training Aircraft, Reconnaissance Planes End User: Air Force, Naval Aviation, Army Aviation, Coast Guard Aviation Deployment Environment: Carrier-Based, Land-Based, Forward Operating Base, Remote Airstrip |
| Companies Covered | Exxon Mobil Corp., Chevron Corp., BP Plc, Shell plc, TotalEnergies SE, Emirates National Oil Co., Honeywell International Inc., Indian Oil Corp. Ltd., Valero Energy Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Aircraft Aviation Fuel Market Trends and Innovations
Fuel formulation science is splitting along performance-versus-sustainability fault lines as military operators confront incompatible certification requirements. Technical investment patterns reveal divergent pathways between legacy turbine optimization and next-generation propulsion compatibility.
Advanced thermal stability additive packages are bifurcating the fighter jet fuel segment from transport aviation procurement. Fifth-generation combat aircraft operators demand customized formulations with enhanced oxidative resistance for sustained supersonic flight profiles, while strategic airlift commands prioritize cost-optimized Jet A variants. This performance tiering is compressing mid-specification product viability and forcing suppliers to choose specialization lanes.
REACH framework enforcement through ECHA is restricting aromatic compound concentrations in fuels supplied to European defense ministries. The industrial consequence mandates reformulation of traditional JP-8 blends to reduce polycyclic aromatic hydrocarbon content without degrading lubricity performance. Fighter squadrons based in Germany and Italy face the steepest compliance timelines as national procurement agencies align with EU chemical safety registrations.
Defense fuel contracting is consolidating toward decade-long supply agreements with integrated producers who control upstream crude access. The spot market and independent distributor channel is contracting as Pentagon procurement and NATO support agency buyers prioritize supply security over price competition. This preference shift is most visible in United States Department of Defense bulk fuel acquisitions, where three-year rolling contracts now dominate single-year tenders.
Defense Aircraft Aviation Fuel Market Segmentation
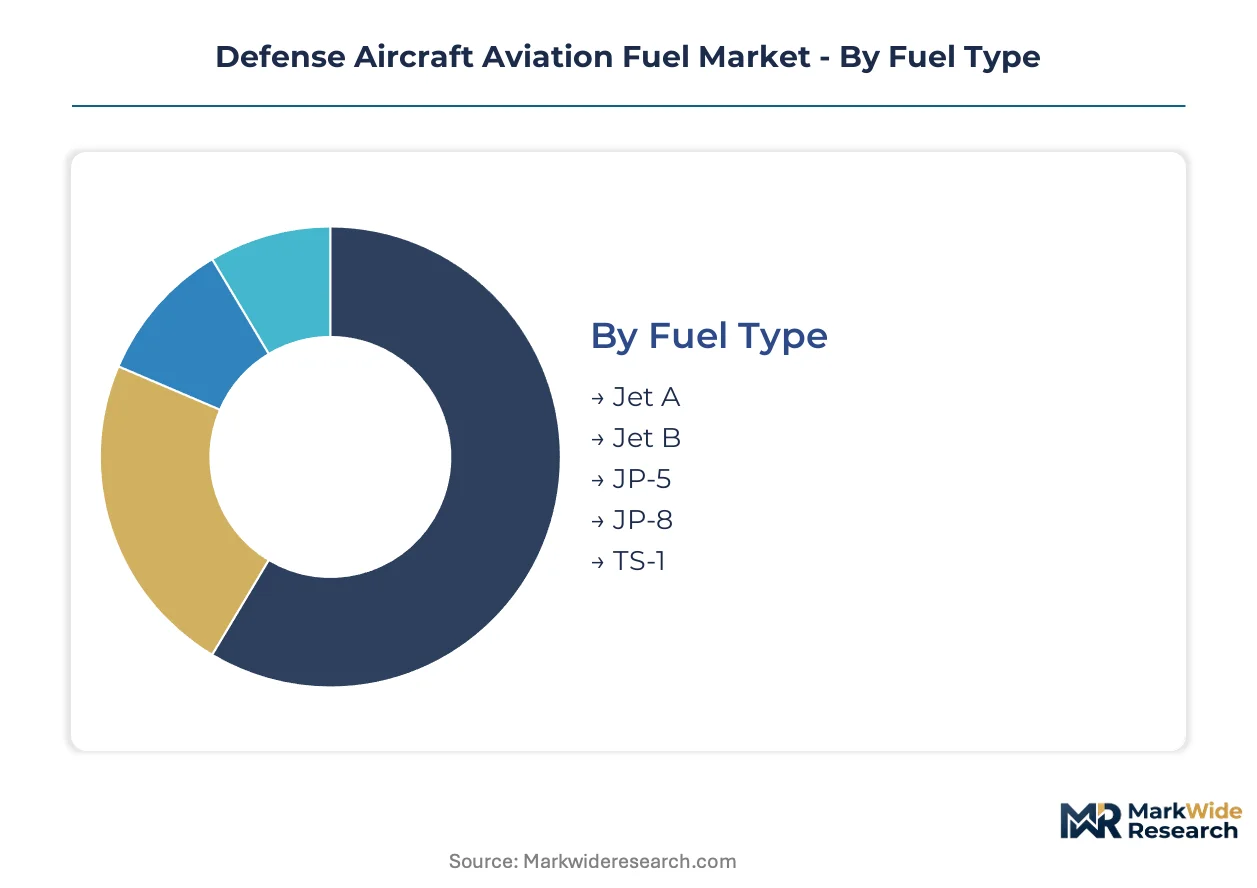
Military procurement channels route different fuel specifications through distinct logistics networks. Understanding segment boundaries clarifies why JP-8 dominates NATO airbases while JP-5 remains captive to naval supply chains. Segmentation reveals where formulation complexity translates into pricing power versus commodity competition.
Fuel Type:
Channel distribution splits sharply between NATO-standardized grades and specialized naval formulations, with each fuel type commanding dedicated storage infrastructure and separate procurement contracts.
- Jet A:Commercial-grade kerosene with flash point minimum of thirty-eight degrees Celsius serves as cost-optimized baseline for transport aviation and training fleets. Demand concentrates in United States Air Force strategic airlift commands where bulk purchasing prioritizes logistics economy over thermal performance margins.
- JP-8:Military-specification kerosene incorporating corrosion inhibitors and anti-icing additives dominates NATO single-fuel policy procurement. United States European Command airbases in Germany and Italy drive volume as alliance interoperability mandates eliminate multi-fuel storage complexity.
- Jet B:Wide-cut gasoline-kerosene blend with enhanced cold-weather fluidity addresses Arctic and high-altitude operations. Alaskan Command and Norwegian Air Force procurement sustains niche demand.
- JP-5:High-flash-point formulation exceeding sixty degrees Celsius serves carrier-based naval aviation exclusively. United States Navy Pacific Fleet requirements anchor production at Gulf Coast refineries with shipboard fire safety certification.
- TS-1:Russian-origin kerosene grade with freeze point below minus sixty degrees Celsius persists in former Soviet bloc inventories. Limited procurement flows through legacy supply agreements with Central Asian defense ministries.
By volume, JP-8 leads. By growth pace, JP-5 is ahead as Indo-Pacific carrier presence expands.
Application:
Performance tiering separates fighter jet procurement—where thermal stability commands premium pricing—from transport aviation's cost-optimized bulk purchasing.
- Fighter Jets:Fifth-generation combat aircraft demand customized formulations with enhanced oxidative resistance for sustained supersonic profiles. United States Air Force F-35 squadrons in Nevada and Arizona anchor demand as thermal efficiency protocols tighten.
- Transport Planes:Strategic airlift commands prioritize Jet A variants with established logistics infrastructure. Air Mobility Command operations from Dover Air Force Base sustain high-volume, low-margin procurement patterns.
- Surveillance Aircraft:Long-endurance platforms require fuel stability across extended loiter missions. NATO Airborne Early Warning Force rotations in Germany concentrate demand.
- Training Aircraft:Flight school fleets consume standardized grades with minimal additive packages. Sheppard Air Force Base and Naval Air Station Whiting Field represent anchor accounts.
- Reconnaissance Planes:High-altitude platforms need freeze point performance below minus forty degrees Celsius. Beale Air Force Base U-2 operations sustain specialized blending requirements.
Transport planes generate largest procurement tonnage. Fighter jets capture steepest expansion trajectory as fifth-generation fleet modernization accelerates.
End User:
Service branch procurement authority determines specification stringency, with naval aviation's shipboard safety requirements imposing the tightest formulation constraints.
- Air Force:Dominates bulk fuel contracting through Defense Logistics Agency Energy, with single-fuel policy standardization reducing formulation diversity across continental United States bases.
- Naval Aviation:Carrier-based operations mandate JP-5 exclusively, creating captive demand insulated from price competition through shipboard fire risk protocols.
- Army Aviation:Rotary-wing and fixed-wing platforms accept NATO-standard grades, with Army Aviation Center at Fort Rucker consolidating training fleet procurement.
- Coast Guard Aviation:Search-and-rescue platforms prioritize cold-weather performance for Arctic patrols, with Kodiak Air Station driving Alaska-specific requirements.
Air Force procurement leads by volume. Naval Aviation is gaining share fastest as Pacific carrier strike group deployments intensify.
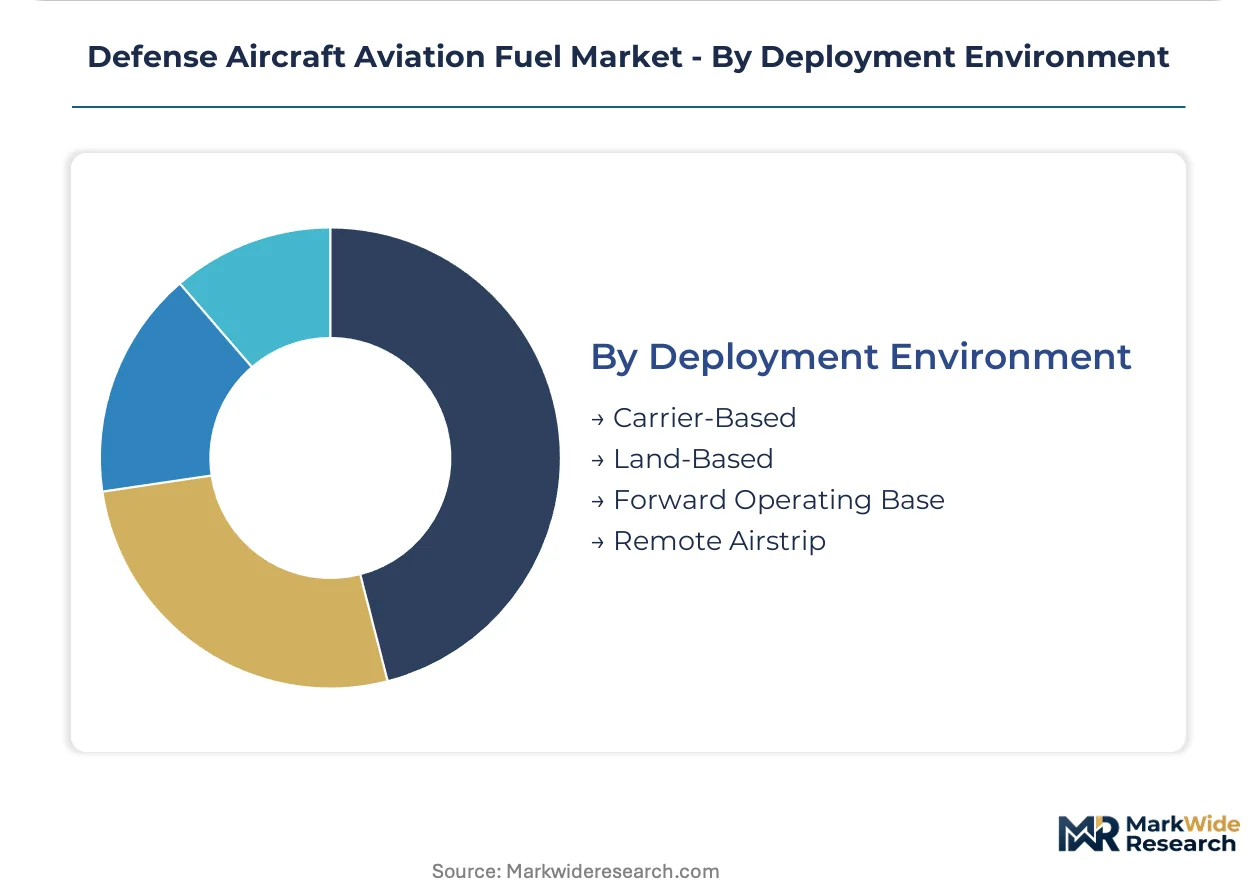
Deployment Environment:
Logistics infrastructure availability dictates fuel specification flexibility, with austere locations forcing compatibility trade-offs against performance optimization.
- Carrier-Based:Shipboard storage constraints and fire safety protocols restrict fuels to JP-5 exclusively, creating highest per-gallon procurement costs in military aviation.
- Land-Based:Established NATO airbase infrastructure enables single-fuel policy compliance with JP-8 standardization across Ramstein, Aviano, and Spangdahlem installations.
- Forward Operating Base:Expeditionary logistics favor drop-in compatible grades minimizing specialized handling equipment. United States Central Command operations in Kuwait and Qatar stress interoperability.
- Remote Airstrip:Limited storage capacity and irregular resupply intervals prioritize stability and contamination resistance. Pacific Air Forces operations across dispersed island chains drive demand.
Land-based deployment leads by volume. Carrier-based operations climb the fastest as naval presence expands in contested maritime zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA and FAA jointly anchor formulation standards in the United States, the dominant geography where Pentagon procurement channels drive volume concentration. Military jet fuel demand clusters around defense infrastructure and carrier strike group deployment patterns across three continents.
United States
Defense Logistics Agency Energy contracts sustain the world's largest military jet fuel consumption footprint. The EPA's emissions testing protocols and FAA alternative fuel certification pathways tighten thermal efficiency standards continuously. Gulf Coast refineries concentrate specialized hydroprocessing capacity for JP-5 production serving Pacific Fleet carrier operations.
Germany
Ramstein and Spangdahlem airbases drive NATO single-fuel policy procurement volumes for allied interoperability. ECHA's REACH framework restricts aromatic compound concentrations, forcing JP-8 reformulation to reduce polycyclic aromatic hydrocarbon content. Bavaria-based logistics hubs coordinate bulk fuel distribution across Central European defense corridors.
United Kingdom
Royal Air Force strategic airlift commands prioritize Jet A variants for cost-optimized bulk purchasing. The UK Environment Agency aligns with EU F-Gas Regulation restrictions on fluorinated additives in military fuel packages. RAF Brize Norton anchors high-volume procurement for transport aviation segments.
Japan
Air Self-Defense Force F-35 squadrons generate premium demand for thermally stable fighter jet formulations. METI oversees energy security frameworks that shape strategic petroleum reserve management policies. Okinawa-based Pacific Air Forces installations stress interoperability with United States supply chains.
Saudi Arabia
Joint military aviation operations with allied forces sustain demand for NATO-standard fuel grades. The Saudi Standards, Metrology and Quality Organization aligns national procurement with international certification protocols. Eastern Province refining clusters position product for Red Sea and Persian Gulf carrier logistics.
Defense Aircraft Aviation Fuel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the defense fuel supply base. Integrated oil majors with upstream crude access dominate long-term contracting through captive infrastructure, while specialized refiners compete on formulation customization. The market structure bifurcates between scale-driven bulk suppliers and niche military-specification blenders. Dominant competitive moves include strategic reserve privatization agreements and decade-long supply contract consolidation.
Among United States-based integrated majors, Exxon Mobil Corp. and Chevron Corp. exemplify the upstream-anchored archetype with Gulf Coast refining concentration. Shell plc and BP Plc represent European-headquartered competitors leveraging NATO-aligned logistics networks. Emirates National Oil Co. occupies a position as a regional specialist serving Middle Eastern defense procurement channels.
| Leading Market Players |
|---|
| Exxon Mobil Corp. |
| Chevron Corp. |
| BP Plc |
| Shell plc |
| TotalEnergies SE |
| Emirates National Oil Co. |
| Honeywell International Inc. |
| Indian Oil Corp. Ltd. |
| Valero Energy Corp. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day strategic fuel reserve rotations anchor procurement economics to Gulf Coast refinery capacity concentration, compressing price negotiation leverage for NATO-aligned buyers while amplifying margin capture for integrated producers with captive hydroprocessing assets.
Pricing Analysis
Gulf Coast JP-5 production commands a fifteen-to-twenty percent premium over European NATO airbase Jet A deliveries, reflecting shipboard fire safety certification thresholds and specialized storage infrastructure requirements. Contract-based long-term offtake agreements dominate Pentagon procurement through Defense Logistics Agency Energy, with price differentiation driven by thermal stability certification grades and volume scale commitments. Cost compression in transport aviation segments is intensifying because commercial aviation demand softening releases surplus Jet A capacity into military channels. Strategic airlift commands exhibit highest price sensitivity due to bulk purchasing mandates, while carrier-based naval aviation remains least sensitive given JP-5's captive supply structure.
Supply Chain Analysis
Strait of Hormuz transit underwrites approximately one-third of global military kerosene feedstock movements, exposing NATO European commands to maritime chokepoint vulnerability. Production clusters disproportionately in the United States, Saudi Arabia, and Singapore, with hydroprocessing capacity drawing from sweet crude, catalytic reforming catalysts, and corrosion inhibitor additive packages. Single-source vulnerability concentrates in Gulf Coast military-specification refineries, where hurricane season disruptions have historically constrained JP-5 availability for Pacific Fleet operations. Distribution runs through defense logistics agency fuel terminals, NATO central European pipeline networks, and forward operating base pre-positioned stockpiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
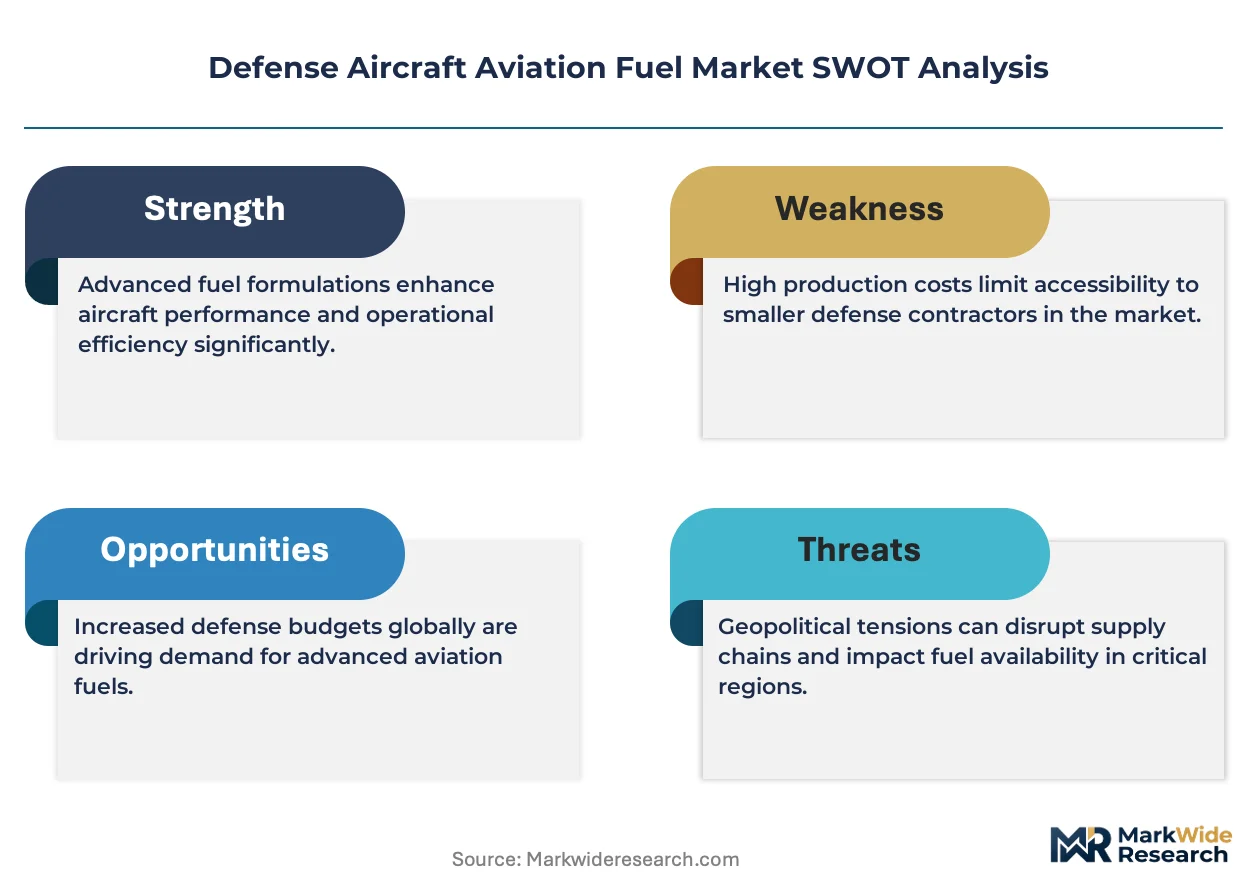
NATO's single fuel policy functions as a platform standardization inflection, where interoperability mandates are compressing formulation diversity and privileging suppliers with NATO-aligned certification infrastructure across multiple continental European airbases.
For Market Incumbents: Consolidate additive package formulation capabilities through captive blending facility investments in Germany and Italy, where REACH framework enforcement tightens fastest. Secure decade-long NATO support agency contracts before EU F-Gas Regulation alignment deadlines eliminate independent distributor channels. Vertical integration into strategic petroleum reserve management contracts insulates against spot market contraction. For New Entrants and Emerging Players: Lead with synthetic fuel pathway development targeting power-to-liquid certification gaps, where current sustainable aviation fuel blends fail supersonic platform thresholds. Penetrate the fighter jet formulation segment through customized oxidative resistance packages for fifth-generation fleet operators in Nevada and Arizona. Pursue joint qualification pathways with Pentagon procurement channels as the fastest route to volume scale. For Investors and Strategic Acquirers: Long-term, this sits as a defense-contracting oligopoly play because decade-long supply agreement consolidation is compressing independent refiner viability and privileging upstream-integrated majors with NATO logistics networks. Target acquisition profiles should emphasize hydroprocessing engineering talent pools and existing NATO single-fuel policy certification. Watch JP-5 demand trajectories from Indo-Pacific carrier strike group deployment schedules as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement Consolidation | Defense Logistics Agency Energy contracts now favor three-year rolling structures over annual tenders. |
| Backward Integration into Additive Manufacturing | REACH compliance drives captive production of low-aromatic corrosion inhibitor packages. |
| Synthetic Fuel Certification Investment | Power-to-liquid pathways align with military drop-in fuel requirements and EPA alternative certification. |
| Strategic Reserve Privatization | NATO member states outsource petroleum reserve management to integrated oil majors with existing infrastructure. |
| Specialized Refinery Capacity Expansion | Gulf Coast hydroprocessing investments target JP-5 production for Pacific Fleet carrier operations. |
Research Methodology
A standing panel of refinery operations directors, Defense Logistics Agency Energy procurement officers, NATO support agency fuel specialists, and ECHA regulatory affairs consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA emissions testing protocols, FAA alternative fuel certification filings, NATO single-fuel policy documentation, and customs trade data tracking military kerosene movements. Bottom-up segment modeling triangulated against top-down macroeconomic demand projections for defense aviation activity.
Consistency checks validated volume and value outputs against external benchmarks from EIA refinery capacity reports and IEA military energy consumption assessments. The analytical framework segmented across fuel type, application, end user, and deployment environment dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical procurement volumes correlated with defense budget appropriations and fleet modernization timelines. Fighter jet thermal stability requirements and carrier aviation safety thresholds served as industry-specific demand drivers in the projection model.
Forecasts assume regulatory continuity in EPA-FAA joint certification pathways and EU REACH framework enforcement; material policy shifts in F-Gas Regulation timelines or NATO single-fuel policy scope would require re-modeling. Practitioners should keep alternative scenarios live as sustainable aviation fuel blending mandates and synthetic fuel certification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Mobile Fuel Delivery Market
Fuels
Fuel Grinder Market
Fuels
Gas Hydrates Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Industrial Fuel Filter Market
Fuels
UAE Chemical Logistics Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Charcoal Briquette Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
India LNG Market
Fuels
South Korea LNG Bunkering Market
Fuels
Solid Recovered Fuel Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Refuse Derived Fuel Market
Fuels
High Octane Racing Fuel Market
Fuels
Global Turbine Oil Market