
 UAE Chemical Logistics Market | 2026-2036
UAE Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Chemical Logistics Market Insights
The shift from captive in-house fleets toward outsourced specialist operators is recalibrating procurement patterns across UAE chemical corridors. Servochem L.L.C. anchors its position through dedicated bulk liquid storage at Jebel Ali Free Zone. CEVA Logistics competes on temperature-controlled polymer distribution networks serving Saudi-border manufacturing clusters. Agility Logistics leverages integrated customs brokerage with warehousing to reduce port dwell times for fertilizer importers.
Chemical logistics encompasses the specialized movement, storage, and handling of hazardous and non-hazardous chemical products under controlled conditions including temperature regulation, segregation protocols, and UN-classified packaging standards. The primary purpose centers on maintaining product integrity while ensuring safety compliance across multimodal supply chains. Transportation services dominate current revenue pools given the UAE's hub-and-spoke geography connecting Gulf petrochemical producers to East African and South Asian markets. Warehousing exhibits the fastest structural expansion as ADNOC and Borouge downstream projects generate demand for ISO-tank staging and bonded chemical yards. Freight forwarding retains mature margin profiles concentrated among operators with in-house dangerous goods certification capabilities.
MOHAP pharmaceutical licensing requirements and the UAE's Federal Transport Authority hazardous materials codes shape facility standards and driver certification across chemical logistics operations. Dubai Municipality's chemical storage zoning regulations and the International Maritime Organization's IMDG Code enforcement at Jebel Ali Port dictate capital deployment toward compliant infrastructure. Stakeholders must monitor how Abu Dhabi National Oil Company's Ruwais Derivatives Park expansion reshapes volume flows and whether Saudi Arabia's Neom chemical cluster diverts transshipment cargo from UAE ports.
Market Dynamics
ADNOC's downstream expansion at Ruwais Derivatives Park is redirecting chemical cargo flows through Abu Dhabi ports, forcing logistics operators to rebalance Jebel Ali-centric capacity toward integrated multimodal corridors serving polymer and specialty chemical exporters.
Growth Catalysts
- Dual carbon goals:UAE federal mandates for net-zero emissions by 2050 accelerate demand for ISO-tank cleaning and vapor recovery systems at bulk liquid terminals. Petrochemical producers now require certified green logistics partners.
- Borouge expansion:The polyolefin producer's capacity additions generate dedicated warehousing demand for polymer pellet staging and temperature-controlled storage near conversion facilities.
- IMDG Code enforcement:Stricter International Maritime Organization hazardous materials handling at Jebel Ali Port elevates compliance barriers, concentrating volume with certified dangerous goods specialists.
Market Restraints
- Specialized asset scarcity:Bonded chemical yards with fire suppression and containment systems require capex intensity that limits new entrants, entrenching incumbent positions.
- Driver certification bottlenecks:UAE Federal Transport Authority hazardous materials codes mandate specialized licensing, constraining available labor pools for bulk liquid transport.
- Port concentration risk:Over 70 percent of chemical throughput moves through Jebel Ali, creating vulnerability to congestion or regulatory disruption at a single node.
Strategic Opportunities
- Kizad chemical zone:Khalifa Industrial Zone Abu Dhabi offers undeveloped land parcels for integrated logistics parks serving Ruwais downstream clusters with direct rail connectivity.
- Digital freight matching:Platforms connecting ISO-tank operators with shippers reduce empty backhaul rates and improve asset utilization across the Emirates.
- East African corridor:Polymer distributors targeting Kenya and Tanzania manufacturing bases seek UAE-based consolidation hubs with customs pre-clearance capabilities.
Industry Challenges
- Warehouse management system integration:Legacy ERP platforms at family-owned distributors resist API connectivity with modern yard management and customs brokerage software.
- Fire safety engineering talent:Shortage of professionals certified to NFPA 30 flammable liquids codes delays facility commissioning and permit approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Chemical Logistics Market |
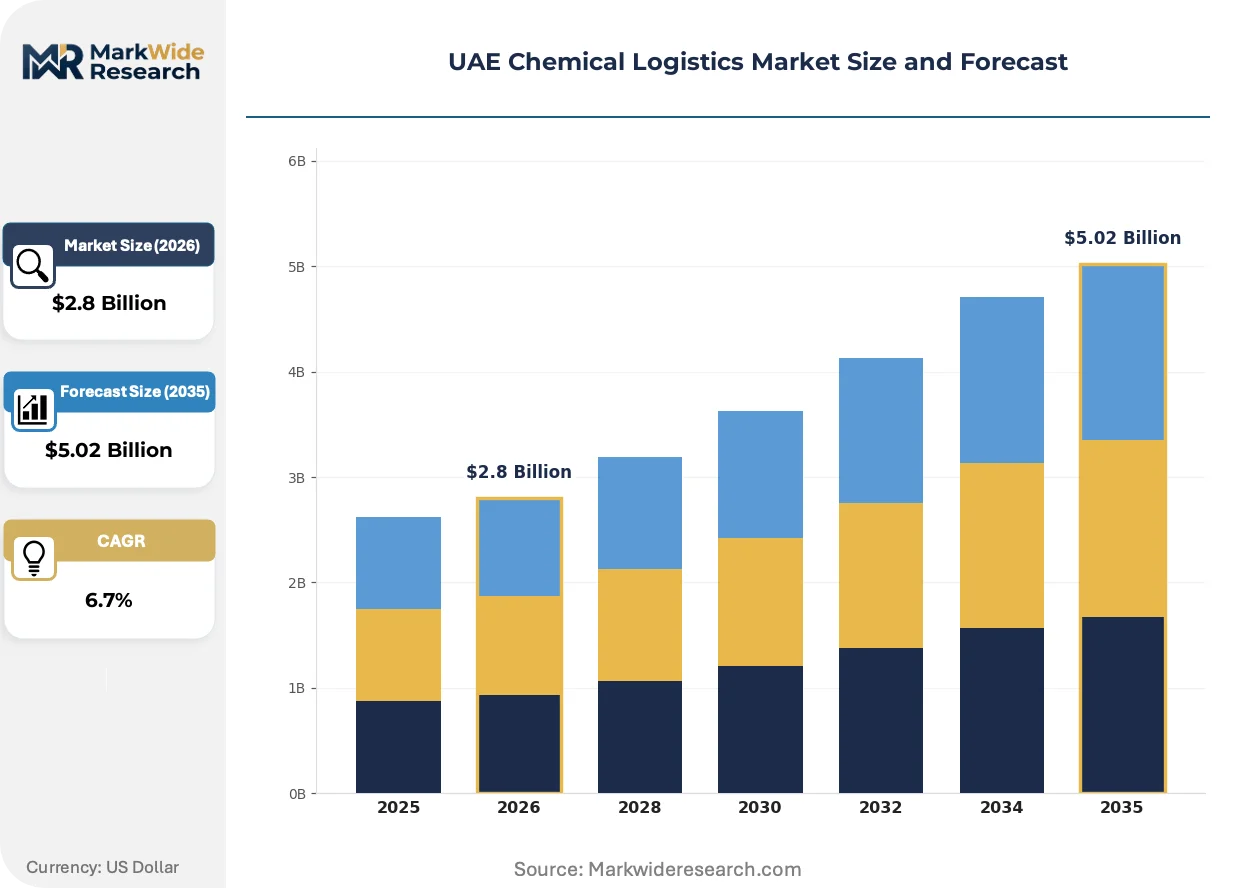
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Product Type: Chemicals, Polymers, Solvents, Fertilizers End User: Manufacturing, Pharmaceuticals, Agriculture, Food Industry Delivery Mode: Road, Rail, Sea, Air |
| Companies Covered | Servochem L.L.C., RSA Global, DHL, CEVA Logistics, Petrocheme, Agility Logistics, Al-Futtaim Logistics, A&R Logistics, BDP International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Chemical Logistics Market Trends and Innovations
Telematics and automation are compressing dwell times and reshaping how chemical cargo moves through UAE free zones, with operators competing on real-time visibility rather than asset ownership alone.
Internet of Things sensor networks is integrating temperature, pressure, and location monitoring into ISO-tank fleets. Polymer distributors serving Saudi-border manufacturing clusters are deploying these systems fastest. The technology is integrating predictive maintenance alerts that reduce cargo spoilage and insurance premiums for hazardous liquid shippers.
MOHAP pharmaceutical licensing requirements now extend to chemical intermediates used in active ingredient synthesis. Facility standards for segregation and contamination control have tightened across Dubai and Abu Dhabi storage operations. Contract logistics providers serving life science verticals are retrofitting warehouses to dual-use chemical-pharma specifications ahead of formal enforcement.
Buyers are consolidating vendor relationships from fragmented local transporters toward integrated operators offering customs brokerage, warehousing, and last-mile delivery under single accountability. Fertilizer importers previously using three separate service providers now contract bundled solutions. This concentration is most visible among agricultural chemical distributors in Jebel Ali Free Zone seeking simplified procurement overhead.
UAE Chemical Logistics Market Segmentation
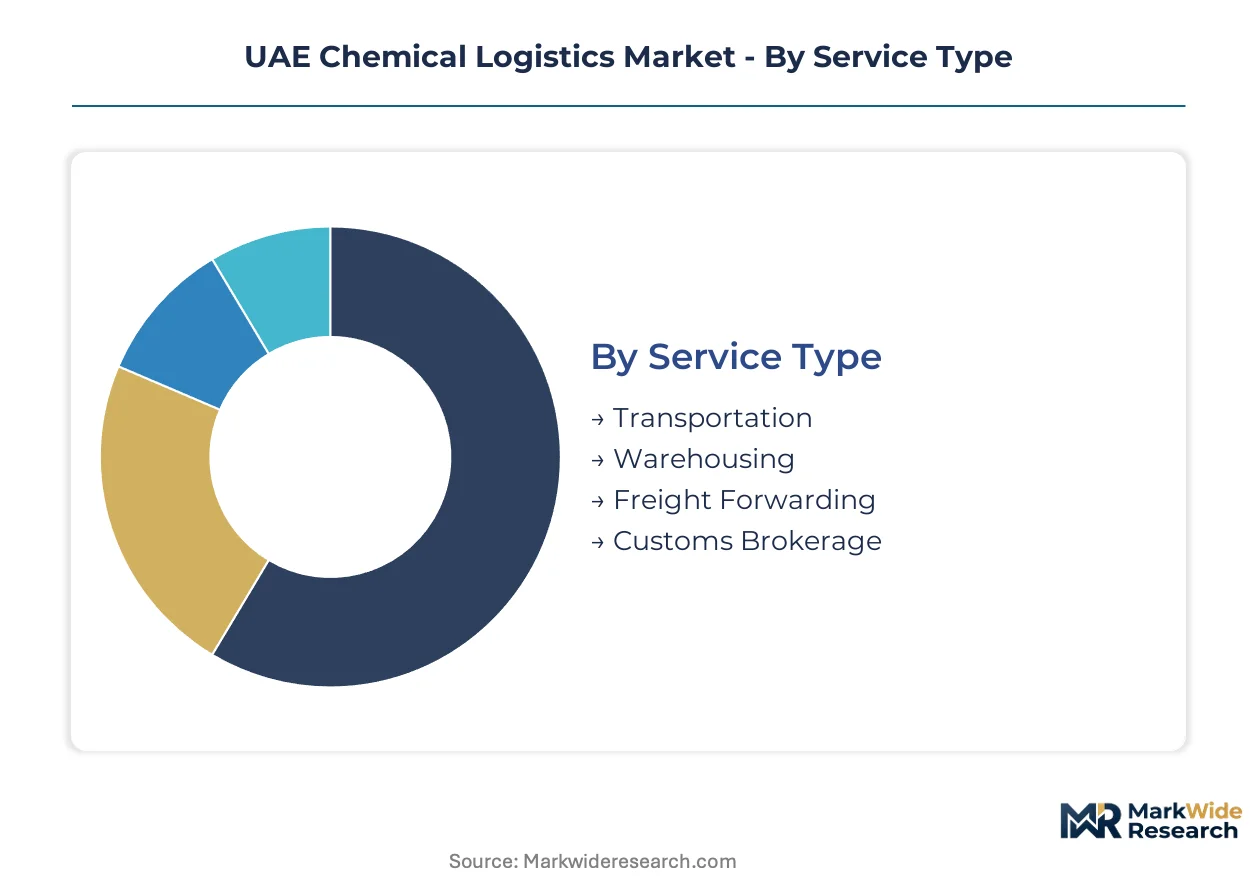
Segmentation in UAE chemical logistics reveals how service specialization, product hazards, and multimodal requirements create distinct procurement profiles. Buyers select providers based on certification depth rather than generic coverage, with ADNOC's Ruwais expansion and Jebel Ali's bonded zone status driving divergent infrastructure investments.
Service Type:
Upgrade cycles in chemical logistics center on replacing fragmented single-service contracts with integrated platforms that unify visibility across transport, storage, and customs clearance.
- Transportation:Bulk liquid tanker fleets and ISO-tank carriers dominate revenue pools, with hazardous materials certification from the UAE Federal Transport Authority separating qualified operators from general freight haulers. Road transport concentrates on polymer pellet movements between Jebel Ali and Saudi-border manufacturing clusters, while coastal shipping handles Ruwais-to-Abu Dhabi chemical flows.
- Warehousing:Bonded chemical yards with NFPA 30 fire suppression systems and vapor recovery infrastructure command premium positioning as Borouge expansion generates demand for temperature-controlled polymer staging. Khalifa Industrial Zone Abu Dhabi attracts new capacity for serving downstream petrochemical clusters with direct rail connectivity.
- Freight Forwarding:Dangerous goods certification capabilities concentrate volume among established operators with in-house IMDG Code expertise.
- Customs Brokerage:Integrated customs clearance with pre-arrival documentation reduces port dwell times for fertilizer importers at Jebel Ali.
Transportation sits at the top of the volume ranking, with Warehousing climbing the fastest.
Product Type:
Cost tier differentiation separates high-hazard specialty chemicals requiring containment infrastructure from commodity polymers moving through standard bulk handling.
- Chemicals:Hazardous and non-hazardous industrial chemicals demand UN-classified packaging, segregation protocols, and temperature-controlled ISO-tank fleets. ADNOC's downstream expansion at Ruwais Derivatives Park redirects specialty chemical flows through Abu Dhabi ports, forcing logistics operators to rebalance Jebel Ali-centric capacity.
- Polymers:Polyolefin pellets and plastic resins constitute the highest throughput category, with Borouge capacity additions generating dedicated warehousing demand near conversion facilities in Dubai and the Northern Emirates.
- Solvents:Flammable liquid solvents require vapor recovery systems and specialized tank cleaning services at bulk liquid terminals.
- Fertilizers:Agricultural chemical distributors in Jebel Ali Free Zone seek bundled logistics solutions combining customs brokerage, warehousing, and last-mile delivery.
Polymers command the largest volume position, while Chemicals expand most quickly on Ruwais downstream growth.
End User:
Application-specific compliance requirements shape procurement, with pharmaceutical and food industry buyers imposing stricter facility standards than manufacturing or agriculture.
- Manufacturing:Petrochemical producers and polymer converters anchor baseline demand, with Saudi-border manufacturing clusters driving road transport intensity from UAE consolidation hubs.
- Pharmaceuticals:MOHAP licensing requirements now extend to chemical intermediates used in active ingredient synthesis, tightening segregation and contamination control standards across Dubai and Abu Dhabi storage operations.
- Agriculture:Fertilizer importers prioritize customs pre-clearance capabilities and reduced port dwell times over specialized handling infrastructure.
- Food Industry:Food-grade chemical additives require dedicated storage bays with contamination prevention protocols.
Manufacturing holds the volume lead, with Pharmaceuticals gaining share fastest on regulatory tightening.
Delivery Mode:
Supply concentration in Jebel Ali Port dictates modal mix, with sea freight dominating inbound chemical flows and road transport controlling inland distribution.
- Road:Tanker trucks and curtain-sided trailers handle polymer pellet distribution to Saudi-border manufacturing clusters and last-mile delivery across the Emirates, with driver certification bottlenecks under UAE Federal Transport Authority codes constraining available labor pools.
- Rail:Etihad Rail connectivity to Khalifa Industrial Zone Abu Dhabi offers integrated multimodal corridors serving Ruwais downstream clusters, though chemical railcar fleets remain underdeveloped.
- Sea:Jebel Ali Port's IMDG Code enforcement elevates compliance barriers for containerized hazardous materials, concentrating volume with certified dangerous goods specialists.
- Air:Limited to high-value specialty chemicals and pharmaceutical intermediates requiring rapid transit.
Sea transport dominates inbound volume, with Rail positioned for steepest expansion on Etihad Rail chemical corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting chemical logistics investment toward jurisdictions offering streamlined hazardous materials permitting and lower compliance costs. The UAE's consolidated federal framework under MOHAP and the Federal Transport Authority creates operational advantages against fragmented multi-state regimes elsewhere in the Gulf.
Dubai
Jebel Ali Port and Free Zone concentrate over 70 percent of national chemical throughput, with IMDG Code enforcement elevating barriers for uncertified operators. Dubai Municipality's chemical storage zoning regulations mandate NFPA 30 fire suppression systems for new bonded yards. The Jebel Ali integrated chemical zone attracts polymer distributors through multimodal connectivity and ISO-tank staging infrastructure.
Abu Dhabi
ADNOC's Ruwais Derivatives Park expansion redirects specialty chemical flows through Khalifa Port, forcing logistics operators to rebalance capacity southward. The Federal Transport Authority's hazardous materials codes apply uniformly, though Abu Dhabi Department of Economic Development offers accelerated licensing for downstream petrochemical logistics. Khalifa Industrial Zone Abu Dhabi is attracting integrated logistics parks with direct Etihad Rail connectivity.
Sharjah
Hamriyah Free Zone and Port serve as a cost-competitive alternative for solvent and fertilizer distributors seeking lower land costs than Dubai. Sharjah's Hamriyah Free Zone Authority streamlined hazardous materials warehousing permits to capture spillover demand from Jebel Ali congestion. The zone's chemical terminal expansion targets East African transshipment cargo.
Northern Emirates
Ras Al Khaimah and Fujairah are developing bulk liquid storage capacity to capture fuel and petrochemical flows bypassing the Dubai-Abu Dhabi corridor. Fujairah Port's deep-water anchorage and exemption from Strait of Hormuz transit constraints attract international chemical tanker operators. The emirates' lower labor and real estate costs support ISO-tank cleaning and maintenance facilities.
UAE Chemical Logistics Market Competitive Landscape
Established logistics providers occupy the standard tier; emerging entrants pursue digital freight matching and specialized hazardous materials certification. The market structure concentrates around incumbent operators with captive infrastructure at Jebel Ali and Khalifa Port, while mid-scale players compete on regional coverage. Two archetypes dominate: integrated free-zone operators bundling customs brokerage with warehousing, and asset-light platforms connecting ISO-tank capacity with shipper demand. Competitive moves center on strategic partnerships with petrochemical producers and selective capacity expansion at Kizad.
Within the integrated operator tier, Servochem L.L.C. anchors its position through dedicated bulk liquid storage infrastructure at Jebel Ali Free Zone. CEVA Logistics exemplifies the global network archetype, competing on temperature-controlled distribution capabilities. Agility Logistics occupies a position combining customs brokerage integration with warehousing to reduce port dwell times. These three operators represent distinct strategic postures: captive infrastructure, global network reach, and service bundling.
| Leading Market Players |
|---|
| Servochem L.L.C. |
| RSA Global |
| DHL |
| CEVA Logistics |
| Petrocheme |
| Agility Logistics |
| Al-Futtaim Logistics |
| A&R Logistics |
| BDP International |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed petrochemical producers and family-owned mid-cap distributors anchor supply behavior across UAE chemical corridors, with ADNOC's downstream expansion and Jebel Ali's bonded zone status creating divergent pricing discipline between captive infrastructure operators and fragmented transporters.
Pricing Analysis
Distributor margins compress most severely at the bulk liquid tier, where ISO-tank cleaning and vapor recovery capex requirements stratify pricing across certified green logistics partners, commodity haulers, and uncertified generalists. Price differentiation hinges on dangerous goods certification depth from the UAE Federal Transport Authority and after-sales bundling of customs brokerage with warehousing. Cost compression in polymer pellet distribution intensifies as Borouge expansion attracts new staging capacity near conversion facilities. Fertilizer importers in Jebel Ali Free Zone exhibit highest price sensitivity, prioritizing reduced port dwell times over specialized handling infrastructure.
Supply Chain Analysis
Certification gating under MOHAP pharmaceutical licensing and IMDG Code enforcement concentrates qualified capacity among incumbent operators with captive infrastructure at Jebel Ali and Khalifa Port. Geographic supply concentration centers on the UAE, Saudi Arabia, and India as primary polymer and solvent sourcing markets. Raw material dependencies include polyolefin feedstocks, flammable liquid solvents, and agricultural chemical compounds. Single-source vulnerability runs through Jebel Ali Port, where over seventy percent of national chemical throughput creates congestion exposure. Distribution runs through integrated free-zone operators bundling customs brokerage, warehousing, and last-mile delivery under single accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier logistics services, with dual carbon compliance requirements and pharmaceutical licensing extensions enabling certified operators to capture pricing power above commodity transport rates.
For Market Incumbents: Extend dangerous goods certification capabilities into pharmaceutical intermediates ahead of formal MOHAP enforcement, while consolidating fragmented family-owned distributors through selective acquisition of bonded chemical yards with NFPA 30 fire suppression systems. Threat substitution from digital freight matching platforms demands API integration investments to retain shipper relationships. Vertical integration into ISO-tank cleaning and maintenance facilities at Khalifa Industrial Zone Abu Dhabi offers the strongest defensive lever against new entrants. For New Entrants and Emerging Players: UAE Federal Transport Authority hazardous materials codes in the Emirates open a window for specialized driver training academies and certification services, addressing the labor bottleneck constraining bulk liquid transport capacity. White-space targets include Kizad chemical zone logistics parks serving Ruwais downstream clusters with direct Etihad Rail connectivity, and East African corridor consolidation hubs targeting Kenya and Tanzania manufacturing bases. A go-to-market angle emphasizing customs pre-clearance capabilities for fertilizer importers offers fastest penetration against established bundling providers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional operators with dangerous goods certification but limited technology infrastructure, positioned for margin expansion through IoT sensor network deployment and yard management system upgrades. Long-term viability across the analysis window favors integrated platforms with captive free-zone real estate and petrochemical producer partnerships. Acquisition target archetype: certified operators with underutilized bonded chemical yard capacity in Sharjah or Northern Emirates. The signal to watch is ADNOC's Ruwais Derivatives Park offtake volume commitments as inflection indicator for southward capacity rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion at Kizad | Etihad Rail connectivity positions integrated logistics parks to capture Ruwais downstream chemical flows. |
| Backward Integration into ISO-Tank Maintenance | Captive cleaning and vapor recovery facilities reduce third-party dependency for hazardous liquid shippers. |
| Green Logistics Certification Program | Dual carbon compliance credentials differentiate operators in ADNOC and Borouge procurement decisions. |
| Long-term Supply Agreement with Polymer Distributors | Temperature-controlled warehousing commitments secure volume commitments from Saudi-border manufacturing clusters. |
| Joint Venture for Digital Freight Matching Platform | API connectivity with legacy ERP systems at family-owned distributors reduces empty backhaul rates. |
Research Methodology
Direct dialogue with chemical logistics operators, petrochemical procurement leads, free-zone authority licensing officers, and hazardous materials safety engineers grounded this analysis, cross-referenced against UAE Federal Transport Authority regulatory filings, customs trade data, ADNOC downstream expansion disclosures, and SEC filings from listed logistics providers. Bottom-up and top-down triangulation validated volume estimates across service type, product category, and emirate-level geographic segmentation.
Bottom-up modeling aggregated individual facility capacity and utilization rates across Jebel Ali, Khalifa Port, and Hamriyah Free Zone, while top-down analysis tracked petrochemical production growth and import-export flows through UAE customs data. Segmentation dimensions included service type, product hazard classification, end-use industry vertical, and delivery mode. CAGRs were derived from trend extrapolation of historical volume growth against announced capacity additions and regulatory enforcement timelines. Industry-specific forecast inputs incorporated Etihad Rail chemical corridor development progress and MOHAP licensing requirement phase-in schedules.
Revisions become necessary when ADNOC's Ruwais Derivatives Park expansion timelines shift, Saudi Arabia's Neom chemical cluster advances to operational status, or UAE dual carbon enforcement mechanisms tighten beyond current announced standards. A model refresh is warranted upon material change in Jebel Ali Port congestion levels or IMDG Code inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Germany Bunker Fuel Market
Fuels
Europe Bunker Fuel Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Compressed Natural Gas Market
Fuels
Europe Firewood Market
Fuels
Marine Fuel Optimization Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
City Gas Distribution Market
Fuels
Gas Pooling Mechanism Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
Briquette Market
Fuels
Canada Bunker Fuel Market