
 Fuel Grinder Market | 2026-2036
Fuel Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Grinder Market Analytics
Industrial biomass processors is reorganizing procurement priorities away from general-purpose contractors toward specialized fuel preparation firms. Bosch Power Tools leverages its pneumatic grinder portfolio to anchor European biomass co-generation sites. Makita Corporation competes through compact electric units optimized for mobile repair operations at remote power facilities. Stanley Black & Decker sustains channel dominance in North American construction-adjacent fuel processing through its dealer network density.
A fuel grinder is a rotary or percussive material reduction device engineered to achieve specified particle fineness, typically operating at motor speeds between 6,000 and 11,000 RPM with thermal management systems to mitigate ignition risks from volatile dust loads. Its primary purpose is to render solid fuels—wood pellets, agricultural residues, or processed refuse—into uniform feedstock for combustion chambers, gasifiers, or pellet densification lines. Electric units command the product type landscape due to torque consistency and lower maintenance burden, while pneumatic grinders retain share in explosive atmospheres where spark containment is mandatory. Steel construction dominates the material category for high-wear industrial applications, though composite housings are gaining traction among hobbyist and light contractor segments where weight reduction offsets durability trade-offs. The aerospace application category remains nascent, constrained by certification cycles for alternative fuel testing infrastructure.
OSHA combustible dust standards and EPA National Emission Standards for Hazardous Air Pollutants shape equipment design mandates, forcing manufacturers to integrate explosion-proof motors and sealed bearing assemblies. The EU Machinery Directive and ATEX certification requirements govern market access for pneumatic and hydraulic units sold into European biomass facilities. Stakeholders must monitor evolving carbon intensity accounting rules, as feedstock preparation efficiency directly affects lifecycle emissions scores that determine subsidy eligibility under clean heat programs.
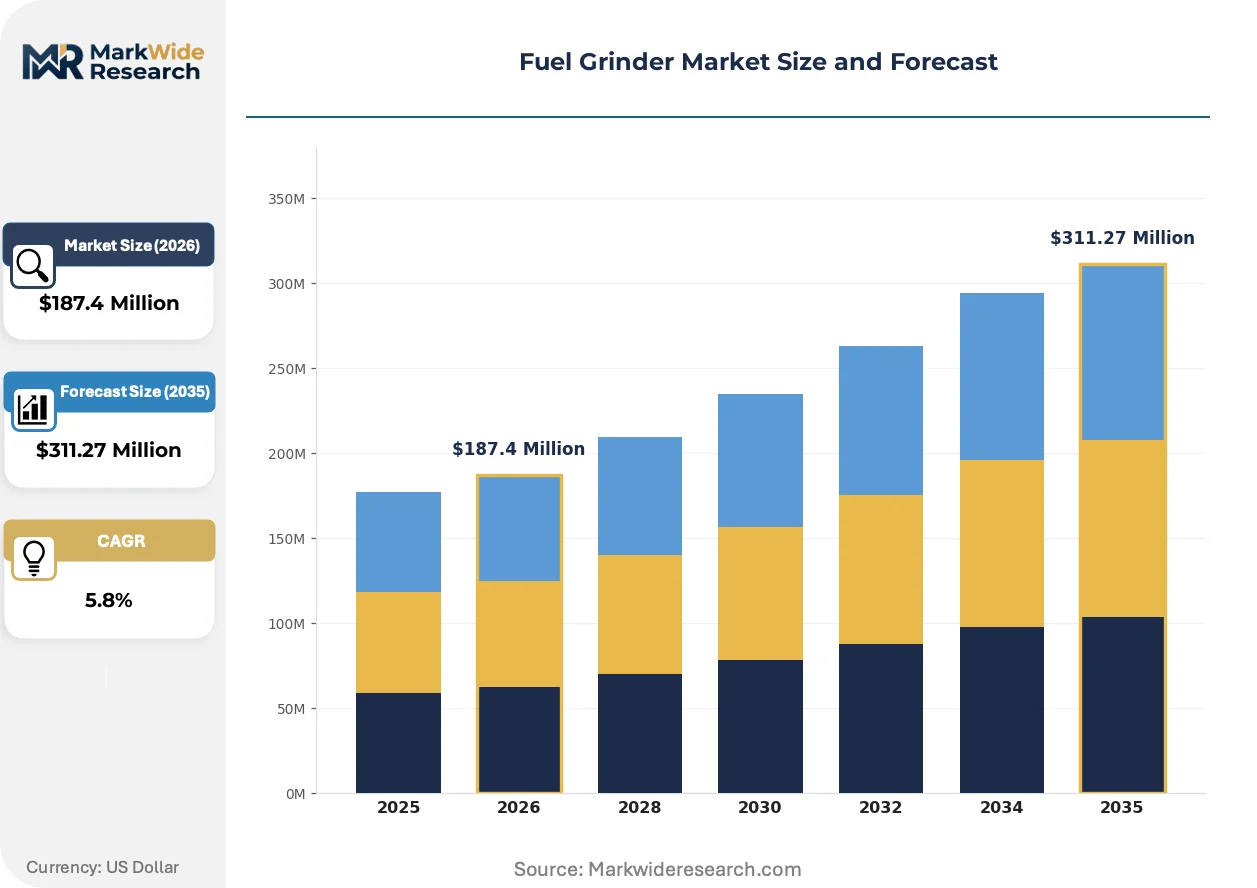
Market Dynamics
Biomass power plants are tightening feedstock preparation standards, forcing precision grinding equipment upgrades across industrial facilities. EPA emissions rules and OSHA combustible dust directives are compelling capital expenditure cycles that favor specialized fuel preparation systems over general-purpose machinery.
Growth Catalysts
- OSHA combustible dust standards:Facility safety mandates are accelerating replacement of legacy grinding equipment with sealed-bearing, explosion-proof designs in US biomass processing plants.
- German district heating networks:Co-firing compatibility requirements for uniform particle size are concentrating procurement demand in Central European biomass co-generation facilities.
- Electric motor torque consistency:Industrial processors are prioritizing electric units over pneumatic alternatives for maintenance burden reduction and operational predictability.
Market Restraints
- Steel input cost volatility:High-wear industrial grinder construction depends on steel alloy pricing, compressing margin structures for manufacturers serving price-sensitive contractor segments.
- ATEX certification friction:European market access requires expensive third-party validation for pneumatic and hydraulic units, extending time-to-revenue for non-EU equipment suppliers.
- Composite durability trade-offs:Lightweight housing materials face penetration ceilings in heavy-duty biomass applications where abrasive feedstock loads accelerate wear failures.
Strategic Opportunities
- Carbon intensity accounting rules:Lifecycle emissions scoring for feedstock preparation efficiency is creating subsidy eligibility differentiation that rewards precision grinding technology investments.
- Refuse-derived fuel processing:Municipal waste-to-energy facilities represent an emerging application vertical with distinct particle size requirements and lower incumbent equipment saturation.
- Mobile repair service channels:Compact electric unit demand from remote power facilities is opening specialized rental and field-service distribution models outside traditional dealer networks.
Industry Challenges
- Explosion-proof engineering talent scarcity:Specialized motor design and thermal management expertise for volatile dust environments commands premium compensation and extends R&D timelines.
- EU Machinery Directive compliance timelines:Multi-year certification cycles for alternative fuel testing infrastructure constrain aerospace application development and capital recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Grinder Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Hydraulic, Manual Material: Steel, Aluminum, Plastic, Composite Application: Industrial, Automotive, Construction, Aerospace End User: Manufacturers, Contractors, Repair Shops, Hobbyists |
| Companies Covered | Bosch Power Tools, Makita Corporation, Stanley Black & Decker, Hilti Corporation, DEWALT Industrial Tool Company, Milwaukee Tool, Metabo Power Tools, Ingersoll Rand, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Grinder Market Evolving Landscape
Equipment design is pivoting toward integrated safety systems and modular service architectures. Manufacturers are responding to regulatory pressure with faster certification pathways and predictive maintenance capabilities.
Sealed bearing assemblies with integrated thermal monitoring are fragmenting the traditional motor-housing supply structure. Biomass power plants in Germany and Scandinavia are specifying these configurations for continuous-duty applications. The technology is fragmenting aftermarket service revenue toward specialized component suppliers and away from integrated OEM service contracts.
EPA National Emission Standards for Hazardous Air Pollutants are forcing grinder enclosure redesigns with negative-pressure dust containment. Industrial facilities face retrofit deadlines that compress procurement cycles toward turnkey system replacements. Steel-housed industrial units are capturing preference over composite alternatives as operators prioritize longevity over first-cost under regulatory compliance pressure.
Buying committees at biomass co-generation sites are unbundling equipment specification from installation contracting. Specialized fuel preparation firms are displacing general-purpose contractors in procurement decisions, particularly in US markets where OSHA enforcement has intensified. This pattern concentrates vendor relationships around technical specialists with certified service capabilities rather than broad-line distributors.
Fuel Grinder Market Segmentation
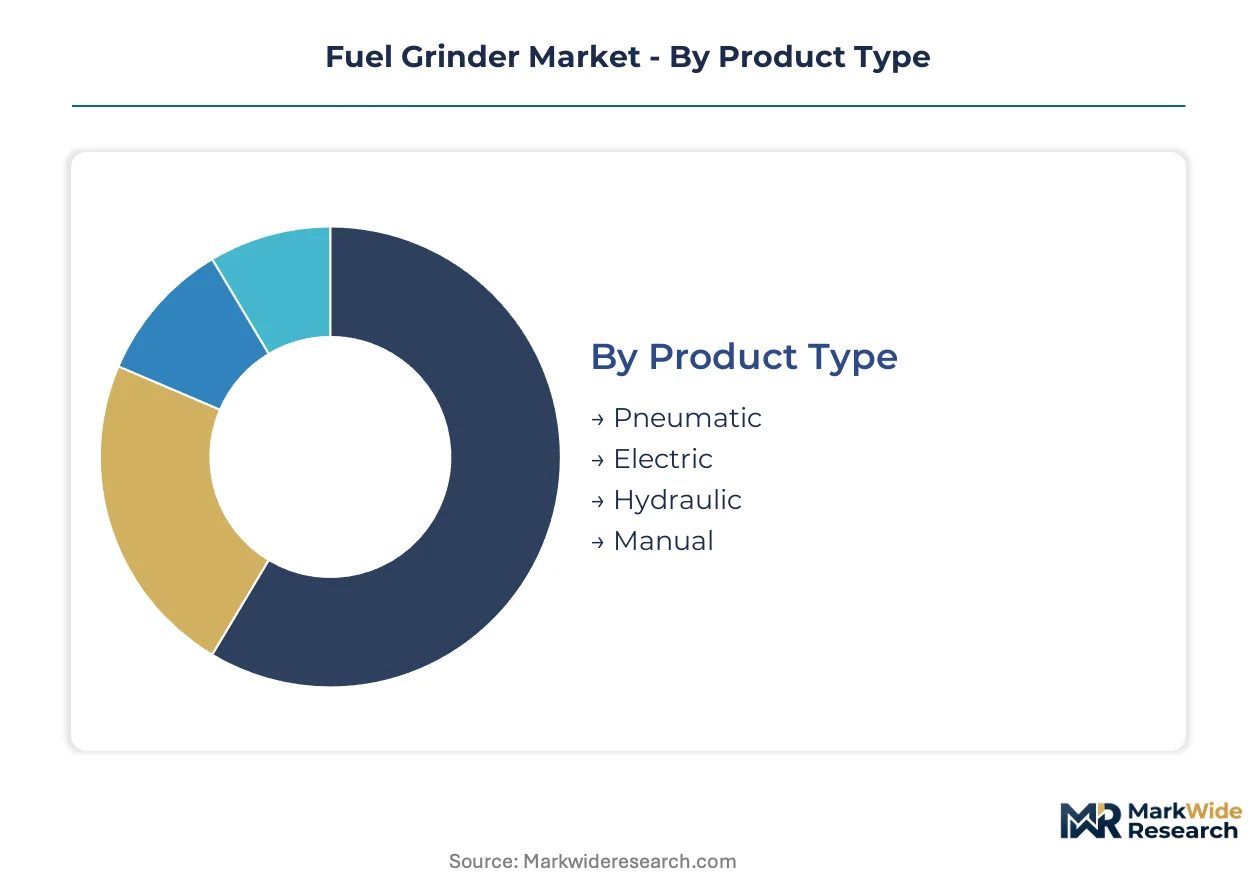
Segmentation in the fuel grinder market reveals divergent margin structures across power systems and material grades. Procurement committees at biomass facilities weight torque consistency against spark containment requirements, creating distinct value pools by application environment.
Product Type:
Margin concentration sits with sealed electric motor architectures where thermal management and bearing longevity command premium pricing over pneumatic alternatives.
- Electric:Torque consistency at 6,000-11,000 RPM enables continuous-duty biomass processing with reduced maintenance burden. German district heating networks specify these units for co-firing feedstock preparation where operational predictability outweighs first-cost considerations.
- Pneumatic:Spark-free operation via compressed air drive suits explosive atmospheres under OSHA combustible dust directives. ATEX certification requirements in European facilities sustain price premiums despite higher total cost of ownership.
- Hydraulic:Delivers sustained torque under variable load conditions for heavy industrial biomass reduction.
- Manual:Serves hobbyist and light contractor segments where capital constraints override productivity metrics.
The dominant share belongs to Electric, while Pneumatic is closing the gap fastest on regulatory compliance tailwinds.
Material:
Volume leadership resides with steel construction despite composite housing entrants targeting weight-sensitive mobile applications.
- Steel:High-wear alloy construction withstands abrasive feedstock loads in continuous industrial duty cycles. EPA emissions retrofit deadlines at US biomass plants favor steel-housed units for longevity under regulatory compliance pressure.
- Composite:Polymer-matrix housings reduce operator fatigue in portable service configurations. Remote power facility repair operations in Scandinavia specify these for field mobility where transport economics override durability trade-offs.
- Aluminum:Balances corrosion resistance with moderate weight reduction for coastal biomass processing installations.
- Plastic:Captures hobbyist segment demand where intermittent use patterns minimize wear failure exposure.
Steel retains volume leadership, though Composite is expanding most quickly in mobile service channels.
Application:
Revenue concentration tracks regulatory enforcement intensity, with industrial biomass processing commanding specification rigor absent in adjacent sectors.
- Industrial:Precision particle size control for combustion chambers and gasifiers requires sealed bearing assemblies with integrated thermal monitoring. OSHA and EPA mandates at US biomass facilities accelerate replacement cycles toward explosion-proof configurations.
- Construction:Fuel preparation for temporary power generation and equipment servicing operates under lighter compliance burdens. Stanley Black & Decker's dealer network density sustains channel position in North American construction-adjacent procurement.
- Automotive:Refuse-derived fuel testing for alternative propulsion research creates niche specification requirements.
- Aerospace:Alternative fuel certification cycles constrain equipment deployment in testing infrastructure development.
Industrial commands the dominant revenue position, while Construction is gaining share fastest on infrastructure spending patterns.
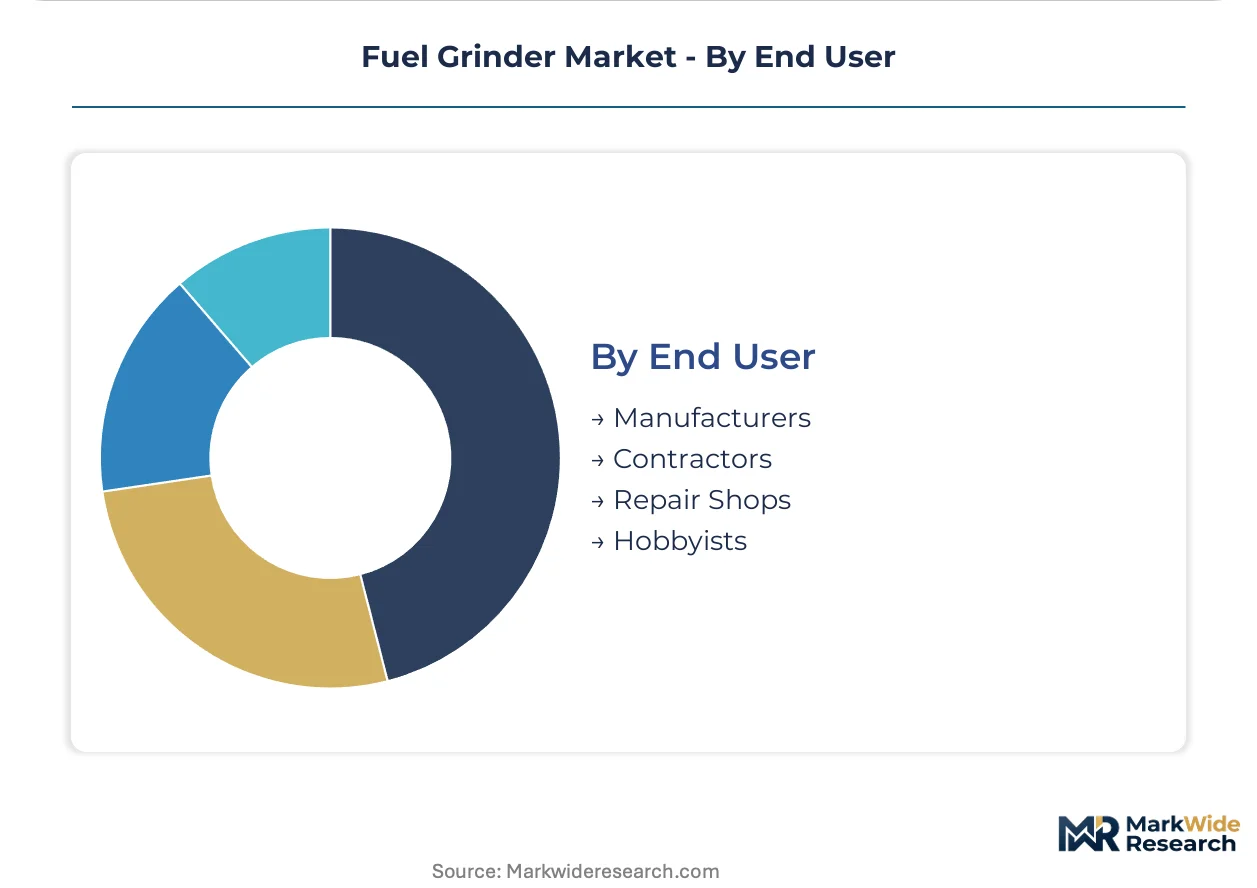
End User:
Procurement authority is shifting from general-purpose contractors toward specialized fuel preparation firms with certified service capabilities.
- Manufacturers:Biomass pellet densification lines and power plant operators specify precision grinding for feedstock uniformity. German co-generation facilities prioritize particle size consistency for district heating network co-firing compatibility.
- Contractors:Construction-adjacent fuel processing demand concentrates through established dealer networks with installation bundling capabilities.
- Repair Shops:Mobile service operations at remote power facilities drive compact electric unit specifications for field deployment.
- Hobbyists:Weight-reduced composite housing demand from non-commercial users creates a price-tiered entry segment.
Manufacturers hold the dominant procurement volume, while Repair Shops are climbing the fastest on distributed power infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters concentrate in Germany, the United States, and Japan, with each jurisdiction imposing distinct certification burdens on market entry. Procurement patterns diverge sharply between EPA-enforced US biomass facilities and EU Machinery Directive-governed European co-generation sites.
United States
OSHA combustible dust directives are accelerating capital expenditure cycles at industrial biomass processors across the Midwest and Southeast. EPA National Emission Standards for Hazardous Air Pollutants mandate sealed-bearing, explosion-proof grinder configurations that favor turnkey system replacements over component retrofits. Procurement committees in Michigan, Ohio, and Georgia are unbundling equipment specification from installation contracting, concentrating vendor relationships around certified service specialists.
Germany
District heating networks in Bavaria and North Rhine-Westphalia prioritize uniform particle size for co-firing compatibility, tightening feedstock preparation standards. ATEX certification requirements govern pneumatic and hydraulic unit market access, extending time-to-revenue for non-EU equipment suppliers. Industrial clusters around Munich and Cologne are specifying integrated thermal monitoring systems for continuous-duty biomass processing applications.
Japan
METI carbon intensity accounting rules are creating subsidy eligibility differentiation that rewards precision grinding technology investments. JIS standards compliance shapes equipment design mandates for domestic biomass co-generation facilities. Manufacturing concentrations in the Nagoya and Osaka industrial corridors are driving demand for compact electric units with predictive maintenance capabilities.
Sweden
District heating infrastructure expansion in Stockholm and Gothenburg is concentrating procurement demand for mobile repair service channels. EU Green Deal clean heat programs tie lifecycle emissions scores to feedstock preparation efficiency, favoring electric motor architectures over pneumatic alternatives. Composite housing specifications for remote power facility repair operations are gaining traction in Scandinavian mobile service configurations.
China
Dual carbon goals under MEE oversight are pressuring municipal waste-to-energy facilities to upgrade refuse-derived fuel processing capabilities. GB standards for industrial safety equipment are tightening spark containment requirements in explosive atmosphere applications. Manufacturing clusters in Jiangsu and Shandong provinces are expanding precision grinding equipment production for domestic biomass power plant retrofit cycles.
Fuel Grinder Market Competitive Landscape
Concentration sits with diversified industrial tool conglomerates and specialized pneumatic equipment manufacturers. The vendor base organizes around three strategic archetypes: integrated power tool portfolios serving construction-adjacent fuel processing, pneumatic specialists capturing explosive atmosphere applications, and compact electric unit providers targeting mobile repair channels. Dominant competitive moves include geographic certification investments for EU Machinery Directive compliance and portfolio diversification into sealed-bearing thermal management systems.
Among diversified industrial tool providers, Bosch Power Tools and Makita Corporation exemplify the integrated portfolio archetype, with geographic footprints spanning European and Asia-Pacific biomass markets. Stanley Black & Decker occupies a position within the North American construction-adjacent segment, anchored by dealer network density. Pneumatic specialists including Ingersoll Rand and Atlas Copco represent the spark-free operation tier, serving OSHA-enforced US facilities and ATEX-certified European installations where compressed air drive systems command sustained price premiums despite higher total cost of ownership.
| Leading Market Players |
|---|
| Bosch Power Tools |
| Makita Corporation |
| Stanley Black & Decker |
| Hilti Corporation |
| DEWALT Industrial Tool Company |
| Milwaukee Tool |
| Metabo Power Tools |
| Ingersoll Rand |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German district heating operators and precision grinding equipment suppliers lock in steel alloy supply access while anchoring price visibility across multi-year procurement cycles. These contracts insulate biomass co-generation facilities from spot-market volatility in high-wear component materials.
Pricing Analysis
OSHA combustible dust standards dictate the pricing tier structure across the fuel grinder market, separating explosion-proof sealed-bearing configurations from standard industrial units. Three-tier pricing structure across premium, standard, and economy levels reflects ATEX certification grade and integrated thermal monitoring capabilities. Cost compression in the economy tier is intensifying because composite housing alternatives face penetration ceilings under abrasive feedstock loads. Hobbyist segments exhibit the highest price sensitivity, while German district heating networks prioritize operational predictability over first-cost considerations.
Supply Chain Analysis
Strait of Malacca transit underwrites much of the specialty steel alloy feedstock reaching European grinder manufacturers, exposing the supply chain to maritime logistics disruptions. Fabrication concentrates in Germany, Japan, and the United States, with each jurisdiction imposing distinct certification burdens on component sourcing. Production draws from high-grade steel alloys, sealed bearing assemblies, and explosion-proof motor windings. Single-source vulnerability sits with German precision bearing suppliers serving ATEX-certified pneumatic unit manufacturers. Distribution runs through specialized fuel preparation firms with certified service capabilities rather than broad-line industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
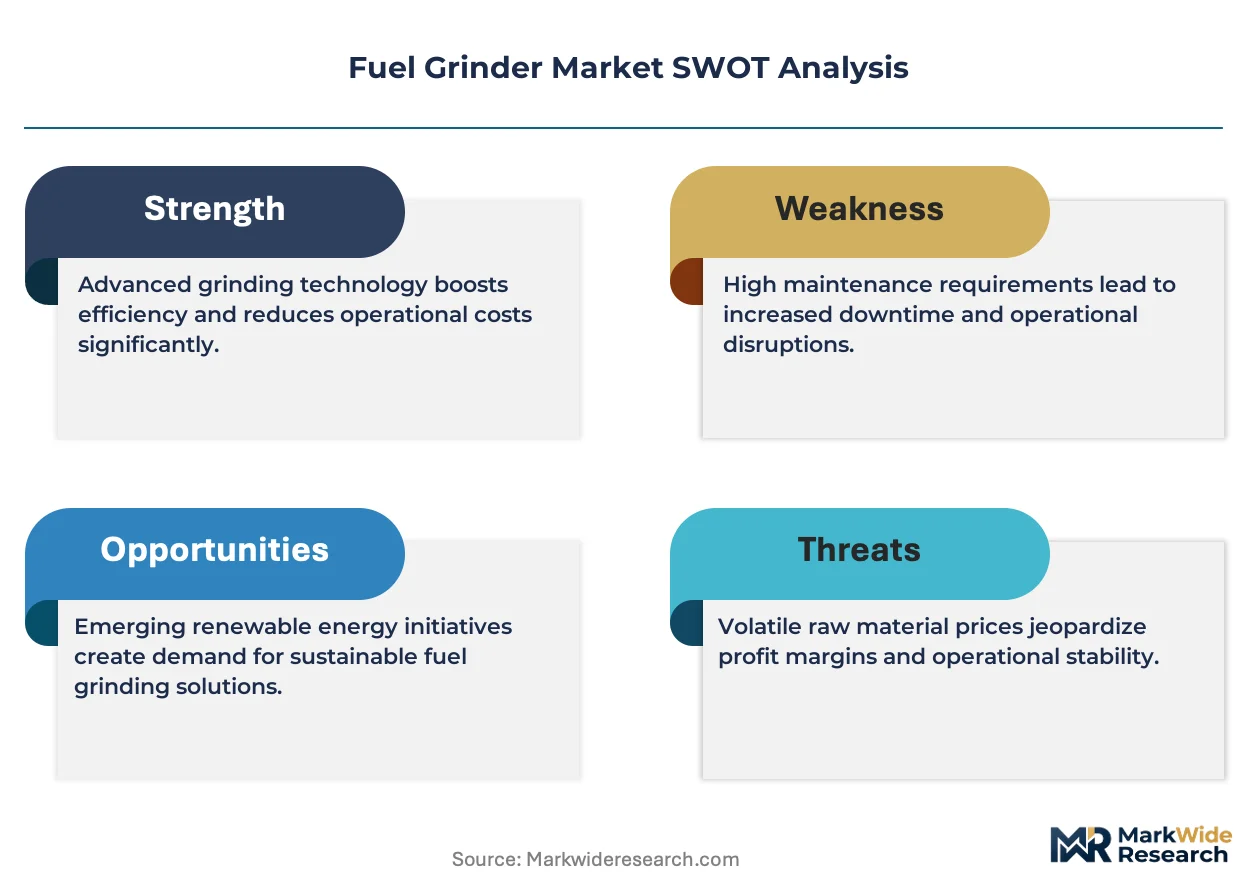
Explosion-proof engineering talent scarcity constrains R&D velocity and extends product development timelines for thermal management systems in volatile dust environments. Specialized motor design expertise commands premium compensation and limits supplier expansion.
For Market Incumbents: Compound channel control by deepening certified service capabilities at German and US biomass facilities where procurement committees unbundle specification from installation. Add capacity for sealed-bearing thermal monitoring systems in Stuttgart and Munich industrial corridors. Defend against pneumatic specialists by accelerating electric unit torque consistency improvements that reduce maintenance burden.
For New Entrants and Emerging Players: Lead with refuse-derived fuel processing applications at Chinese municipal waste-to-energy facilities where incumbent equipment saturation remains lower. Target mobile repair service channels in Scandinavian remote power facilities with compact electric composite housing configurations. Establish field-service rental partnerships outside traditional dealer networks to bypass Stanley Black & Decker's North American distribution density.
For Investors and Strategic Acquirers: Capital is best deployed toward pneumatic equipment manufacturers with ATEX certification assets and established European biomass facility relationships. Long-term viability favors suppliers with backward integration into sealed bearing component production. Watch carbon intensity accounting rule refinements under EU Green Deal implementation as the inflection signal for subsidy eligibility differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| ATEX Certification Investment | Unlocks German district heating procurement and extends time-to-revenue advantage over non-EU suppliers. |
| Sealed Bearing Integration | Captures premium pricing from OSHA-enforced US biomass facilities facing combustible dust retrofit deadlines. |
| Mobile Service Channel Development | Addresses distributed power infrastructure expansion in Scandinavian remote facility repair operations. |
| Composite Housing R&D | Reduces operator fatigue for field deployment while managing durability trade-offs under abrasive loads. |
| Refuse-Derived Fuel System Design | Positions for Chinese waste-to-energy upgrade cycles under MEE dual carbon goals oversight. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomass plant maintenance directors, OEM procurement teams at pellet densification lines, aftermarket service heads, and plant engineers at German co-generation facilities. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants filings, EU Machinery Directive implementation guidance, OSHA combustible dust enforcement records, and customs trade data for steel alloy inputs. Bottom-up equipment shipment analysis and top-down energy infrastructure investment tracking were triangulated against regulatory compliance expenditure patterns.
Across the analysis window, volume and value outputs reflect segmentation modeling by power system architecture, material grade tier, application environment, and end-user procurement authority. CAGRs were derived from regression analysis against regulatory enforcement intensity indices and district heating network expansion plans. Forecast inputs incorporated steel alloy price volatility assumptions and ATEX certification timeline distributions for pneumatic unit market entry.
Underlying assumptions cover sustained EPA and OSHA enforcement intensity at US biomass facilities, with deviation risk concentrated in EU Machinery Directive amendment cycles and carbon intensity accounting rule refinements. Practitioners should keep alternative scenarios live as German district heating co-firing specifications and Chinese waste-to-energy subsidy structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Emulsified Fuel Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Smart Gas Solutions Market
Fuels
LPG Vaporizer Market
Fuels
Coal Trading Market
Fuels
High Octane Racing Fuel Market
Fuels
Iso-Octane Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Industrial Fuel Filter Market
Fuels
China Coal Market
Fuels
Brazil Bunker Fuel Market
Fuels
South Korea LNG Bunkering Market
Fuels
Europe Bunker Fuel Market
Fuels
Global Fuel Ethanol Market
Fuels
Coal Intelligent Dry Separators Market