
 Charcoal Briquette Market | 2026-2036
Charcoal Briquette Market Size, Share, and Industry Trends Forecast 2026-2036
Charcoal Briquette Market Intelligence
Restaurant chain procurement is rebalancing toward fewer, larger suppliers with national distribution networks. Kingsford Products Company leverages its grocery channel dominance to secure shelf space across major retail banners. Weber-Stephen Products LLC sustains brand loyalty through bundled grill-and-fuel merchandising. Royal Oak Enterprises LLC anchors its position in the independent hardware and specialty store segment.
Charcoal briquettes are compressed combustible blocks manufactured from carbonized biomass, typically bound with starch or clay and shaped into uniform cylinders for controlled, sustained heat release in cooking and industrial applications. Commercial briquettes dominate volume sales through foodservice distributors, while coconut shell charcoal commands premium positioning in specialty retail due to its higher fixed carbon content and lower ash residue. The application split reveals barbecuing as the mature revenue base, with industrial metallurgy and water treatment emerging as faster-growing demand pockets for activated carbon precursors.
The US EPA regulates particulate emissions from charcoal manufacturing under Clean Air Act provisions, while Indonesia's Ministry of Environment and Forestry enforces SVLK timber legality verification for export-bound wood charcoal. Brazil's IBAMA monitors deforestation-linked supply chains, pressuring producers toward certified agricultural residue feedstocks. Stakeholders must track evolving biomass certification schemes and carbon border adjustment mechanisms to secure long-term market access.
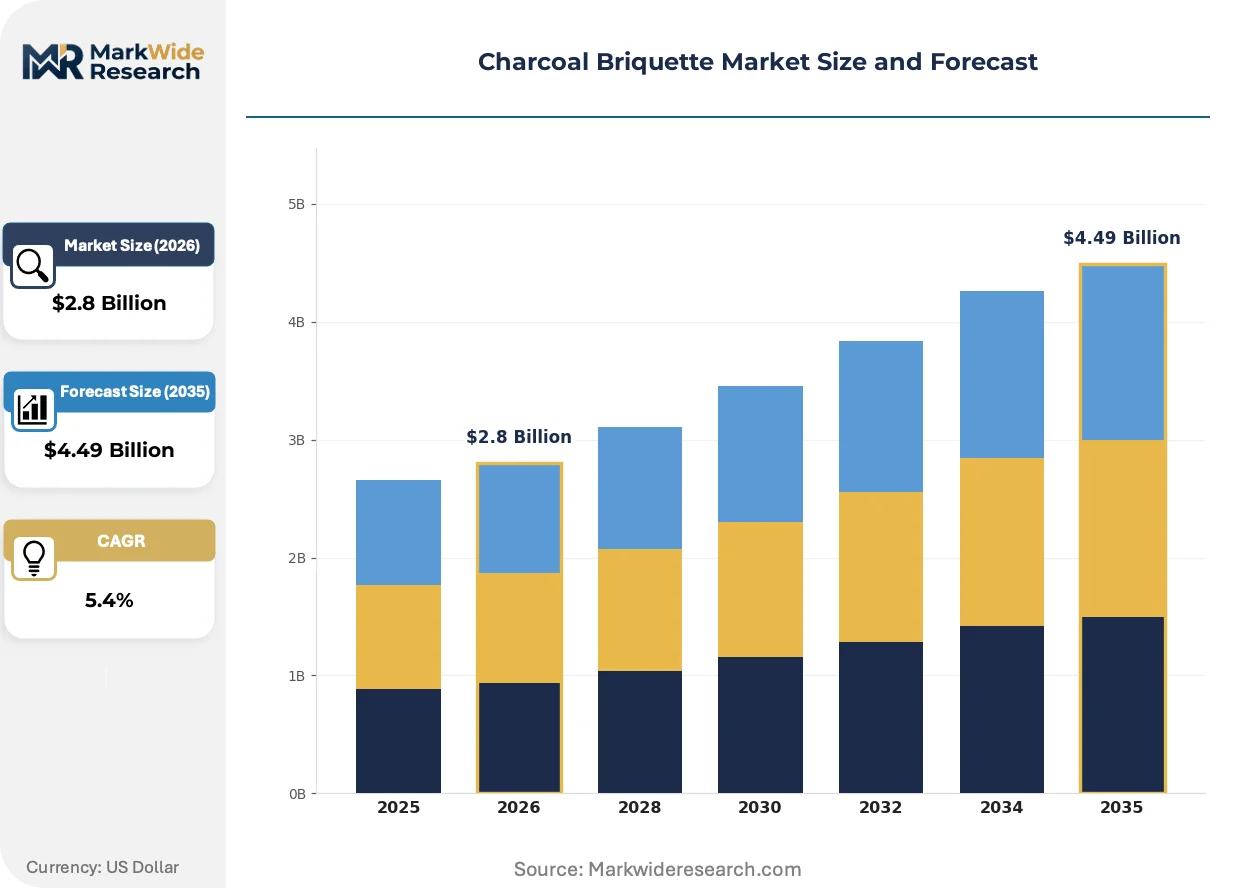
Market Dynamics
Restaurant chain procurement consolidation is compressing supplier margins while Indonesia's SVLK timber legality verification and Brazil's IBAMA deforestation monitoring force feedstock traceability investments across export-oriented producers.
Growth Catalysts
- Churrasco culture expansion:São Paulo state's premium barbecue consumption is pulling high-fixed-carbon briquette demand across Brazil's foodservice channel.
- SVLK certification mandates:Indonesia's Ministry of Environment and Forestry requires sustainable sourcing verification for wood charcoal exports, locking compliant producers into long-term supply contracts.
- Activated carbon precursor demand:Industrial metallurgy and water treatment applications are absorbing specialty coconut shell charcoal as a feedstock for activated carbon production.
Market Restraints
- Agricultural residue feedstock volatility:Coconut shell and palm kernel supply fluctuates with tropical crop yields, squeezing margin predictability for premium briquette manufacturers.
- Deforestation-linked supply chain risk:Brazil's IBAMA enforcement actions against non-certified wood charcoal producers have disrupted export volumes from Pará and Maranhão states.
- Electrification substitution pressure:Pellet grills and electric smokers are capturing share in US residential outdoor cooking, compressing growth in traditional charcoal-dependent segments.
Strategic Opportunities
- Carbon border adjustment positioning:EU CBAM implementation is creating first-mover advantage for producers with verified lifecycle carbon accounting and ISO 14064-compliant emissions disclosures.
- Specialty retail channel expansion:Independent hardware and outdoor specialty stores are building dedicated grilling sections that favor premium coconut shell briquette placement.
- Water treatment application growth:Municipal filtration infrastructure upgrades in Southeast Asia are expanding demand for activated carbon precursors derived from high-grade charcoal feedstocks.
Industry Challenges
- Certification timeline compression:SVLK, FSC, and PEFC multi-standard compliance requires 18-24 month audit cycles that delay market entry for new Indonesian exporters.
- Legacy kiln modernization capex:Traditional earth-mound carbonization methods face replacement pressure from steel retort systems demanding capital outlays that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charcoal Briquette Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Briquettes, Commercial Briquettes, Flavored Briquettes, Premium Briquettes Application: Barbecuing, Industrial Use, Smoking, Heating Material: Wood Charcoal, Coconut Shell Charcoal, Agricultural Residues, Sawdust Packaging Type: Bulk Bags, Retail Packs, Bag-in-Box, Cardboard Boxes |
| Companies Covered | GRYFSKAND, Weber-Stephen Products LLC, Kingsford Products Company, Subur Tiasa Holdings Berhad, Haycarb PLC, Royal Oak Enterprises LLC, Timber Charcoal Company LLC, Fire & Flavor, Duraflame Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charcoal Briquette Market Strategic Shifts & Innovations
Carbonization technology advances and regulatory traceability mandates are restructuring competitive advantage around feedstock provenance verification rather than combustion performance alone.
Steel retort carbonization systems with methane capture and thermal energy recovery are rewriting production economics for export-grade briquette manufacturers. Large Indonesian and Brazilian processors are retrofitting facilities to meet EU CBAM documentation requirements. The technology is compressing cost structures for compliant producers while marginalizing traditional earth-mound operators.
REACH chemical registration and EU Deforestation Regulation due diligence obligations are forcing supply chain restructuring for European-bound charcoal shipments. Producers must now document geolocation coordinates for all biomass feedstock sources. Coconut shell charcoal from certified plantation sources is gaining preferential access relative to mixed-origin wood charcoal.
Foodservice distributor consolidation is concentrating procurement authority with national buying groups that demand uniform quality specifications and just-in-time delivery. Independent restaurant operators are losing negotiating leverage as Sysco, US Foods, and similar broadliners standardize briquette offerings. The shift is most visible in US metropolitan markets where chain barbecue concepts dominate outdoor dining expansion.
Charcoal Briquette Market Segmentation
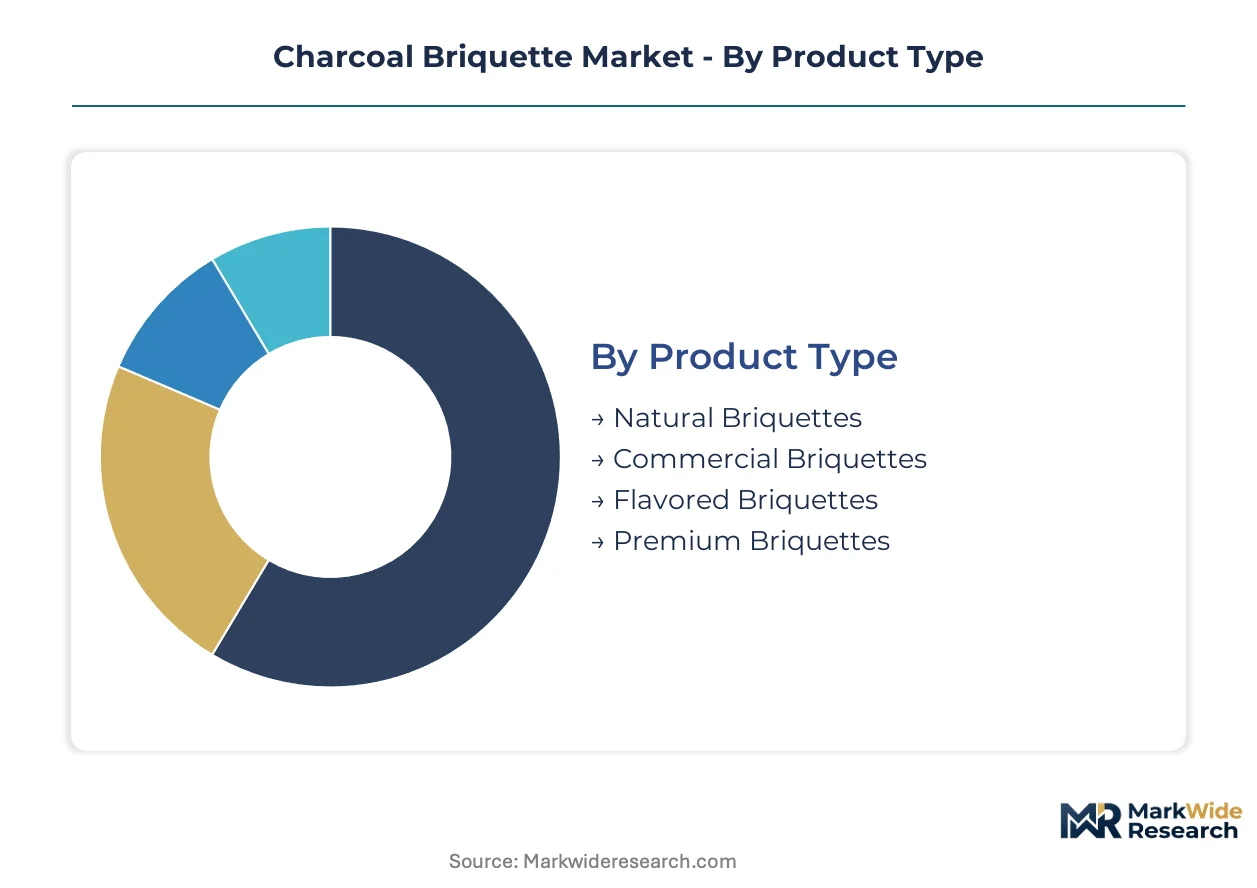
Segmentation in charcoal briquettes tracks how feedstock sourcing, combustion specifications, and channel economics partition demand across distinct buyer workflows. Product formulation and packaging format determine margin capture, while material origin shapes regulatory compliance burdens and carbon accounting requirements.
Product Type:
Standalone fuel products dominate foodservice procurement, while embedded flavor and premium positioning segments serve specialty retail and enthusiast channels with differentiated combustion profiles.
- Natural Briquettes:Compressed carbonized biomass bound with natural starch, delivering consistent heat output without chemical additives. Foodservice distributors in Brazil's São Paulo state specify these for churrasco operations where flame purity affects meat flavor profiles.
- Commercial Briquettes:Standardized density blocks engineered for extended burn duration and uniform temperature maintenance. Restaurant chain procurement consolidation favors these for national menu consistency across multi-unit barbecue concepts.
- Flavored Briquettes:Infused with hardwood essences (hickory, mesquite, apple) during carbonization. Specialty retail placement in US independent hardware stores targets residential grilling enthusiasts.
- Premium Briquettes:High-fixed-carbon formulations from coconut shell or select hardwood feedstocks with sub-5% ash residue. Indonesian SVLK-certified producers command price premiums in EU-bound shipments under EUDR due diligence requirements.
Volume placements concentrate in Commercial Briquettes; the faster expansion belongs to Premium Briquettes.
Application:
Cost tier separation distinguishes mature consumer barbecue demand from emerging industrial feedstock applications with divergent specification tolerances and contract structures.
- Barbecuing:Direct-heat cooking applications across residential, restaurant, and catering segments. Brazil's foodservice channel absorbs the largest share, with São Paulo state's churrasco culture sustaining premium briquette consumption.
- Industrial Use:Metallurgy fluxing, activated carbon precursor production, and water treatment feedstocks. Southeast Asian municipal filtration infrastructure upgrades are expanding offtake for high-grade charcoal derivatives.
- Smoking:Low-temperature, extended-duration combustion for flavor infusion in prepared meats. US specialty barbecue retailers stock dedicated smoking briquettes alongside pellet grill alternatives.
- Heating:Supplementary space heating in rural and off-grid residential settings. Seasonal demand fluctuates with heating degree days in temperate climate zones.
Barbecuing retains the largest revenue base; Industrial Use is climbing the fastest as activated carbon precursor demand accelerates.
Material:
Supply concentration patterns trace tropical agricultural residue availability against certified plantation timber sources with diverging traceability documentation burdens.
- Wood Charcoal:Carbonized hardwood from managed forests or agricultural clearance. Indonesia's SVLK verification requirements and Brazil's IBAMA deforestation monitoring constrain non-certified supply from Pará and Maranhão states.
- Coconut Shell Charcoal:Pyrolyzed coconut endocarp with superior fixed carbon content and minimal ash. Philippine and Indonesian processors with plantation-source documentation gain preferential EU market access under EUDR geolocation mandates.
- Agricultural Residues:Palm kernel shells, rice husks, and other crop processing byproducts. Supply volatility tracks tropical crop yields, squeezing margin predictability for manufacturers dependent on spot feedstock markets.
- Sawdust:Mill residue from lumber and furniture manufacturing, carbonized in retort systems. North American and European producers leverage captive sawmill relationships for cost-stable feedstock supply.
Wood Charcoal still dominates volume; Coconut Shell Charcoal is gaining share fastest on activated carbon precursor demand.
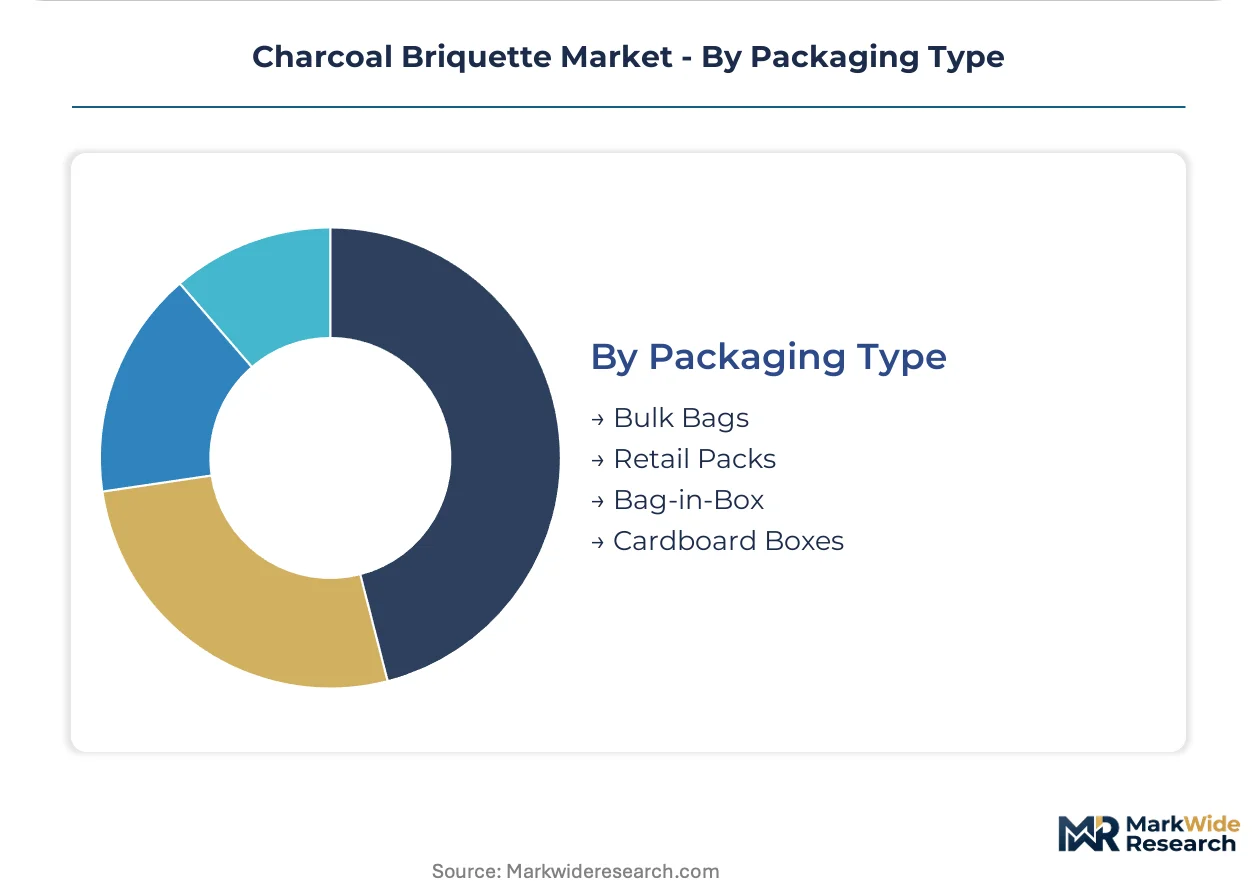
Packaging Type:
Customer type segmentation separates institutional procurement with scale economics from retail channel requirements for shelf presence and handling convenience.
- Bulk Bags:500-2000kg flexible intermediate bulk containers for industrial and large foodservice accounts. National broadliners like Sysco and US Foods specify bulk formats for distribution center efficiency.
- Retail Packs:2-10kg consumer-facing bags with moisture-resistant barriers and carry handles. US grocery and mass merchant channels demand pallet-ready case configurations.
- Bag-in-Box:Inner plastic liner within corrugated outer for club store and restaurant supply. Format balances moisture protection with stacking strength for warehouse retail.
- Cardboard Boxes:Rigid packaging for premium and gift-oriented briquette assortments. Specialty outdoor retailers favor these for dedicated grilling section merchandising.
Volume concentrates in Bulk Bags; Retail Packs show the steepest expansion trajectory as premium briquette placement expands in specialty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's São Paulo state concentrates the world's most intense barbecue-driven briquette consumption, while Indonesia and the United States anchor export production and retail distribution respectively. Regulatory enforcement in Southeast Asia and Latin America is fragmenting supply chains around certified feedstock provenance.
Brazil
Churrasco culture in São Paulo state sustains premium briquette demand across foodservice channels. IBAMA deforestation monitoring restricts wood charcoal exports from Pará and Maranhão states, pressuring producers toward certified agricultural residue sourcing. The São Paulo metropolitan corridor hosts the densest concentration of steakhouse chains and churrascaria concepts driving high-fixed-carbon product specifications.
Indonesia
SVLK timber legality verification from the Ministry of Environment and Forestry locks compliant wood charcoal exporters into long-term supply contracts with EU buyers. Coconut shell charcoal processors with plantation-source documentation gain preferential market access under EUDR geolocation mandates. Java-based producers dominate export volumes while Kalimantan operations face intensified sustainability audit requirements.
United States
EPA Clean Air Act particulate emission regulations govern domestic charcoal manufacturing while restaurant chain procurement consolidation favors national distribution networks. The Southeast and Midwest regions concentrate retail channel penetration through grocery and mass merchant banners. Pellet grill substitution pressure compresses growth in traditional charcoal-dependent residential segments.
Philippines
Plantation-source coconut shell charcoal production serves activated carbon precursor demand from water treatment infrastructure upgrades across Southeast Asia. Bureau of Product Standards certification requirements shape export quality specifications for metallurgy and filtration feedstock applications. Mindanao-based processors leverage integrated coconut milling relationships for feedstock cost stability.
Germany
EU Deforestation Regulation due diligence obligations force supply chain restructuring for charcoal shipments bound for Central European markets. REACH chemical registration requirements apply to processed carbon products entering industrial applications. The Rhine-Ruhr industrial corridor absorbs specialty briquette volumes for metallurgy fluxing and activated carbon manufacturing.
Charcoal Briquette Market Key Industry Players
Brazilian and Indonesian producers anchor the export-grade tier; United States specialists hold domestic retail and foodservice distribution. Market structure splits between vertically integrated plantation processors and brand-aggregating distributors with national logistics networks. Three archetypes dominate: certified-feedstock exporters, grocery-channel brand owners, and specialty retail placement specialists. Competitive moves center on SVLK/FSC certification acquisition and steel retort carbonization capacity expansion.
Within the grocery-channel tier, Kingsford Products Company and Duraflame Inc. exemplify brand-aggregating distribution scale. Royal Oak Enterprises LLC occupies a position among specialty retail and independent hardware channel specialists. Weber-Stephen Products LLC anchors bundled grill-and-fuel merchandising archetypes. GRYFSKAND represents European-certified feedstock sourcing structures. Subur Tiasa Holdings Berhad and Haycarb PLC sit within plantation-integrated coconut shell charcoal export positioning.
| Leading Market Players |
|---|
| GRYFSKAND |
| Weber-Stephen Products LLC |
| Kingsford Products Company |
| Subur Tiasa Holdings Berhad |
| Haycarb PLC |
| Royal Oak Enterprises LLC |
| Timber Charcoal Company LLC |
| Fire & Flavor |
| Duraflame Inc. |
| Others |
Cost & Logistics Intelligence
Coconut shell feedstock costs cascade through three distinct pricing tiers, with SVLK-certified Indonesian producers commanding premium placement in EU-bound shipments while uncertified wood charcoal from Brazil's Pará state trades at compressed margins under IBAMA enforcement pressure.
Pricing Analysis
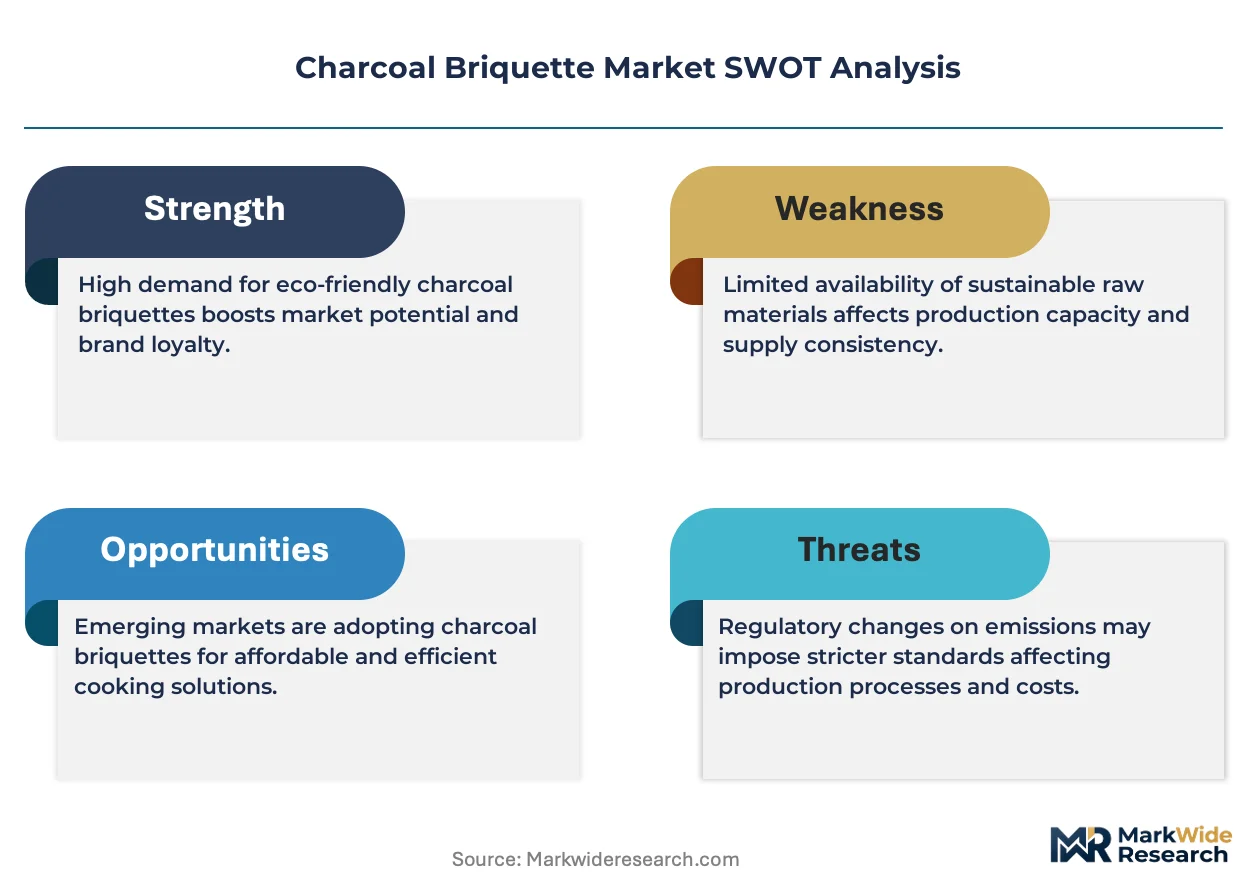
Volume placements concentrate in commercial-grade briquettes sold through national broadliners, while margin capture concentrates in premium coconut shell formulations with plantation-source documentation. Price differentiation hinges on certification tier and fixed carbon content, with EUDR-compliant producers extracting substantial premiums over mixed-origin competitors. Pricing pressure stems from agricultural residue feedstock volatility, particularly coconut shell availability tracking tropical crop yields. Restaurant chain procurement teams exhibit highest price sensitivity due to consolidated national buying group leverage, while specialty retail channels show lowest sensitivity as enthusiast buyers prioritize combustion performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows remain minimal in charcoal briquettes given combustion consumption, though spent activated carbon from water treatment applications creates secondary material recovery pathways for industrial metallurgy fluxing. Geographic supply concentrates in Indonesia, Brazil, and the Philippines, with Kalimantan and Mindanao processors dominating coconut shell charcoal exports. Raw material dependencies center on coconut endocarp, hardwood timber, and palm kernel shells with diverging traceability documentation burdens. Supply chain risk manifests as single-source vulnerability for EU-bound shipments dependent on SVLK-certified Indonesian exporters. Distribution runs through foodservice broadliners for institutional volumes and specialty outdoor retailers for premium consumer placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with plantation control over coconut shell feedstocks emerging as the decisive upstream lever separating margin leaders from price-takers.
For Market Incumbents: Anchor defensible positioning through captive coconut plantation relationships in Mindanao and Kalimantan, insulating against spot feedstock volatility that compresses margin predictability for competitors dependent on open markets. Accelerate steel retort carbonization retrofit programs to satisfy EU CBAM documentation requirements before compliance deadlines marginalize traditional earth-mound operators. Pellet grill substitution in US residential segments demands bundled grill-and-fuel merchandising to sustain brand loyalty against electrification pressure. For New Entrants and Emerging Players: Begin with white-space capture in Southeast Asian water treatment activated carbon precursor supply, where municipal filtration infrastructure upgrades outpace established producer capacity expansion. Target specialty retail channel placement in US independent hardware stores building dedicated grilling sections, as national broadliner consolidation leaves fragmented regional coverage vulnerable to niche penetration. Pursue plantation-source documentation from Philippine Bureau of Product Standards certified processors to unlock preferential EU market access under EUDR geolocation mandates. For Investors and Strategic Acquirers: Steel retort carbonization capacity announcements from Indonesian and Brazilian processors are the leading indicator that production economics are shifting toward compliance-heavy capital intensity that favors scaled players over artisanal operators. Long-term viability hinges on backward integration into certified feedstock sourcing rather than brand aggregation alone. Acquisition targets should display integrated plantation relationships or locked long-term supply contracts with SVLK-certified timber suppliers. Monitor EU Deforestation Regulation enforcement actions as the critical signal for which export-oriented producers will retain market access versus face exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Steel Retort Carbonization Retrofit | EU CBAM compliance requirements favor producers with thermal energy recovery and methane capture systems. |
| Plantation Feedstock Integration | Captive coconut shell supply from Mindanao and Kalimantan insulates margin predictability against tropical crop yield volatility. |
| SVLK Certification Investment | Indonesian Ministry of Environment and Forestry verification locks compliant exporters into long-term EU supply contracts. |
| Specialty Retail Channel Expansion | Independent hardware store grilling sections favor premium briquette placement over grocery channel commoditization. |
| Activated Carbon Precursor Positioning | Southeast Asian municipal filtration infrastructure upgrades expand offtake for high-grade charcoal derivatives. |
Research Approach
Independent corroboration across foodservice distributor procurement leads, coconut plantation operations managers, and activated carbon manufacturer technical directors underwrites the qualitative findings in this study. Primary fieldwork engaged carbonization plant engineers, SVLK certification auditors, and national broadliner category buyers alongside secondary validation through Indonesian Ministry of Environment and Forestry export statistics, Philippine Bureau of Product Standards certification records, and EU trade flow documentation. Bottom-up triangulation across feedstock cost structures and top-down reconciliation against channel shipment volumes ensures analytical robustness.
Rate-of-change decomposition across product type, application, material origin, and packaging format segments drives the forecast framework. Modeled dimensions include feedstock certification tier, combustion specification grade, and regional regulatory cluster. CAGRs derive from segment-level demand elasticity analysis against supply-side capacity constraints, with projection inputs incorporating SVLK audit cycle timelines, steel retort adoption curves, and EU Deforestation Regulation implementation phases across the analysis window.
Underlying measurement precision varies by segment; premium briquette and activated carbon precursor categories carry tighter precision than commoditized commercial-grade volumes given concentrated producer bases and transparent export documentation. Forecasts reflect assumptions on certification timeline compression and legacy kiln modernization capex availability that could revise trajectory if regulatory enforcement intensity shifts or agricultural residue supply disruption exceeds historical volatility bands. Practitioners should monitor EU CBAM documentation deadline adherence and IBAMA deforestation enforcement actions in Pará and Maranhão states for early signals of supply-side restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
South Korea LNG Bunkering Market
Fuels
Solid Fuel Tablet Market
Fuels
South America Aviation Fuel Market
Fuels
Gas Hydrates Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Europe Coal Market
Fuels
Liquid Propellants Market
Fuels
China LNG Bunkering Market
Fuels
White Coal Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
LNG Filling Station Market
Fuels
Hybrid Propellants Market
Fuels
India Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
LNG As a Fuel Market