
 Renewable Fuel Quality and Regulatory Compliance Test Instruments Market | 2026-2036
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market Insights
Multi-sourced instrument procurement is realigning how refiners and biofuel producers build their analytical capabilities. Anton Paar leverages its density and viscosity measurement specialization to anchor European renewable fuel certification workflows. Thermo Fisher Scientific sustains broad chromatography and mass spectrometry portfolios that span fuel blending analysis through emissions compliance testing. Intertek Group competes on third-party validation services, extending instrument deployment models beyond direct sales into managed analytical service contracts.
Renewable fuel quality and regulatory compliance test instruments comprise precision analytical systems that measure chemical composition, physical properties, and contaminant levels in biofuels and blended petroleum products using techniques such as gas chromatography with flame ionization detection at parts-per-million sensitivity and infrared spectroscopy for fatty acid methyl ester quantification. These instruments enable producers to verify compliance with renewable identification number tracking, carbon intensity scoring, and storage stability protocols before commercial release. Chromatographs and spectrometers dominate capital expenditure patterns due to their centrality in multi-parameter fuel certification, while flash point testers occupy a mature replacement-driven segment with lower growth but predictable aftermarket revenue. Calorimeters and viscosity meters are gaining share in emerging renewable diesel and sustainable aviation fuel applications where energy density and cold-flow properties carry premium regulatory weight.
The EPA administers Renewable Fuel Standard enforcement through standardized test methods that mandate specific instrument precision classes for renewable identification number generation. ASTM International and the California Air Resources Board layer additional compliance protocols that shape product development roadmaps for instrument manufacturers serving North American biofuel markets. Europe's ECHA and REACH frameworks impose substance-level disclosure requirements that extend test instrument demand into feedstock traceability applications. Stakeholders must monitor how evolving lifecycle carbon accounting rules will redefine which analytical parameters become mandatory versus optional in renewable fuel qualification pathways.
Market Dynamics
EPA enforcement of Renewable Fuel Standard measurement tolerances is compressing allowable analytical variance below 0.5% for biodiesel blend verification, forcing producers to retire legacy flash point testers and recalibrate entire quality control workflows around chromatography-centered multi-parameter certification.
Growth Catalysts
- California Air Resources Board carbon intensity scoring:The LCFS protocol mandates quarterly third-party verification of fuel pathway carbon values, creating recurring instrument service contracts and consumables demand across ethanol and renewable diesel facilities.
- Sustainable aviation fuel cold-flow property requirements:ASTM D7566 specifications for freeze point and viscosity at altitude are driving calorimeter and viscometer procurement at biorefineries co-processing hydroprocessed esters.
- Biofuel producers:In-house laboratory expansion at US Midwest ethanol plants and Gulf Coast renewable diesel complexes is displacing external testing dependencies and accelerating capital deployment toward automated gas chromatography systems.
Market Restraints
- Helium supply concentration:US Bureau of Land Management stewardship of federal helium reserves and Qatar's dominance in liquefied natural gas-derived helium extraction creates price volatility for gas chromatography carrier gas, directly inflating operating cost structures for high-throughput fuel analysis laboratories.
- Reference standard scarcity:NIST-traceable certified reference materials for fatty acid methyl ester matrices exhibit 12-16 week lead times, constraining method validation timelines and instrument commissioning schedules.
- Skilled technician availability:Regional labor markets around Houston and Des Moines show acute shortages of chromatography method developers familiar with ASTM D5501 and EN 14103 protocols, extending installation and qualification periods.
Strategic Opportunities
- Near-infrared spectroscopy-portable deployment:Handheld NIR units for biodiesel blend verification at fuel terminal loading racks are penetrating downstream distribution infrastructure previously served only by central laboratory analysis.
- EPA RFS eRIN pathway expansion:Proposed electricity-based renewable identification number qualification for biogas-to-grid applications would extend test instrument demand into biomethane composition analysis and siloxane detection markets.
- Lifecycle carbon accounting integration:Convergence of chromatography data management systems with feedstock traceability software platforms creates bundled analytical service offerings linking laboratory measurement to regulatory reporting automation.
Industry Challenges
- Method transfer complexity:Migrating ASTM D7371 infrared biodiesel blend analysis from laboratory Fourier-transform instruments to process analytical technology installations at continuous renewable diesel hydrotreaters requires extensive correlation studies against offline reference methods.
- Calibration drift management:Flame ionization detector response factors for ethanol-gasoline blends degrade under high-sulfur sample matrices common in imported sugarcane ethanol, demanding more frequent validation cycles and consumables replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Fuel Quality and Regulatory Compliance Test Instruments Market |
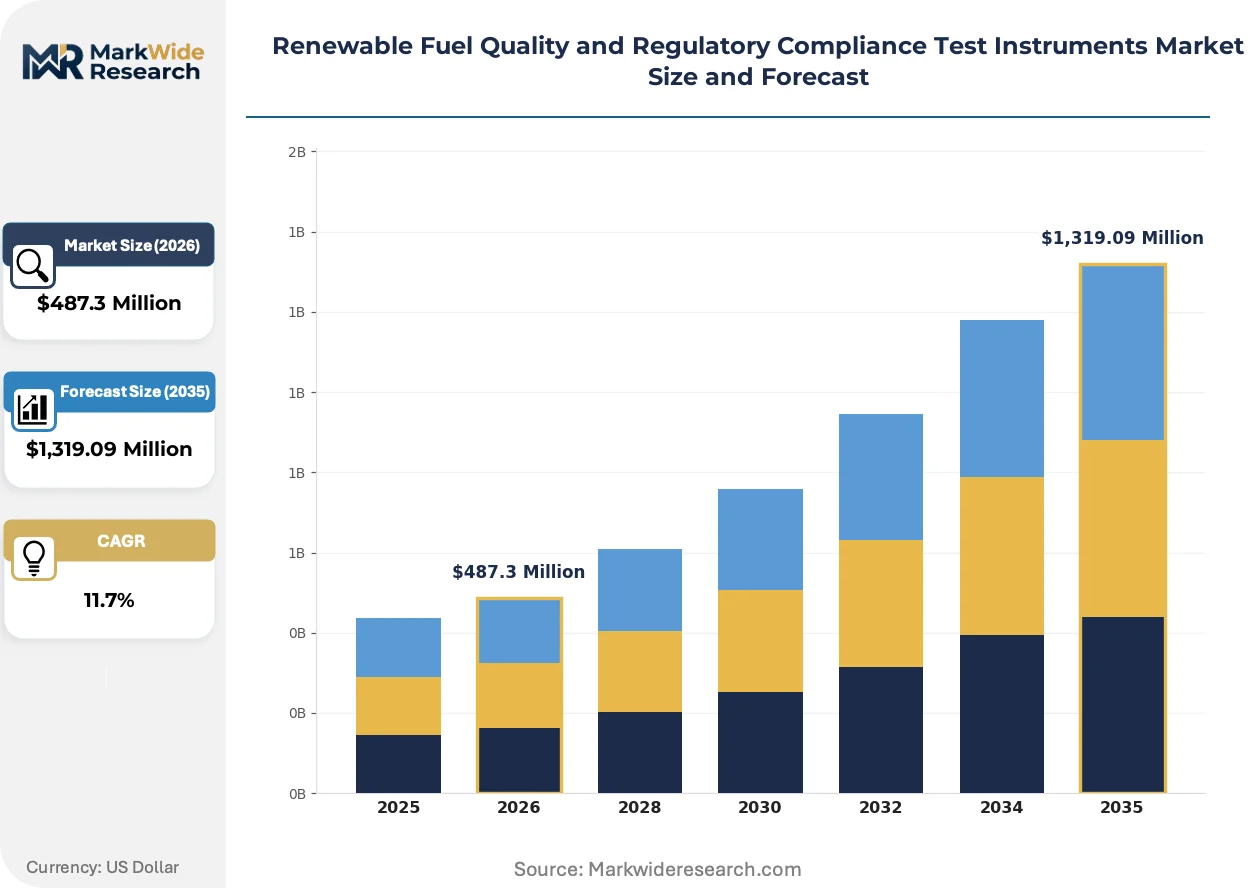
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatographs, Spectrometers, Calorimeters, Viscosity Meters, Flash Point Testers Technology: Gas Chromatography, Infrared Spectroscopy, Mass Spectrometry, Ultraviolet Spectrophotometry, Rheometry Application: Fuel Blending Analysis, Contaminant Detection, Additive Content Testing, Emissions Compliance, Storage Stability Assessment End User: Refiners, Biofuel Producers, Regulatory Agencies, Quality Control Labs, Certification Bodies |
| Companies Covered | Emerson Electric, Honeywell International, ABB, Siemens, Endress+Hauser, Baker Hughes, Anton Paar, Thermo Fisher Scientific, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market Trends and Innovations
Instrument architectures are converging around modular platforms that consolidate multiple ASTM and EN test methods into single automated sequences, compressing capital footprints while expanding analytical throughput for multi-fuel biorefineries.
Multi-detector gas chromatography configurations are unifying flame ionization detection with vacuum ultraviolet spectroscopy in single analytical runs, enabling simultaneous quantification of ethanol content, benzene traces, and oxygenate speciation. Renewable diesel producers in Louisiana and Texas are adopting these unified platforms to replace sequential single-method instruments. This consolidation is compressing laboratory floor space requirements and reducing per-sample analytical labor by eliminating manual sample transfer between discrete instrument stations.
EPA's proposed updates to 40 CFR Part 80 test method equivalency protocols are narrowing acceptable variance windows for D5501 ethanol blend analysis from plus-or-minus 0.9 volume percent to plus-or-minus 0.5 volume percent. Refiners and importers must revalidate existing chromatography methods or procure higher-precision instrumentation. The ethanol marketing and trading segment faces the most acute compliance pressure, with terminal operators in Nebraska and Iowa already upgrading to temperature-controlled autosamplers and narrower-bore capillary columns.
Third-party managed analytical service contracts are displacing direct instrument ownership at mid-sized biodiesel facilities lacking dedicated metrology staff. Intertek and similar providers deploy portable chromatography units on monthly rotation, transferring capital burden to operational expenditure. This model concentrates most rapidly among 5-30 million gallon per year producers in the US Southeast where technical staffing constraints intersect with seasonal feedstock variability demanding flexible analytical capacity.
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market Segmentation
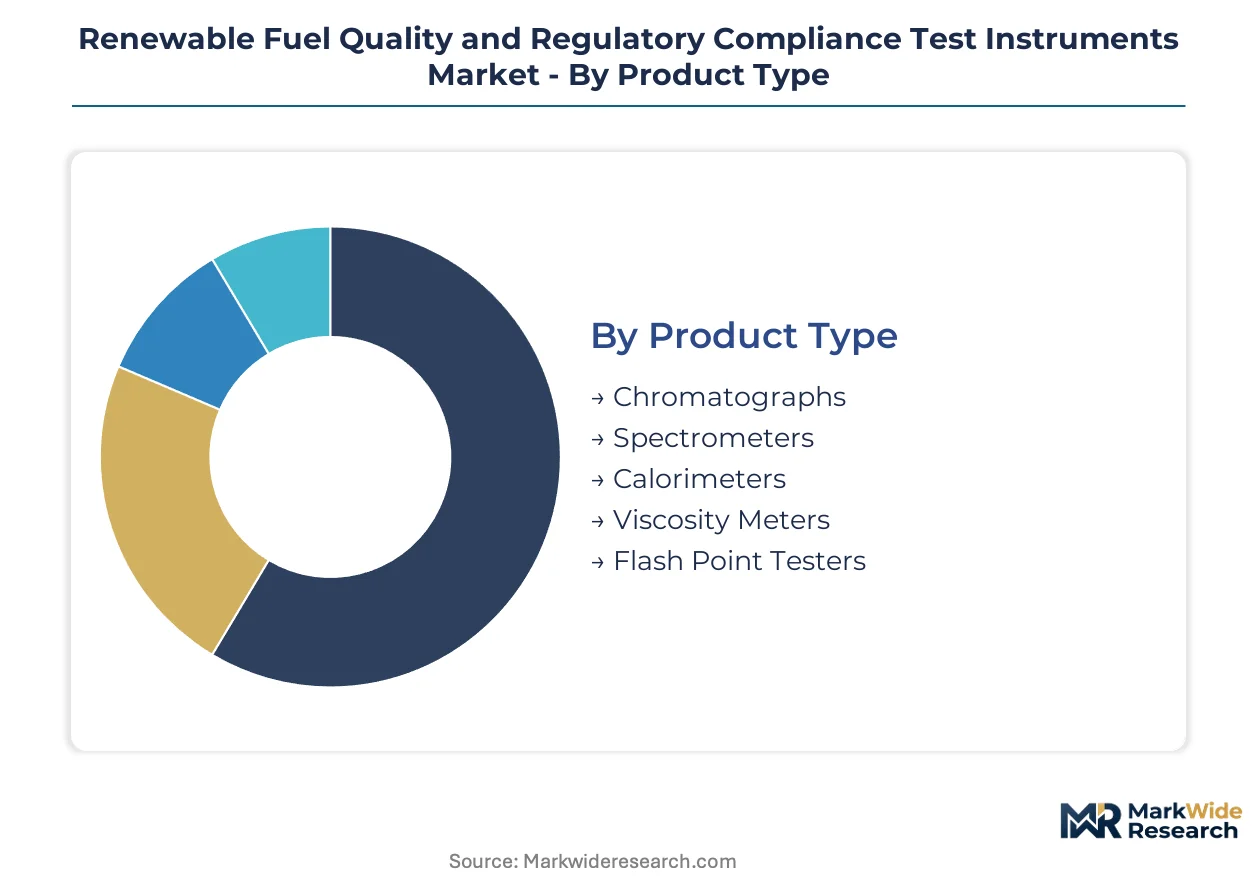
Segmentation in renewable fuel test instruments reflects divergent capital deployment strategies across precision requirements and regulatory stringency. Producers prioritize multi-parameter platforms that consolidate ASTM and EN protocols, while terminal operators favor portable units for downstream verification.
Product Type:
Technology sophistication separates instruments by analytical capability and capital intensity.
- Chromatographs:Gas chromatography systems with flame ionization detection achieve parts-per-million sensitivity for ethanol and biodiesel blend quantification. US Midwest ethanol plants and Gulf Coast renewable diesel complexes are automating these platforms to replace manual sample workflows under tightening EPA measurement tolerances.
- Spectrometers:Fourier-transform infrared and near-infrared systems enable rapid fatty acid methyl ester quantification without sample derivatization. Louisiana and Texas biorefineries deploy these for real-time process control at hydrotreater outlets where cold-flow property verification drives procurement.
- Calorimeters:Bomb calorimetry systems measure energy density for renewable diesel and sustainable aviation fuel certification pathways.
- Viscosity Meters:Rheometric and kinematic viscometers assess cold-flow performance at altitude-relevant temperatures.
- Flash Point Testers:Pensky-Martens and Tag closed-cup apparatus remain staple equipment for biodiesel storage safety compliance.
Mature deployment sits with flash point testers. Newer deployment is concentrated in chromatographs.
Technology:
Detection principles determine throughput, precision, and regulatory acceptance.
- Gas Chromatography:Capillary GC with autosampler integration dominates renewable identification number generation workflows. Nebraska and Iowa terminal operators are upgrading to temperature-controlled systems with narrower-bore columns as EPA compresses allowable variance for D5501 ethanol analysis.
- Infrared Spectroscopy:Portable NIR units are penetrating fuel terminal loading racks previously served only by central laboratories. Southeast US biodiesel distributors deploy handheld verification tools to confirm blend ratios at point of custody transfer.
- Mass Spectrometry:GC-MS configurations enable contaminant identification at trace levels for feedstock qualification.
- Ultraviolet Spectrophotometry:UV-Vis systems support additive content quantification in oxygenated gasoline formulations.
- Rheometry:Rotational and oscillatory rheometers characterize viscoelastic properties of hydroprocessed ester intermediates.
Laboratory-scale deployment concentrates in gas chromatography. Field-scale expansion is accelerating fastest in infrared spectroscopy.
Application:
Regulatory mandate intensity varies across the fuel lifecycle.
- Fuel Blending Analysis:Ethanol-gasoline and biodiesel-diesel ratio verification commands the largest instrument installed base. California Air Resources Board LCFS quarterly verification requirements sustain recurring service contracts across ethanol and renewable diesel facilities.
- Contaminant Detection:Siloxane and sulfur speciation analysis is gaining traction in biogas-to-grid applications under proposed EPA eRIN pathway expansions.
- Additive Content Testing:Detergent and corrosion inhibitor quantification supports gasoline detergent certification.
- Emissions Compliance:Benzene and oxygenate speciation enables refinery regulatory reporting.
- Storage Stability Assessment:Oxidation stability and sediment formation testing addresses biodiesel degradation during extended holding.
Compliance-driven procurement dominates fuel blending analysis. Emerging demand is concentrating in contaminant detection.
End User:
Capital ownership models diverge by scale and technical staffing.
- Refiners:Integrated petroleum refiners deploy multi-detector platforms for both petroleum and renewable fuel certification. These operators consolidate ASTM D7566 sustainable aviation fuel testing with conventional jet fuel analysis on unified chromatography systems.
- Biofuel Producers:In-house laboratory expansion at 5-30 million gallon per year facilities is displacing external testing dependencies. Third-party managed analytical service contracts are penetrating this segment where chromatography method developers remain scarce.
- Regulatory Agencies:EPA and state environmental departments maintain reference laboratories for enforcement sampling.
- Quality Control Labs:Independent testing facilities serve mid-sized producers lacking dedicated metrology staff.
- Certification Bodies:Third-party validators execute California LCFS and EPA RFS verification protocols.
Direct instrument ownership prevails among refiners. Service-based deployment is expanding fastest among biofuel producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern corn belts and Gulf Coast petrochemical corridors anchor instrument demand through concentrated biofuel production infrastructure.
United States
EPA Renewable Fuel Standard enforcement compresses measurement tolerances below 0.5% for biodiesel blend verification. Nebraska and Iowa terminal operators upgrade to temperature-controlled autosamplers and narrower-bore capillary columns. The Gulf Coast renewable diesel complexes in Louisiana and Texas drive calorimeter and viscometer procurement for sustainable aviation fuel certification.
Germany
REACH substance-level disclosure requirements extend test instrument demand into feedstock traceability applications. ECHA frameworks mandate precision analytical systems for renewable fuel pathway verification. Bavarian and North Rhine-Westphalian biorefineries deploy multi-detector gas chromatography platforms to consolidate ASTM and EN protocols.
Brazil
Sugarcane ethanol export matrices with high sulfur content degrade flame ionization detector response factors, demanding frequent validation cycles. The national biofuel regulator mandates quarterly carbon intensity verification for export qualification. São Paulo state biorefineries expand in-house quality control laboratories to displace external testing dependencies.
Canada
Clean Fuel Standard implementation drives renewable diesel and sustainable aviation fuel production growth. Alberta and Saskatchewan biofuel facilities procure chromatography-centered multi-parameter certification systems. Ontario ethanol plants automate gas chromatography platforms to meet federal blend verification mandates.
India
Ethanol blending program expansion to 20% mandates creates instrument procurement pressure at sugarcane-based distilleries. BIS standards for fuel quality testing shape product development roadmaps for instrument manufacturers. Maharashtra and Uttar Pradesh ethanol clusters deploy flash point testers and viscosity meters for storage safety compliance.
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market Competitive Landscape
Global majors compete with regional champions across precision measurement specialization and service deployment models. The vendor base stratifies into three tiers: integrated industrial conglomerates with broad automation portfolios, analytical instrument specialists with chromatography and spectroscopy depth, and third-party validation providers with managed service capabilities. Dominant competitive moves include portfolio diversification into multi-detector platforms and geographic expansion through third-party analytical service contracts.
Within the analytical specialization tier, Anton Paar anchors European renewable fuel certification workflows through density and viscosity measurement expertise. Thermo Fisher Scientific occupies a position exemplifying broad chromatography and mass spectrometry portfolios spanning fuel blending analysis through emissions compliance testing. Intertek Group represents the third-party validation archetype, extending instrument deployment models beyond direct sales into managed analytical service contracts that transfer capital burden to operational expenditure for mid-sized producers.
| Leading Market Players |
|---|
| Emerson Electric |
| Honeywell International |
| ABB |
| Siemens |
| Endress+Hauser |
| Baker Hughes |
| Anton Paar |
| Thermo Fisher Scientific |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
Chromatography method developers in Houston and Des Moines command wage premiums that compress margins at mid-sized biofuel facilities, widening the spread between premium multi-detector platforms and economy-tier flash point testers.
Pricing Analysis
Extended warranty and calibration service bundling distinguishes premium gas chromatography systems from unbundled economy alternatives where validation cycles incur separate fees. Three-tier pricing structure across premium, standard, and economy levels separates Anton Paar and Thermo Fisher Scientific configurations from Intertek's managed service contracts. Cost compression in the economy tier is intensifying because helium carrier gas price volatility inflates operating budgets for high-throughput laboratories. Biofuel producers in the 5-30 million gallon per year range exhibit acute price sensitivity, while integrated refiners absorbing capital costs show minimal elasticity.
Supply Chain Analysis
Helium supply rests on US Bureau of Land Management stewardship of federal reserves and Qatar's dominance in liquefied natural gas-derived extraction, creating single-source vulnerability for gas chromatography carrier gas. Capillary columns, autosampler consumables, and NIST-traceable certified reference materials constitute critical input dependencies. Tariff exposure on Chinese-manufactured optical components for spectrometers threatens infrared system cost structures. Distribution runs through direct manufacturer sales for large refiners and third-party service contracts for mid-sized producers lacking metrology staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA enforcement of sub-0.5% measurement tolerances is forcing consolidation as legacy instrument owners face stranded asset risk from obsolete flash point testers.
For Market Incumbents: Deploy multi-detector platform consolidation to capture laboratory floor space compression demand at Gulf Coast renewable diesel complexes. Backward integration into consumables manufacturing insulates margin structures from helium price volatility and reference material lead time constraints. Threat substitution from portable near-infrared units at fuel terminals demands premium calibration service bundling to defend installed base stickiness. For New Entrants and Emerging Players: EPA's proposed eRIN pathway expansion in the United States opens a window for biomethane composition analysis specialists to penetrate biogas-to-grid verification markets. Southeast US biodiesel distributors represent the most penetrable segment given technical staffing constraints and seasonal feedstock variability. A handheld NIR deployment model with monthly rotation service contracts transfers capital burden to operational expenditure for facilities lacking chromatography expertise. For Investors and Strategic Acquirers: Re-rating potential sits with third-party validation providers given California Air Resources Board LCFS quarterly verification mandates sustaining recurring revenue visibility. Mid-sized analytical service contracts in the 5-30 million gallon producer segment offer five-to-ten year contracted cash flow streams with embedded consumables pull-through. Watch EPA test method equivalency protocol finalization as the inflection trigger for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Detector Platform Consolidation | Unifies ASTM D7566 and D5501 protocols for sustainable aviation fuel certification at Louisiana biorefineries. |
| Managed Analytical Service Contracts | Transfers capital burden to operational expenditure for Southeast US biodiesel producers lacking metrology staff. |
| Helium Recovery and Recycling Systems | Mitigates carrier gas price volatility for high-throughput gas chromatography laboratories in Nebraska and Iowa. |
| Portable NIR Terminal Deployment | Penetrates downstream fuel distribution infrastructure previously served only by central laboratory analysis. |
| Lifecycle Carbon Accounting Integration | Links chromatography data management to California LCFS feedstock traceability software platforms. |
Research Methodology
Independent corroboration across EPA enforcement guidance documents, ASTM International method revision records, and California Air Resources Board LCFS verification protocols underwrites the qualitative findings. Primary interviews with biofuel quality control laboratory directors, chromatography method developers, and third-party validation service contract managers combined with secondary validation from EIA renewable fuel production statistics, NIST reference material availability reports, and SEC instrument manufacturer filings. Bottom-up facility-level procurement tracking and top-down regulatory mandate sizing provided cross-check triangulation.
Comparable-period anchoring to historical EPA measurement tolerance compression episodes informed variance assumptions across the projection horizon. Segmentation modeling spanned product type, detection technology, application mandate intensity, and end-user capital ownership model dimensions. CAGRs derived from facility expansion announcements, instrument replacement cycle analysis, and regulatory timeline probability weighting. Helium supply concentration and reference material lead time constraints factored as supply-side dampeners on adoption velocity.
The model assumes a particular technology adoption path; alternative pathways for near-infrared spectroscopy displacing laboratory gas chromatography would alter the outlook. Forecasts reflect assumptions regarding EPA eRIN pathway finalization timing and California LCFS carbon intensity methodology stability. A small set of triggers—helium reserve privatization legislation, ASTM method variance window revisions, and biogas-to-grid interconnection standards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Coal Briquette Box Market
Fuels
Industrial Fuel Filter Market
Fuels
Fuel Oil Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
Oil & Gas Lubricants Market
Fuels
Global Fuel Ethanol Market
Fuels
Multifuel Gas Turbine Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
South America Bunker Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Global Wood Gas Generator Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Wood Charcoal Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
China LNG Bunkering Market
Fuels
Global Gas Treatment Market