
 Date Sugar Market | 2026-2036
Date Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Date Sugar Market Analysis
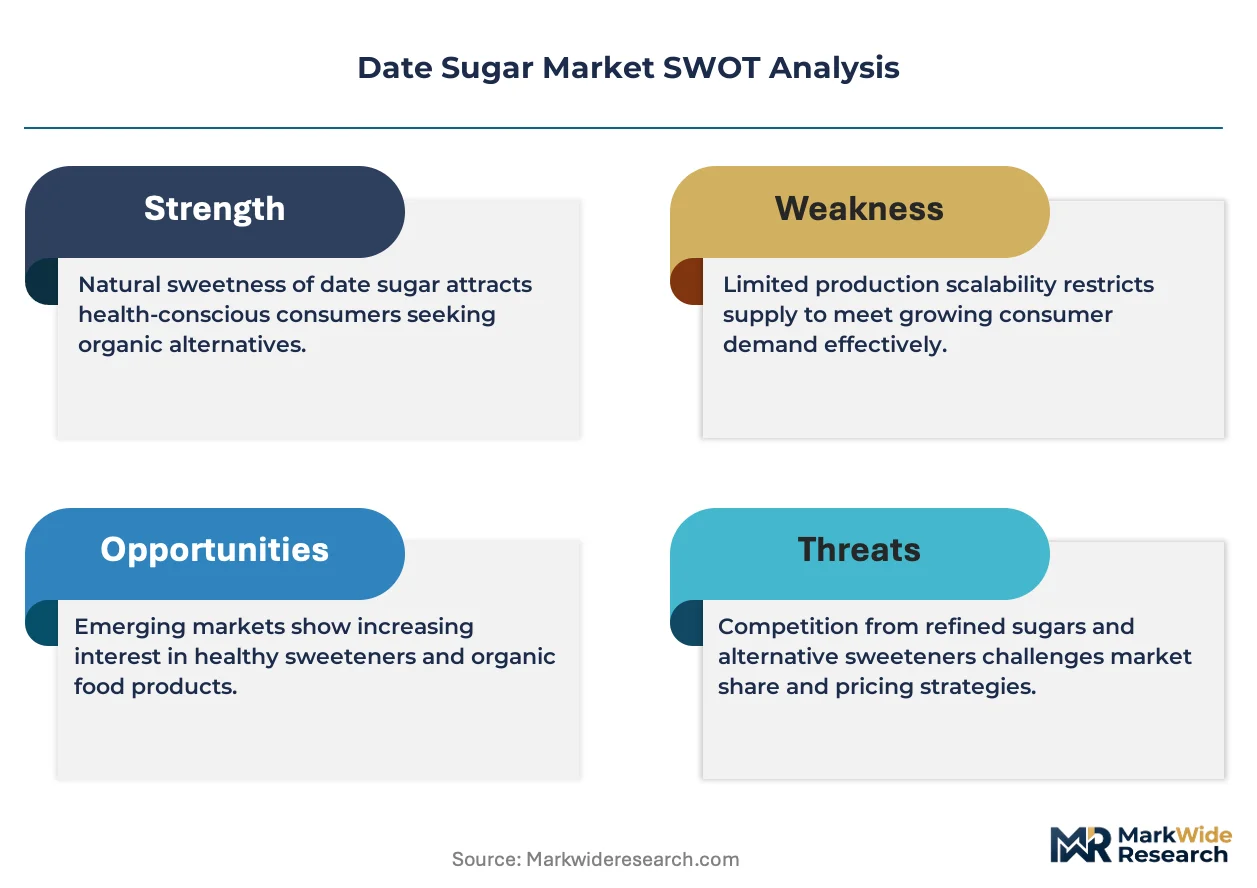
REACH compliance in Europe is expanding the cost-of-entry calculus for date sugar suppliers seeking shelf space in EU retail channels. Now Foods leverages its organic certification infrastructure to sustain North American distribution depth. Bob's Red Mill Natural Foods anchors its competitive position through heritage brand strength in specialty flour and natural sweetener aisles. Date Lady specializes in single-origin date supply chains, differentiating its product narrative from commodity-grade alternatives.
Date sugar consists of dried, ground date fruit with naturally occurring fructose, glucose, and sucrose, typically retaining fiber content and mineral profiles absent in refined cane sugar; manufacturers pulverize whole dates at controlled temperatures to preserve enzymatic activity and prevent caramelization. The ingredient serves commercial bakeries and health-oriented food processors seeking reduced-glycemic sweetening with clean-label appeal. Granulated and organic product types command premium positioning as consumers scrutinize ingredient lists, while liquid formats compete in beverage applications where solubility determines formulation viability. Baking and confectionery applications absorb the dominant volume share, though snack foods represent an emerging channel as protein-bar manufacturers reformulate away from artificial sweeteners.
FDA labeling requirements in the United States, EFSA Novel Food consultations in Europe, and FSSAI standards in India collectively shape product specifications, import documentation burdens, and health claim permissibility across major demand centers. These frameworks elevate compliance costs for smaller suppliers while rewarding pre-certified operators with accelerated market access. Stakeholders must monitor evolving glycemic index disclosure rules and organic equivalency agreements to anticipate which production geographies will retain tariff advantages.
Market Dynamics
Clean-label mandates from the EU Green Deal and FDA disclosure rules are compressing formulation timelines for commercial bakers, forcing rapid substitution of refined cane sugar with minimally processed alternatives that retain fiber and mineral content.
Growth Catalysts
- REACH Compliance Expansion:ECHA's tightening additive restrictions in Europe are disqualifying synthetic sweeteners from retail channels, opening shelf space for date sugar in Germany and France.
- Protein Bar Reformulation:Snack food manufacturers are accelerating date sugar procurement to replace artificial sweeteners in clean-label protein formulations.
- Organic Certification Infrastructure:Pre-certified suppliers in North America are capturing accelerated market access as compliance costs rise for uncertified competitors.
Market Restraints
- Input Cost Volatility:Date harvest yields in the Middle East and North Africa fluctuate with irrigation water scarcity, compressing supplier margins.
- Technical Solubility Limitations:Granulated date sugar's poor cold-water dissolution restricts beverage applications where liquid cane syrup dominates.
- Regulatory Documentation Burden:FSSAI standards in India and EFSA Novel Food consultations impose lengthy approval timelines for new suppliers.
Strategic Opportunities
- Underpenetrated Indian Market:FSSAI's evolving standards create first-mover advantage for suppliers establishing organic equivalency agreements with Indian authorities.
- Confectionery Premiumization:Single-origin date supply chains command price premiums in artisan chocolate and premium baking segments.
- Dual Carbon Policy Alignment:China's SAMR sustainability incentives favor low-carbon sweetener alternatives in domestic food processing.
Industry Challenges
- Specialized Milling Equipment Scarcity:Temperature-controlled pulverization systems that preserve enzymatic activity require capital investment that smaller processors cannot access.
- Organic Equivalency Negotiation Complexity:Bilateral recognition agreements between USDA NOP and foreign certifiers delay export market entry by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Date Sugar Market |
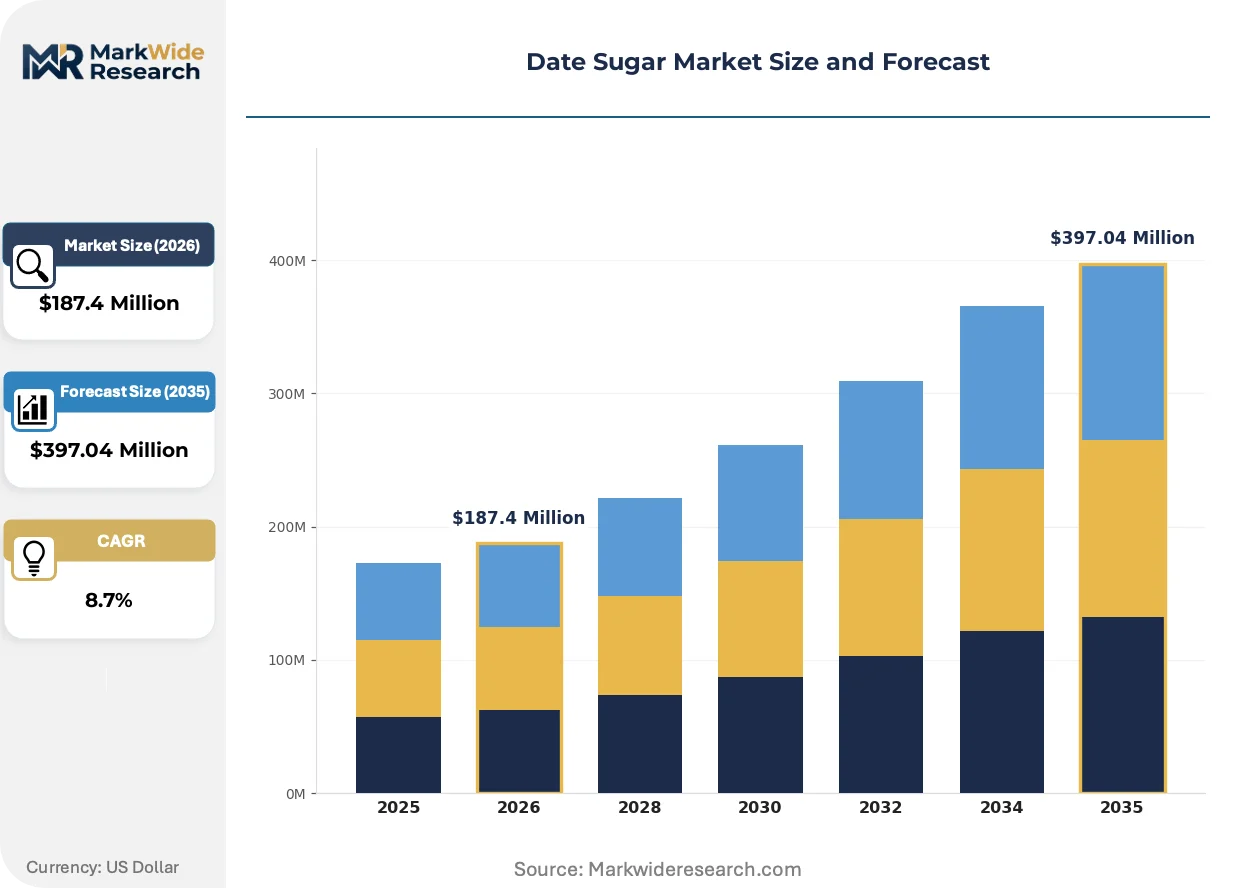
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Liquid, Organic Application: Baking, Beverages, Confectionery, Snack Foods Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers End User: Food Industry, Home Cooks, Restaurants, Health Food Stores |
| Companies Covered | Now Foods, Teeccino, Bob’s Red Mill Natural Foods, Chatfield’s Brands, Clarks U.K., Date Lady, Barry Farms, Glory Bee, Naturalia Ingredients SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Date Sugar Market Emerging Trajectories
Processing technology advances and regulatory disclosure mandates are reshaping competitive positioning in date sugar, with fiber retention and glycemic transparency becoming primary differentiation vectors.
Spray-drying technology for date syrup is converging with beverage formulation requirements, enabling cold-soluble formats that maltodextrin carriers previously dominated. Sports drink manufacturers in the United States are piloting these formats for reduced-glycemic product lines. The structural consequence is compression of liquid sweetener substitution timelines.
EFSA's evolving Novel Food consultation framework is extending safety assessment requirements for non-traditional sweeteners, elevating documentation burdens for date sugar entrants without GRAS-equivalent status. European bakery chains are delaying reformulation timelines pending clarity. German and French retail buyers are prioritizing suppliers with pre-submitted dossiers.
Ingredient list scrutiny by health-conscious consumers is shortening switching cycles between sweetener suppliers, with procurement teams demanding batch-level glycemic index documentation. Direct supplier relationships are displacing distributor intermediaries in North American natural food channels. This pattern concentrates in California and Pacific Northwest retail clusters where clean-label penetration is deepest.
Date Sugar Market Segmentation
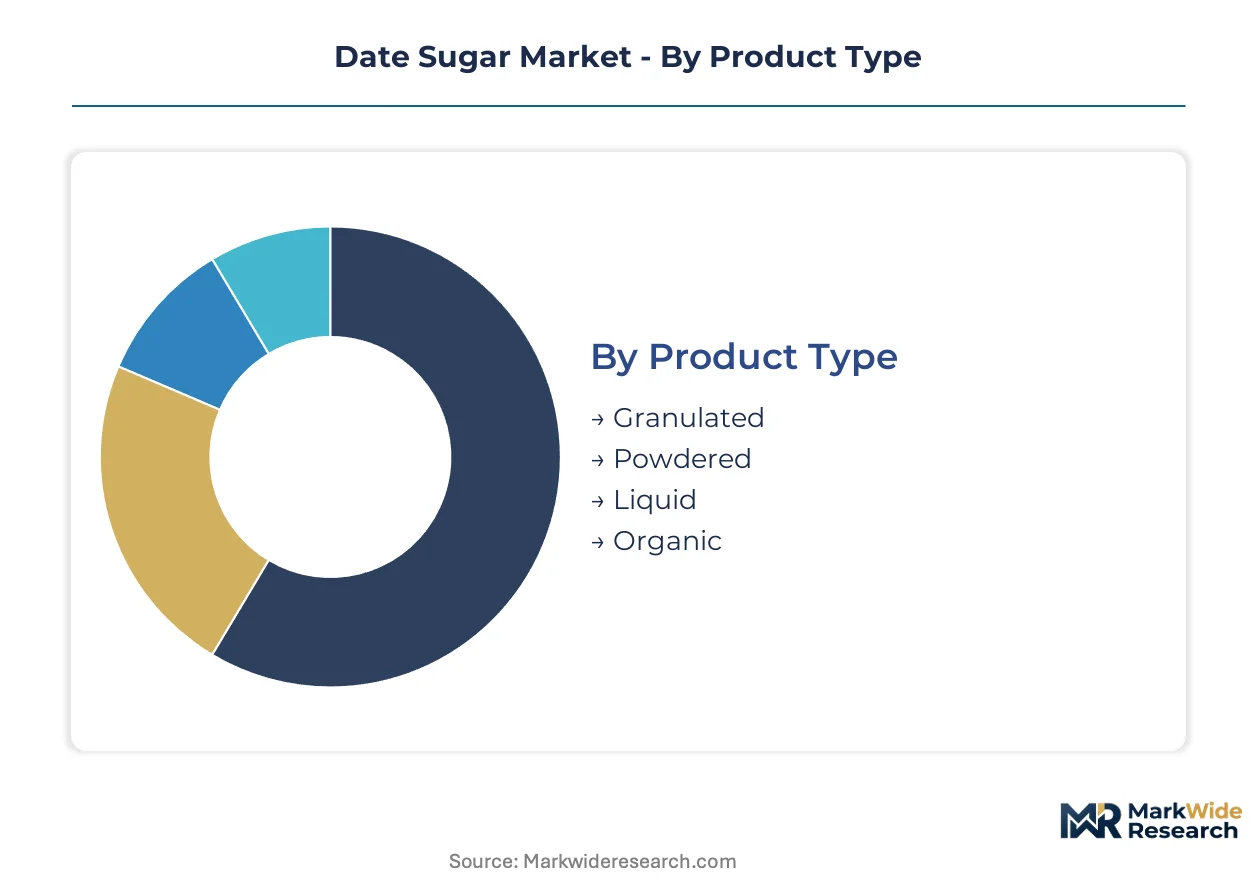
Date sugar procurement patterns diverge sharply across product formats and use cases. Manufacturers optimize formulations around solubility thresholds, fiber retention rates, and clean-label positioning mandates that vary by end-use channel.
Product Type:
Granulation technology and moisture content define functional viability across temperature-sensitive applications.
- Granulated:Coarse crystalline structure from low-temperature pulverization retains date fiber and enzymatic activity. Commercial bakeries in Germany and France specify this format for clean-label bread formulations where particle size affects moisture binding.
- Organic:USDA NOP or EU Organic certification commands shelf-space priority in North American natural food channels. Pre-certified suppliers capture accelerated retail placement as REACH compliance tightens additive restrictions across European markets.
- Powdered:Finer milling enables dusting applications in artisan confectionery and dry mix formulations.
- Liquid:Date syrup concentrates serve beverage manufacturers seeking cold-soluble sweetening with reduced glycemic signatures.
Granulated leads on scale; organic leads on momentum.
Application:
Formulation requirements dictate thermal stability and dissolution speed specifications by end-use.
- Baking:Heat-stable granules caramelize predictably between 160-180°C, enabling cookie and cake applications where Maillard reaction control determines product consistency. French and German industrial bakeries drive procurement volume as EU Green Deal mandates accelerate refined sugar substitution timelines.
- Snack Foods:Protein bar manufacturers reformulate away from artificial sweeteners, concentrating demand in California and Pacific Northwest production clusters where clean-label penetration is deepest.
- Confectionery:Fine particle size requirements for chocolate tempering compatibility limit supplier qualification pools.
- Beverages:Cold-water solubility constraints restrict granulated formats; liquid concentrates compete with maltodextrin carriers in sports drink formulations.
Baking absorbs dominant volume share; snack foods are climbing the fastest.
Distribution Channel:
Channel selection determines margin structure and documentation requirements for organic equivalency.
- Supermarkets:Mass retail placement requires EFSA Novel Food dossier completion for European chains. German and UK buyers prioritize suppliers with pre-submitted safety assessments to compress onboarding timelines.
- Specialty Stores:Natural food independents in California and Oregon accept smaller batch sizes with batch-level glycemic index documentation, displacing distributor intermediaries in favor of direct supplier relationships.
- Online:E-commerce penetration concentrates in North American metro areas where subscription models reduce customer acquisition costs for heritage brands.
- Wholesalers:Food service distributors serve restaurant and bakery manufacturing accounts with volume-tiered pricing.
Supermarkets dominate procurement volume; specialty stores gain share fastest.
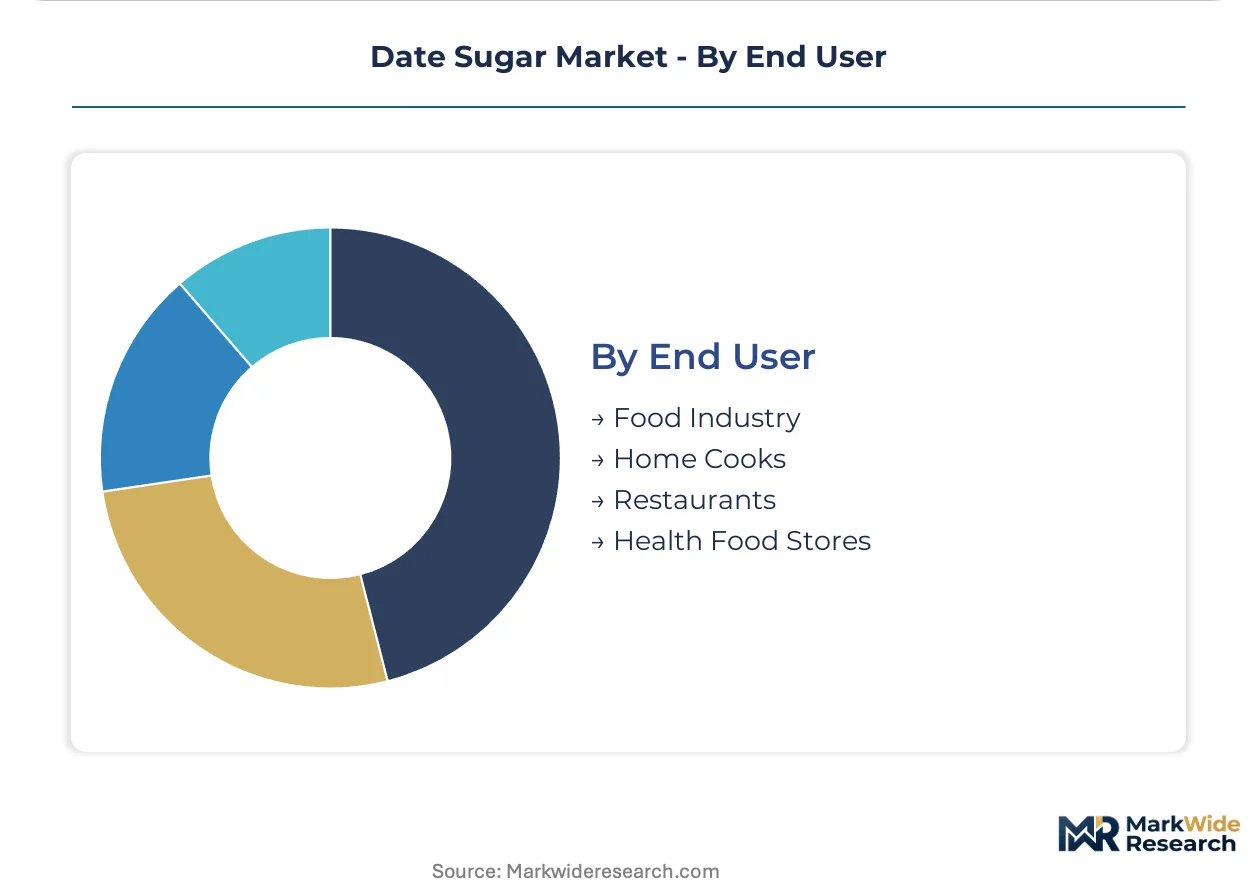
End User:
User sophistication determines specification stringency and certification requirements.
- Food Industry:Commercial processors demand temperature-controlled milling documentation and fiber retention certificates for clean-label claims. REACH compliance and FDA disclosure rules compress supplier qualification cycles for multinational accounts.
- Health Food Stores:Retail buyers in Germany and France stock organic granulated formats exclusively, rejecting conventional alternatives as EU additive restrictions tighten.
- Home Cooks:Recipe bloggers and direct-to-consumer channels in the United States drive powdered format demand for smoothie and home baking applications.
- Restaurants:Fine dining establishments in Paris and London specify single-origin date provenance for menu storytelling and premium positioning.
Food industry commands procurement scale; health food stores show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food chemists and clean-label formulation specialists cluster in Germany, California, and Paris, anchoring global date sugar innovation pipelines. These talent concentrations align with tightening EU additive restrictions and FDA disclosure mandates that favor minimally processed sweeteners. Regional procurement patterns diverge sharply between established organic certification infrastructure and emerging equivalency negotiations.
United States
Protein bar manufacturers in California and the Pacific Northwest are accelerating date sugar procurement for clean-label reformulations. FDA labeling requirements compress supplier qualification timelines for multinational food processors. Los Angeles and San Francisco retail clusters drive specialty store penetration where direct supplier relationships displace distributor intermediaries.
Germany
Industrial bakeries specify granulated formats for bread formulations where EU Green Deal mandates accelerate refined sugar substitution. ECHA's REACH compliance expansion disqualifies synthetic sweeteners from retail channels. Berlin and Munich buyers prioritize suppliers with pre-submitted EFSA Novel Food dossiers to compress onboarding timelines.
France
Fine dining establishments in Paris specify single-origin date provenance for menu storytelling and premium positioning. EU organic certification commands shelf-space priority as additive restrictions tighten across French retail. Lyon and Marseille production clusters concentrate artisan confectionery demand where fine particle size requirements limit supplier qualification pools.
United Kingdom
Health food retail buyers in London stock organic granulated formats exclusively, rejecting conventional alternatives under evolving EU-UK organic equivalency frameworks. Clarks U.K. leverages heritage brand strength in specialty sweetener aisles. Manchester and Birmingham distribution hubs serve food service accounts with volume-tiered procurement structures.
India
FSSAI standards evolution creates first-mover advantage for suppliers establishing organic equivalency agreements with Indian authorities. Domestic food processors in Maharashtra and Gujarat pilot date sugar formulations for clean-label snack applications. Mumbai and Delhi-NCR retail channels absorb emerging demand as health-conscious consumers scrutinize ingredient lists.
Date Sugar Market Vendor Landscape
The competitive structure tilts toward heritage natural food brands with pre-certified organic infrastructure. Mid-scale specialists and commodity-grade processors occupy secondary tiers, differentiated by milling technology access and supply chain transparency. Three archetypes dominate: certification-anchored heritage brands, single-origin supply chain specialists, and private-label contract manufacturers. Consolidation pressure concentrates around organic equivalency capabilities and temperature-controlled processing assets.
Within the heritage brand tier, Now Foods and Bob's Red Mill Natural Foods exemplify certification-anchored positioning through established North American distribution depth. Date Lady occupies a specialist position emphasizing supply chain transparency narratives. Teeccino and Chatfield's Brands represent the mid-scale organic segment where batch-level documentation capabilities determine retail placement viability. Naturalia Ingredients SRL anchors European sourcing relationships for Mediterranean date provenance.
| Leading Market Players |
|---|
| Now Foods |
| Teeccino |
| Bob's Red Mill Natural Foods |
| Chatfield's Brands |
| Clarks U.K. |
| Date Lady |
| Barry Farms |
| Glory Bee |
| Naturalia Ingredients SRL |
| Others |
Supply Flow & Price Mechanics
Irrigation water scarcity in Middle East and North Africa date orchards propagates downstream through three distinct pricing tiers, with organic-certified granulated formats commanding shelf-space premiums in German and French retail while conventional commodity grades face margin compression from harvest yield volatility.
Pricing Analysis
Bundled certification-and-documentation services separate premium-tier suppliers from unbundled commodity sellers. Three-tier pricing structure across premium, standard, and economy levels reflects USDA NOP certification status, batch-level glycemic index documentation, and temperature-controlled milling verification. Cost compression in the economy tier is intensifying because uncertified processors cannot absorb REACH compliance documentation burdens. Protein bar manufacturers in California demonstrate the least price sensitivity, while conventional bakery accounts in price-competitive markets show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Tunisia, Algeria, and Saudi Arabia as dominant date fruit origins. Temperature-controlled pulverization equipment draws from specialized European and North American machinery suppliers, while organic certification audits rest on USDA-accredited and EU-recognized bodies. Tariff exposure runs through evolving organic equivalency negotiations between USDA NOP and foreign certifiers. Distribution runs through food service wholesalers serving industrial bakery accounts, with direct supplier relationships displacing intermediaries in specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier organic certification uptake, as REACH compliance and FDA disclosure rules force rapid substitution of uncertified alternatives and concentrate procurement with pre-validated suppliers.
For Market Incumbents: To counter emerging single-origin supply chain specialists, heritage brands should deepen backward integration into controlled-temperature milling assets and secure bilateral organic equivalency agreements with Indian FSSAI authorities to compress 12-18 month export timelines. Channel control through direct relationships with California and Pacific Northwest specialty retailers displaces distributor intermediaries where clean-label penetration is deepest. For New Entrants and Emerging Players: Enter via underpenetrated Indian food processing clusters in Maharashtra and Gujarat, where FSSAI standards evolution creates first-mover advantage for suppliers establishing organic equivalency. Target protein bar reformulation demand in California production clusters. Position through batch-level glycemic index documentation capabilities that industrial accounts increasingly mandate. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification infrastructure and temperature-controlled processing assets concentrate in mid-scale specialists. Long-term viability favors acquisition targets with pre-submitted EFSA Novel Food dossiers and established Mediterranean date provenance relationships. Watch for clarity in EU-UK organic equivalency frameworks as inflection signal for British retail channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature-Controlled Milling | Preserves enzymatic activity certifications that REACH-compliant European buyers require for clean-label claims. |
| Organic Equivalency Agreement Negotiation | Accelerates market access in India and EU channels where FSSAI and ECHA documentation burdens delay competitors. |
| Direct-to-Specialty-Retailer Channel Expansion | Displaces distributor intermediaries in California and Pacific Northwest clusters with deepest clean-label penetration. |
| Single-Origin Provenance Certification | Commands price premiums in Paris fine dining and artisan chocolate segments where menu storytelling drives procurement. |
| Spray-Drying Technology Investment | Enables cold-soluble formats that penetrate sports drink formulations previously dominated by maltodextrin carriers. |
Methodological Framework
Bottom-up bakery and protein bar formulation modeling reconciled against top-down date fruit harvest and processing capacity tracking forms the analytical core. Primary interviews with commercial bakery procurement directors, protein bar R&D formulators, organic certification auditors, and specialty retail category buyers combined with secondary validation from FDA GRAS filings, EFSA Novel Food consultation registers, FSSAI standard notifications, and USDA NOP equivalency agreement databases. Trade flow analysis from customs records and organic certification body disclosure reports enabled cross-verification of supply-side concentration assumptions.
Input-output matrices mapped date fruit harvest volumes through processing stage yields to end-use consumption across granulated, powdered, liquid, and organic format segments. Modeled dimensions span product type, application channel, certification status, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated irrigation water availability projections for Middle East and North Africa growing regions and evolving EU Green Deal additive restriction timelines.
Inputs from EFSA consultation registers and FSSAI draft standards were available through the study window; gaps in real-time harvest yield data from Algerian and Tunisian growing regions introduce uncertainty bands around near-term supply assumptions. Forecasts reflect documented assumptions regarding organic equivalency negotiation progress and REACH compliance enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Palm Sugar Market
Sweeteners
Methyl Glucose Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Beetroot Molasses Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Allulose Powder Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Rare Sugar Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Oligofructose Market
Sweeteners
White Sugar Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Brown Rice Syrup Market