
 Isomaltooligosaccharide Market | 2026-2036
Isomaltooligosaccharide Market Size, Share, and Industry Trends Forecast 2026-2036
Isomaltooligosaccharide Market Foresight
Asset-light toll manufacturing and third-party fermentation leasing is reshaping competitive entry in isomaltooligosaccharide production, lowering capital barriers for regional challengers. Baolingbao Biology Co., Ltd. leverages captive starch supply from its Shandong base to control input costs across the value chain. Nikon Shikuhin Kako Co., Ltd. anchors premium positioning in Japanese functional foods through decades of FOSHU compliance expertise. Beneo differentiates its IMO portfolio with integrated preclinical research services that support customer health-claim submissions in regulated markets.
Isomaltooligosaccharide refers to a mixture of alpha-D-glucose oligomers linked primarily by alpha-1,6 glucosidic bonds, typically manufactured via enzymatic transglucosylation of maltose using alpha-glucosidase or transglucosidase enzymes at controlled pH and temperature conditions. The resulting syrup or powder functions as a low-calorie, non-cariogenic bulking agent and selective bifidogenic substrate in formulated foods and dietary supplements. Powder grades command margin premiums in pharmaceutical and nutraceutical applications where precise dosing and extended shelf stability matter more than cost. Liquid and syrup forms dominate food and beverage volumes, though granular formats are gaining traction in tabletop sweetener blends where flowability and dissolution rate determine formulation acceptance.
FDA GRAS notifications and EFSA novel food opinions shape market access timelines for new isomaltooligosaccharide suppliers seeking entry into North American and European formulated food channels. China's SAMR food additive registration and Japan's Consumer Affairs Agency FOSHU approvals create additional compliance layers that favor established players with documented clinical dossiers. Stakeholders must monitor evolving prebiotic definition standards from ISO and national regulators, as harmonized analytical methods for IMO content verification will determine which product specifications qualify for premium positioning in health-positioned formulations.
Market Dynamics
Enzymatic transglucosidase efficiency improvements and tightening purity benchmarks under Japan's FOSHU system and China's GB standards are compressing supplier qualification timelines while raising capital requirements for new fermentation capacity.
Growth Catalysts
- Prebiotic beverage formulation:Functional drink manufacturers in China and South Korea are expanding IMO procurement as low-glycemic bulking agents replace maltodextrin in sports and digestive health SKUs.
- FOSHU compliance infrastructure:Japan's positive-list system for Foods for Specified Health Uses creates sustained demand for clinical-grade IMO with documented bifidogenic dossiers.
- Enzyme immobilization:Fixed-bed transglucosidase reactors are reducing enzyme consumption per ton of output, improving process economics for mid-scale fermentation operators.
Market Restraints
- Corn starch input volatility:Feedstock costs fluctuate with Shandong province crop yields and import parity pricing, squeezing margin predictability for non-integrated processors.
- Supply concentration risk:Over half of global IMO fermentation capacity sits within 200 kilometers of Yucheng and禹城 in Shandong, creating geographic single-point vulnerability.
- Allulose substitution pressure:Rare sugar alternatives with superior sweetness intensity are capturing tabletop sweetener and beverage reformulation budgets in North American retail channels.
Strategic Opportunities
- Pharmaceutical excipient qualification:USP-grade IMO powder for pediatric and geriatric dosage forms remains under-supplied relative to nutraceutical demand, opening margin-rich positioning.
- EU novel food authorization:EFSA positive opinions on enzymatic IMO would unlock formulated food access across 27 member states for suppliers with ISO 17025 analytical capabilities.
- Direct-to-manufacturer e-procurement:B2B platforms connecting Shandong fermentation facilities with Southeast Asian contract manufacturers are disintermediating traditional ingredient distributors.
Industry Challenges
- Alpha-glucosidase strain optimization:Talent scarcity in industrial microbiology and enzyme engineering is extending R&D cycles for improved transglucosylation yield.
- SAMR registration timelines:China's food additive renewal and new-source approval processes create 18-24 month market access delays for imported IMO specifications.
- Analytical standardization gaps:Divergent HPLC methods for degree-of-polymerization distribution across ISO, AOAC, and Chinese GB protocols complicate cross-border quality arbitration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isomaltooligosaccharide Market |
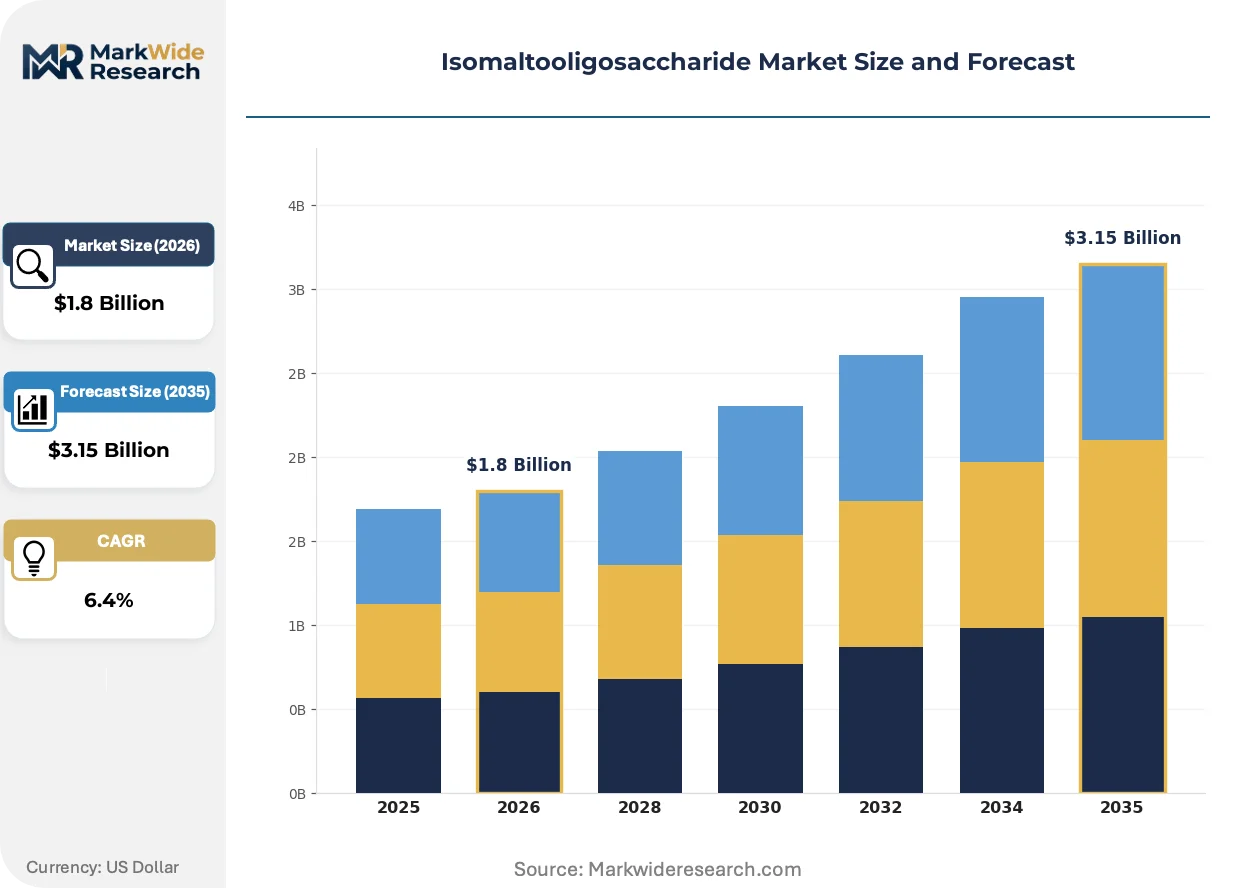
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Syrup Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Personal Care End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Baolingbao Biology Co., Ltd., Nikon Shikuhin Kako Co., Ltd., BioNeutra North America, Shandong Bailong Chuangyuan Bio-Tech Co., Ltd., Luzhou Bio-chem Technology Co., Ltd., Shandong Tianmei Bio-Tech Co., Ltd., Shandong Tianjiao Bio-engineering Co., Ltd., Dancheng Caixin Sugar Industry Co., Ltd., Beneo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isomaltooligosaccharide Market Shifts & Advancements
Continuous processing technologies and regulatory harmonization efforts are compressing batch cycle times while expanding addressable end-use categories beyond traditional food and beverage applications.
Immobilized enzyme membrane reactors are virtualizing traditional stirred-tank fermentation by enabling semi-continuous maltose conversion with reduced downtime for cleaning-in-place cycles. Japanese and South Korean toll manufacturers are adopting these systems fastest, typically achieving 30-40% higher volumetric productivity. This architecture is virtualizing the economics of smaller-scale production, enabling regional challengers to serve pharmaceutical and specialty nutrition accounts without billion-liter capital commitments.
EFSA's evolving novel food guidance on enzymatically produced oligosaccharides is forcing dossier restructuring for suppliers seeking European market access. The regulator's tightened toxicological data requirements and specification transparency mandates are extending pre-submission preparation by 12-18 months. Powder-grade IMO destined for infant formula and medical nutrition applications faces the highest scrutiny, with several Asian suppliers pivoting toward US GRAS notification pathways as an interim commercialization route.
Formulators are consolidating supplier relationships around vertically integrated starch-IMO processors with captive enzyme production and in-house analytical laboratories. This concentration is displacing multi-source procurement strategies previously common among multinational CPG companies. The shift is most pronounced in Japan and China, where FOSHU and blue-hat health food registration requirements favor long-term partnerships with documented supply chain traceability.
Isomaltooligosaccharide Market Segmentation
Isomaltooligosaccharide specifications diverge sharply across end-use requirements, with pharmaceutical-grade powder commanding fundamentally different purity thresholds than beverage-grade syrup. Segmentation discipline separates volume-driven commodity positions from margin-protected specialty applications.
Product Type:
Use-case spectrum spans precise dosing in pediatric formulations to bulk sweetening in functional beverages, with physical form determining both manufacturing economics and regulatory qualification pathways.
- Liquid:Standard IMO syrup at 50-75% dry solids serves as the workhorse input for beverage reformulation, with South Korean functional drink manufacturers absorbing significant volumes for low-glycemic sports nutrition SKUs. Enzymatic transglucosidase conversion yields this grade most efficiently, though cold-chain logistics constrain geographic reach.
- Powder:Spray-dried crystalline grades achieve >95% purity with defined degree-of-polymerization distribution, qualifying for USP excipient standards in Japanese pharmaceutical and medical nutrition applications where FOSHU dossiers require documented bifidogenic activity. Shandong processors with captive starch supply dominate this specification tier.
- Granular:Agglomerated formats optimize flowability for tabletop sweetener blends and dry-mix beverage powders, gaining traction in Southeast Asian retail channels.
- Syrup:High-viscosity concentrates target industrial bakery and confectionery applications requiring humectant functionality alongside prebiotic positioning.
The dominant share belongs to Liquid, while Powder is closing the gap fastest.
Application:
Margin architecture separates regulated health claims from commodity positioning, with compliance infrastructure acting as the primary segmentation variable.
- Food & Beverage:Functional drink and digestive health SKU proliferation in China and South Korea absorbs the majority of commodity-grade IMO output, with maltodextrin replacement driving procurement decisions at mid-tier CPG formulators.
- Pharmaceuticals:USP-grade specifications for pediatric and geriatric dosage forms remain supply-constrained relative to nutraceutical demand, creating margin-rich positioning for processors with ISO 17025 analytical capabilities and documented clinical dossiers.
- Nutraceuticals:Dietary supplement capsules and powders leverage IMO's selective bifidogenic substrate properties, with Japanese FOSHU compliance requirements filtering supplier qualification.
- Personal Care:Emerging applications in microbiome-targeted topical formulations represent experimental demand volumes with unproven scale economics.
Food & Beverage holds volume leadership, though Pharmaceuticals exhibits the steepest expansion trajectory on margin pull.
End User:
Procurement authority concentrates at the manufacturing tier, with downstream tiers adding limited value beyond logistics and local regulatory navigation.
- Manufacturers:Contract formulators and brand-owning CPG companies drive specification setting, with Japanese and Chinese health food registrants consolidating supplier relationships around vertically integrated starch-IMO processors.
- Retailers:Private-label functional food programs at South Korean and Chinese supermarket chains generate spot demand for standard-grade IMO with flexible packaging requirements.
- Distributors:Traditional ingredient traders face disintermediation pressure from B2B e-procurement platforms connecting Shandong fermentation facilities directly to Southeast Asian contract manufacturers.
- Consumers:Direct purchases of tabletop sweetener products represent minimal volume with high packaging cost sensitivity.
Manufacturers control specification authority, while Distributors are losing share fastest to platform-mediated direct sourcing.
Distribution Channel:
Channel economics reflect customer scale and technical service intensity, with complex formulations requiring application support that pure digital interfaces cannot replicate.
- Online:B2B platforms enable spot procurement for standard specifications, though pharmaceutical and FOSHU-grade transactions still require documented audit trails and technical dossier exchange.
- Supermarkets:Retail channel relevance concentrates in finished consumer products rather than bulk ingredient sales, with limited IMO volume transiting this pathway.
- Specialty Stores:Nutraceutical ingredient distributors serving mid-scale supplement manufacturers provide formulation support and smaller lot sizes with higher per-kilometer logistics costs.
- Direct Sales:Long-term supply agreements between integrated starch processors and major Japanese functional food registrants lock in volume commitments with price stability mechanisms.
Direct Sales anchors relationship-based procurement, while Online is gaining transaction volume fastest among non-regulated applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in isomaltooligosaccharide track the geographic mismatch between corn starch supply and functional food demand. China maintains substantial export surplus positions, while Japan and South Korea remain net importers of clinical-grade specifications.
China
Shandong province fermentation clusters process domestic corn starch into IMO syrup and powder grades for export markets. SAMR food additive registration requirements under GB standards enforce purity benchmarks that filter smaller processors from regulated channels. Yucheng and禹城 industrial zones host multiple dedicated IMO facilities with captive enzyme production.
Japan
FOSHU compliance infrastructure sustains premium demand for clinical-grade IMO with documented bifidogenic dossiers. Consumer Affairs Agency positive-list approvals require multi-year clinical submissions that favor established supplier relationships. Kanto region functional food manufacturers consolidate procurement around vertically integrated starch-IMO processors with traceable supply chains.
South Korea
Functional beverage formulators expand IMO procurement as low-glycemic bulking agents replace maltodextrin in sports nutrition SKUs. MFDS health functional food standards create parallel compliance tracks for domestic and imported specifications. Seoul Capital Area contract manufacturers drive spot demand through B2B e-procurement platforms connecting directly to Shandong fermentation facilities.
United States
FDA GRAS notification pathways attract Asian suppliers seeking interim commercialization routes while EFSA dossiers mature. North American beverage reformulation budgets face substitution pressure from rare sugar alternatives in retail channels. California and Northeast corridor nutraceutical contract manufacturers absorb pharmaceutical-grade powder volumes for pediatric and geriatric dosage forms.
Germany
EFSA novel food authorization timelines extend pre-submission preparation for enzymatic IMO suppliers seeking European market access. REACH compliance and CSRD sustainability disclosure requirements add qualification layers for imported specifications. Bavaria and North Rhine-Westphalia ingredient distributors face disintermediation from platform-mediated direct sourcing connecting Asian processors to Southeast Asian contract manufacturers.
Isomaltooligosaccharide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical anchors. The supplier base concentrates around vertically integrated starch processors with captive fermentation capacity and in-house analytical laboratories. Three archetypes dominate: integrated corn starch-IMO processors controlling input costs, toll manufacturers leveraging asset-light fermentation leasing, and research-oriented suppliers bundling preclinical services with ingredient supply. Capacity expansion and regulatory dossier development constitute the primary competitive moves, with EFSA novel food submissions and USP-grade pharmaceutical qualifications absorbing significant capital.
Within the integrated processor tier, Baolingbao Biology Co., Ltd. and Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. exemplify the Shandong-based archetype of captive starch supply and controlled fermentation economics. Nikon Shikuhin Kako Co., Ltd. occupies a distinct position representing decades of FOSHU compliance expertise and premium market anchoring in Japanese functional foods. These three entities illustrate the geographic and regulatory stratification that separates commodity-grade syrup suppliers from clinical-grade powder specialists.
| Leading Market Players |
|---|
| Baolingbao Biology Co., Ltd. |
| Nikon Shikuhin Kako Co., Ltd. |
| BioNeutra North America |
| Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. |
| Luzhou Bio-chem Technology Co., Ltd. |
| Shandong Tianmei Bio-Tech Co., Ltd. |
| Shandong Tianjiao Bio-engineering Co., Ltd. |
| Dancheng Caixin Sugar Industry Co., Ltd. |
| Beneo |
| Others |
Supply & Pricing Matrix
Qingdao-to-Busan maritime freight corridors absorb cold-chain logistics premiums that compound Shandong supply concentration, forcing Japanese FOSHU-grade buyers to pay steep differentials over commodity syrup while South Korean beverage formulators exploit platform-direct sourcing to compress landed costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across pharmaceutical-grade powder, FOSHU-certified syrup, and commodity beverage specifications. Price differentiation hinges on purity benchmarks under Japan's Consumer Affairs Agency standards and volume scale commitments, with pharmaceutical excipient qualifications commanding substantial premiums. Pricing pressure stems from allulose substitution in North American retail channels, eroding tabletop sweetener margins. Contract manufacturers in South Korea exhibit highest price sensitivity due to spot procurement habits, while Japanese functional food registrants show lowest sensitivity given FOSHU dossier switching costs.
Supply Chain Analysis
Extended payment terms from integrated starch processors to enzyme suppliers are tightening working capital cycles across Shandong fermentation clusters. Geographic supply concentrates in China, Japan, and South Korea, with raw material dependencies on corn starch from Shandong province, alpha-glucosidase enzyme strains, and crystallization adjuncts for powder grades. Single-source vulnerability radiates from the Yucheng-禹城 corridor where over half of global capacity sits within 200 kilometers. Distribution runs through direct sales agreements for regulated grades and B2B e-procurement platforms for commodity specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isomaltooligosaccharide production is experiencing high-growth disruption as enzymatic immobilization technologies virtualize fermentation economics and EFSA novel food guidance restructures market access timelines for European entry.
For Market Incumbents: Entrench FOSHU compliance infrastructure against emerging toll manufacturers by deepening captive enzyme production and locking multi-year supply agreements with Japanese functional food registrants. Add ISO 17025 analytical capacity in Shandong to defend pharmaceutical-grade positioning against mid-scale challengers leveraging asset-light fermentation leasing.
For New Entrants and Emerging Players: Establish a beachhead in USP-grade pharmaceutical excipients where supply constraints relative to nutraceutical demand create margin-rich white space. Target Southeast Asian contract manufacturers through B2B e-procurement platforms, bypassing traditional ingredient distributors with spot pricing and flexible lot sizes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated starch-IMO processors with in-house transglucosidase production and documented clinical dossiers. Long-term viability hinges on regulatory moat depth rather than scale alone. Watch EFSA novel food opinion timelines as the critical inflection signal for European market access unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Immobilization Scale-Up | Fixed-bed reactor deployment cuts enzyme consumption per ton and enables semi-continuous output. |
| FOSHU Dossier Investment | Consumer Affairs Agency approvals require multi-year clinical submissions that lock in premium positioning. |
| Backward Integration into Starch | Captive corn starch supply from Shandong processors insulates margin against feedstock volatility. |
| USP-Grade Pharmaceutical Qualification | Powder specifications for pediatric dosage forms remain undersupplied relative to nutraceutical demand. |
| B2B E-Procurement Platform Partnership | Direct connections between fermentation facilities and Southeast Asian manufacturers disintermediate distributors. |
Research Methodology
A spread of perspectives from fermentation plant managers, FOSHU registration consultants, functional beverage formulators, and pharmaceutical excipient procurement leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notifications, EFSA novel food opinions, SAMR food additive filings, and customs trade data from Shandong export corridors. Bottom-up capacity assessments and top-down demand triangulation from beverage reformulation trends anchored the quantitative framework.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product form, application tier, and regulatory qualification pathway. The analytical framework incorporated enzymatic conversion yield improvements, FOSHU approval velocity, and substitution pressure from rare sugar alternatives. CAGRs were derived from volume trajectory analysis against pricing tier evolution, with specific inputs including transglucosidase efficiency curves and pharmaceutical-grade powder supply deficits.
Sensitivities concentrate around EFSA opinion timelines, allulose penetration rates in North American retail, and Shandong corn starch harvest variability. Forecasts reflect documented assumptions on regulatory harmonization progress and enzyme technology maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Spain Food Sweetener Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
United States Xylitol Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
India Cane Sugar Market
Sweeteners
Maltodextrin Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Sour Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Smoked Sugar Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
North America Food Sweetener Market