
 Short-Chain Fructooligosaccharides (Scfos) Market | 2026-2036
Short-Chain Fructooligosaccharides (Scfos) Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Chain Fructooligosaccharides (Scfos) Market Analysis
European scFOS enzyme suppliers is realigning capacity toward pharmaceutical-grade output as dietary supplement purity thresholds tighten across the EU. BENEO GmbH leverages its Belgian fermentation infrastructure to dominate long-chain separation capabilities while sustaining scFOS purity benchmarks. Cargill Incorporated anchors North American supply through its corn-derived fructose stream, competing on feedstock cost against Asian sucrose-based rivals. Meiji Co., Ltd. occupies Japan's specialized dairy-prebiotic niche, where scFOS integration into yogurt cultures commands formulation premiums.
Short-chain fructooligosaccharides comprise 2-4 fructose units linked by beta-(2,1) glycosidic bonds, typically manufactured via enzymatic transfructosylation from sucrose using fungal fructosyltransferases at 50-60°C; these oligomers resist human digestive enzymes while selectively nourishing Bifidobacterium and Lactobacillus colonies in the distal colon. Powder formulations lead volume due to stability in dry-blended supplements and infant nutrition, though liquid syrups represent the fastest-growing format as beverage manufacturers seek clean-label sugar reduction without artificial sweeteners. Dietary Supplements captures the deepest margin pool through cGMP-certified production, while Food & Beverages applications expand through bakery and dairy fortification where scFOS provides dual functionality as fiber claim and humectant.
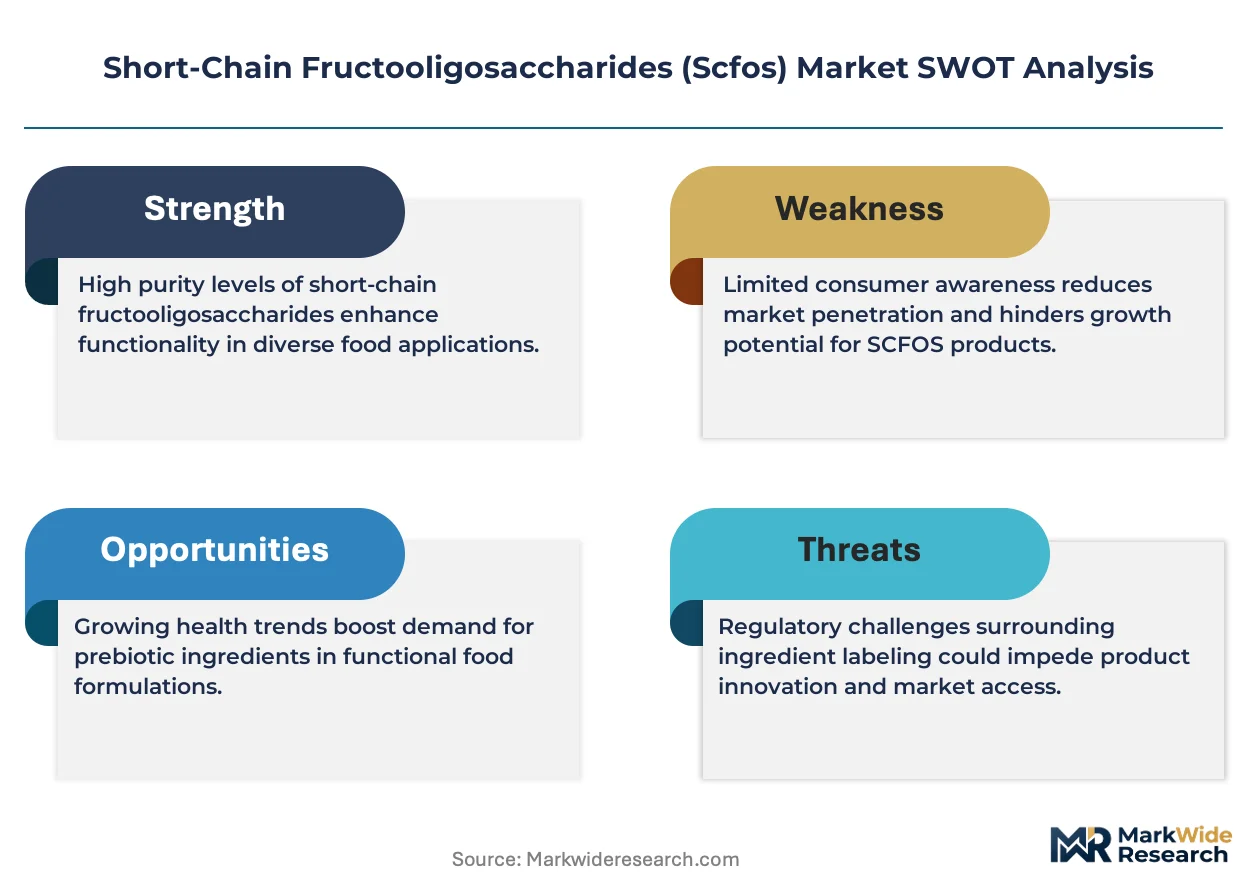
FDA GRAS notifications and EFSA health claim authorizations shape commercial viability, with the former enabling U.S. infant formula inclusion and the latter restricting prebiotic marketing to specific strain-substrate combinations. China's SAMR implements GB standards for oligosaccharide content claims, creating compliance divergence that fragments export packaging requirements. Japan's FOSHU system maintains distinct efficacy thresholds, forcing reformulators to maintain multiple specification sheets. Stakeholders must monitor regulatory harmonization between pharmacopoeial-grade and food-grade scFOS specifications as clinical trial evidence accumulates for microbiome-targeted therapeutics.
Market Dynamics
Enzymatic manufacturing cost curves are flattening as Chinese domestic producers scale fungal fructosyltransferase capacity, compressing import premiums that historically protected European and Japanese supply positions.
Growth Catalysts
- EFSA dietary fiber labeling guidance:European reformulation mandates redirect investment toward shorter-chain oligomer profiles, expanding addressable product categories for scFOS suppliers.
- Infant formula fortification:Asia-Pacific prebiotic procurement accelerates as food safety frameworks tighten minimum oligosaccharide thresholds in early-life nutrition.
- Enzymatic transfructosylation advances:Temperature-tolerant fungal enzyme variants reduce energy input requirements, improving process economics at commercial scale.
Market Restraints
- Sucrose feedstock volatility:Raw material costs fluctuate with Brazilian and Indian sugar harvest cycles, squeezing margin predictability for non-integrated producers.
- Long-chain FOS substitution:BENEO's Belgian separation infrastructure enables competitive inulin-derived alternatives in bakery and dairy applications.
- SAMR-EFSA regulatory divergence:China's GB standards for oligosaccharide claims force dual specification maintenance, fragmenting packaging and compliance overhead.
Strategic Opportunities
- Pharmaceutical-grade pivot:EU dietary supplement purity thresholds create margin expansion potential for enzyme suppliers realigning toward cGMP-certified output.
- Beverage clean-label substitution:Liquid syrup formats capture sugar-reduction demand as CPG brands seek fiber-functional sweeteners without artificial additives.
- Microbiome therapeutic convergence:Clinical trial accumulation for Bifidobacterium-targeted interventions positions scFOS as a pharmacopoeial-grade precursor.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and downstream processing expertise concentrates in Belgian and Japanese enzyme houses, constraining new entrant hiring pipelines.
- Multi-jurisdiction FOSHU compliance:Japan's efficacy thresholds require distinct formulation sheets, complicating unified product architecture for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Chain Fructooligosaccharides (Scfos) Market |
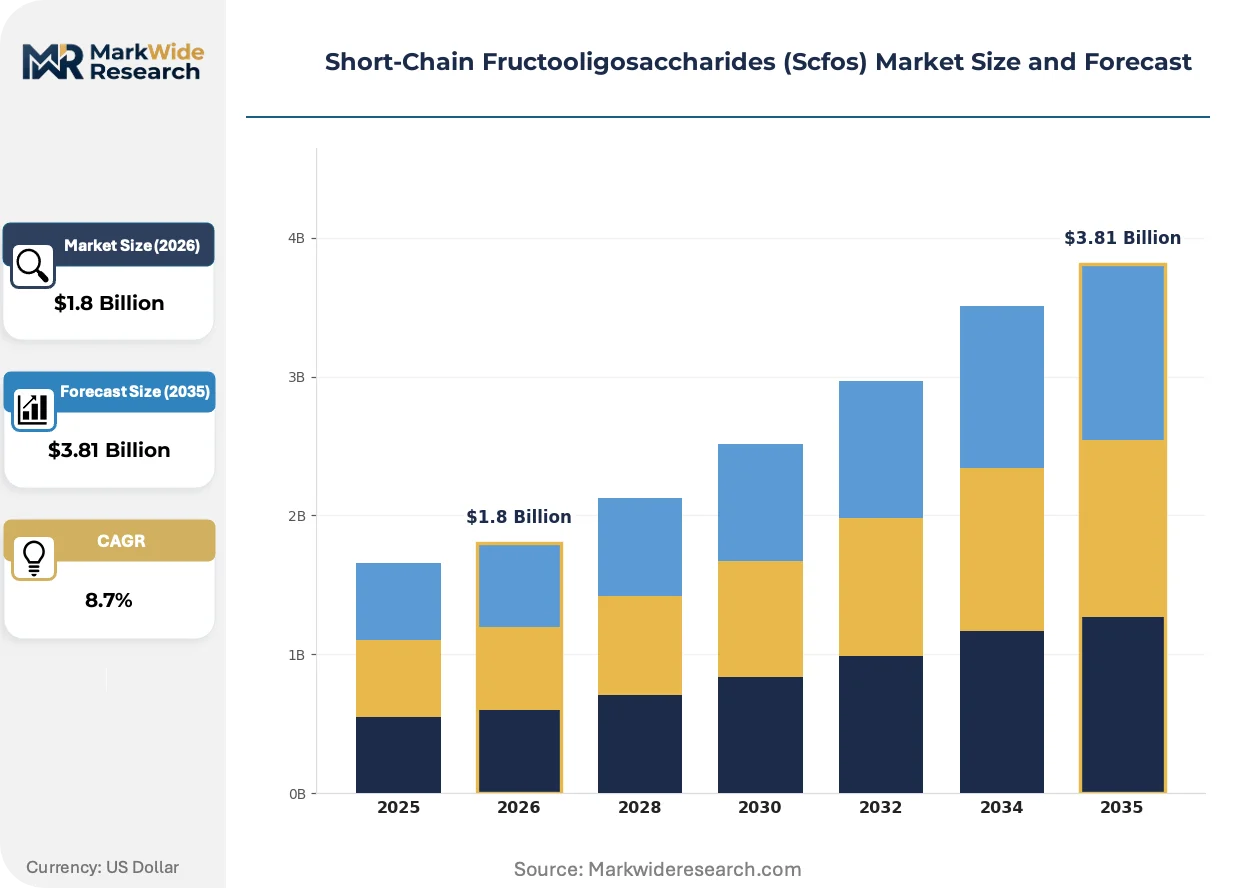
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Syrup Application: Dietary Supplements, Food & Beverages, Pharmaceuticals, Animal Feed End User: Households, Food Manufacturers, Healthcare Providers, Animal Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | BENEO GmbH, Cargill Incorporated, Ingredion, Cosucra Groupe Warcoing, Baolingbao Biology, Galam Ltd, Tereos, Meiji Co., Ltd., Sensus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Chain Fructooligosaccharides (Scfos) Market Emerging Trajectories
Bioprocess intensification and regulatory harmonization pressures are compressing traditional manufacturing advantages while opening formulation frontiers in precision nutrition and therapeutic applications.
Continuous enzymatic bioreactor technology is integrating into commercial scFOS production, replacing batch fermentation with steady-state systems that improve substrate conversion efficiency. European and North American ingredient houses pilot these configurations to reduce capital intensity per ton. The technology is integrating process analytical control loops that enable real-time chain-length distribution adjustment, compressing quality variation penalties in pharmaceutical-grade contracts.
EFSA health claim authorization restrictions on prebiotic marketing are reshaping commercial positioning across the European Union. Manufacturers now anchor fiber claims on analytical fiber content rather than strain-specific efficacy, redirecting R&D toward analytical certification. Infant formula and dietary supplement segments absorb the greatest compliance burden, with reformulators maintaining parallel dossiers for EU and non-EU markets.
Clean-label procurement patterns now prioritize supply chain transparency over historical supplier relationships. Beverage and bakery manufacturers audit enzyme sources and fermentation substrates, displacing opaque intermediaries with direct producer contracts. This behavioral shift concentrates procurement authority in China's functional food corridor and Germany's ingredient distribution hubs, where documentation standards are most mature.
Short-Chain Fructooligosaccharides (Scfos) Market Segmentation
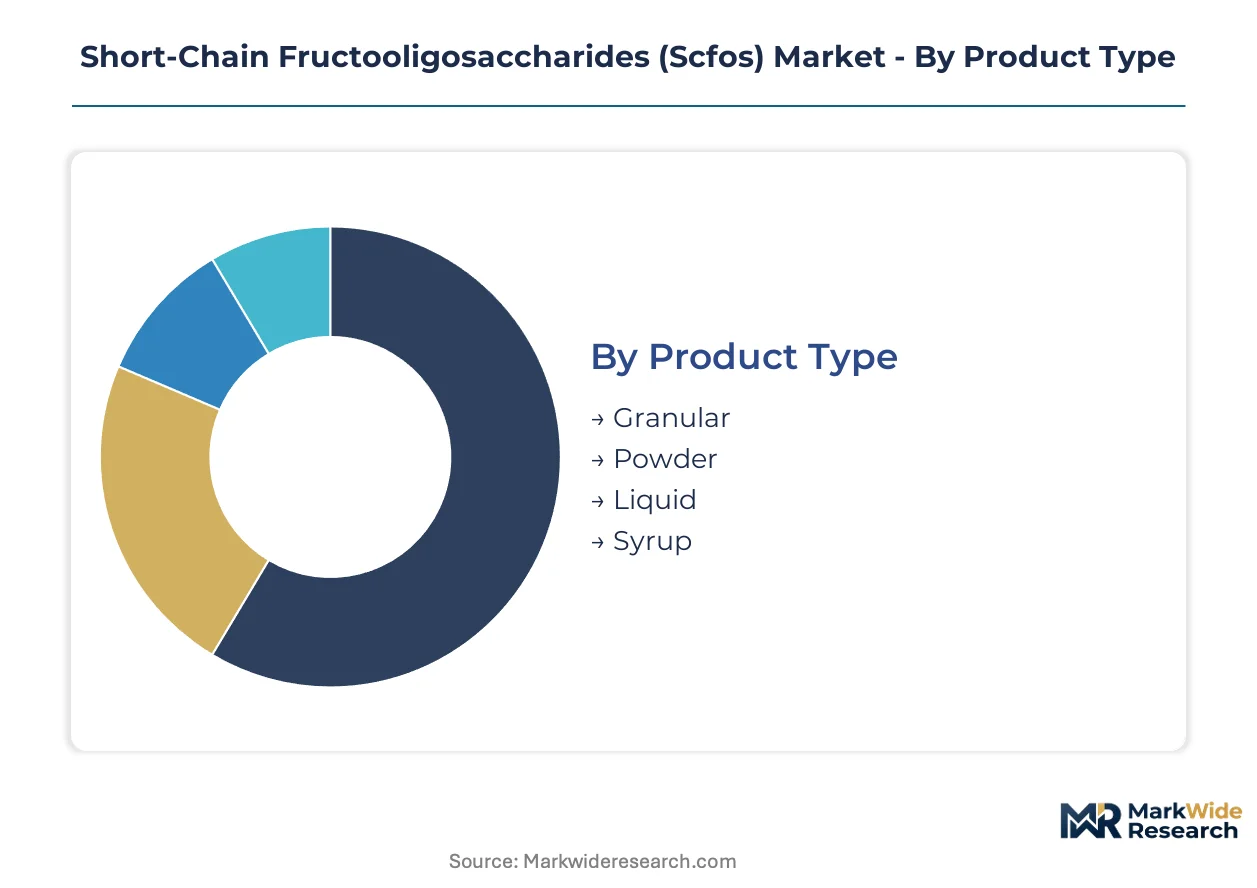
ScFOS buyers span infant formula compounders seeking pharmaceutical-grade certification, beverage manufacturers demanding clean-label sugar reduction, and dairy processors optimizing yogurt fermentation kinetics. Segmentation reveals how formulation requirements, regulatory exposure, and supply chain integration reshape procurement priorities across end-use categories.
Product Type:
Buyers differentiate by moisture sensitivity, dissolution kinetics, and downstream processing compatibility when selecting physical formats.
- Granular:Free-flowing crystalline particles with low hygroscopicity suit automated dry-blending lines in high-volume infant nutrition facilities. North American compounders favor this format for cGMP-certified production environments where dust containment is critical.
- Powder:Fine particle distribution maximizes surface area for rapid hydration in instant beverage applications. China's functional food corridor drives procurement volume as domestic enzyme technology advances reduce import premiums for feedstock-derived material.
- Liquid:Pre-hydrated solutions eliminate dissolution steps in continuous beverage manufacturing. European reformulation mandates under EFSA dietary fiber guidance redirect investment toward pumpable formats for bakery and dairy integration.
- Syrup:Viscous aqueous concentrates with defined solids content enable precise dosing in sugar-reduction formulations. Beverage manufacturers in Japan's FOSHU system specify this format for validated prebiotic efficacy thresholds.
Powder leads volumes today; liquid is gaining share fastest.
Application:
Margin structure and regulatory burden diverge sharply between pharmaceutical-grade certification and food-grade fiber claims.
- Dietary Supplements:cGMP-certified production with pharmacopoeial-grade specifications captures premium pricing through third-party analytical certification. EU dietary supplement purity thresholds tighten, forcing enzyme suppliers to realign capacity toward contaminant-controlled output.
- Food & Beverages:Dual functionality as fiber claim and humectant drives bakery and dairy fortification. EFSA health claim restrictions redirect commercial positioning toward analytical fiber content rather than strain-specific prebiotic marketing.
- Pharmaceuticals:Excipient-grade material for microbiome-targeted therapeutic development requires batch-level chain-length distribution documentation. Clinical trial accumulation for Bifidobacterium interventions positions scFOS as a pharmacopoeial-grade precursor.
- Animal Feed:Cost-optimized specifications for gut health modulation in poultry and swine production prioritize substrate conversion efficiency over oligomer purity. Procurement concentrates among integrated livestock operations with captive enzyme supply.
Food & Beverages dominates current revenue; pharmaceuticals is expanding most quickly.
End User:
Technical sophistication and specification control vary from household label-reading to industrial formulation science.
- Households:Direct consumption through retail-packaged prebiotic supplements and functional foods. Japanese consumers demonstrate highest willingness-to-pay for FOSHU-validated products with specific strain-substrate documentation.
- Food Manufacturers:Industrial procurement with customized chain-length profiles for process integration. Clean-label audits now prioritize supply chain transparency, displacing opaque intermediaries with direct producer contracts.
- Healthcare Providers:Clinical nutrition and therapeutic microbiome interventions requiring pharmacopoeial-grade material. EU hospitals increasingly specify enzyme source and fermentation substrate documentation for enteral nutrition applications.
- Animal Nutrition:Feed compounders optimizing cost-per-unit of gut health benefit in intensive livestock systems. Brazilian and Indian sugar harvest cycles squeeze margin predictability for non-integrated producers serving this price-sensitive segment.
Food Manufacturers absorb the greatest volume; healthcare providers command the steepest expansion trajectory.
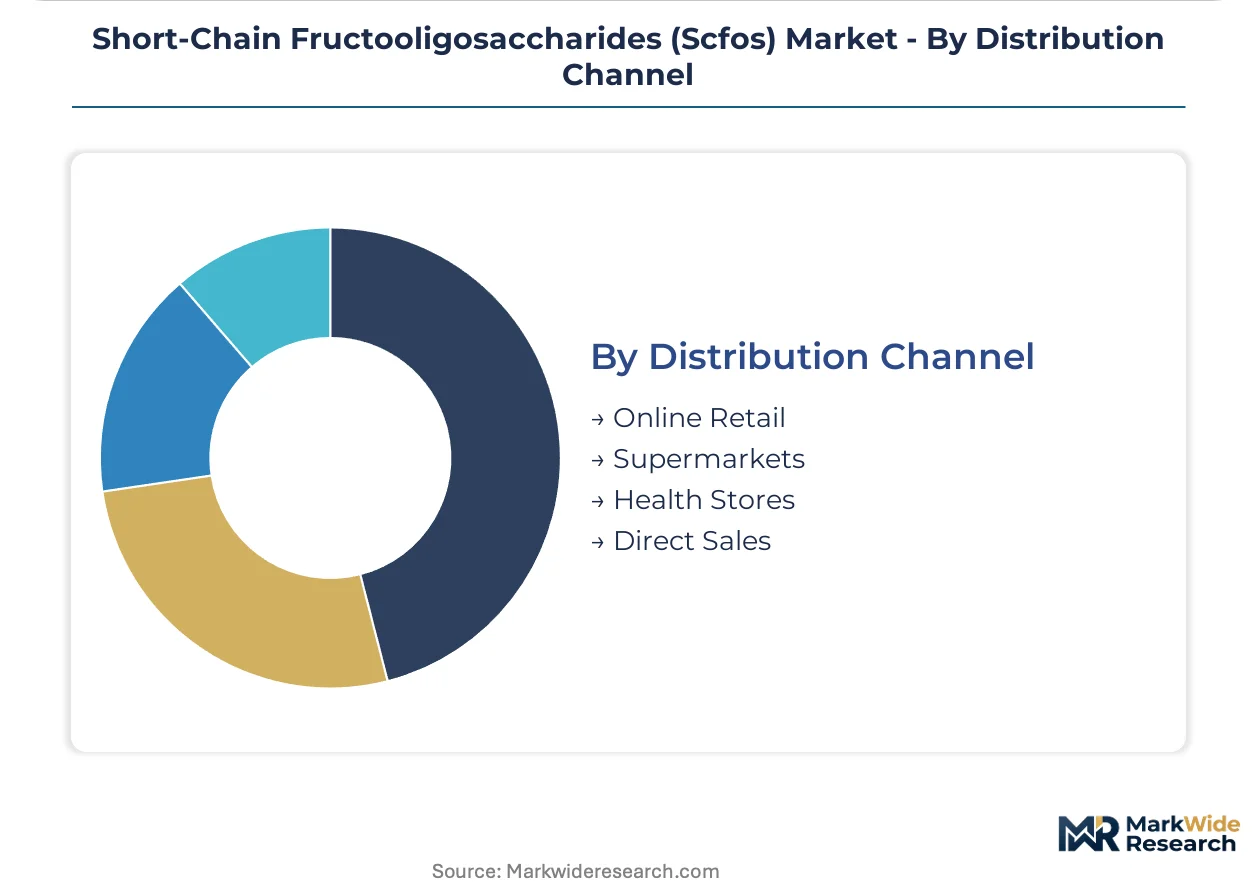
Distribution Channel:
Documentation standards and procurement authority concentrate in channels with mature traceability infrastructure.
- Online Retail:Direct-to-consumer platforms with subscription models for repeat supplement purchases. China's SAMR GB standards for oligosaccharide content claims create compliance divergence that fragments export packaging requirements for cross-border e-commerce.
- Supermarkets:Mass-market retail with private-label functional food and beverage placement. European reformulation mandates redirect shelf-space allocation toward shorter-chain oligomer profiles meeting EFSA dietary fiber labeling guidance.
- Health Stores:Specialty retail with trained staff capable of explaining prebiotic mechanisms to educated consumers. Japan's distinct efficacy thresholds force reformulators to maintain multiple specification sheets for this channel.
- Direct Sales:Producer-to-manufacturer contracts with integrated technical service and formulation support. Belgium and Germany anchor this channel through mature ingredient distribution hubs with advanced documentation standards.
Supermarkets move the highest tonnage; direct sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting scFOS production toward jurisdictions with lower cost-of-compliance structures, particularly as EFSA and FDA purity thresholds diverge from China's GB standards. Enzyme suppliers are relocating fermentation capacity to exploit these gaps while maintaining pharmaceutical-grade certification pathways for premium markets.
China
Domestic enzyme technology advances are reducing import dependence for scFOS feedstocks, with Yangtze River Delta biotech clusters scaling fungal fructosyltransferase production. SAMR's GB standards for oligosaccharide content claims create compliance divergence that fragments export packaging requirements. Zhejiang and Jiangsu provinces anchor functional food manufacturing corridors where direct producer contracts displace opaque intermediaries.
Belgium
Long-chain separation capabilities concentrate in Belgian fermentation infrastructure, with producers leveraging EFSA dietary fiber labeling guidance to capture reformulation demand. The country's national pharmaceutical regulator maintains distinct efficacy thresholds for microbiome-targeted therapeutics. Flanders anchors European scFOS enzyme supply, with Antwerp-Ghent industrial zones dominating downstream processing expertise.
United States
FDA GRAS notifications enable infant formula inclusion, driving procurement from corn-derived fructose streams competing on feedstock cost. The pricing structure reflects three-tier differentiation across premium pharmaceutical-grade, standard food-grade, and economy feed-grade specifications. Midwest agricultural processing clusters in Iowa and Illinois anchor North American supply integration.
Japan
Meiji Co., Ltd. occupies the specialized dairy-prebiotic niche, where scFOS integration into yogurt cultures commands formulation premiums. METI's FOSHU system maintains distinct efficacy thresholds, forcing reformulators to maintain multiple specification sheets. Kanto and Kansai industrial corridors concentrate pharmaceutical-grade production for clinical nutrition applications.
Germany
EFSA health claim restrictions redirect commercial positioning toward analytical fiber content rather than strain-specific prebiotic marketing. The country's national pharmaceutical regulator tightens dietary supplement purity thresholds, forcing enzyme suppliers to realign capacity. North Rhine-Westphalia and Bavaria anchor ingredient distribution hubs with mature documentation standards for clean-label procurement audits.
Short-Chain Fructooligosaccharides (Scfos) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and beverage-format specialization. The vendor base stratifies across integrated fermentation houses with captive enzyme supply, ingredient distributors with formulation technical service, and regional specialists in dairy-prebiotic niches. Strategic archetypes include: purity-focused pharmaceutical-grade suppliers, cost-optimized feed-grade producers, and application-specific format innovators. Dominant competitive moves center on capacity expansion in temperature-tolerant enzyme variants and geographic licensing partnerships to bypass multi-jurisdiction compliance overhead.
Within the integrated fermentation tier, BENEO GmbH and Cargill Incorporated exemplify divergent feedstock strategies—Belgian sucrose-based separation capabilities versus North American corn-derived fructose streams. Meiji Co., Ltd. occupies a specialized position in Japan's FOSHU-validated dairy applications. These three entities represent distinct geographic and application anchors: European pharmaceutical-grade certification, North American agricultural supply integration, and Asian functional food formulation premiums.
| Leading Market Players |
|---|
| BENEO GmbH |
| Cargill Incorporated |
| Ingredion |
| Cosucra Groupe Warcoing |
| Baolingbao Biology |
| Galam Ltd |
| Tereos |
| Meiji Co., Ltd. |
| Sensus |
| Others |
Supply Flow & Price Mechanics
Captive enzyme supply from integrated fermentation houses anchors both procurement security and margin protection for scFOS producers serving pharmaceutical-grade contracts. Belgian and Japanese enzyme houses leverage in-house fungal fructosyltransferase production to command premium positioning against non-integrated competitors exposed to raw material volatility.
Pricing Analysis
Distributor margin compression runs through the standard food-grade tier as Chinese domestic producers scale temperature-tolerant enzyme capacity and erode historical import premiums. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications separates cGMP-certified output commanding analytical certification premiums from cost-optimized animal nutrition material. Pricing pressure stems from sucrose feedstock volatility tied to Brazilian and Indian sugar harvest cycles. Animal feed compounders exhibit highest price sensitivity, while dietary supplement manufacturers absorbing EU purity threshold compliance costs show lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Belgium, China, and Japan anchor hub-and-spoke patterns for pharmaceutical-grade material requiring temperature-controlled documentation. Feedstock supply draws from Brazilian and Indian sugar cane, North American corn-derived fructose streams, and Asian sucrose sources. Single-source vulnerability concentrates in fungal fructosyltransferase expertise held by Belgian and Japanese enzyme houses. Distribution runs through direct producer contracts displacing opaque intermediaries, with Germany and China's functional food corridors commanding procurement authority through mature traceability infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scFOS market functions as a stable compounder anchored by tightening infant formula fortification mandates across Asia-Pacific food safety frameworks. Regulatory divergence between EFSA, FDA, and SAMR creates persistent reformulation demand that sustains ingredient supplier relevance.
For Market Incumbents: Cement pharmaceutical-grade certification barriers by expanding cGMP capacity in Flanders and Kanto industrial corridors before EU dietary supplement purity thresholds tighten further. Defend against long-chain FOS substitution by leveraging Belgian separation infrastructure for chain-length precision. Prioritize backward integration into temperature-tolerant fungal enzyme variants to compress energy input costs and widen margin buffers against Chinese domestic rivals.
For New Entrants and Emerging Players: Capture beverage clean-label substitution demand through liquid syrup format specialization targeting sugar-reduction formulations in European reformulation cycles. Target Japan's FOSHU-validated dairy-prebiotic niche where Meiji Co., Ltd. commands premiums but specification complexity deters multinational competitors. Lead with supply chain transparency audits and direct producer contracts that displace opaque intermediaries in China's functional food corridor.
For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up talent scarcity constrains new entrant hiring pipelines and concentrates expertise in Belgian and Japanese enzyme houses. Five-to-ten year viability favors integrated producers with captive enzyme supply and pharmaceutical-grade certification pathways. Monitor clinical trial accumulation for Bifidobacterium-targeted microbiome therapeutics as the inflection signal elevating pharmacopoeial-grade scFOS from excipient to active precursor status.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | cGMP capacity expansion in Flanders captures EU dietary supplement purity threshold tightening. |
| Temperature-Tolerant Enzyme Scale-Up | Chinese domestic fungal fructosyltransferase production erodes historical import premiums protecting European supply. |
| Liquid Syrup Format Development | Beverage clean-label sugar-reduction demand redirects investment toward pumpable bakery and dairy integration. |
| Direct Producer Contracting | Supply chain transparency audits in Germany and China displace opaque intermediaries from procurement authority. |
| Microbiome Therapeutic Partnership | Clinical trial positioning elevates scFOS from fiber claim excipient to pharmacopoeial-grade active precursor. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with infant formula compounders, beverage formulation scientists, dairy processing engineers, and pharmaceutical excipient procurement managers with secondary validation against FDA GRAS notifications, EFSA health claim dossiers, SAMR GB standards, and customs trade data. Bottom-up volume modeling from enzyme capacity installations and top-down demand triangulation from end-use consumption patterns converged on segment-level estimates.
Comparable-period anchoring tied projection assumptions to historical reference periods spanning enzyme technology diffusion cycles and regulatory guidance implementation lags across the analysis window. Segmentation dimensions modeled included physical format, application grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from substrate conversion efficiency improvements and reformulation mandate penetration curves, with fungal fructosyltransferase yield advances and infant formula fortification thresholds as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade and dietary supplement categories carry tighter precision than animal feed applications given documentation standard maturity. Forecasts reflect documented assumptions around enzyme scale-up rates and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Trehalose Market
Sweeteners
Aspartame Market
Sweeteners
Invert Sugar Market
Sweeteners
Europe Stevia Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Allulose Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Saccharin Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Mannitol Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Dextrates Market
Sweeteners
Liquid Sugar Market