
 Palm Sugar Market | 2026-2036
Palm Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Palm Sugar Market Analysis
The bakery segment is pivoting toward unrefined sweeteners as consumer preference for clean-label desserts intensifies. Wholesome Sweeteners Inc. leverages its certified organic supply chain to dominate North American retail shelf space. Big Tree Farms anchors Indonesian production with direct farmer partnerships across Sulawesi and Java. Navitas Organics differentiates through raw-food positioning and specialty store distribution.
Palm sugar denotes the crystallized sap of Borassus flabellifer, Arenga pinnata, or Cocos nucifera palms, containing sucrose, glucose, and fructose with a glycemic index below standard cane sugar. The sap undergoes slow evaporation at temperatures under 120 degrees Celsius to preserve caramel notes and mineral content, yielding a brown granule valued in confectionery and beverage applications. Organic palm sugar commands premium positioning as EU organic regulations and USDA National Organic Program standards restrict synthetic input use. Liquid palm sugar extracts are gaining traction in craft beverage manufacturing where solubility and flavor consistency matter. Granulated forms still occupy the largest volume share through supermarket and wholesale channels.
Indonesia's Ministry of Agriculture and Thailand's Department of Agriculture enforce geographic indication protections for regional palm sugar varieties, shaping export eligibility and price premiums. India's FSSAI mandates clear labeling of added sugars versus naturally occurring content, pushing reformulation in domestic packaged foods. Stakeholders must monitor evolving organic equivalency agreements between ASEAN suppliers and destination markets to secure uninterrupted certification pathways.
Market Dynamics
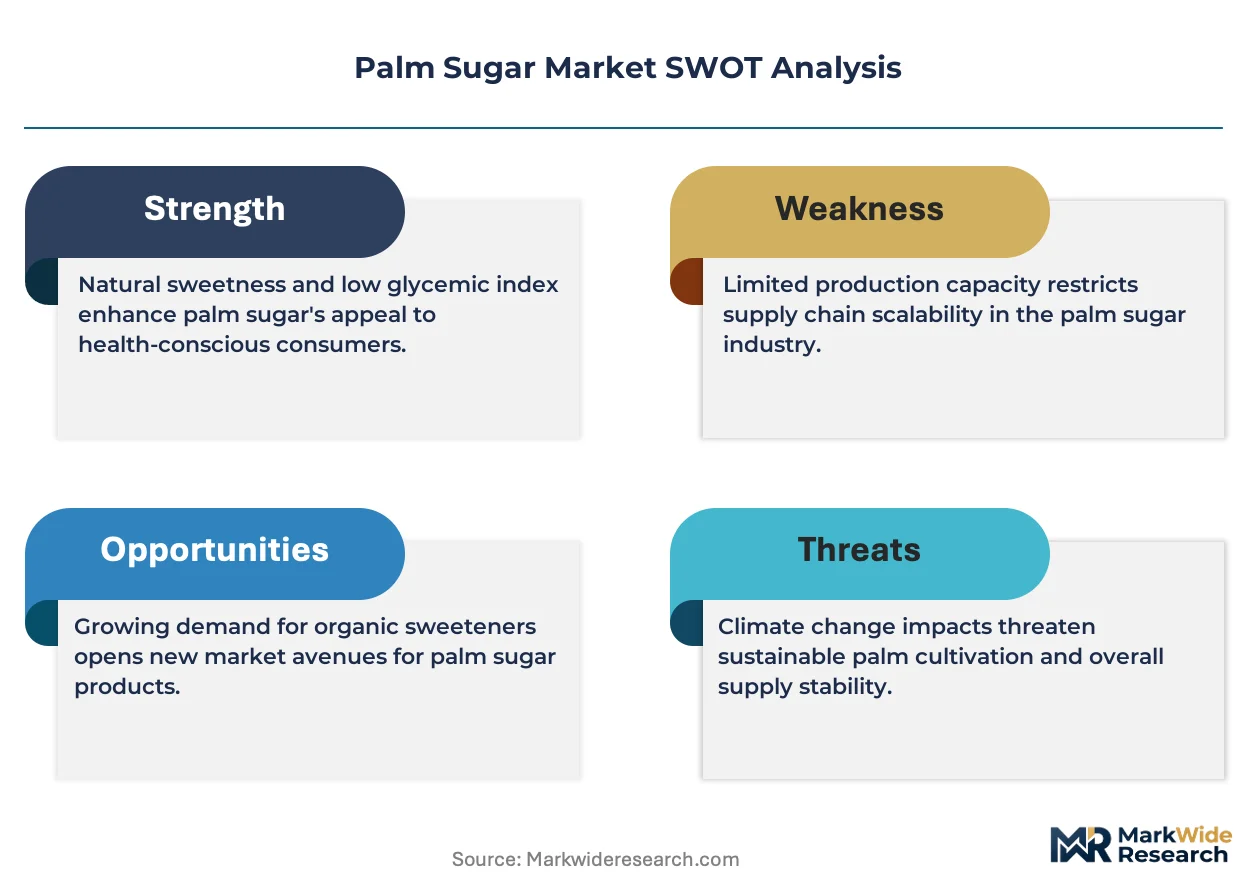
Clean-label reformulation mandates from EU organic regulations and India's FSSAI are forcing ingredient substitution across packaged food sectors, compressing adoption timelines for certified unrefined sweeteners.
Growth Catalysts
- EU Organic Certification:Mandatory purity standards under EU organic regulations accelerate bakery sector substitution of refined cane sugar with certified palm sugar across German and French retail channels.
- Indonesian Farmer Networks:Direct partnership models between processors and Sulawesi sap harvesters stabilize raw material throughput and reduce intermediary markup.
- Low-Temperature Evaporation:Sub-120°C processing technology preserves mineral content and caramel flavor profiles that command premium positioning in specialty confectionery.
Market Restraints
- Monsoon-Dependent Sap Flow:Indonesian and Thai harvest volumes fluctuate with irregular rainfall patterns, creating raw material scarcity during El Niño cycles.
- Geographic Concentration Risk:Over 70% of primary processing capacity clusters in Java and Sumatra, exposing supply chains to localized infrastructure disruptions.
- Glycemic Index Perception Gap:Consumer confusion between palm sugar and coconut sugar nutritional profiles limits penetration in diabetes-focused product segments.
Strategic Opportunities
- Craft Beverage Solubility Demand:Liquid palm sugar extracts address flavor consistency requirements in small-batch distillery and kombucha manufacturing.
- Indian FSSAI Label Clarity:Mandated differentiation between added and naturally occurring sugars creates reformulation incentives for domestic packaged food producers.
- Geographic Indication Premiums:Thailand's Department of Agriculture GI protections for regional varieties enable price stratification in export markets.
Industry Challenges
- Organic Equivalency Documentation:ASEAN suppliers face certification pathway interruptions when destination markets update organic recognition agreements.
- Artisan Skill Attrition:Traditional sap-tapping expertise concentrates among aging harvester populations in rural Indonesian provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palm Sugar Market |
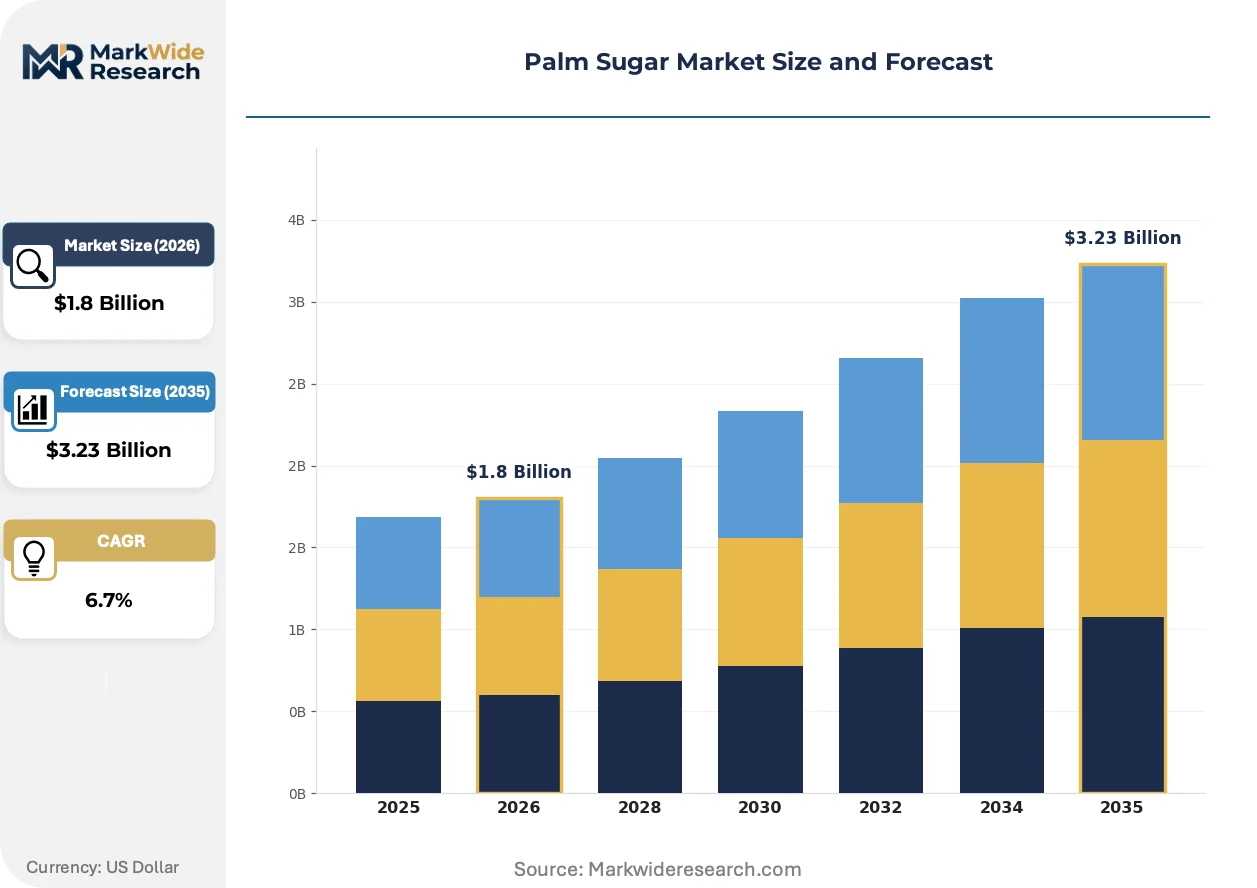
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Palm Sugar, Coconut Palm Sugar, Date Palm Sugar, Raw Palm Sugar Form: Granulated, Liquid, Powdered, Cubes End User: Food Industry, Bakery, Beverage Manufacturing, Hospitality Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Wholesome Sweeteners Inc., Betterbody Foods and Nutrition LLC, Navitas Organics, Celebes Coconut Corporation, Thai Coconut Public Company Limited, Big Tree Farms, American Key Food Products Inc., Medikonda Nutrients, Windmill Organics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palm Sugar Market Emerging Trajectories
Processing technology and regulatory alignment are compressing the gap between artisan production and industrial-scale consistency, reshaping how palm sugar enters formulated food systems.
Solar-powered vacuum evaporation is automating sap concentration workflows previously dependent on wood-fired open pans. Mid-scale Indonesian processors deploy these systems to reduce fuel costs and stabilize output quality. Craft chocolate manufacturers in Belgium and the Netherlands source from these upgraded facilities to meet batch-to-batch consistency requirements.
India's FSSAI labeling mandates are forcing added-sugar disclosure on packaged dessert and beverage products. Domestic bakery chains reformulate recipes to feature palm sugar as a naturally occurring ingredient rather than an additive. This regulatory pressure accelerates procurement from certified organic suppliers in Kerala and Tamil Nadu.
Specialty retailers are consolidating shelf space around single-origin palm sugar with traceable harvest coordinates. German and Austrian organic supermarket chains now require batch-specific geographic documentation. This procurement standard filters back to Indonesian exporters, who invest in blockchain-linked farmer identification systems to maintain access.
Palm Sugar Market Segmentation
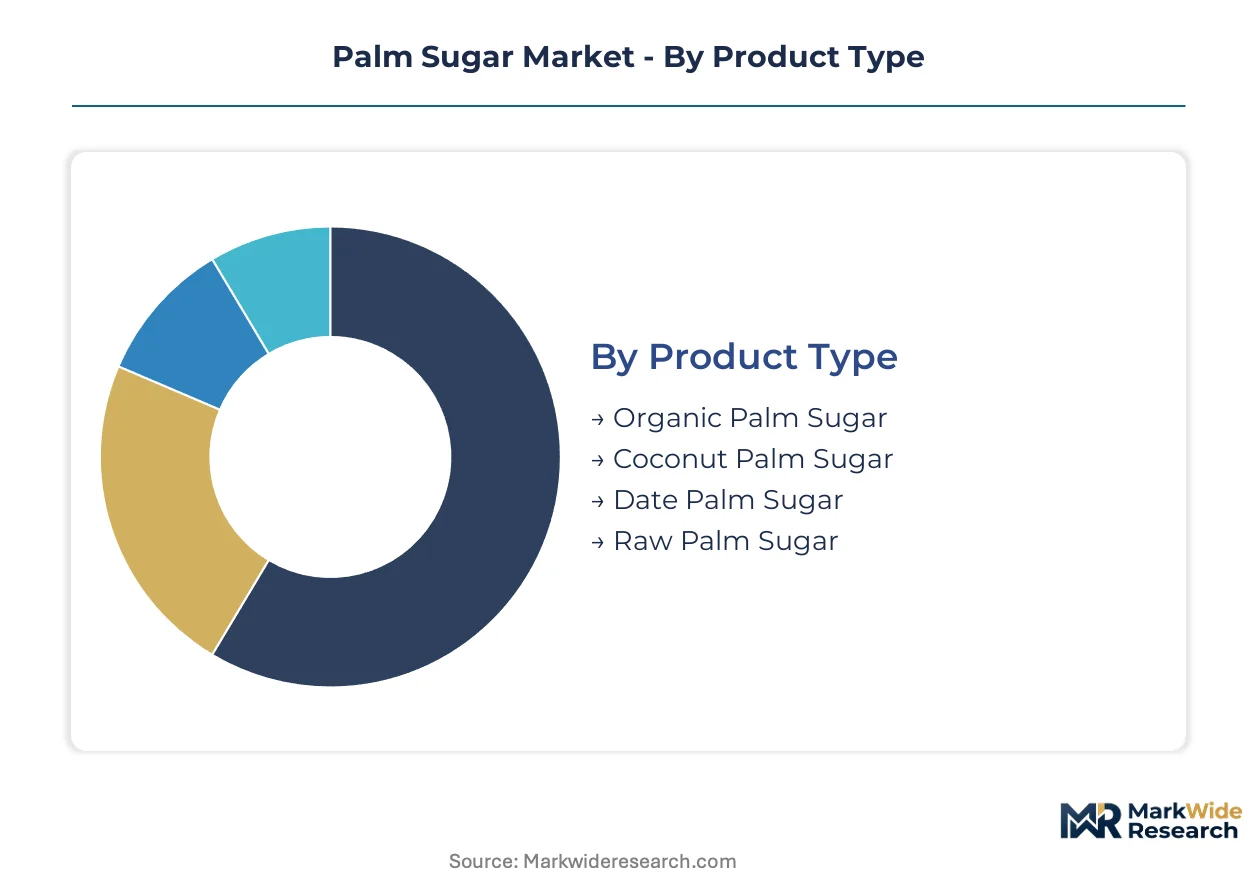
Palm sugar segmentation reveals how certification burdens, processing methods, and channel economics fragment commercial opportunities across the value chain. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Certification requirements diverge sharply across product types, with EU organic regulations and USDA National Organic Program standards imposing the heaviest documentation burdens on certified organic grades while conventional varieties face lighter oversight.
- Organic Palm Sugar:EU organic regulations and USDA National Organic Program standards mandate synthetic input prohibitions throughout the supply chain. German and French retail channels demand this grade for clean-label bakery reformulation, though equivalency documentation between ASEAN suppliers and destination markets creates certification pathway friction.
- Coconut Palm Sugar:Derived from Cocos nucifera sap with sucrose-glucose-fructose composition and glycemic index positioning below standard cane sugar. Consumer confusion between coconut sugar and palm sugar nutritional profiles constrains penetration in diabetes-focused segments despite functional similarities.
- Date Palm Sugar:Regional specialty concentrated in Middle Eastern and North African markets with limited export standardization.
- Raw Palm Sugar:Minimal processing preserves mineral content and caramel notes, appealing to specialty confectionery and raw-food positioning segments.
Organic Palm Sugar sits at the top of the volume ranking, with Coconut Palm Sugar climbing the fastest.
Form:
Processing technology investments and solubility requirements drive cost tier differentiation, with liquid extracts commanding premium positioning due to specialized evaporation infrastructure.
- Granulated:Dominates supermarket and wholesale channels through established packaging formats and recipe substitution compatibility. Indonesian and Thai processors concentrate capacity here, with Java and Sumatra facilities exposed to localized infrastructure disruption risks.
- Liquid:Addresses flavor consistency requirements in craft beverage manufacturing including small-batch distillery and kombucha production. Solubility advantages justify premium pricing, though cold-chain logistics add distribution complexity.
- Powdered:Fine particle size enables rapid dissolution in instant beverage applications.
- Cubes:Traditional format serving hospitality and gift segments with limited industrial uptake.
Granulated forms capture the largest volume share, with Liquid extracts gaining share fastest in premium beverage channels.
End User:
Application-specific purity standards and reformulation timelines create customer-type stratification, with packaged food manufacturers facing the tightest regulatory deadlines.
- Food Industry:Packaged dessert and confectionery producers respond to India's FSSAI labeling mandates by reformulating around naturally occurring sugar positioning. Procurement from certified organic suppliers in Kerala and Tamil Nadu accelerates to meet disclosure requirements.
- Bakery:Clean-label dessert demand intensifies across European and North American retail, with unrefined sweetener substitution compressing adoption timelines. German and Austrian organic supermarket chains now require batch-specific geographic documentation.
- Beverage Manufacturing:Craft distillery and kombucha segments prioritize liquid extracts for solubility and batch consistency.
- Hospitality:Restaurants and hotels source through wholesale channels with less stringent certification demands than retail-facing suppliers.
Food Industry applications lead by volume, with Beverage Manufacturing expanding most quickly on craft segment demand.
Distribution Channel:
Channel economics reflect traceability investment requirements, with specialty retail and online platforms demanding the most granular supply chain documentation.
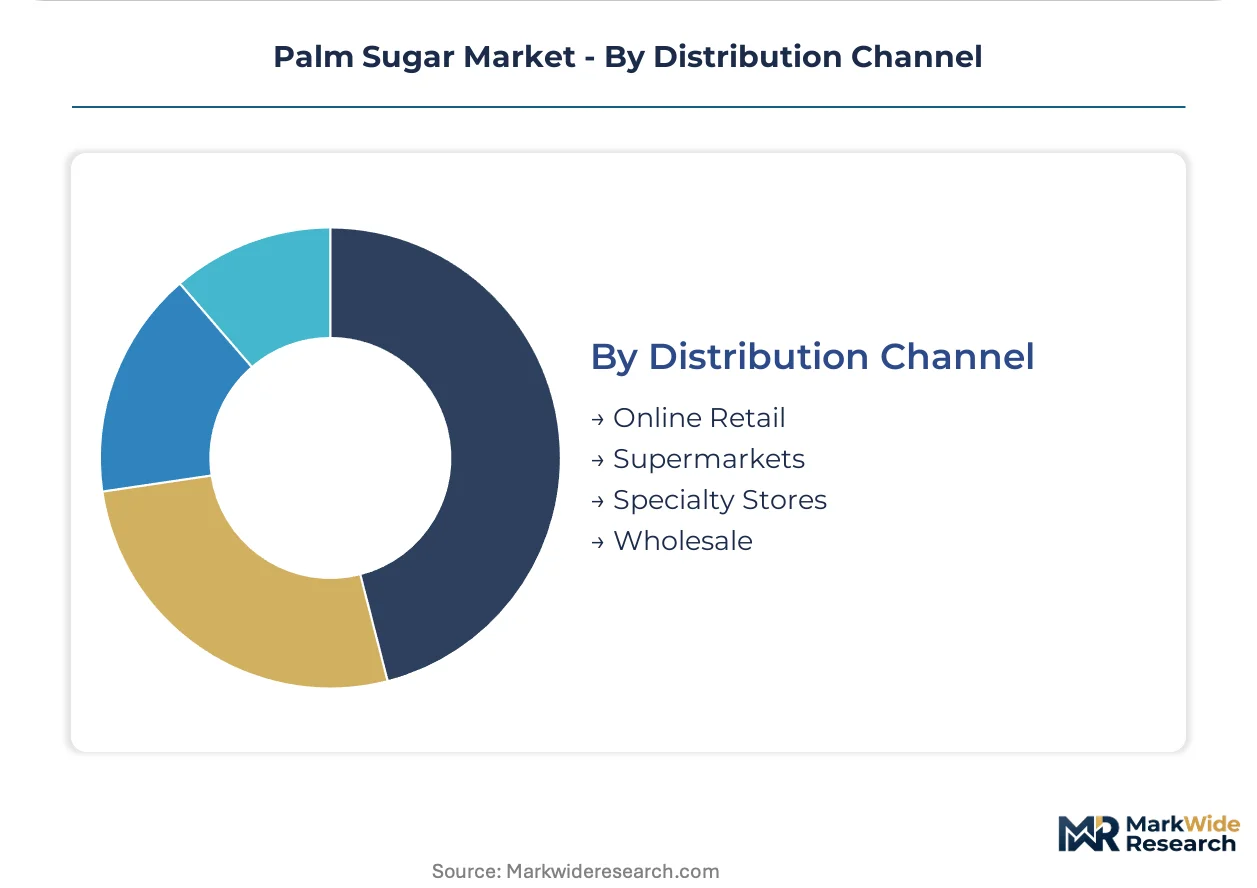
- Online Retail:Direct-to-consumer growth enables single-origin positioning with blockchain-linked farmer identification systems. German and Austrian organic supermarket chains filter procurement standards back to Indonesian exporters through digital traceability requirements.
- Supermarkets:Mass retail shelf space consolidation favors certified organic supply chains with established brand recognition. Wholesome Sweeteners Inc. dominates North American placement through certified organic infrastructure.
- Specialty Stores:Raw-food positioning and geographic indication premiums thrive here, with Navitas Organics differentiating through specialty distribution.
- Wholesale:Volume-driven channel serving hospitality and food service with lower margin but steadier throughput.
Supermarkets maintain the largest volume position, with Online Retail gaining share fastest on traceability-premium convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes production geography as ASEAN suppliers leverage lower certification costs against tightening EU organic standards. Compliance cost differentials between Indonesian harvester networks and European processing facilities redirect investment toward Sulawesi and Java.
Indonesia
Direct farmer partnerships across Sulawesi and Java stabilize raw material throughput for processors serving export markets. The Ministry of Agriculture enforces geographic indication protections for regional palm sugar varieties, shaping export eligibility criteria. Mid-scale processors in Sulawesi deploy solar-powered vacuum evaporation systems to reduce fuel costs and meet Belgian craft chocolate manufacturer consistency requirements.
Thailand
Thai Coconut Public Company Limited anchors domestic production capacity with integrated harvesting and processing operations. The Department of Agriculture administers geographic indication protections that enable price stratification in German and Austrian retail channels. Traditional sap-tapping expertise concentrates in aging rural harvester populations, creating artisan skill attrition risks for specialty exporters.
India
Domestic bakery chains accelerate procurement from certified organic suppliers in Kerala and Tamil Nadu to meet FSSAI labeling mandates. The Food Safety and Standards Authority of India requires clear differentiation between added and naturally occurring sugars on packaged dessert products. Processing clusters in Tamil Nadu reformulate recipes to feature palm sugar as a naturally occurring ingredient rather than an additive.
Germany
EU organic regulations drive bakery sector substitution of refined cane sugar with certified palm sugar across retail channels. German organic supermarket chains now require batch-specific geographic documentation with blockchain-linked traceability. Wholesome Sweeteners Inc. leverages certified organic supply chain infrastructure to dominate mass retail shelf space.
United States
Clean-label dessert demand intensifies unrefined sweetener substitution across North American retail channels. The USDA National Organic Program restricts synthetic input use throughout certified supply chains, creating documentation burdens for ASEAN exporters. Navitas Organics differentiates through raw-food positioning and specialty store distribution networks.
Palm Sugar Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with certified organic suppliers commanding premium positioning in European retail while conventional processors serve volume-driven hospitality channels. Market structure tilts toward consolidation at the branded tier and fragmentation among regional harvester cooperatives. Three archetypes dominate: certified organic specialists with traceable supply chains, integrated plantation-to-processor operators, and commodity traders sourcing through spot markets. Competitive moves concentrate on strategic partnerships with farmer networks and portfolio diversification into liquid extract formats.
Within the certified organic tier, Wholesome Sweeteners Inc. and Navitas Organics exemplify brand-led positioning through retail channel dominance and specialty distribution respectively. Big Tree Farms anchors Indonesian production archetypes with direct farmer partnership models. Among integrated operators, Thai Coconut Public Company Limited occupies a position representing plantation-to-processor vertical control. Celebes Coconut Corporation and Betterbody Foods and Nutrition LLC sit within the mid-scale processor category serving private-label and branded product lines.
| Leading Market Players |
|---|
| Wholesome Sweeteners Inc. |
| Betterbody Foods and Nutrition LLC |
| Navitas Organics |
| Celebes Coconut Corporation |
| Thai Coconut Public Company Limited |
| Big Tree Farms |
| American Key Food Products Inc. |
| Medikonda Nutrients |
| Windmill Organics Ltd. |
| Others |
Supply Flow & Price Mechanics
Raw sap procurement costs in Sulawesi and Java flow through three distinct margin layers before reaching German and Austrian retail shelves, with organic certification premiums compounding at each stage to separate certified organic grades from conventional commodity tiers.
Pricing Analysis
Distributor margins compress most acutely at the conventional grade tier where spot-market sourcing from Indonesian trader networks dominates. Three-tier pricing structure across premium, standard, and economy levels stratifies around EU organic certification status and batch-specific geographic traceability. Price differentiation stems from certification grade and volume scale, with boutique craft chocolate manufacturers absorbing the steepest premiums for single-origin documentation. Pricing pressure stems from El Niño-driven raw material scarcity in Indonesian harvest zones. Food industry procurement teams exhibit highest price sensitivity, while Belgian and Dutch craft chocolate manufacturers demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from German organic supermarket chains now mandate blockchain-linked farmer identification systems from Indonesian exporters, forcing mid-scale processors to qualify multiple Sulawesi harvester cooperatives simultaneously. Supply concentration rests on Indonesia, Thailand, and India as primary production nodes. Raw material dependencies center on Borassus flabellifer, Arenga pinnata, and Cocos nucifera palm sap flows, plus wood fuel or solar evaporation infrastructure. Single-source vulnerability intensifies where traditional sap-tapping expertise concentrates among aging harvester populations in rural Indonesian provinces. Distribution runs through direct processor-to-retailer contracts for certified organic grades, with conventional volumes flowing via commodity traders through spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's FSSAI labeling mandates and EU organic certification requirements continuously tighten compliance burdens, forcing ingredient substitution timelines that favor pre-certified supply chain operators.
For Market Incumbents: Extend geographic indication documentation investments to defend premium positioning against emerging Southeast Asian entrants. Anchor procurement contracts with Sulawesi farmer networks to secure throughput stability as monsoon volatility intensifies. Deepen backward integration into solar-powered vacuum evaporation infrastructure to capture margin from Belgian craft chocolate manufacturer consistency requirements.
For New Entrants and Emerging Players: India's FSSAI labeling mandates open a window for domestic Kerala and Tamil Nadu processors to capture bakery chain reformulation demand. Target liquid extract formats for craft beverage manufacturing where solubility premiums justify specialized infrastructure investment. Pursue direct-to-specialty-retailer distribution to bypass incumbent supermarket shelf space dominance.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale Indonesian processors lack capital to deploy blockchain traceability systems required by German procurement standards. Position acquisition screening around certified organic specialists with established farmer partnership networks rather than commodity traders. Monitor organic equivalency agreement negotiations between ASEAN suppliers and EU authorities as the critical inflection signal for certification pathway continuity.
| Strategic Initiative | Industry Significance |
|---|---|
| Farmer Partnership Network Expansion | Direct Sulawesi and Java harvester contracts stabilize raw material throughput against monsoon volatility. |
| Blockchain Traceability Implementation | German organic supermarket chains now require batch-specific geographic documentation for shelf access. |
| Solar-Powered Evaporation Deployment | Mid-scale Indonesian processors reduce fuel costs while meeting Belgian craft chocolate consistency standards. |
| Liquid Extract Format Development | Craft distillery and kombucha segments prioritize solubility advantages that justify premium positioning. |
| FSSAI Compliance Certification | Indian bakery chains accelerate procurement from certified suppliers to meet added-sugar disclosure mandates. |
Methodological Framework
Multiple input streams — processor production records, customs and trade documentation, retail audit data — were reconciled through bottom-up and top-down triangulation. Primary interviews with Indonesian harvester cooperative leaders, Thai plantation operations managers, Indian FSSAI compliance officers, German organic supermarket category buyers, and Belgian craft chocolate manufacturer procurement directors informed supply chain structure and pricing dynamics. Secondary validation drew from EU organic certification databases, USDA National Organic Program filings, FSSAI regulatory circulars, and ASEAN trade statistics. Cross-referencing across these sources established volume and value baselines.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include certification grade, product form, end-use application, and distribution channel, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from trend extrapolation against documented substitution patterns in bakery and beverage reformulation. Forecast inputs incorporated El Niño cycle impact assessments on Indonesian sap flow and evolving organic equivalency agreement status between ASEAN suppliers and destination markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged drought conditions in Sulawesi harvest zones or abrupt EU organic standard revisions. Deviation in FSSAI enforcement intensity or equivalency pathway interruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sanding Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Aspartame Market
Sweeteners
North America Stevia Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Xylitol Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
India Food Sweetener Market
Sweeteners
Citrus Molasses Market
Sweeteners
Erythritol Market
Sweeteners
South Korea Allulose Market