
 APAC Next Generation Storage Market | 2026-2036
APAC Next Generation Storage Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Next Generation Storage Market Outlook
Project finance for hyperscale data center buildouts is rewriting competitive access across the APAC Next Generation Storage Market. SAMSUNG anchors memory chip supply through captive fabrication in South Korea. Huawei Technologies Co., Ltd competes on integrated infrastructure stacks spanning compute, networking, and storage layers. Dell Inc. leverages direct enterprise relationships to sustain premium positioning in Australian and Japanese accounts.
APAC Next Generation Storage encompasses solid-state, magnetic, and cloud-distributed architectures engineered for sub-millisecond latency, petabyte-scale durability, and automated tiering across flash, HDD, and hybrid media. These systems serve data centers, enterprises, and government agencies requiring resilient, software-defined capacity for analytics, AI training pipelines, and regulatory archiving. Flash arrays lead technology spending as NAND cost curves improve access economics for latency-sensitive workloads. Object storage extends fastest among product types, driven by unstructured data proliferation in media, genomics, and surveillance. Hybrid deployment models capture widening margin pools by bridging on-premise control with cloud elasticity.
China's MIIT enforces GB standards for data localization and energy efficiency in storage facilities. India's TRAI and BIS frame cloud interoperability and cybersecurity certification requirements for government procurement. Japan's METI promotes JIS-aligned green IT targets that shape vendor qualification. Stakeholders must weigh regulatory fragmentation against scale economies when selecting deployment architectures and supplier partnerships.
Market Dynamics
Flash memory cost deflation is compressing the economic threshold for all-flash data centers across Southeast Asia, while China's MIIT energy efficiency mandates force infrastructure replacement cycles that bypass incremental upgrades.
Growth Catalysts
- Cloud migration mandates:India's financial services regulators require data localization for payment systems, compelling domestic storage infrastructure buildouts.
- GB standards enforcement:China's MIIT data localization rules create captive demand for compliant domestic storage architectures in government and telecom verticals.
- NAND cost curves:Flash array economics now match hybrid disk performance tiers for latency-sensitive AI training workloads.
Market Restraints
- Memory supply concentration:Captive fabrication in South Korea creates geographic chokepoints for enterprise SSD procurement.
- Dual carbon compliance costs:China's MEE efficiency standards impose capital-intensive cooling and power density retrofits on existing facilities.
- Object storage latency floors:Unstructured data architectures face hard limits for real-time analytics without flash tiering.
Strategic Opportunities
- Indonesia data center greenfield:Underserved archipelago geography offers first-mover positioning for edge storage nodes.
- JIS-aligned green IT procurement:Japan's METI certification creates preference premiums for energy-efficient array vendors.
- AI inference at edge:Convergence of 5G RAN and NVMe-over-Fabrics enables sub-millisecond storage for autonomous systems.
Industry Challenges
- Embedded firmware security certification:India's BIS cybersecurity mandates for government procurement extend validation timelines by quarters.
- Legacy SAN integration complexity:Financial services incumbents face forklift upgrade costs for software-defined storage migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Next Generation Storage Market |
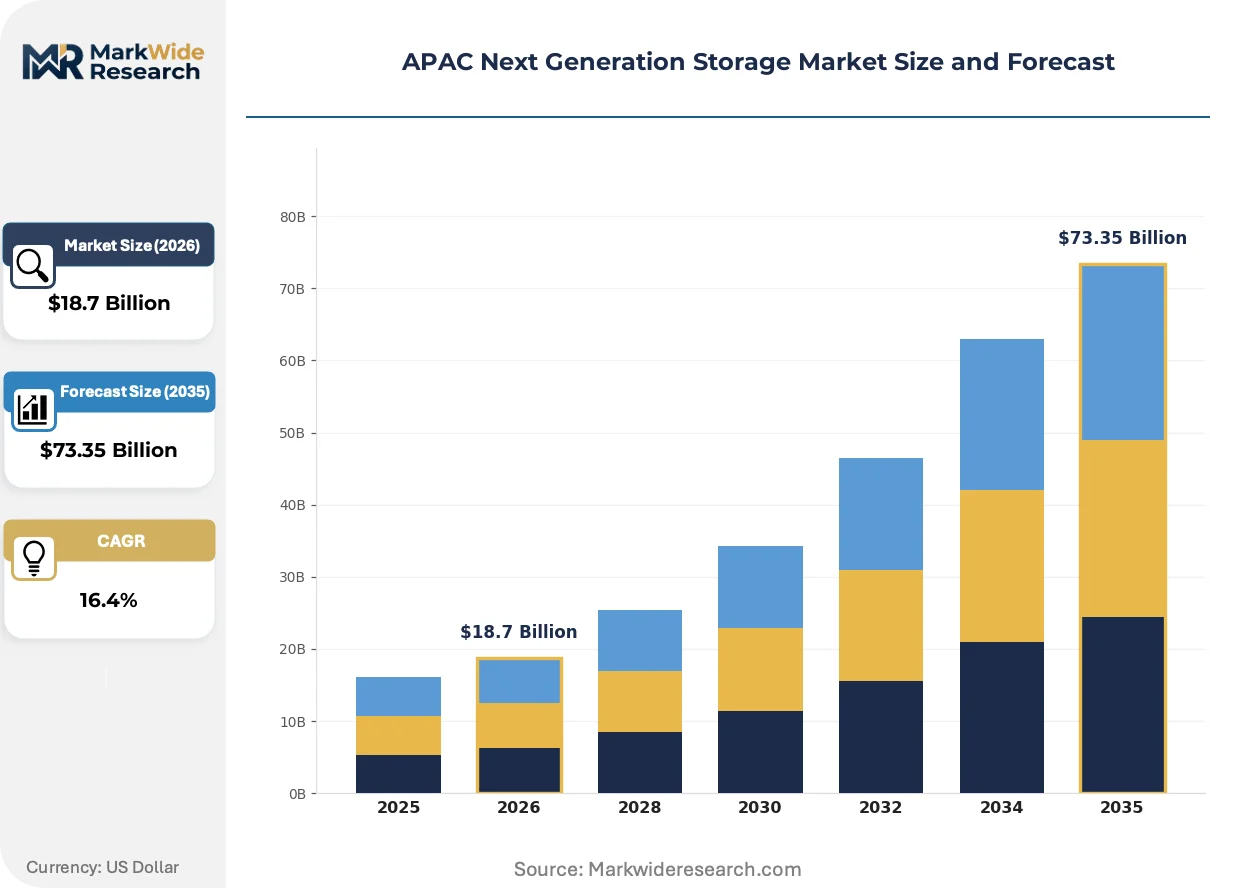
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SAN, NAS, Object Storage, Tape Storage Technology: Flash, HDD, Cloud Storage, Hybrid Solutions End User: Small Businesses, Enterprises, Data Centers, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Distributed |
| Companies Covered | Hewlett Packard Enterprise Development LP, Dell Inc., IBM Corporation, SAMSUNG, TOSHIBA CORPORATION, NetApp, Huawei Technologies Co., Ltd, Pure Storage, Inc., Hitachi Vantara LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Next Generation Storage Market Strategic Shifts
Computational storage architectures are collapsing the data movement bottleneck between memory and processing layers. This structural shift redefines where intelligence resides in the infrastructure stack.
Computational storage drives with embedded processing cores are digitizing analytics pipelines by executing queries at the storage layer rather than shuttling data to CPUs. Hyperscale operators in Singapore and Sydney are deploying these devices for real-time fraud detection. The technology is digitizing the traditional separation between compute and storage silos.
China's MIIT enforcement of GB 40879-2021 data center energy efficiency standards is accelerating liquid cooling retrofits for high-density flash arrays. Facilities in Beijing and Shanghai must demonstrate PUE thresholds or face operational restrictions. Flash-based systems with integrated thermal management capture disproportionate qualification share.
Consumption-based capacity contracts are displacing perpetual licensing for enterprise storage procurement. Australian and Japanese buyers now meter actual utilization rather than provisioning for peak. Financial services firms in Mumbai and Bangkok lead this transition, compressing vendor revenue recognition cycles while improving capital efficiency.
APAC Next Generation Storage Market Segmentation
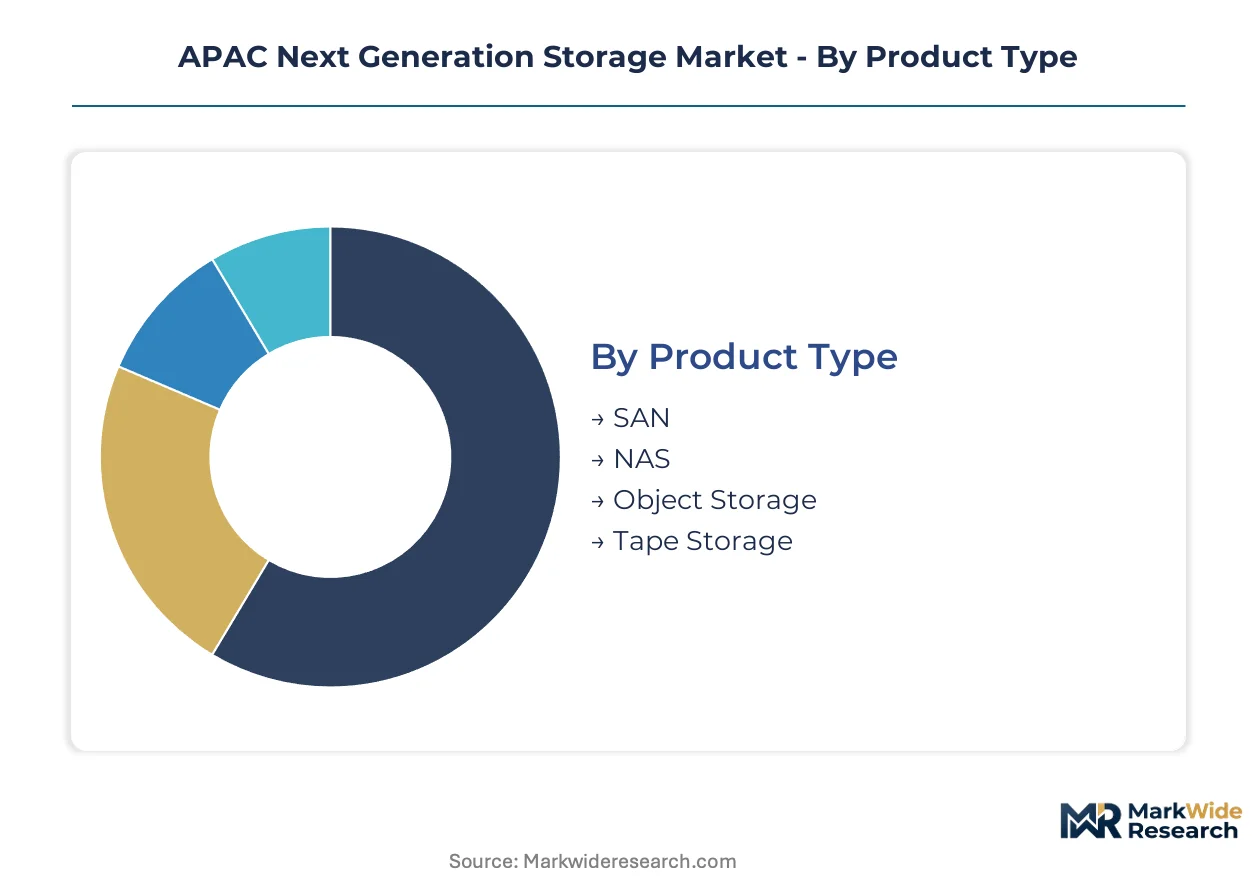
Segmentation in the APAC Next Generation Storage Market reveals how procurement patterns diverge across infrastructure maturity levels and regulatory environments. Understanding these dimensions enables vendors to align product roadmaps with the specific latency, durability, and compliance requirements dominating each buyer category.
Product Type:
Application workload characteristics dictate which storage architecture delivers optimal economics for transaction processing versus archival retention.
- SAN:Block-level storage networks deliver sub-millisecond latency for database workloads through dedicated Fibre Channel or iSCSI fabrics. Indian financial services firms in Mumbai deploy SAN infrastructure to meet RBI data localization mandates for core banking systems.
- NAS:File-level access protocols serve unstructured content repositories through Ethernet-attached appliances. Japanese media production houses in Tokyo leverage NAS clusters for 4K/8K video rendering pipelines requiring concurrent multi-user access.
- Object Storage:Flat namespace architectures scale to exabyte capacity for immutable data lakes. Australian genomics research facilities favor this format for long-term sequence archives.
- Tape Storage:Linear magnetic media provides air-gapped durability for regulatory compliance at the lowest cost per terabyte. South Korean government agencies maintain tape libraries for statutory retention periods.
SAN commands the established base. The steepest expansion runs through Object Storage.
Technology:
Cost tier positioning separates premium performance tiers from capacity-optimized alternatives across flash, magnetic, and cloud-native media.
- Flash:NAND-based solid-state drives eliminate mechanical latency for real-time analytics. Singaporean hyperscale operators deploy all-flash arrays for fraud detection workloads where millisecond response determines transaction approval.
- HDD:Magnetic spinning media retains cost advantage for sequential access patterns and warm archival tiers. Chinese cloud providers in Beijing maintain HDD farms for video streaming buffer caches.
- Cloud Storage:API-driven object services abstract physical infrastructure behind consumption billing. Indonesian e-commerce platforms adopt cloud storage to bypass capital-intensive data center construction.
- Hybrid Solutions:Automated tiering software migrates data across flash, disk, and cloud based on access patterns. Thai hospital networks implement hybrid architectures balancing EMR performance against decades of imaging archives.
HDD retains volume leadership in raw petabytes shipped. Hybrid Solutions are climbing the fastest as enterprises reconcile on-premise control with cloud elasticity.
End User:
Customer type determines procurement sophistication, with scale correlating to software-defined storage adoption and multi-year infrastructure planning horizons.
- Enterprises:Large organizations operate dedicated storage engineering teams evaluating NVMe-over-Fabrics and computational storage architectures. Australian mining conglomerates lead regional adoption of these advanced protocols for seismic data processing.
- Data Centers:Colocation and hyperscale facilities standardize on disaggregated storage pools serving multi-tenant workloads. Operators in Johor, Malaysia engineer for MIIT-equivalent efficiency standards to attract Chinese cloud customers.
- Small Businesses:Limited IT staffing drives preference for managed storage services and hyperconverged appliances. Vietnamese manufacturing SMEs procure through channel partners offering bundled support.
- Government Agencies:Sovereign data requirements and cybersecurity certification dominate procurement criteria. India's BIS mandates shape vendor qualification timelines for state-level data center projects.
Data Centers drive aggregate capacity absorption. Government Agencies are gaining share fastest as digital sovereignty initiatives accelerate across Southeast Asia.
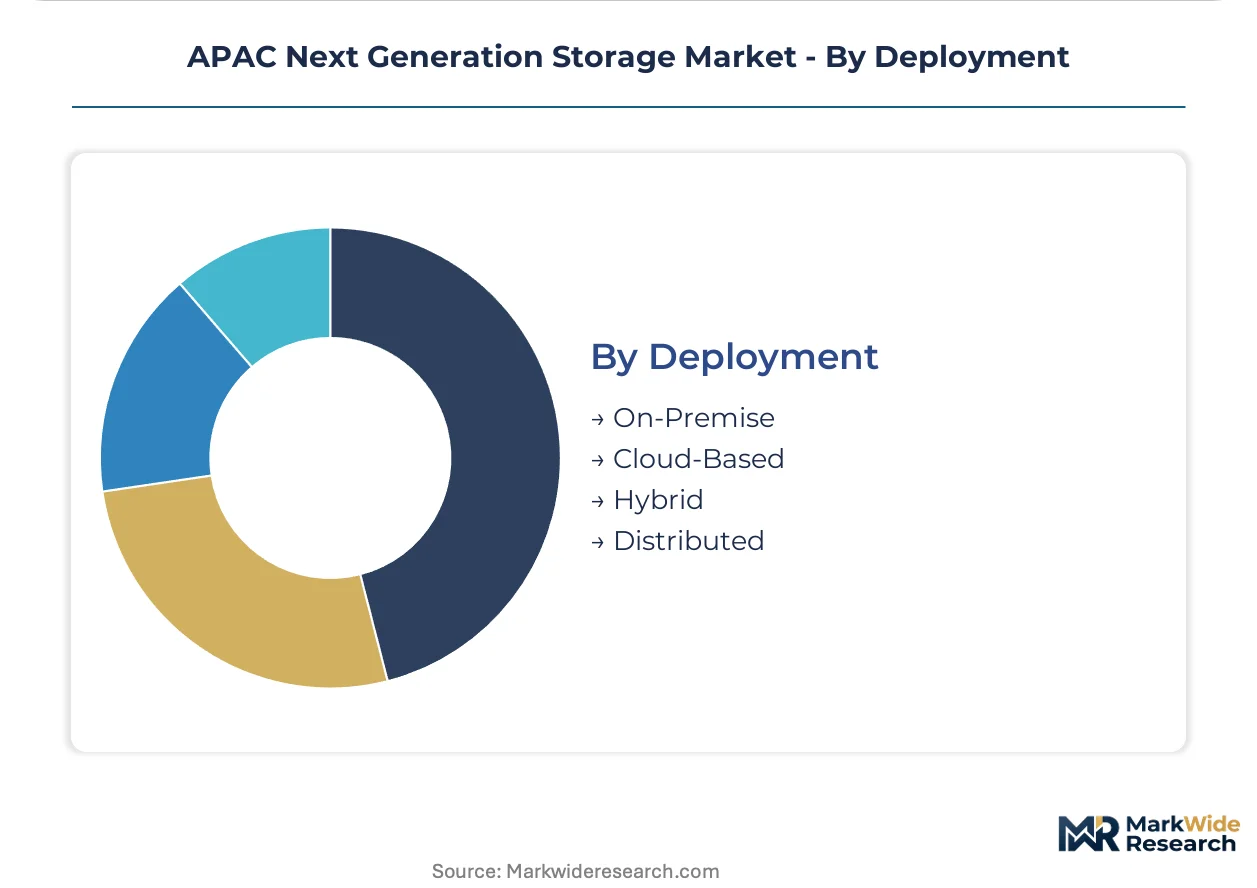
Deployment:
Geography and regulatory jurisdiction constrain where data physically resides, creating distinct architectural preferences across on-premise, cloud, and edge configurations.
- Hybrid:Workload portability between on-premise and cloud infrastructure addresses data gravity and compliance boundaries. Japanese financial institutions architect hybrid deployments to satisfy METI guidelines while leveraging public cloud burst capacity.
- On-Premise:Dedicated facilities maintain physical control over sensitive workloads and custom hardware configurations. Chinese telecom operators retain on-premise storage for MIIT-mandated data localization in government systems.
- Cloud-Based:Fully managed services eliminate capital expenditure and operational overhead for variable workloads. Philippine BPO providers consume cloud storage to align costs with fluctuating client contract volumes.
- Distributed:Edge nodes position storage capacity close to data generation points across dispersed geographies. Indonesian maritime logistics firms deploy distributed architectures across archipelago ports for vessel tracking systems.
On-Premise retains the installed base. Distributed deployment shows the steepest trajectory as 5G infrastructure enables edge analytics across fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT enforcement of GB energy efficiency standards is accelerating storage infrastructure replacement cycles across Chinese data centers. India's TRAI data localization mandates for financial services are driving domestic capacity buildouts. Southeast Asian governments are offering tax incentives for hyperscale facility investments.
China
Dual carbon targets from MEE are forcing efficiency upgrades in Beijing and Shanghai storage facilities. MIIT's GB 40879-2021 standards mandate PUE thresholds that disqualify legacy disk arrays. Flash-based systems with liquid cooling capture dominant share in Yangtze River Delta data center clusters.
India
Cloud migration among Mumbai financial services firms concentrates demand for compliant domestic infrastructure. RBI and TRAI data localization rules for payment systems require captive storage architectures. Telangana and Karnataka states are emerging as preferred locations for hyperscale buildouts serving banking workloads.
Japan
METI JIS-aligned green IT procurement creates preference premiums for energy-efficient array vendors. Tokyo media production houses drive NAS cluster demand for 4K/8K rendering pipelines. Osaka-Kansai industrial corridor leads computational storage adoption for manufacturing analytics.
Australia
Mining conglomerates in Western Australia pioneer NVMe-over-Fabrics deployment for seismic data processing. Consumption-based capacity contracts are displacing perpetual licensing across Sydney and Melbourne enterprises. TGA-aligned data sovereignty requirements shape government procurement criteria.
Singapore
Hyperscale operators deploy all-flash arrays for real-time fraud detection where millisecond response determines transaction approval. Johor Bahru cross-border data center clusters attract Chinese cloud customers seeking MIIT-equivalent efficiency standards. 5G RAN convergence enables edge storage nodes for maritime logistics tracking.
APAC Next Generation Storage Market Competitive Environment
On the supply side, the industry is consolidating around integrated infrastructure stacks and captive memory fabrication. Tiered competitive positioning separates premium array vendors from commodity disk suppliers. Three archetypes dominate: semiconductor-integrated manufacturers, systems integrators with direct enterprise relationships, and software-defined storage specialists. M&A activity targets NVMe software stacks, while strategic partnerships bridge flash supply with cloud distribution channels.
Among semiconductor-integrated manufacturers, SAMSUNG anchors regional memory supply through South Korean captive fabrication. Huawei Technologies Co., Ltd exemplifies the integrated infrastructure archetype spanning compute, networking, and storage layers. Dell Inc. occupies a position in premium enterprise segments through direct account relationships in Australian and Japanese markets.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Development LP |
| Dell Inc. |
| IBM Corporation |
| SAMSUNG |
| TOSHIBA CORPORATION |
| NetApp |
| Huawei Technologies Co., Ltd |
| Pure Storage, Inc. |
| Hitachi Vantara LLC |
| Others |
Value Chain & Pricing Dynamics
Single-source NAND flash dependency in South Korea determines both pricing tier spreads and supply chain shape across the APAC Next Generation Storage Market. MIIT energy efficiency mandates in China compound this concentration risk by forcing premium qualification tiers for liquid-cooled flash arrays.
Pricing Analysis
Certification level creates the primary spread between MIIT-compliant arrays and standard enterprise tiers. Subscription-based capacity contracts now dominate procurement across Australian and Japanese accounts, displacing perpetual licensing. Price differentiation hinges on GB standard compliance and liquid cooling integration, with Chinese government buyers showing least price sensitivity due to regulatory mandates. Cost compression in mid-tier hybrid solutions is intensifying because NAND spot price volatility feeds directly into array bill-of-materials.
Supply Chain Analysis
Upstream NAND wafer fabrication concentrates in South Korea, Japan, and the United States, with Chinese captive memory projects still ramping yield. Raw material dependencies span silicon wafers, rare earth elements for controller chips, and specialized cooling fluids for high-density deployments. Tariff exposure on semiconductor manufacturing equipment creates chokepoint vulnerability for Chinese domestic array vendors. Distribution runs through direct enterprise relationships for premium tiers and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
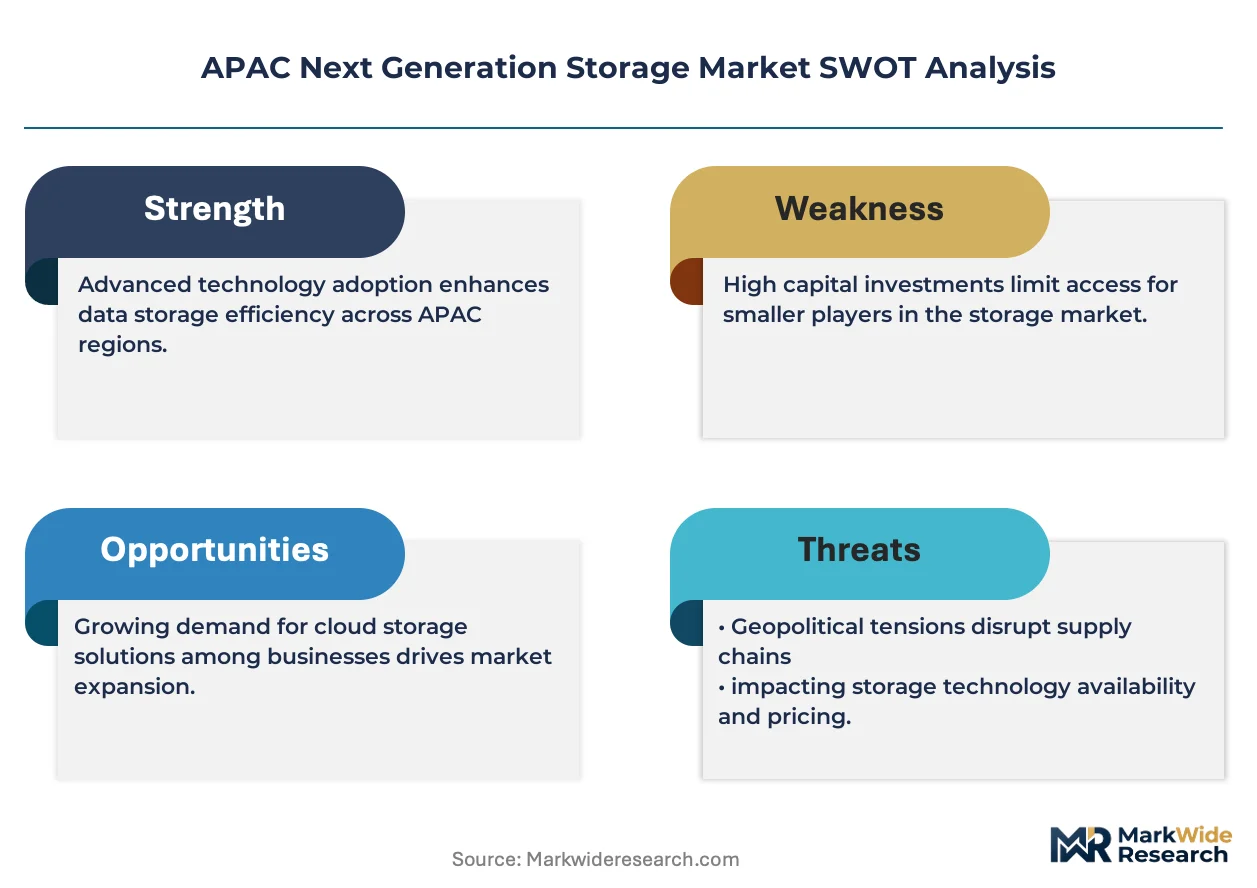
Fragmentation opportunity exists as regulatory divergence across China, India, and Japan creates specialized qualification requirements that favor niche specialists over generalist suppliers.
For Market Incumbents: Pre-empt margin erosion in standard flash tiers by deepening backward integration into NAND supply through long-term foundry partnerships. Capture MIIT certification premiums by accelerating liquid-cooled array roadmaps ahead of enforcement deadlines in Beijing and Shanghai clusters. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's underserved archipelago edge storage segment where geographic fragmentation blocks incumbent scale advantages. Target maritime logistics and port automation verticals with NVMe-over-Fabrics solutions purpose-built for distributed 5G RAN convergence. For Investors and Strategic Acquirers: The market sits at a regulatory-driven replacement phase that favors software-defined storage specialists with proven MIIT and BIS certification track records. Long-term viability across the analysis window hinges on acquiring NVMe software stack capabilities rather than commodity hardware assets. Monitor NAND cost curve inflection as the signal for margin expansion timing in all-flash array segments.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Fast-Track | GB 40879-2021 compliance unlocks government and telecom vertical procurement in Yangtze River Delta clusters. |
| Computational Storage Partnership | Embedded processing core alliances with Singaporean hyperscale operators accelerate fraud detection workload capture. |
| Indonesia Edge Node Buildout | Archipelago geography creates first-mover positioning for maritime logistics and port automation verticals. |
| Consumption-Based Contract Transition | Metered utilization models align vendor revenue with Australian and Japanese enterprise capital efficiency demands. |
| Liquid Cooling Retrofit Integration | Thermal management bundling captures disproportionate share in Beijing and Shanghai data center replacement cycles. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with data center operators, storage engineering directors, and procurement leads at hyperscale facilities, combined with secondary validation through MIIT GB standard filings, TRAI regulatory circulars, and hyperscaler capex disclosures. Bottom-up triangulation against top-down market sizing ensured segment-level consistency across flash, HDD, and hybrid technology tiers.
Forecast inputs incorporated deployment model adoption curves, regulatory enforcement timelines, and NAND cost trajectory assumptions across the projection horizon. Segmentation dimensions spanned product architecture, technology media, end-user scale, and deployment geography. CAGRs derived from slope analysis of historical capacity absorption rates adjusted for MIIT-mandated replacement acceleration in Chinese facilities.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or cross-border data flow restrictions would shift the trajectory. Cross-checking against foundry utilization reports and hyperscaler infrastructure disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
USB Key Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Transparent Caching Market
Data Storage
Flash-Based Array Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Australia Data Center Storage Market
Data Storage
Next-Generation Storage Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Japan Data Center Storage Market
Data Storage
North America Next Generation Storage Market
Data Storage
Solid State Array Market
Data Storage
Blu-Ray Drive Market
Data Storage
Transparent Cache Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Distributed Storage System Market