
 South Korea Data Center Storage Market | 2026-2036
South Korea Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Storage Market Insights
Project finance structures and sale-leaseback arrangements for hyperscale facilities is reshaping competitive access for mid-tier domestic operators. Samsung Electronics leverages captive semiconductor supply to anchor its storage systems division with vertically integrated NAND flash. SK hynix sustains R&D intensity in high-bandwidth memory architectures that feed directly into next-generation server platforms. Dell Technologies competes through established enterprise relationships and localized service networks across Korean commercial districts.
South Korea data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention in centralized compute environments, typically operating across SAS, NVMe, and Ethernet protocols with latency thresholds below five milliseconds for enterprise workloads. The primary commercial purpose centers on enabling continuous availability for transactional databases, analytics clusters, and virtualized infrastructure serving cloud-native applications. SAN deployments dominate enterprise procurement for structured database workloads where block-level access and fiber channel reliability justify premium positioning. Object storage segments are expanding fastest as media streaming platforms and AI training pipelines generate exabyte-scale unstructured datasets that defy traditional hierarchical file systems. Hybrid deployment models capture widening margin pools by allowing enterprises to maintain sensitive workloads on-premises while bursting peak demand into colocation facilities.
MFDS guidelines on medical data localization and KISA cybersecurity certifications shape product compliance requirements for storage vendors serving healthcare and financial verticals. The Personal Information Protection Act amendments enforce strict cross-border transfer restrictions that mandate domestic data residency, directly expanding capacity requirements at Korean facilities. Stakeholders must monitor evolving K-Cloud procurement standards and sovereign AI infrastructure commitments that will determine qualification criteria for government-linked storage contracts.
Market Dynamics
Sovereign data requirements under the Personal Information Protection Act are compressing procurement timelines for domestic storage infrastructure. Cloud hyperscalers now face mandatory localization clauses that redirect capital flows toward Korean facility construction.
Growth Catalysts
- K-Cloud Strategy:Government procurement mandates under this framework require domestic data residency for public sector workloads. State-backed demand creates guaranteed offtake for qualified storage vendors.
- AI Training Pipelines:Generative model development generates exabyte-scale unstructured datasets that overwhelm traditional hierarchical storage. Object storage architectures capture this surge.
- Seoul-Gyeonggi Corridor:Demand concentrates in this metropolitan cluster where latency-sensitive financial services and media platforms require sub-five-millisecond access to primary data stores.
Market Restraints
- NAND Flash Supply Concentration:Domestic fabrication capacity remains captive to Samsung Electronics and SK hynix. Mid-tier operators face allocation constraints during supply tightness.
- MFDS Medical Data Localization:Healthcare storage deployments require dual certification timelines that extend revenue recognition by six to twelve months versus commercial workloads.
- Power Density Constraints:Gyeonggi Province grid interconnection limits prevent facility expansion beyond 50 megawatts at single sites without transmission upgrades.
Strategic Opportunities
- Busan-Ulsan Secondary Cluster:Underdeveloped coastal markets offer lower land costs and submarine cable landing proximity for export-oriented cloud nodes.
- NVMe-over-Fabric Convergence:Ethernet-based storage networking merges compute and storage traffic onto unified switches. Infrastructure consolidation reduces switch port counts by forty percent.
- KISA Cybersecurity Certification:Mandatory security ratings for critical infrastructure create qualification barriers that favor established vendors with compliance resources.
Industry Challenges
- Specialized Firmware Engineering:Domestic talent pools lack depth in NVMe controller optimization and FTL algorithm development. Vendors compete for limited semiconductor systems engineers.
- Legacy SAN Migration Complexity:Financial institutions maintain fifteen-to-twenty-year-old Fibre Channel estates. Parallel operation periods stretch eighteen months during protocol transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Storage Market |
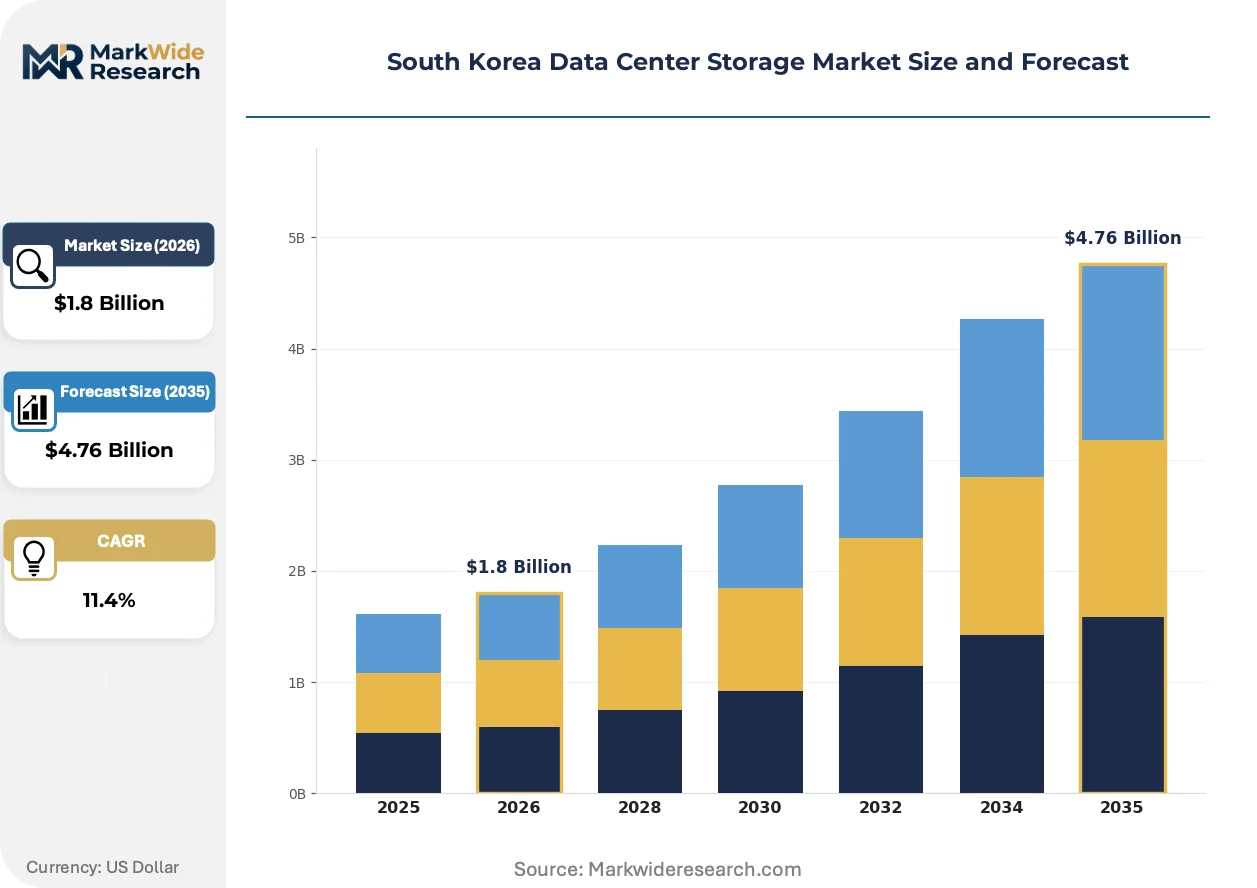
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: SAN, NAS, DAS, Object Storage Deployment Model: On-Premises, Colocation, Hybrid, Managed Services End User: IT Service Providers, Telecom Operators, Enterprises, Government Agencies Capacity: Below 50TB, 50-100TB, 100-500TB, Above 500TB |
| Companies Covered | Samsung SDS, Samsung Electronics, SK hynix, LG CNS, Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM Corporation, Hitachi Vantara, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Storage Market Trends and Innovations
Storage-class memory architectures and software-defined disaggregation are dissolving traditional boundaries between compute, memory, and persistent tiers. Korean operators now pilot composable infrastructure that treats NAND flash as addressable memory.
Compute Express Link technology enables cache-coherent memory pooling across server nodes. Hyperscale operators in Pangyo and Songdo deploy CXL-attached memory expansion modules to support in-memory analytics without proportional DRAM growth. This architecture is collapsing the performance gap between DRAM and NVMe storage, permitting tier consolidation that reduces server node counts.
Amendments to the Personal Information Protection Act enforce strict cross-border transfer restrictions. Financial services and healthcare providers must maintain primary data copies within Korean territorial jurisdiction. Storage vendors serving these verticals now embed encryption key management that satisfies KISA certification requirements, extending sales cycles but creating switching costs post-implementation.
Buyers now unbundle hardware procurement from management software licensing. Large enterprises negotiate direct NAND flash supply agreements while sourcing control plane software separately. This pattern fragments vendor relationships and compresses gross margins on integrated systems, particularly visible among Seoul-based internet platforms with internal engineering capabilities.
South Korea Data Center Storage Market Segmentation
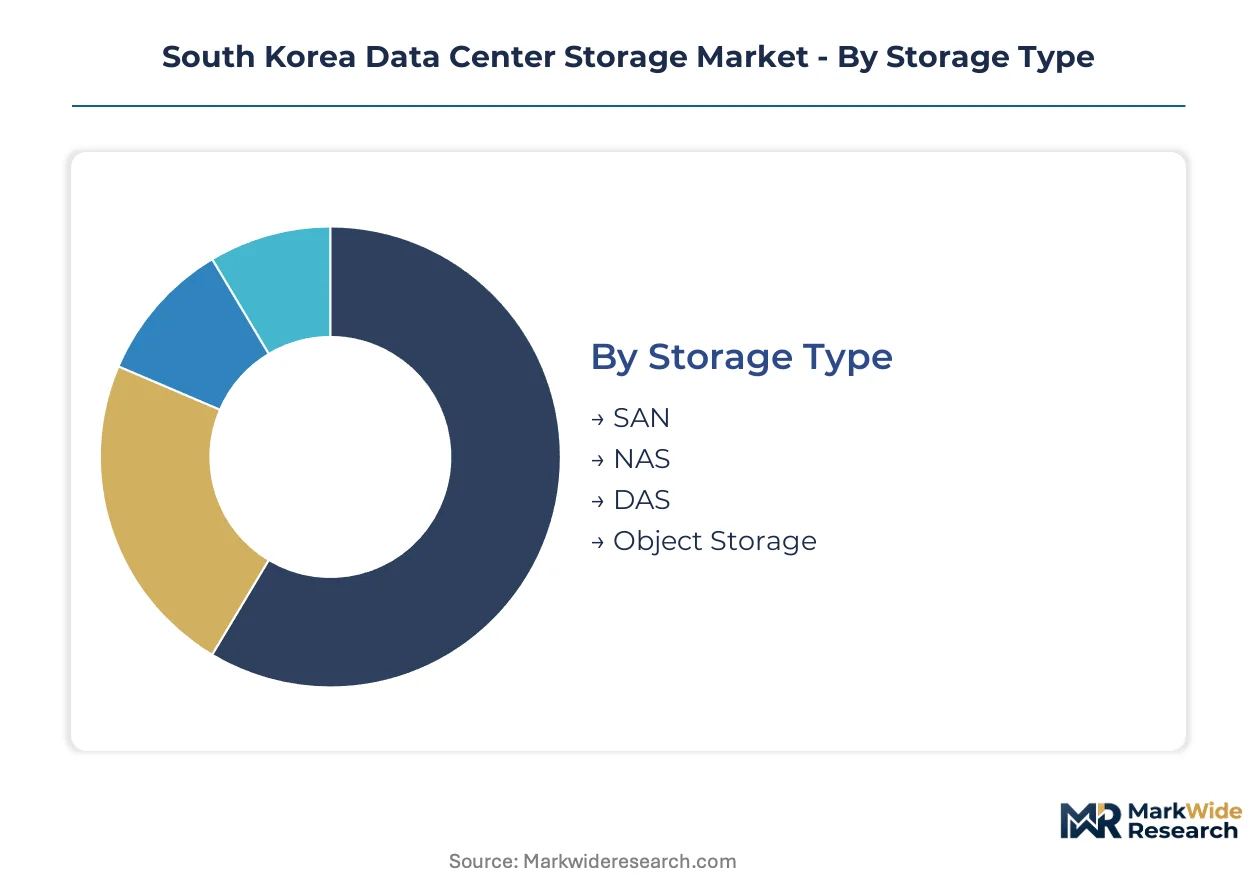
South Korea data center storage segmentation reveals distinct procurement rhythms across architectures and deployment modes. Replacement cycles vary from three-year SSD refreshes in hyperscale facilities to decade-long SAN investments at financial institutions.
Storage Type:
Replacement velocity diverges sharply across architectures, with flash-based systems cycling every 36-48 months while mechanical disk arrays persist for 7-10 years in archival tiers.
- SAN:Block-level storage networks utilizing Fibre Channel or iSCSI protocols deliver sub-millisecond latency for transactional databases. Seoul financial district deployments prioritize SAN for core banking systems where downtime costs exceed $1 million per hour.
- Object Storage:Flat namespace architectures scale to exabyte capacity without hierarchical metadata bottlenecks. Pangyo-based streaming platforms and AI training clusters drive demand for S3-compatible object stores handling unstructured media and model checkpoint datasets.
- NAS:File-level access protocols serve departmental shares and content repositories. Mid-tier enterprises in Gyeonggi Province favor NAS for consolidated home directories and engineering design files.
- DAS:Direct-attached configurations persist in edge computing nodes and legacy application silos. Manufacturing facilities in Incheon maintain DAS for shop-floor data collection systems with localized retention requirements.
SAN anchors the volume base while Object Storage gains share at the steepest rate.
Deployment Model:
Capital allocation patterns separate ownership-heavy strategies from operational expenditure models, with hybrid architectures capturing margin from workload portability requirements.
- On-Premises:Dedicated facilities under enterprise control house compliance-sensitive workloads. MFDS medical data localization mandates force healthcare providers to maintain primary storage within hospital-owned Seoul metropolitan facilities.
- Hybrid:Orchestrated workload placement across owned and leased infrastructure enables burst capacity without permanent overprovisioning. Korean internet platforms deploy hybrid models to handle traffic spikes during live commerce events.
- Colocation:Wholesale leased space in certified facilities reduces facility construction timelines. Cloud hyperscalers secure multi-megawatt commitments in Songdo and Busan data centers to satisfy K-Cloud domestic residency clauses.
- Managed Services:Third-party operational responsibility transfers staffing burdens to specialized providers. Regional banks without internal storage engineering depth contract managed services for 24/7 array administration.
On-Premises retains the largest installed base though Hybrid deployments expand most quickly as sovereignty requirements collide with elasticity demands.
End User:
Procurement sophistication varies from standardized government tenders to highly customized enterprise specifications negotiated over 18-month cycles.
- Enterprises:Large manufacturing conglomerates and chaebol affiliates operate multi-petabyte estates with dedicated storage engineering teams. Samsung and SK affiliates leverage captive NAND supply relationships for preferential allocation during supply constraints.
- IT Service Providers:Domestic cloud operators and systems integrators aggregate demand across downstream clients. Naver Cloud and Kakao Enterprise build distributed storage fabrics to compete with global hyperscalers for Korean enterprise workloads.
- Government Agencies:Public sector procurement follows K-Cloud framework mandates with domestic vendor preferences. National tax and pension systems require KISA-certified encryption for all persistent storage tiers.
- Telecom Operators:KT, SK Telecom, and LG Uplus integrate storage with edge computing and 5G network infrastructure. Mobile carriers position storage-as-a-service offerings to capture enterprise data gravity at network edge locations.
Enterprises dominate current capacity deployment while IT Service Providers capture the steepest growth trajectory as multi-tenant platforms consolidate fragmented demand.
Capacity:
Unit economics shift nonlinearly across scale thresholds, with petabyte-scale deployments accessing fundamentally different supply negotiations than sub-100TB procurements.
- Above 500TB:Hyperscale configurations negotiate direct NAND flash supply agreements bypassing channel margins. Major streaming platforms and AI labs in Pangyo deploy disaggregated storage pools exceeding single-rack capacity limits.
- 100-500TB:Mid-range arrays serve consolidated enterprise workloads and regional cloud nodes. This tier captures healthcare PACS imaging archives and financial risk analytics clusters requiring balanced performance with capital efficiency.
- 50-100TB:Departmental and branch office deployments favor converged infrastructure with embedded storage. Provincial government offices and manufacturing plant IT maintain this scale for localized operational data.
- Below 50TB:Entry-level configurations address remote sites and development environments. Small enterprises in secondary cities deploy these capacities for initial virtualization projects before scaling to centralized infrastructure.
The 100-500TB tier anchors procurement volume while Above 500TB configurations climb fastest as AI training and media streaming concentrate demand at extreme scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Seoul Capital Area exceeds Busan-Ulsan by 18-22 percent due to latency premiums and land scarcity. Secondary clusters command lower rates but attract submarine cable landing investments. The analysis covers five sub-regions defining Korean storage infrastructure deployment.
Seoul Capital Area
Financial services and cloud hyperscalers drive petabyte-scale procurement in Gangnam and Yeouido districts. MFDS medical data localization mandates force hospital systems to maintain primary storage within metropolitan boundaries. Pangyo Techno Valley hosts disaggregated storage pools for AI training clusters exceeding single-rack capacity limits.
Busan-Ulsan
Submarine cable landings at Busan port create export-oriented cloud node opportunities with 40 percent lower land costs than Seoul. K-Cloud framework procurement extends to regional government data centers in this corridor. Ulsan industrial complexes maintain direct-attached storage for manufacturing execution systems with localized retention requirements.
Daegu-Gyeongbuk
Telecom edge computing investments by KT and SK Telecom concentrate storage-as-a-service infrastructure in this inland hub. KISA cybersecurity certification requirements apply to critical infrastructure deployments across the region. Daegu medical clusters deploy compliant storage for hospital information systems under MFDS guidelines.
Daejeon-Sejong
Government agency data centers under K-Cloud mandates anchor demand in this administrative capital corridor. National tax and pension systems require KISA-certified encryption for all persistent storage tiers. Sejong smart city initiatives pilot software-defined storage for municipal IoT data aggregation.
Gwangju-Honam
Underdeveloped grid interconnection limits facility expansion beyond 50 megawatts at single sites without transmission upgrades. Regional internet platforms deploy hybrid models to handle traffic spikes during live commerce events. Honam agricultural data collection systems utilize entry-level storage for initial virtualization projects.
South Korea Data Center Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with NAND flash and memory architectures. The vendor base concentrates around captive semiconductor supply chains and established enterprise relationships. Three archetypes dominate: vertically integrated chaebol affiliates, global systems integrators with localized service networks, and domestic cloud operators building distributed storage fabrics. Competitive moves center on strategic partnerships for firmware engineering talent and direct NAND supply agreements that bypass channel margins.
Within the domestic chaebol tier, Samsung Electronics and SK hynix occupy positions defined by captive semiconductor fabrication capacity. Samsung SDS represents the systems integration archetype, anchoring enterprise storage deployments with localized service coverage across Korean commercial districts. Dell Technologies exemplifies the global platform vendor archetype, competing through established relationships and compliance resources for KISA certification requirements.
| Leading Market Players |
|---|
| Samsung SDS |
| Samsung Electronics |
| SK hynix |
| LG CNS |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM Corporation |
| Hitachi Vantara |
| Others |
Pricing and Supply Chain Analysis
Samsung Electronics and SK hynix captive NAND fabrication in South Korea concentrates upstream supply control, directing margin pools toward vertically integrated system vendors and compressing channel margins for third-party array assemblers. Pricing power accumulates at the semiconductor tier while downstream integrators compete on service attach rates and KISA certification bundling.
Pricing Analysis
Configured-to-order enterprise SAN deployments command 35-50 percent premiums over standard SKUs due to firmware customization and Fibre Channel zoning complexity. Pricing stratifies across premium certified tiers, standard commercial configurations, and economy cloud-scale volumes with minimal service entanglement. Cost compression in the mid-tier array segment is intensifying because internet platforms negotiate direct NAND supply agreements, bypassing traditional channel markups. Hyperscale cloud operators exhibit lowest price sensitivity due to volume scale, while provincial healthcare providers face acute budget constraints that extend procurement cycles.
Supply Chain Analysis
Fab-less controller vendors and Taiwanese ODMs hold dominant contract manufacturing capacity for enterprise storage enclosures and NVMe carrier boards. Component sourcing draws from South Korea for NAND flash, Taiwan for controller silicon and PCB fabrication, and China for power supply and mechanical chassis subassemblies. Single-source vulnerability concentrates in high-bandwidth memory die supply from SK hynix for AI-optimized storage platforms. Distribution runs through authorized systems integrators with KISA-certified service capabilities, supplemented by direct hyperscale procurement teams managing multi-petabyte annual allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI training infrastructure mandates are disrupting procurement patterns, with sovereign data residency requirements under K-Cloud frameworks accelerating domestic capacity buildouts beyond historical replacement cycles.
For Market Incumbents: Build switching-cost moats through embedded encryption key management that satisfies MFDS medical data localization and KISA cybersecurity certification requirements. Anchor enterprise relationships with localized firmware engineering support in Seoul and Pangyo districts. Threaten emerging domestic cloud operators by extending direct NAND supply agreements to captive chaebol affiliates, compressing their procurement economics. Prioritize R&D investment in CXL-attached memory expansion modules to capture hyperscale AI training cluster demand. For New Entrants and Emerging Players: Busan-Ulsan coastal markets with submarine cable landing proximity and 40 percent lower land costs than Seoul represent the most penetrable entry point for export-oriented cloud node operators. Secondary Gwangju-Honam grid interconnection constraints have suppressed facility development, creating whitespace for modular edge deployments serving agricultural IoT data aggregation. Target managed services contracts at regional banks lacking internal storage engineering depth. Go-to-market execution should emphasize KISA certification pre-qualification to accelerate revenue recognition versus six-to-twelve month healthcare compliance timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hyperscale colocation facilities as power density requirements exceed 50 megawatt single-site limits without transmission upgrades. Long-term viability over the coming decade centers on qualification for government-linked K-Cloud procurement and sovereign AI infrastructure commitments. Acquisition targets should display established KISA certification resources and localized service networks across Korean commercial districts. Monitor quarterly hyperscaler capex disclosure patterns for inflection signals in domestic facility construction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabric Convergence | Ethernet-based storage networking reduces switch port counts by forty percent through infrastructure consolidation. |
| KISA Cybersecurity Certification | Mandatory security ratings create qualification barriers favoring vendors with established compliance resources. |
| Direct NAND Supply Agreements | Hyperscale procurement teams bypass channel margins by negotiating direct allocation with Samsung and SK hynix. |
| CXL-Attached Memory Expansion | Cache-coherent memory pooling collapses the performance gap between DRAM and NVMe storage tiers. |
| Busan-Ulsan Facility Development | Submarine cable landing proximity and lower land costs attract export-oriented cloud node investment. |
Research Methodology
Initial hypotheses were tested against primary input from data center infrastructure directors, storage procurement officers at chaebol affiliates, KISA certification auditors, and hyperscale facility engineering leads and refined through secondary validation. Primary fieldwork encompassed structured interviews across Seoul Capital Area, Busan-Ulsan, and Daejeon-Sejong corridors. Secondary sources included hyperscaler capex disclosures, MFDS medical data localization filings, K-Cloud framework procurement documents, and customs records for NAND flash import volumes. Bottom-up capacity deployment tracking was triangulated against top-down semiconductor supply allocation data.
Demand-supply balance modeling across the analysis window incorporated storage type segmentation by SAN, object, NAS, and DAS architectures alongside deployment mode differentiation across on-premises, hybrid, colocation, and managed services. End-user segmentation captured enterprise, IT service provider, government agency, and telecom operator procurement patterns. Capacity tier modeling addressed nonlinear unit economics above 500TB, 100-500TB, 50-100TB, and below 50TB thresholds. CAGRs were derived from facility construction pipeline tracking and replacement cycle velocity differentials between flash-based systems and mechanical disk arrays.
Macroeconomic conditions sit as an overlay; deviation in Korean won exchange rates, domestic power pricing, or semiconductor capital equipment cycles would shift the trajectory. Forecasts reflect assumptions regarding K-Cloud procurement mandate continuity, MFDS guideline stability, and hyperscaler localization commitment durability. Quarterly review of hyperscaler facility announcement patterns, KISA certification issuance rates, and NAND flash spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Data Storage Devices Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Tape Storage Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Digital Recording System Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Solid State Array Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Channel Storage Systems Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Hybrid Flash Storage Market
Data Storage
North America SSD Caching Market
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
North America AMH and Storage Systems Market