
 Zoned Flash Market | 2026-2036
Zoned Flash Market Size, Share, and Industry Trends Forecast 2026-2036
Zoned Flash Market Analytics
Hyperscale data center demand is decoupling from traditional consumer storage patterns as AI training clusters consume zoned flash at unprecedented density. Samsung Electronics leverages its captive 3D NAND fabrication to dominate supply contracts for cloud providers. SK Hynix anchors the high-bandwidth memory adjacent segment with advanced packaging investments. Micron Technology competes through vertical control over TLC and QLC wafer output in Idaho and Singapore fabs.
Zoned flash designates NAND memory architected with host-managed logical zones that isolate write streams to optimize endurance, latency, and garbage collection efficiency; each zone typically spans hundreds of megabytes to gigabytes and exposes append-only write semantics through the Zoned Namespaces command set. This architecture serves primary industrial purposes in data centers requiring predictable quality-of-service for object storage and in automotive systems logging sensor telemetry under strict temporal determinism. TLC cells now lead volume shipments across cloud deployments where cost-per-gigabyte dominates procurement decisions, while QLC accelerates fastest in warm-archive tiers where read-heavy patterns offset write-amplification penalties. SLC retains premium positioning in automotive and industrial end users where ten-year retention specifications and extended temperature ranges sustain margin pools despite shrinking unit share.
FCC equipment authorization requirements govern zoned flash integration into telecommunications infrastructure in the United States, while REACH substance restrictions and the EU AI Act shape material compliance and data governance obligations for European deployments. China's GB standards and MIIT cybersecurity review processes condition market access for imported NAND controllers and firmware. Stakeholders must monitor evolving zone capacity specifications in the NVMe standard and assess whether host-software ecosystems or controller-integrated FTL abstraction will determine the next interface generation's commercial winners.
Market Dynamics
Host-managed zoned namespaces are displacing conventional block interfaces as AI training clusters demand deterministic latency and predictable garbage collection behavior from petabyte-scale storage arrays.
Growth Catalysts
- EU AI Act data governance mandates:European hyperscale operators are rearchitecting storage layers to satisfy auditability requirements for training data provenance, accelerating zoned flash qualification timelines.
- QLC endurance breakthroughs:Controller firmware advances have extended write cycles sufficiently for warm-archive tiers, opening zoned architectures to cost-sensitive cloud object stores previously served by hard disk.
- Automotive sensor fusion logging:Deterministic write latency specifications for autonomous vehicle black-box recorders are mandating zoned append-only semantics under ISO 26262 functional safety frameworks.
Market Restraints
- 3D NAND fabrication concentration:Advanced node capacity clusters in South Korea and Taiwan create geographic supply vulnerability amplified by water-intensive process dependencies.
- Controller firmware complexity:Host-managed zone state machines require kernel-level driver development that extends enterprise qualification cycles and elevates integration costs versus legacy FTL abstraction.
- NVMe specification fragmentation:Evolving zone capacity and append-size limits across protocol revisions force redundant hardware validation for multi-generational data center refresh programs.
Strategic Opportunities
- India data localization buildout:Domestic cloud infrastructure investments under the Digital Personal Data Protection Act are creating greenfield demand for compliant zoned storage architectures without legacy migration burden.
- Computational storage convergence:Zoned namespaces integrating near-data processing engines enable query-offload for analytics workloads, collapsing storage-network-compute boundaries in edge deployments.
- REACH substance substitution incentives:European environmental compliance pressures are accelerating fluoropolymer-free packaging qualification, rewarding early movers with preferred supplier status.
Industry Challenges
- Firmware engineering scarcity:Deep expertise in zone state machine optimization and garbage collection algorithms concentrates among controller vendors, constraining independent system integrator capabilities.
- Multi-generational qualification overhead:Cloud procurement cycles demand simultaneous validation of TLC and QLC variants across multiple controller generations, compressing product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zoned Flash Market |
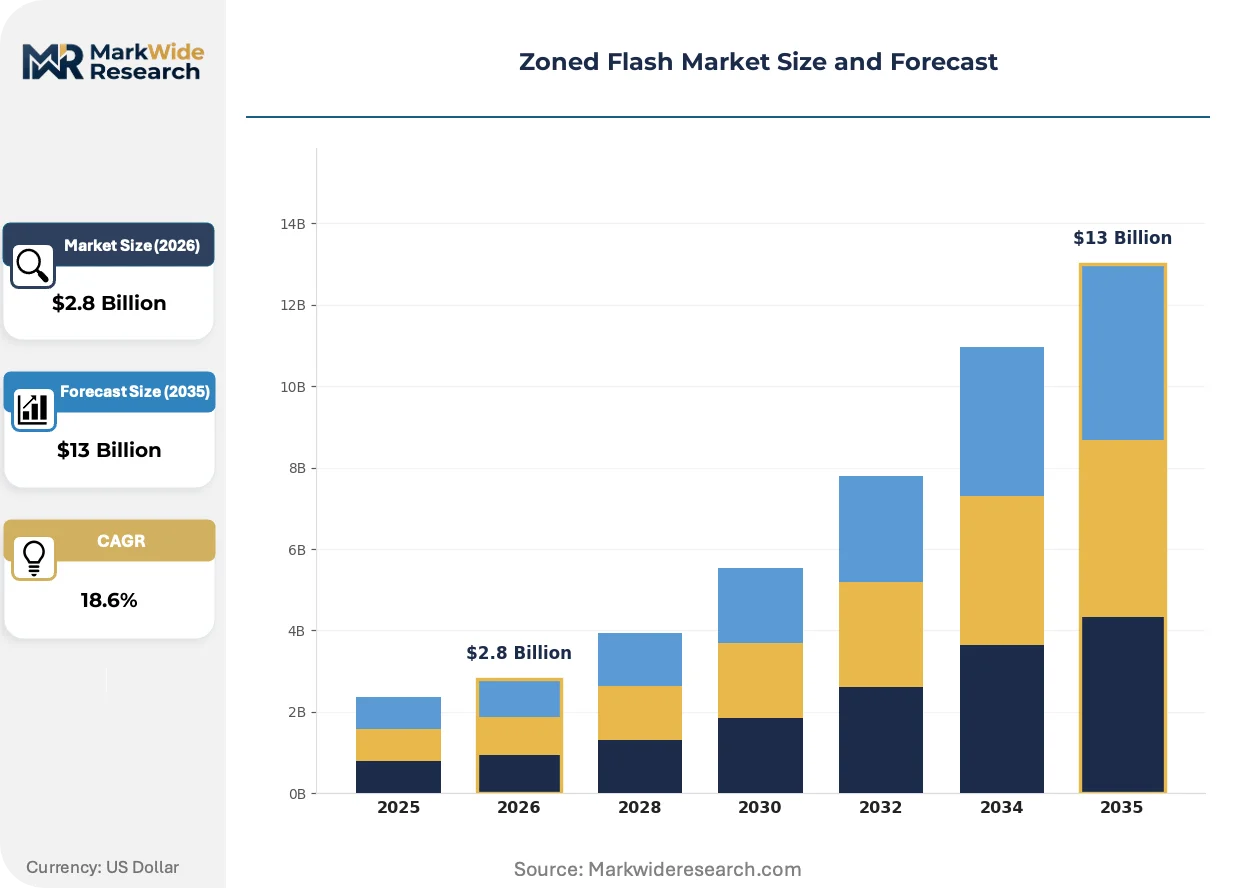
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLC, MLC, TLC, QLC Technology: 3D NAND, 2D NAND, NOR Flash, Floating Gate End User: Consumer Electronics, Data Centers, Automotive, Industrial Applications Deployment: On-Premises, Cloud, Hybrid, Embedded Systems |
| Companies Covered | Micron Technology, Toshiba, Samsung Electronics, Kingston Technology, ADATA Technology, Western Digital, Intel, Corsair Memory, SK Hynix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zoned Flash Market Evolving Landscape
Computational storage controllers are embedding inference engines directly into zoned flash devices, collapsing data movement penalties for vector search and similarity computation workloads.
Zone-append semantics are electrifying object storage software stacks by eliminating write amplification penalties that previously constrained QLC deployment in high-ingestion environments. Cloud operators in the United States are retrofitting existing NVMe-oF fabrics to expose zoned namespaces without hardware replacement. The structural consequence is a compression of cost-per-terabyte curves that previously separated performance from capacity tiers.
China's MIIT cybersecurity review processes for imported NAND controllers are mandating domestic firmware signing and source code audit provisions that extend market access timelines. Manufacturers are responding by establishing joint verification laboratories in Shanghai and Shenzhen. Automotive suppliers targeting Chinese OEMs face the longest qualification delays due to additional GB standard harmonization requirements.
Hyperscale procurement contracts are unbundling hardware acquisition from firmware lifecycle management, with cloud providers demanding decade-long security patch commitments from controller vendors. This behavior shift concentrates purchasing power among buyers with sufficient scale to enforce contractual terms. The pattern is most visible in United States and German data center expansions where total-cost-of-ownership models now dominate capital allocation decisions.
Zoned Flash Market Segmentation
Zoned flash architectures impose distinct endurance, latency, and cost profiles across cell types and deployment contexts. Segmentation reveals where host-managed namespaces displace legacy block storage versus where controller abstraction persists. Upgrade cycles vary dramatically between automotive ten-year retention specifications and hyperscale three-year refresh intervals.
Product Type:
Replacement cycles for zoned flash products diverge sharply by cell density, with single-level cells outlasting quad-level cells by an order of magnitude in write endurance.
- SLC:Single-level cells store one bit per cell, delivering the highest endurance and retention specifications. Automotive black-box recorders and industrial control systems specify SLC for ten-year data integrity under extended temperature ranges.
- MLC:Multi-level cells encode two bits per cell, occupying a narrowing middle ground between endurance and density. Legacy enterprise SSDs continue MLC procurement, though new designs favor TLC economics.
- TLC:Triple-level cells dominate cloud infrastructure procurement where cost-per-gigabyte governs capital allocation. Hyperscale data centers in the United States and China specify TLC for warm-tier object storage with moderate write amplification tolerance.
- QLC:Quad-level cells pack four bits per cell, accelerating fastest in read-heavy archive tiers. Controller firmware advances have extended QLC write cycles sufficiently to displace hard disk in high-ingestion environments.
TLC sits at the top of the volume ranking, with QLC climbing the fastest.
Technology:
Cost tiers in zoned flash manufacturing map directly to wafer stacking complexity and lithography node requirements.
- 3D NAND:Vertical stacking of memory cells achieves density scaling independent of planar lithography limits. Samsung Electronics and SK Hynix deploy 200+ layer 3D NAND for zoned namespace controllers serving cloud providers.
- 2D NAND:Planar architectures persist in cost-constrained embedded applications where legacy controller compatibility outweighs density requirements. Industrial automation systems specify 2D NAND for supply continuity.
- NOR Flash:Byte-addressable read performance supports execute-in-place firmware storage. Automotive ECUs specify NOR for deterministic boot sequences under ISO 26262 safety frameworks.
- Floating Gate:Charge-trapping alternatives dominate new designs, though floating gate retains niche deployment in radiation-hardened aerospace applications.
3D NAND captures the dominant cost tier, with NOR Flash holding premium positioning in safety-critical segments.
End User:
Application requirements determine whether zoned append-only semantics justify host-software integration costs versus legacy FTL abstraction.
- Consumer Electronics:Smartphones and laptops specify zoned flash primarily through opaque controller abstraction. End users rarely expose host-managed namespaces directly.
- Data Centers:Hyperscale operators rearchitect storage software around zone-append semantics to eliminate garbage collection jitter. AI training clusters demand deterministic latency from petabyte-scale arrays.
- Automotive:Autonomous vehicle sensor fusion systems mandate zoned logging for temporal determinism. ISO 26262 functional safety frameworks require append-only write semantics with failure-mode predictability.
- Industrial Applications:Factory automation and energy infrastructure specify extended temperature ranges and decade-long retention. SLC dominates where failure costs exceed premium pricing.
Data Centers generate the highest absolute volume, with Automotive expanding most quickly on autonomous platform deployment.
Deployment:
Customer infrastructure maturity shapes whether zoned flash integrates through greenfield architecture or retrofit overlay.
- On-Premises:Enterprise data centers qualify zoned namespaces through NVMe-oF fabric upgrades without full hardware replacement. Storage administrators manage zone state machines through kernel-level drivers.
- Cloud:Hyperscale operators deploy zoned flash at rack scale with custom controller firmware. Amazon Web Services and Microsoft Azure specify decade-long security patch commitments from vendors.
- Hybrid:Edge-to-core pipelines expose zoned semantics at the edge while abstracting zones in centralized tiers. Manufacturing customers deploy hybrid architectures for sensor telemetry preprocessing.
- Embedded Systems:Microcontroller-integrated zoned flash serves deterministic logging without host software complexity. Automotive Tier 1 suppliers specify embedded deployment for ECU cost constraints.
Cloud deployment leads in volume scale, with Embedded Systems gaining share fastest on automotive ECU integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping zoned flash manufacturing footprints as compliance cost gaps between jurisdictions widen. Fabricators are relocating controller firmware development and final assembly to regions with streamlined cybersecurity review processes while maintaining captive NAND production in established clusters.
United States
Hyperscale cloud operators in Northern Virginia and Oregon are driving zoned flash procurement for AI training clusters. FCC equipment authorization requirements govern telecommunications infrastructure integration. The Greater Phoenix semiconductor corridor hosts advanced packaging facilities serving data center demand.
China
Domestic cloud infrastructure buildouts and autonomous vehicle programs are accelerating zoned namespace adoption. MIIT cybersecurity review processes mandate domestic firmware signing and source code audits for imported controllers. The Yangtze River Delta concentration in Shanghai and Suzhou houses joint verification laboratories established by foreign manufacturers.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify zoned flash for autonomous driving black-box recorders. The EU AI Act and REACH substance restrictions shape data governance and material compliance obligations. The Dresden semiconductor cluster anchors European 3D NAND backend processing.
South Korea
Captive 3D NAND fabrication capacity in Pyeongtaek and Icheon supplies global cloud provider contracts. The Korea Communications Commission coordinates with international standards bodies on NVMe protocol harmonization. Seoul-based controller vendors concentrate zone state machine optimization expertise.
India
Domestic cloud infrastructure investments under the Digital Personal Data Protection Act are creating greenfield demand for compliant storage architectures. BIS certification requirements and data localization rules condition market access for imported NAND controllers. The Bengaluru-Hyderabad corridor hosts hyperscale data center construction without legacy migration burden.
Zoned Flash Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators race to qualify 200-plus layer 3D NAND for zoned namespace controllers. The market structure concentrates among integrated memory manufacturers with captive wafer output and specialized controller vendors with firmware expertise. Two strategic archetypes prevail: vertically integrated semiconductor conglomerates and fabless controller specialists. Competitive dynamics center on decade-long security patch commitments demanded by hyperscale buyers and geographic diversification of backend assembly to mitigate supply concentration risk.
Within the integrated memory tier, Samsung Electronics, SK Hynix, and Micron Technology exemplify archetypes defined by captive 3D NAND fabrication and direct cloud provider supply relationships. Samsung Electronics anchors the high-volume contract segment through vertical control over wafer output. SK Hynix occupies a position adjacent to high-bandwidth memory packaging investments. Micron Technology represents the North American fabrication alternative with Idaho and Singapore production bases.
| Leading Market Players |
|---|
| Micron Technology |
| Toshiba |
| Samsung Electronics |
| Kingston Technology |
| ADATA Technology |
| Western Digital |
| Intel |
| Corsair Memory |
| SK Hynix |
| Others |
Value Network & Pricing Analysis
Captive 3D NAND fabrication anchors both supply positioning and pricing power for integrated memory manufacturers serving hyperscale cloud providers. Samsung Electronics, SK Hynix, and Micron Technology leverage in-house wafer output to secure decade-long security patch commitments from buyers while insulating margin pools from controller vendor competition.
Pricing Analysis
Direct-to-OEM volume discounts compress distributor margins as hyperscale procurement teams unbundle hardware from firmware lifecycle management. Contract-based long-term offtake dominates cloud infrastructure procurement, with price differentiation driven by cell density tier and zone capacity specifications. Cost compression in QLC tiers intensifies as controller firmware advances extend write cycles toward hard disk displacement. Data center operators exhibit the highest price sensitivity, while automotive OEMs absorbing SLC premiums for ISO 26262 compliance remain least elastic.
Supply Chain Analysis
Returns and refurbishment flows remain minimal for zoned flash given write-endurance degradation patterns, though automotive black-box recorders mandate decade-long retention specifications that stress replacement logistics. Wafer fabrication concentrates in South Korea, Taiwan, and the United States, with advanced packaging drawing from fluoropolymer substrate supplies and EUV photoresist chemistries. Single-source vulnerability in 200-plus layer 3D NAND etching equipment creates chokepoint exposure. Distribution runs through direct OEM contracts and specialized memory distributors serving industrial automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hyperscale AI training clusters shift procurement criteria from cost-per-gigabyte toward deterministic latency specifications and predictable garbage collection behavior.
For Market Incumbents: Lock in firmware engineering talent through decade-long security patch commitments that cloud providers now demand contractually. Prioritize backward integration into zone state machine optimization capabilities to defend against controller vendor consolidation. Samsung Electronics and SK Hynix should extend captive 3D NAND advantages through advanced packaging investments in high-bandwidth memory adjacent segments. For New Entrants and Emerging Players: The price-point gap between TLC cloud volumes and SLC automotive premiums creates white-space opportunity for mid-tier QLC controllers with extended endurance firmware. Target India's greenfield data center buildout under the Digital Personal Data Protection Act, where legacy migration burden is absent. Pursue joint verification laboratory partnerships with domestic firmware signing capabilities to satisfy MIIT cybersecurity review timelines in China. For Investors and Strategic Acquirers: Consolidation pressure builds where controller firmware expertise concentrates among Seoul-based vendors and independent system integrators lack zone state machine optimization capabilities. Long-term viability favors vertically integrated semiconductor conglomerates with captive wafer output over fabless controller specialists exposed to NAND price cycles. Monitor NVMe specification harmonization progress as inflection indicator for hardware validation cost trajectories across multi-generational data center refresh programs.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Lifecycle Unbundling | Hyperscale cloud operators now demand decade-long security patch commitments separate from hardware acquisition. |
| Zone State Machine Optimization | Kernel-level driver development expertise concentrates competitive advantage among Seoul-based controller vendors. |
| Computational Storage Convergence | Near-data processing engines collapsing storage-network-compute boundaries enable query-offload for edge analytics. |
| Domestic Verification Laboratory Partnership | Joint facilities in Shanghai and Shenzhen accelerate MIIT cybersecurity review timelines for imported controllers. |
| REACH Fluoropolymer Substitution | European environmental compliance pressures reward early movers with preferred supplier status in German automotive. |
Research Methodology
Bottom-up data center and automotive deployment modeling reconciled against top-down 3D NAND wafer output tracking forms the analytical core. Primary interviews with hyperscale storage architects, automotive Tier 1 supplier procurement leads, controller firmware engineers, and cloud infrastructure capex planners combined with secondary validation from SEC hyperscaler filings, MIIT cybersecurity review disclosures, NVMe specification documentation, and EU AI Act implementation guidance. Triangulation against customs trade data for NAND controller imports and BIS certification registries in India completes the supply-side reconciliation.
Historical trendline analysis of cell density migration patterns from SLC through QLC anchors the projection framework. Segmentation dimensions modeled include cell type tier, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs derive from unit shipment trajectories weighted by average selling price evolution across the analysis window. Forecast inputs incorporate AI training cluster storage density requirements and autonomous vehicle sensor fusion logging mandates under ISO 26262 frameworks.
Caveats apply where MIIT cybersecurity review timeline extensions, EU AI Act auditability requirement refinements, or 3D NAND layer transition yield disruptions could materially shift the outlook. Forecasts reflect assumptions regarding zone capacity specification stabilization in NVMe protocol revisions and QLC endurance firmware advancement rates. Periodic stress-testing of base assumptions against hyperscale procurement contract renegotiation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
OTG Pen Drive Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
AI Powered Storage Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
NOR Flash Market
Data Storage
Transparent Cache Market
Data Storage
Storage Virtualization Market
Data Storage
Distributed Storage System Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Hardware Storage Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Solid State Array Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
APAC SSD Caching Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Next Generation Data Storage Market