
 Point-To-Point Antenna Market | 2026-2036
Point-To-Point Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Point-To-Point Antenna Market Analysis
Composite substrates are replacing traditional aluminum reflectors in parabolic antenna construction and is expanding design flexibility for millimeter-wave frequencies. CommScope leverages captive material science programs to control dielectric supply chains for these next-generation substrates. Cambium Networks anchors its competitive stance through integrated radio-and-antenna platforms purpose-built for unlicensed spectrum bands. Ericsson dominates microwave backhaul tenders across European mobile operators with compact all-outdoor transceiver designs.
A point-to-point antenna transmits focused radio-frequency energy between two fixed stations across line-of-sight paths, typically operating between 6 GHz and 80 GHz with gain specifications exceeding 30 dBi for long-haul links. These systems serve as critical backhaul infrastructure for cellular networks, enterprise connectivity, and broadcast distribution where fiber deployment proves uneconomical. Parabolic configurations retain the largest installed base due to proven reliability in rain-fade conditions, though panel antennas gain traction in urban 5G small-cell densification where wind loading and aesthetic constraints matter. Microwave technology still carries the majority of active links, but millimeter-wave segments attract disproportionate R&D investment as E-band and V-band spectrum opens for multi-gigabit throughput.
FCC Part 101 rules govern licensed microwave operations in the United States, while ETSI EN 302 217 harmonizes equipment standards across European Union member states; both frameworks increasingly mandate higher spectral efficiency and smaller channel spacing that force hardware upgrades. India's WPC (Wireless Planning and Coordination) wing imposes strict type-approval requirements on imported antenna systems, creating compliance barriers that favor local manufacturing partnerships. Stakeholders must monitor spectrum auction timelines and equipment authorization rulemakings across their target geographies to align product roadmaps with regulatory windows.
Market Dynamics
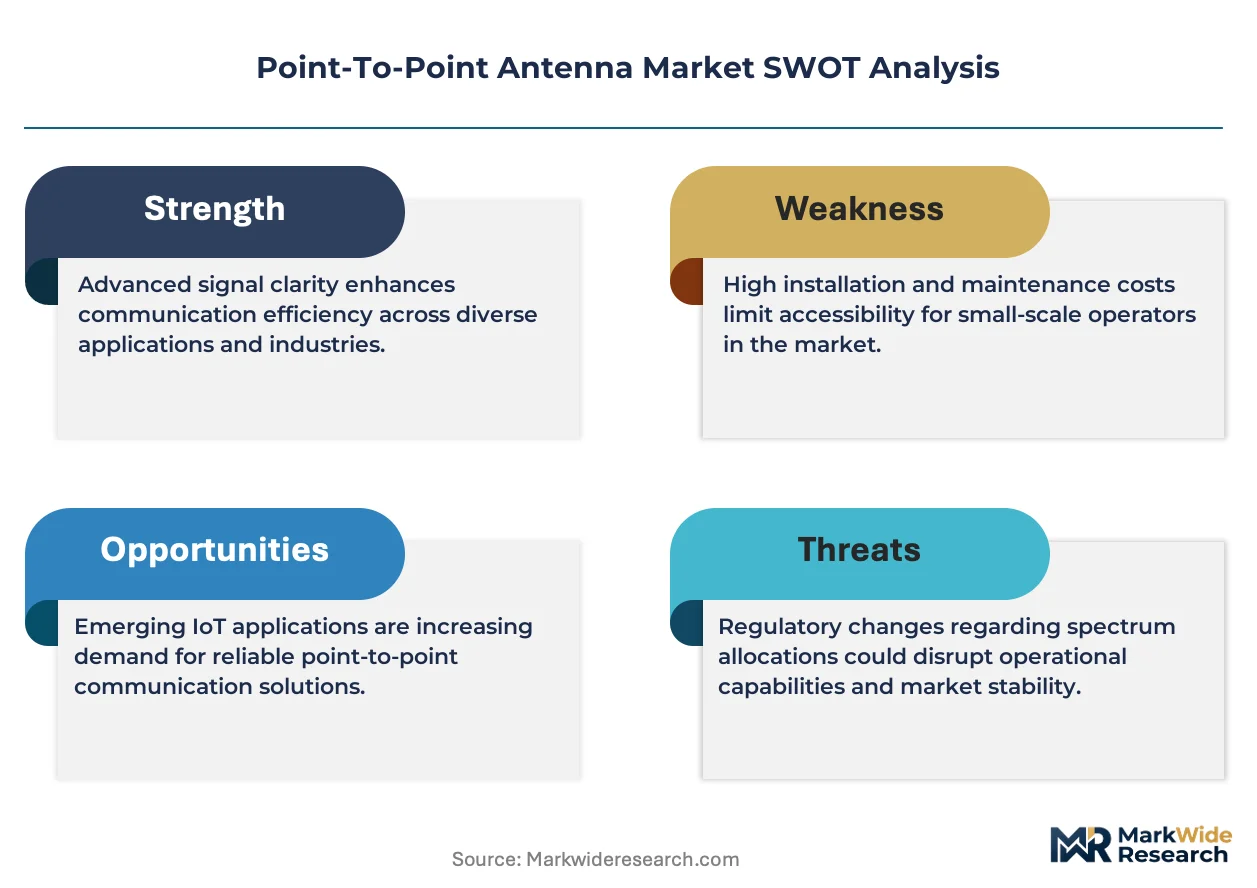
Spectrum reallocation mandates across multiple jurisdictions are forcing synchronized hardware refresh cycles, compressing replacement timelines from typical seven-year cycles to three-to-four-year intervals as operators race to meet band-clearing deadlines.
Growth Catalysts
- E-band spectrum liberalization:Regulators in Germany and India have opened 71-76 GHz and 81-86 GHz bands for commercial backhaul, enabling multi-gigabit rural connectivity where fiber deployment remains uneconomical.
- 5G network densification:Mobile operators require high-capacity microwave and millimeter-wave links to connect small-cell clusters in urban corridors, with procurement volumes concentrating in Indian metropolitan zones.
- Composite substrate maturation:Dielectric materials with tunable thermal properties are replacing aluminum reflectors, allowing manufacturers to achieve tighter beam patterns at frequencies above 60 GHz.
Market Restraints
- Copper and rare-earth price volatility:Feedhorn assemblies and waveguide components depend on copper and gallium arsenide substrates, with spot-price swings compressing gross margins for antenna fabricators.
- Indian import licensing friction:WPC type-approval requirements create six-to-nine-month certification delays for foreign equipment vendors, favoring domestic manufacturing partnerships but constraining supply elasticity.
- Fiber substitution in dense urban cores:Municipal fiber-overbuilds in Seoul, Tokyo, and Singapore are displacing microwave backhaul for last-mile enterprise connectivity below one kilometer.
Strategic Opportunities
- Unlicensed 60 GHz whitespace:Enterprises in Brazil and Indonesia are deploying multi-gigabit fixed wireless for campus interconnect and industrial automation, bypassing carrier infrastructure entirely.
- Integrated radio-antenna platforms:Convergence of transceiver electronics with planar antenna arrays reduces installation complexity and tower loading, opening opportunities in wind-constrained European urban sites.
- US IRA broadband equity provisions:Federal infrastructure funding prioritizes rural connectivity deployments, creating subsidized demand for long-haul microwave links in underserved Appalachian and Great Plains corridors.
Industry Challenges
- Millimeter-wave RF engineering scarcity:Design talent capable of optimizing E-band and V-band link budgets remains concentrated among a handful of specialized firms, constraining product development velocity.
- Legacy SDH/TDM integration complexity:Operators maintaining hybrid networks face interoperability headaches when interfacing new packet-native radios with existing synchronous infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-To-Point Antenna Market |
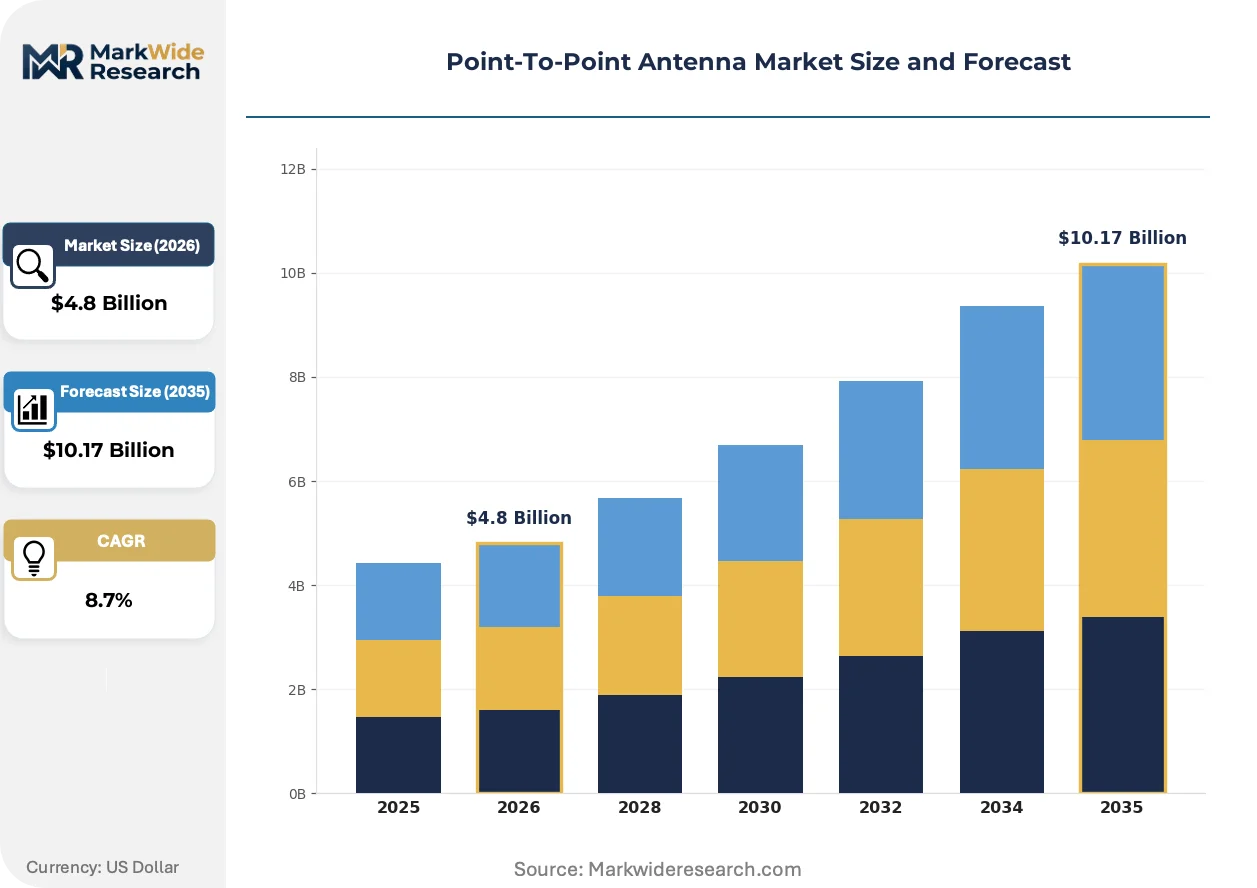
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic, Mesh, Panel, Dish Technology: Microwave, Laser, Millimeter Wave, Fiber Optic Installation Type: Fixed, Portable, Temporary, Permanent End User: Telecommunications, Government, Military, Broadcasting |
| Companies Covered | CommScope, Cambium Networks, Ericsson, Amphenol Corporation, Radio Frequency Systems, Tongyu Communication, Infinite Electronics, Ceragon Networks, Aviat Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-To-Point Antenna Market Emerging Trajectories
Hardware architectures are converging around software-defined radio principles, with analog front-ends giving way to digitized intermediate-frequency stages that permit field-upgradable modulation schemes without truck rolls.
Phased-array panel antennas with electronically steerable beams are electrifying deployment economics for 5G small-cell backhaul. Urban operators in Seoul and Singapore are adopting these systems to eliminate mechanical azimuth adjustments during network optimization. The technology is electrifying competitive dynamics by collapsing installation timelines from days to hours and reducing skilled-labor dependencies.
FCC Part 101 rulemakings are mandating 256-QAM modulation and 28 MHz channel spacing minimums for new licensed microwave authorizations. Equipment vendors must redesign filter banks and power amplifiers to meet tightened spectral efficiency thresholds. Long-haul transport links above 10 kilometers face the steepest compliance burdens, with rural US carriers accelerating procurement of next-generation transceivers ahead of grandfathering deadlines.
Carrier procurement departments are unbundling antenna supply from radio contracts, creating direct vendor relationships previously intermediated by system integrators. European mobile operators pioneered this shift during 2020-2022 cost restructuring, with Indian and Brazilian carriers now adopting similar direct-sourcing frameworks. The practice is most pronounced in high-volume microwave deployments where antenna standardization across multiple radio platforms yields procurement leverage.
Point-To-Point Antenna Market Segmentation
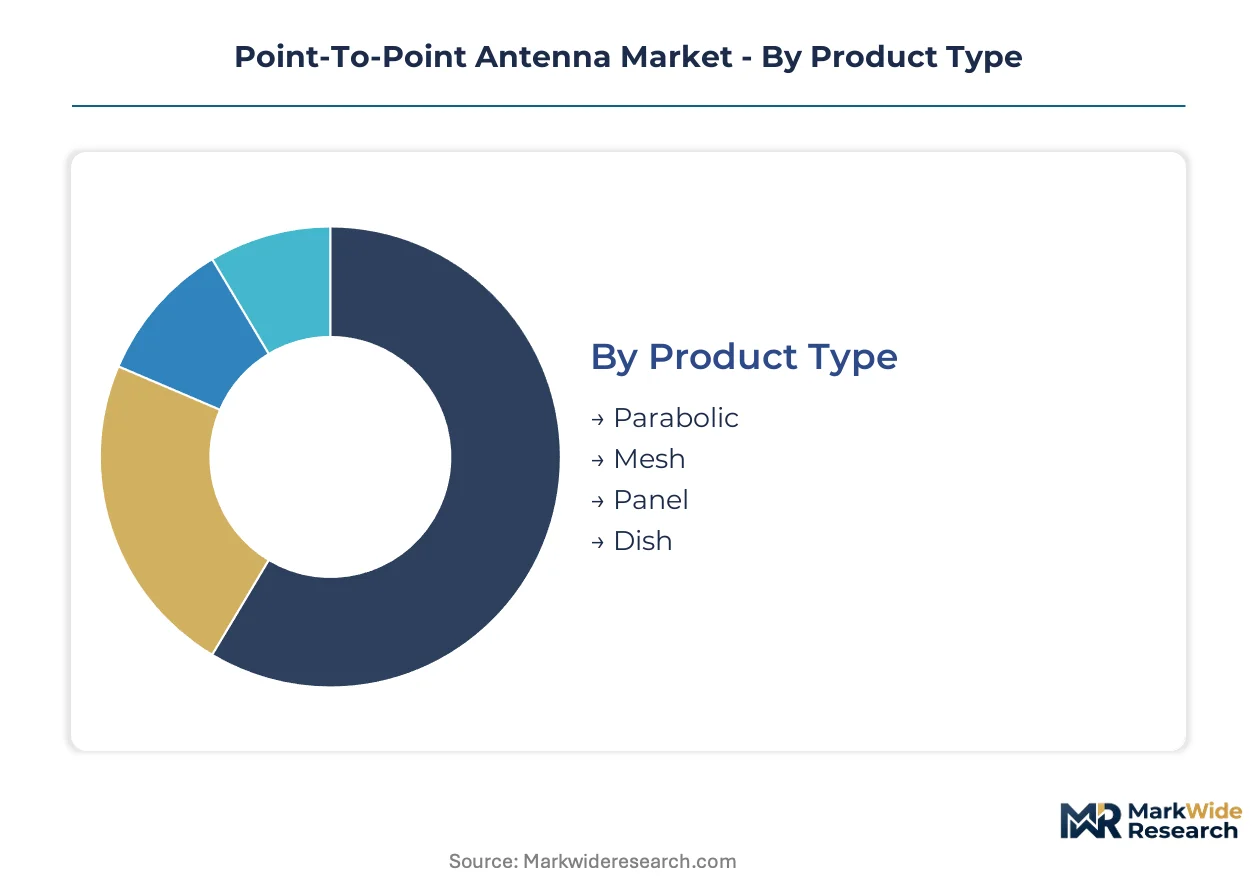
Segmentation in the point-to-point antenna market reveals how procurement patterns split between legacy infrastructure refresh and greenfield 5G deployment. Product architecture, spectrum technology, installation constraints, and end-user security requirements each create distinct competitive arenas with divergent margin profiles and vendor qualification barriers.
Product Type:
Standalone parabolic systems dominate long-haul backhaul, while panel antennas embed directly into integrated small-cell enclosures for urban densification.
- Parabolic:Aluminum or composite reflector dishes exceeding 30 dBi gain serve licensed microwave links above 10 kilometers. Rural Indian carriers deploy these for BharatNet backhaul where terrain blocks fiber routes.
- Panel:Flat planar arrays with phased-array beam steering mount on street furniture and building facades. Seoul and Singapore operators favor these for 5G small-cell interconnection where wind loading limits parabolic size.
- Mesh:Lightweight perforated reflectors reduce wind resistance on tower structures. Broadcast relay networks in Germany use mesh configurations for temporary event coverage.
- Dish:Compact solid-surface antennas under 60 centimeters target enterprise campus links. Brazilian fixed-wireless providers deploy dish antennas for unlicensed 60 GHz campus interconnect.
Volume placements concentrate in Parabolic; the faster expansion belongs to Panel.
Technology:
Cost tiers separate mature microwave infrastructure from emerging millimeter-wave platforms requiring premium RF engineering.
- Microwave:Conventional 6-42 GHz radios with proven rain-fade tolerance carry the majority of active links. Indian mobile operators procure microwave systems for suburban 5G backhaul where spectrum licensing remains economical.
- Millimeter Wave:E-band and V-band systems operating 71-86 GHz deliver multi-gigabit throughput in compact footprints. German regulators opened these bands for rural connectivity, accelerating R&D investment in dielectric substrate optimization.
- Laser:Free-space optical links provide interference-immune connectivity across short distances. Military installations in classified locations deploy laser systems for electromagnetic-spectrum denial environments.
- Fiber Optic:Hybrid radio-fiber convergence platforms integrate optical transport with wireless last-mile extension. US rural broadband equity programs subsidize these for Appalachian corridor deployments where full fiber trenching proves uneconomical.
Procurement volume tilts toward Microwave; Millimeter Wave claims the steepest expansion trajectory.
Installation Type:
Application context determines whether antennas deploy as permanent infrastructure or rapid-response assets.
- Fixed:Hardened outdoor units with 15-year design life anchor carrier backhaul networks. European mobile operators specify fixed installations for licensed microwave links with stringent availability SLAs.
- Permanent:Concrete-pad or tower-mounted systems with integrated lightning protection serve broadcast distribution. Government agencies in India mandate permanent installations for national network resilience.
- Portable:Rapid-deploy kits with collapsible mounts target emergency response and military field operations. Disaster relief agencies in Indonesia stock portable microwave units for post-typhoon connectivity restoration.
- Temporary:Rental-grade equipment for events, construction sites, and seasonal demand spikes. Brazilian mining operations lease temporary links for remote exploration camps.
Fixed installations capture the largest deployment base; Portable systems are climbing the fastest as defense and emergency budgets expand.
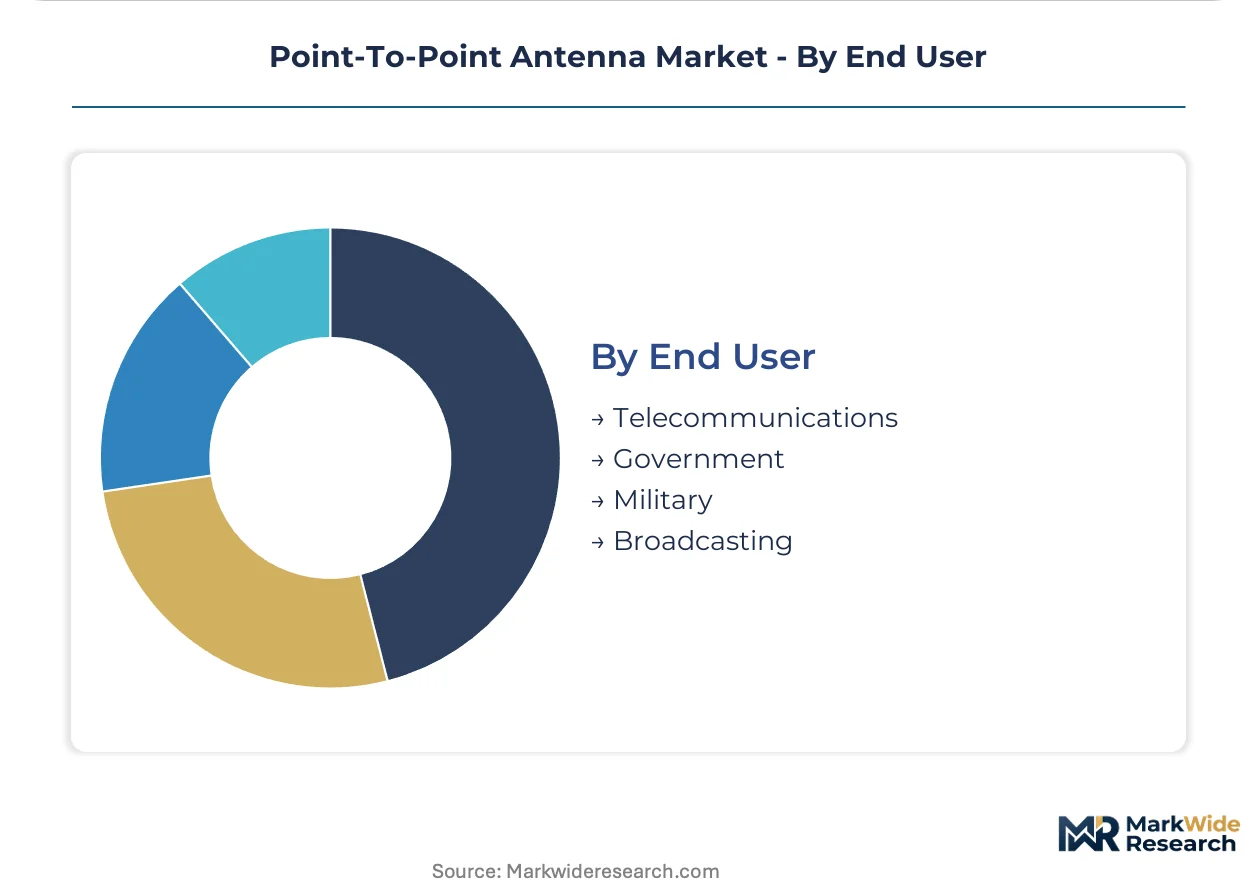
End User:
Customer type dictates security certification depth, procurement channel structure, and payment term expectations.
- Telecommunications:Mobile operators and fixed-wireless carriers purchasing through direct vendor relationships or systems integrators. Indian carriers now unbundle antenna procurement from radio contracts to standardize across multiple platform vendors.
- Government:Civil agencies requiring type-approved equipment with domestic content preferences. US IRA broadband equity provisions channel federal funding toward rural connectivity deployments in underserved corridors.
- Military:Defense departments with classified specifications and anti-jamming requirements. NATO procurement frameworks favor vendors with in-country security clearances.
- Broadcasting:Television and radio networks needing high-availability contribution links. German public broadcasters maintain extensive microwave relay networks for regional program distribution.
Telecommunications generates the highest absolute volume; Government segment gains share fastest on infrastructure stimulus programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Germany concentrate point-to-point antenna manufacturing and testing facilities, driven by rural broadband mandates and spectrum reallocation deadlines. Tax incentives in these zones accelerate hardware refresh cycles for telecommunications carriers.
United States
FCC Part 101 rulemakings mandate 256-QAM modulation and tighter channel spacing for licensed microwave authorizations. The IRA broadband equity provisions channel federal funding toward rural connectivity in Appalachian and Great Plains corridors. Tower manufacturers in Texas and Arizona report accelerated procurement of next-generation transceivers ahead of grandfathering deadlines.
Germany
ETSI EN 302 217 harmonization drives equipment standardization across EU member states with escalating spectral efficiency requirements. Regulators opened 71-76 GHz and 81-86 GHz E-band spectrum for commercial backhaul, enabling multi-gigabit rural connectivity. Industrial clusters in Bavaria specialize in dielectric substrate optimization for millimeter-wave frequencies above 60 GHz.
India
BharatNet rural broadband initiatives and 5G network densification programs concentrate procurement volumes in metropolitan zones. WPC type-approval requirements impose six-to-nine-month certification delays on imported equipment, favoring domestic manufacturing partnerships. Tamil Nadu and Karnataka host antenna fabrication facilities serving carrier unbundling of antenna supply from radio contracts.
China
MIIT spectrum coordination supports millimeter-wave R&D investment as E-band and V-band channels open for multi-gigabit throughput. GB standards for microwave equipment align with international frameworks while prioritizing domestic supply chain security. Yangtze River Delta manufacturing bases produce composite substrates replacing aluminum reflectors in parabolic antenna construction.
Brazil
Unlicensed 60 GHz whitespace deployment accelerates for campus interconnect and industrial automation applications. ANVISA equipment certification frameworks govern imported telecommunications hardware with type-approval requirements. São Paulo-based fixed-wireless providers deploy dish antennas for enterprise connectivity, bypassing carrier infrastructure entirely.
Point-To-Point Antenna Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated radio-antenna platforms commanding premium positioning in urban densification projects while standalone parabolic suppliers compete on volume in rural backhaul. The vendor base organizes into three tiers: captive material science programs controlling dielectric supply chains, integrated platform vendors purpose-built for unlicensed spectrum, and compact all-outdoor transceiver specialists. Consolidation pressures favor M&A activity among microwave subsystem providers and strategic partnerships for WPC type-approval navigation in India.
Among North American-headquartered incumbents, CommScope and Cambium Networks occupy distinct archetype positions. CommScope exemplifies the captive supply chain model through in-house material science programs. Cambium Networks represents the integrated platform specialist tier with radio-antenna convergence. Ericsson anchors European competitive dynamics through compact transceiver designs. These three collectively illustrate how geographic origin and corporate structure map to strategic positioning across spectrum licensing regimes.
| Leading Market Players |
|---|
| CommScope |
| Cambium Networks |
| Ericsson |
| Amphenol Corporation |
| Radio Frequency Systems |
| Tongyu Communication |
| Infinite Electronics |
| Ceragon Networks |
| Aviat Networks |
| Others |
Supply Flow & Price Mechanics
Composite substrate maturation in parabolic antenna manufacturing simultaneously compresses material costs and concentrates dielectric supply chains among vendors with captive material science programs. This production-method transition forces tiered pricing stratification across aluminum-reflector legacy systems and next-generation composite platforms.
Pricing Analysis
Volume placements in parabolic systems run on thin margins, while panel antennas with phased-array beam steering command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates E-band millimeter-wave platforms from conventional microwave links and unlicensed 60 GHz campus equipment. Price differentiation hinges on certification grade for WPC type-approval in India and spectral efficiency compliance under FCC Part 101 rules. Cost compression in standard-tier microwave hardware is intensifying because copper and gallium arsenide spot-price volatility feeds directly into feedhorn assembly economics. Government procurement under US IRA broadband equity provisions shows lowest price sensitivity; Brazilian fixed-wireless providers operating in unlicensed whitespace exhibit highest elasticity.
Supply Chain Analysis
Freight costs for oversized parabolic reflectors and tower-mounted assemblies constrain sourcing radius, favoring regional fabrication hubs over intercontinental shipment. Dielectric substrate production concentrates in China, Germany, and the United States, with Yangtze River Delta and Bavarian industrial clusters feeding millimeter-wave antenna programs. Feedhorn assemblies draw from copper suppliers in Chile and rare-earth processors in China, creating tariff exposure at multiple nodes. Distribution runs through direct vendor relationships with telecommunications carriers, bypassing systems integrators as Indian and European operators unbundle antenna procurement from radio contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point-to-point antenna market functions as a vertical-integration race where control over dielectric substrate supply chains determines margin capture in millimeter-wave segments. Players are pursuing backward integration into composite material production to escape aluminum-reflector commoditization.
For Market Incumbents: Acquire dielectric substrate fabrication capabilities to secure supply for E-band and V-band antenna programs. Incumbent vendors face displacement from integrated radio-antenna platforms purpose-built for unlicensed spectrum; defensive consolidation through microwave subsystem provider M&A preserves procurement relationships with European mobile operators. Capacity addition in Tamil Nadu and Karnataka antenna fabrication facilities navigates WPC type-approval barriers while serving carrier unbundling trends. For New Entrants and Emerging Players: Phased-array panel antennas with electronically steerable beams offer technology-first entry into urban 5G small-cell densification where wind loading constraints favor compact form factors. White-space targets concentrate in Brazilian unlicensed 60 GHz campus interconnect and Indonesian industrial automation corridors. Go-to-market positioning as direct antenna suppliers to carriers adopting unbundled procurement frameworks bypasses entrenched systems integrator relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to communications infrastructure conglomerates seeking millimeter-wave RF engineering talent pools. Long-term viability over the projection horizon favors vendors with demonstrated WPC type-approval navigation and captive composite substrate programs. Acquisition target archetype: mid-cap specialists with in-country security clearances for NATO defense procurement. Signal to watch: spectrum auction timelines in India and Germany that trigger synchronized hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Substrates | Captive supply of composite materials insulates margin from copper price volatility under FCC Part 101 compliance mandates. |
| WPC Type-Approval Partnership Formation | Domestic manufacturing alliances in Tamil Nadu bypass six-to-nine-month certification delays for Indian carrier procurement. |
| Integrated Radio-Antenna Platform Launch | Converged transceiver-electronics designs reduce tower loading for Seoul and Singapore urban densification deployments. |
| E-Band Spectral Efficiency R&D Investment | 256-QAM modulation capability secures licensed microwave authorizations ahead of grandfathering deadlines under tightened channel spacing rules. |
| Direct Carrier Procurement Channel Development | Unbundled antenna supply relationships with Indian and European operators displace systems integrator intermediation. |
Methodological Framework
Document review covered FCC Part 101 rulemakings, ETSI EN 302 217 harmonization frameworks, and WPC type-approval requirements, complemented by interviews with RF engineering directors at telecommunications carriers, procurement leads at European mobile operators, composite substrate material scientists, tower manufacturers in Texas and Arizona, and regulatory affairs specialists navigating Indian import licensing. Secondary validation drew from spectrum auction databases, customs records for antenna imports, SEC filings of listed communications infrastructure vendors, and carrier capex disclosure documents. Bottom-up unit economics for parabolic and panel antenna configurations were triangulated against top-down market sizing from infrastructure deployment pipelines.
Cross-referencing historical procurement patterns from BharatNet rural broadband initiatives and 5G densification programs against expert panel input on millimeter-wave R&D trajectories anchored the analytical framework. Segmentation dimensions modeled encompass product architecture, spectrum technology, installation type, and end-user security requirements across the projection horizon. CAGRs were derived from installed base refresh cycles compressed by spectrum reallocation mandates and greenfield deployment curves for E-band rural connectivity. Industry-specific forecast inputs included WPC certification queue lengths and composite substrate yield rates at Yangtze River Delta manufacturing bases.
Several conditions sit outside the modeled scope, including military classified procurement volumes, free-space optical link deployments in electromagnetic-spectrum denial environments, and potential fiber-overbuild substitution in dense Asian urban cores. Forecasts reflect documented assumptions regarding regulatory grandfathering timelines and material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market