
 Data Preparation Tools Market | 2026-2036
Data Preparation Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Preparation Tools Market Intelligence
The EU's General Data Protection Regulation (GDPR) is expanding the compliance burden for data governance, creating new demand for auditable data preparation workflows. Informatica Corporation leverages its established enterprise data management footprint to serve large-scale deployments. Microsoft Corporation integrates its data preparation capabilities within the broader Azure and Power BI ecosystems. This strategy targets a wide user base from individual analysts to enterprise IT.
Data preparation tools encompass a suite of software designed to discover, clean, transform, and structure raw data into a usable format for analysis. These tools automate processes like handling missing values and standardizing formats, which are essential for feeding business intelligence models. Cloud-based deployment models are outpacing on-premises solutions due to scalability. Within product types, data wrangling and data cleansing represent foundational capabilities, while metadata management is a key differentiator.
Frameworks like the EU's GDPR and the California Consumer Privacy Act (CCPA) mandate stringent data handling protocols, directly influencing tool selection. ISO/IEC 27001 standards for information security management push organizations toward tools that can demonstrate data lineage and control. Vendor selection increasingly hinges on a platform's ability to automate compliance reporting and manage data access policies across hybrid environments.
Market Dynamics
The market's central dynamic is the tension between the accelerating demand for AI-driven analytics and the increasing stringency of data governance mandates. This dual pressure forces organizations to seek tools that not only streamline data structuring for machine learning models but also provide auditable compliance with regulations like GDPR.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU's GDPR and the CCPA in California create a compliance-driven need for tools that can demonstrate data lineage and control, making auditable data preparation a necessity for enterprises.
- Financial Services Adoption:Demand from banks and financial institutions for sophisticated risk analysis, algorithmic trading, and real-time fraud detection requires high-quality, structured data inputs, serving as a primary market accelerant.
- Generative AI Proliferation:The rise of large language models and other generative AI applications necessitates the processing of vast, diverse datasets, creating new demand for powerful tools to clean and structure training data at scale.
Market Restraints
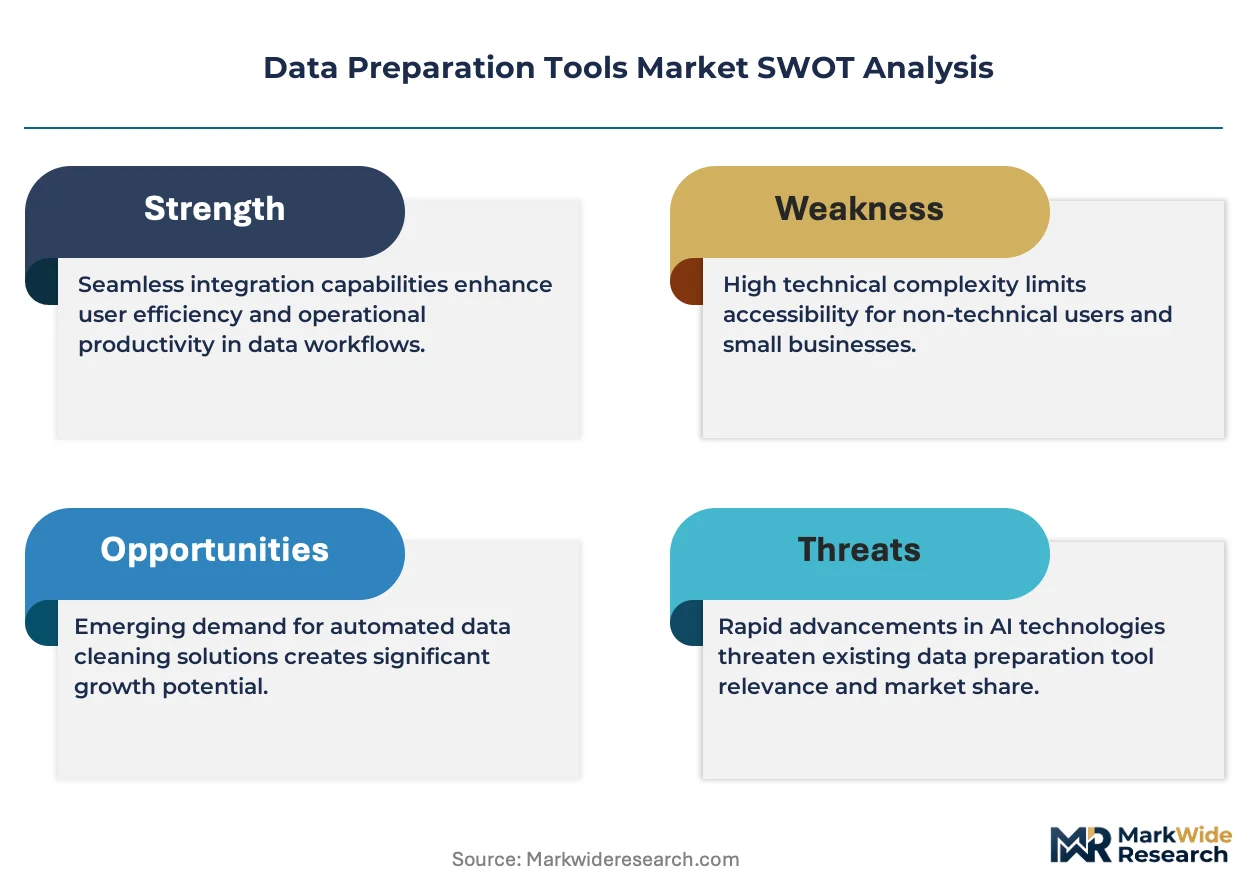
- Legacy System Integration:The technical difficulty and high cost of integrating modern data preparation tools with entrenched legacy IT systems, particularly within established sectors like banking and insurance, slow down adoption cycles.
- Open-Source Alternatives:The widespread availability and power of open-source libraries, such as Python's Pandas and Dask, present a significant substitution threat, especially for cost-sensitive organizations and highly skilled data science teams.
- Talent Scarcity:A persistent shortage of data engineers and data scientists with the specialized skills to effectively deploy and manage sophisticated data preparation platforms acts as a structural bottleneck to market expansion.
Strategic Opportunities
- Embedded Analytics in Healthcare:Integrating data preparation tools directly into electronic health record (EHR) systems and clinical trial management platforms offers a significant opportunity to improve clinical outcomes and research efficiency.
- Convergence with MLOps:The fusion of data preparation capabilities with Machine Learning Operations (MLOps) platforms creates a new product category for end-to-end AI lifecycle management, from raw data to model deployment.
- Geographic Expansion in India:With its rapidly digitizing economy and burgeoning tech sector, India represents an underpenetrated market where demand for data preparation tools to support local analytics initiatives is set to grow.
Industry Challenges
- Hybrid Cloud Complexity:Managing data governance, security, and lineage consistently across disparate on-premises, private cloud, and public cloud environments poses a major operational challenge for enterprise IT departments.
- Data Interoperability Standards:The absence of universally adopted standards for metadata and data format exchange between different vendor tools leads to data silos and complicates the creation of a unified data fabric.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Preparation Tools Market |
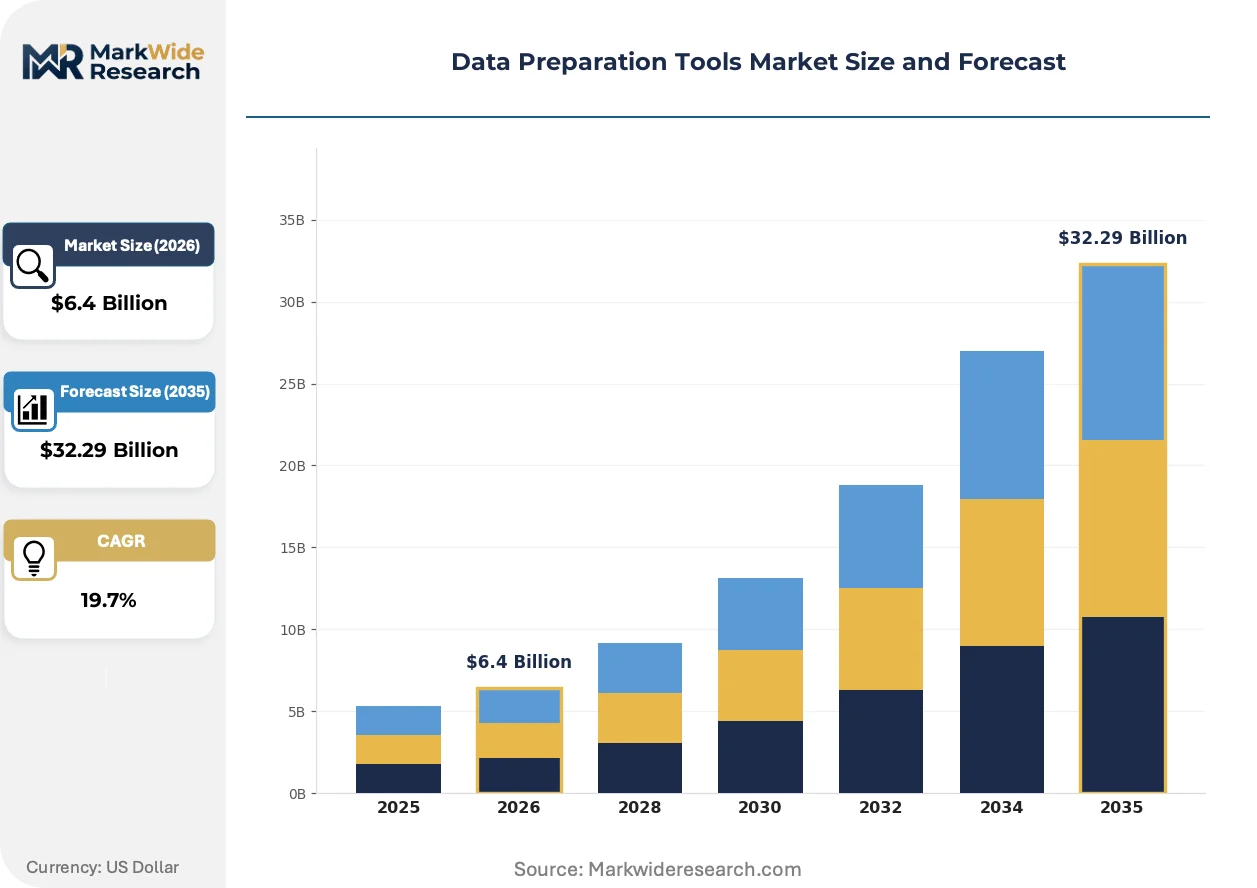
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $32.29 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Product Type: Data Integration, Data Wrangling, Data Cleansing, Data Transformation, Metadata Management Application: Business Intelligence, Customer Analytics, Risk Analysis, Fraud Detection, Marketing Analytics End User: Financial Institutions, IT Services, Manufacturing Firms, Telecommunications Providers, Government Agencies |
| Companies Covered | Alteryx, Inc., Informatica Corporation, International Business Machines Corporation, Microsoft Corporation, SAP SE, SAS Institute Inc., TIBCO Software Inc., Datawatch Corporation, QlikTech International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Preparation Tools Market Strategic Shifts & Innovations
The market is shifting from manual, code-dependent processes toward automated, AI-infused platforms. This evolution democratizes data preparation, enabling business users and analysts to perform tasks previously reserved for specialized data engineers and reducing the time to insight.
AI-augmented data preparation uses machine learning algorithms to automatically profile data, detect anomalies, and recommend transformations. Business analysts and citizen data scientists are the primary adopters, accelerating their analytic workflows. This technology is rewriting the traditional division of labor between central IT and business units, empowering departments to manage their own data pipelines.
The forthcoming EU AI Act establishes stringent requirements for data quality and bias mitigation in high-risk AI systems. This legislation compels companies in sectors like finance and human resources to rigorously document data provenance and processing steps. Consequently, demand is rising for data preparation platforms that feature automated audit trails and robust data governance capabilities.
A notable demand-side shift involves the preference for data preparation features embedded within broader business intelligence and cloud data platforms. This disrupts the market for standalone specialist tools, as enterprises consolidate vendors to streamline workflows within ecosystems like Azure Synapse or Google Cloud's BigQuery. This trend is most pronounced in North America, where platform-centric IT strategies are common.
Data Preparation Tools Market Segmentation
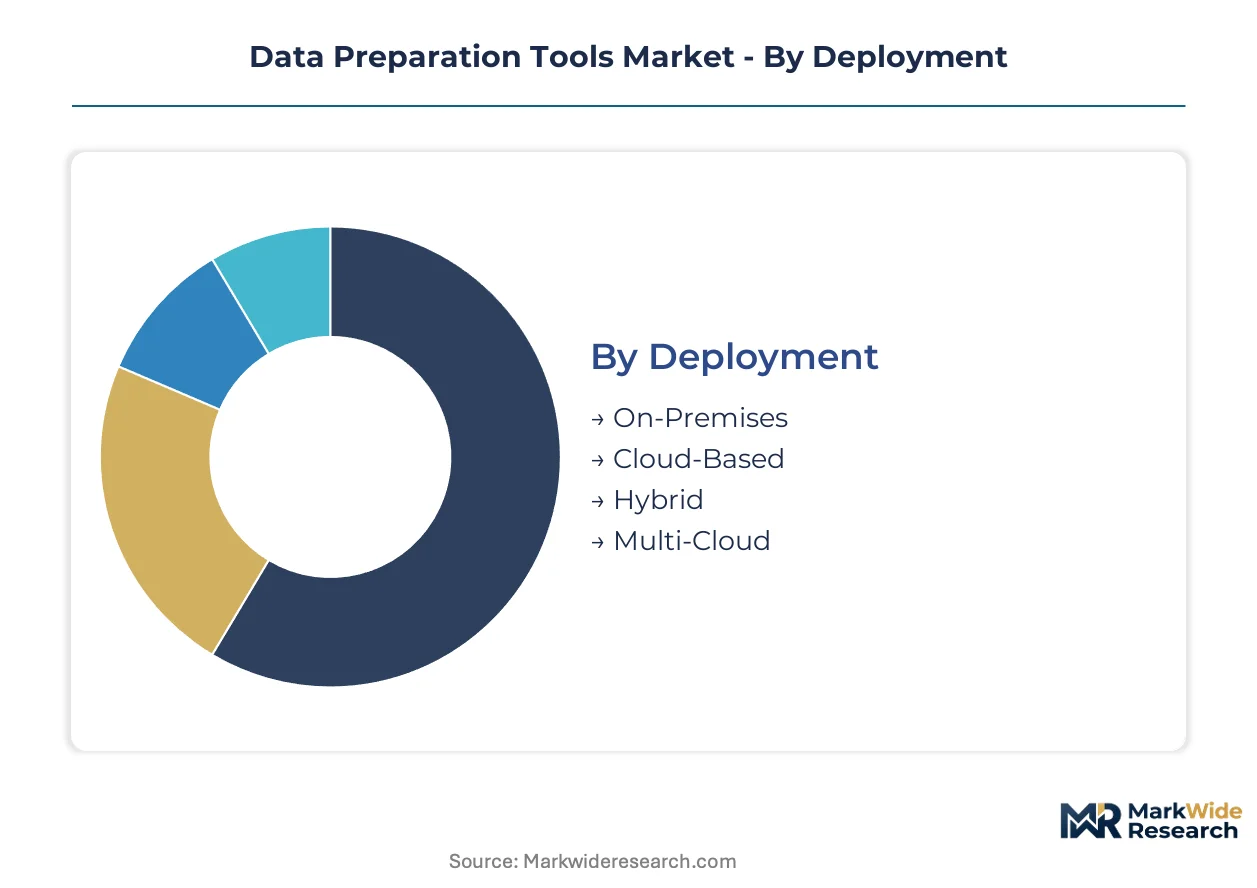
The Data Preparation Tools Market segmentation highlights diverse operational approaches and specific functional requirements across its user base. Understanding these distinct segments is crucial for identifying areas of concentrated demand and emerging technological preferences. This analysis reveals how different deployment models and product capabilities address varied industry needs.
Deployment:
The deployment landscape for data preparation tools reflects a spectrum from highly customized on-premises installations to standardized cloud-native solutions.
- On-Premises:These solutions are installed and operated within an organization's own infrastructure, offering maximum control and security for sensitive data. Organizations with legacy systems or strict data residency requirements often prefer this model.
- Cloud-Based:Delivered as a service over the internet, cloud-based tools offer scalability, reduced infrastructure costs, and faster deployment. Demand is concentrating in technology-forward economies like the United States and Germany, driven by agile development needs.
- Hybrid:This model combines on-premises and cloud environments, offering flexibility and addressing complex data governance needs.
- Multi-Cloud:Utilizing services from multiple cloud providers, multi-cloud deployments mitigate vendor lock-in and enhance resilience. This supports diversified data management across enterprise IT strategies.
Most installed capacity flows through On-Premises deployments. Expansion is steepest in Cloud-Based solutions.
Product Type:
Product types range from foundational capabilities to advanced governance features, indicating varying levels of market maturity.
- Data Integration:These tools connect disparate data sources, consolidating information for unified analysis. They are essential for creating a cohesive data fabric across complex enterprise systems.
- Data Wrangling:This capability structures raw, messy data into a usable format, often involving parsing and reshaping. Business analysts widely adopt these tools to accelerate analytic workflows.
- Data Cleansing:These tools focus on error detection and correction, identifying and fixing inconsistencies or missing values.
- Data Transformation:These tools convert data from one format to another, optimizing it for specific analytical tasks. They are critical for feeding business intelligence models.
- Metadata Management:This segment involves cataloging, classifying, and tracking data assets, including their lineage and access policies. The EU AI Act compels companies to document data provenance, driving demand for this capability.
Data wrangling and cleansing remain core functionalities. Metadata management is gaining significant strategic importance for enterprises.
Application:
Applications for data preparation tools span from core operational reporting to high-impact strategic decision-making.
- Business Intelligence:This application prepares data for dashboards, reports, and analytical queries, supporting operational insights. It empowers individual analysts to manage data pipelines effectively.
- Customer Analytics:Tools here structure customer interaction data to reveal purchasing patterns and preferences. This improves personalization and targeted engagement strategies.
- Risk Analysis:Within financial institutions, data preparation for risk analysis aggregates complex datasets to assess credit, market, and operational risk. Regulatory mandates like GDPR expand the compliance burden.
- Fraud Detection:This application relies on high-quality, structured data for real-time anomaly detection and pattern recognition in transactional data. Financial institutions require this for protecting assets and maintaining trust.
- Marketing Analytics:Data preparation for marketing optimizes campaign performance and audience segmentation. It supports data-driven decision-making in competitive markets.
Financial services applications like risk analysis and fraud detection are primary accelerants. Business intelligence remains a foundational use case for data preparation.
End User:
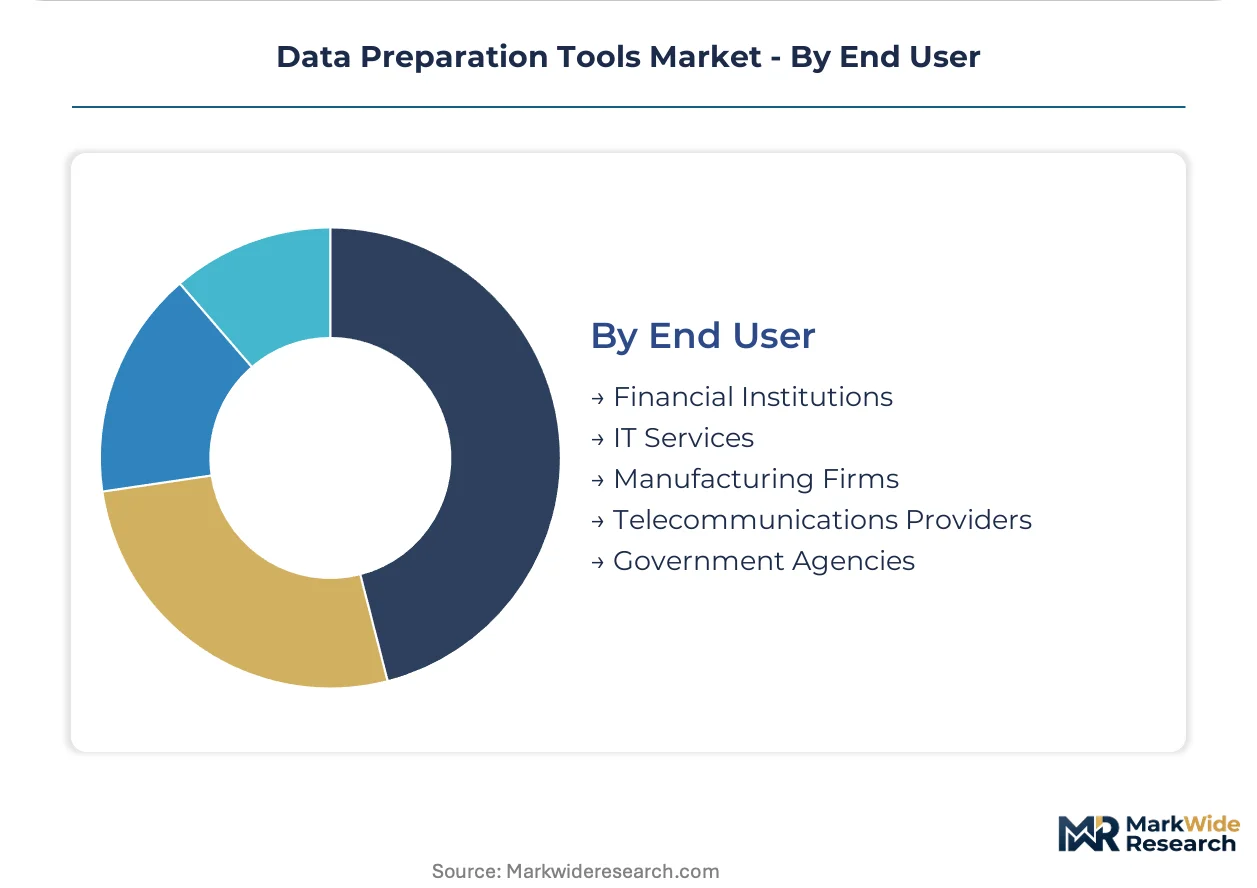
End-user segments are differentiated by their data intensity and regulatory compliance requirements.
- Financial Institutions:This segment utilizes data preparation for critical functions like risk analysis, algorithmic trading, and real-time fraud detection. Mandates from GDPR and CCPA necessitate auditable data workflows within these organizations.
- IT Services:Firms in this segment deploy data preparation tools to manage diverse client data, support cloud migrations, and integrate solutions across hybrid environments. These platforms enable broad enterprise deployments.
- Manufacturing Firms:These companies use data preparation for optimizing supply chains, predictive maintenance, and quality control. Structured data improves operational efficiency.
- Telecommunications Providers:Data preparation here supports network optimization, customer churn prediction, and service personalization. Managing vast datasets is critical for competitive advantage.
- Government Agencies:Public sector entities require data preparation for demographic analysis, public service delivery, and compliance reporting. Data lineage is vital for accountability.
Financial institutions represent a significant demand cluster due to stringent data requirements. IT services firms are expanding their adoption to support diverse client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant concentration of data scientists and engineers anchors the demand for sophisticated data preparation tools across leading global economies. These skilled workforces drive innovation and deployment of advanced analytics platforms. Organizations seek solutions that can handle complex data environments with increasing regulatory scrutiny.
United States
The United States sees strong demand for data preparation tools driven by its robust financial services sector and technology innovation hubs. Financial institutions require high-quality data for risk analysis and fraud detection. The California Consumer Privacy Act (CCPA) mandates stringent data handling protocols, influencing tool selection. Major tech clusters in Silicon Valley and Boston are at the forefront of adopting AI-driven data preparation solutions.
Germany
Germany's advanced manufacturing and automotive industries generate substantial demand for data preparation to optimize operational efficiency and predictive maintenance. The EU's General Data Protection Regulation (GDPR) expands the compliance burden for data governance. Industrial centers in Bavaria and North Rhine-Westphalia are actively integrating these tools into their Industry 4.0 initiatives to manage complex sensor data.
Japan
Japanese enterprises prioritize data preparation for industrial automation and precision manufacturing, aiming to enhance product quality and supply chain resilience. The Ministry of Economy, Trade and Industry (METI) promotes digital transformation across various sectors. Technology hubs in Tokyo and Osaka are driving the adoption of AI-augmented data preparation for advanced analytics and machine learning model training.
India
India's rapidly digitizing economy and burgeoning tech sector represent a significant underpenetrated market for data preparation tools, supporting local analytics initiatives. Government programs like the Production-Linked Incentive (PLI) scheme encourage domestic manufacturing, increasing data generation. Major IT services and software development centers in Bengaluru and Hyderabad are expanding their use of data preparation for diverse client needs.
United Kingdom
The United Kingdom's strong financial services sector and growing AI research capabilities fuel demand for data preparation tools, particularly for risk analysis and regulatory compliance. The UK's data protection laws, aligned with GDPR principles, necessitate auditable data workflows. London's financial district and the Cambridge technology cluster actively integrate advanced data preparation into their strategic decision-making processes.
Data Preparation Tools Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the data preparation tools market. This competitive dynamic creates a tiered structure, with large technology providers offering integrated platforms and niche vendors delivering specialized capabilities. Strategic archetypes include ecosystem integrators, data governance experts, and agile data wrangling providers. Dominant competitive moves involve portfolio diversification and strategic partnerships to extend market reach.
Among large enterprise solution providers, Microsoft Corporation and Informatica Corporation exemplify the trend towards integrated data management ecosystems, offering comprehensive capabilities from data ingestion to advanced analytics. Microsoft leverages its extensive Azure cloud infrastructure and Power BI platforms to target a broad user base, from individual analysts to enterprise IT departments. Informatica Corporation, with its established enterprise data management footprint, focuses on large-scale deployments, particularly in regulated industries requiring robust data governance. Alteryx, Inc. sits within the specialized data science and analytics segment, anchoring innovation in self-service data preparation capabilities for business users and citizen data scientists.
| Leading Market Players |
|---|
| Alteryx, Inc. |
| Informatica Corporation |
| International Business Machines Corporation |
| Microsoft Corporation |
| SAP SE |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Datawatch Corporation |
| QlikTech International AB |
| Others |
Cost & Logistics Intelligence
The increasing stringency of data governance mandates, such as the EU AI Act, forces providers to invest heavily in auditable data lineage features, directly impacting the pricing of compliant data preparation tools. This demand-side pressure elevates the value of platforms capable of automating regulatory reporting and managing complex data access policies.
Pricing Analysis
The market's bundled-vs-unbundled service split shapes pricing models, with comprehensive platforms offering subscription-based SaaS tiers and specialized tools often using project-based or per-feature licensing. Price differentiation stems from the level of AI augmentation, integration complexity with existing enterprise systems, and the robustness of data governance features. Pricing pressure arises from the widespread availability of powerful open-source alternatives, particularly for basic data wrangling. Large financial institutions and regulated enterprises exhibit lower price sensitivity for solutions guaranteeing compliance and security.
Supply Chain Analysis
Cloud marketplaces and direct enterprise sales channels dominate distribution for data preparation tools, facilitating rapid deployment and scalability. Supply concentration aligns with technology-forward economies like the United States, Germany, and Japan, which are centers for advanced analytics development. The supply chain relies heavily on a skilled workforce of data engineers and scientists, as well as robust cloud infrastructure services. Talent scarcity presents a structural supply chain risk, creating bottlenecks in tool adoption and implementation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Preparation Tools Market is evolving into a late-cycle quality story, driven by a pronounced demand-shift towards premium specifications for auditable data quality and compliance features.
For Market Incumbents: Hedge against the competitive threat from open-source alternatives by embedding advanced AI-augmented capabilities directly into core offerings. Consolidate disparate data preparation functionalities into comprehensive, integrated enterprise data management platforms to streamline customer workflows. Invest in R&D for automated compliance reporting, particularly for emerging regulations like the EU AI Act, to maintain a differentiated value proposition.
For New Entrants and Emerging Players: Launch specialized data preparation solutions via cloud marketplaces, targeting specific industry verticals with high compliance needs, such as healthcare EHR integration. Focus on providing end-to-end MLOps-integrated data preparation for generative AI applications, addressing the critical need for structured training data. The mid-market segment, particularly those navigating initial stages of digital transformation, offers a penetrable entry point for solutions emphasizing ease of use and compliance automation.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche specialists in metadata management, data lineage, and AI-driven data quality assurance. The long-term viability of this market is secured by the persistent growth of data-driven decision-making and the ever-tightening regulatory landscape around data governance. A key signal to watch is the increasing M&A activity focused on companies offering robust data provenance and automated audit trail capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Streamlines data workflows within broader ecosystems like Azure Synapse for enterprise users. |
| Acquisition of Specialist Firm | Enhances metadata management and data lineage capabilities for regulatory compliance. |
| Strategic Partnership | Extends market reach into electronic health record (EHR) systems for embedded analytics. |
| Product Launch | Introduces AI-augmented data profiling tools, empowering citizen data scientists. |
| Geographic Expansion | Penetrates underpenetrated markets like India to support local analytics initiatives. |
Research Approach
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each region. The analysis combines in-depth primary interviews with industry stakeholders, including data engineers, IT directors, compliance officers, and business analysts, with rigorous secondary validation. Secondary data sources encompass regulatory body publications, technology vendor reports, financial institution disclosures, and academic research, triangulated with bottom-up market sizing and top-down validation.
The analytical framework employs a rate-of-change decomposition, breaking down market growth into key demand drivers and supply-side capabilities across the analysis window. Segmentation dimensions modeled include deployment model, product type, application, end-user, and specific regulatory compliance requirements. Compound Annual Growth Rates (CAGRs) are derived from historical trends, projected technology adoption rates, and anticipated impacts of evolving data governance mandates. Key industry-specific forecast inputs include machine learning model proliferation and the increasing stringency of data governance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid technological disruption or unforeseen regulatory shifts. Forecasts reflect assumptions concerning current technological trajectories and regulatory enforcement levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Machine Translation Software Market
Software & Services
Global Project Software Market
Software & Services
Plant Design Software Market
Software & Services
Attendance Management Software Market
Software & Services
Engineering Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Collaboration Software Market
Software & Services
Smartphone OS Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Enterprise Software Market
Software & Services
Mainframe Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Customer Self-Service Software Market