
 Attendance Management Software Market | 2026-2036
Attendance Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Attendance Management Software Market Outlook
Platform licensing is fragmenting across subscription tiers, implementation services, and API monetization as vendors chase recurring revenue stability. Zoho People leverages its broader enterprise application ecosystem to bundle attendance tools with HR and payroll workflows. Hubstaff anchors its position through deep integration with project management platforms and granular productivity analytics. ActivTrak competes by emphasizing employee monitoring capabilities that extend beyond simple timekeeping into behavioral workforce intelligence.
Attendance management software comprises digital systems that capture, record, and analyze worker presence through biometric scanners, mobile GPS, web dashboards, and API-connected hardware, typically processing timestamps, leave balances, and overtime calculations against configurable organizational rules. Its primary commercial purpose is to automate payroll accuracy, ensure regulatory labor compliance, and reduce administrative overhead in distributed or shift-based work environments. Cloud-based deployment leads the market as enterprises prioritize remote accessibility and reduced IT infrastructure burden, while mobile functionality represents the fastest-growing feature dimension as field and hybrid workforces expand. Corporate end users dominate current spending, though healthcare facilities show the steepest adoption curve as patient-staff ratio regulations intensify tracking requirements.
The EU AI Act and GDPR constrain how European vendors deploy automated attendance verification and biometric data processing, forcing architecture redesigns toward on-device processing and explicit consent workflows. In the United States, OSHA recordkeeping standards and state-level wage-and-hour enforcement by agencies such as the Department of Labor shape product requirements around audit trails and retroactive adjustment capabilities. Stakeholders must monitor the divergence between permissive biometric regulation in some jurisdictions and outright bans in others when architecting geographic rollout strategies and data residency policies.
Market Dynamics
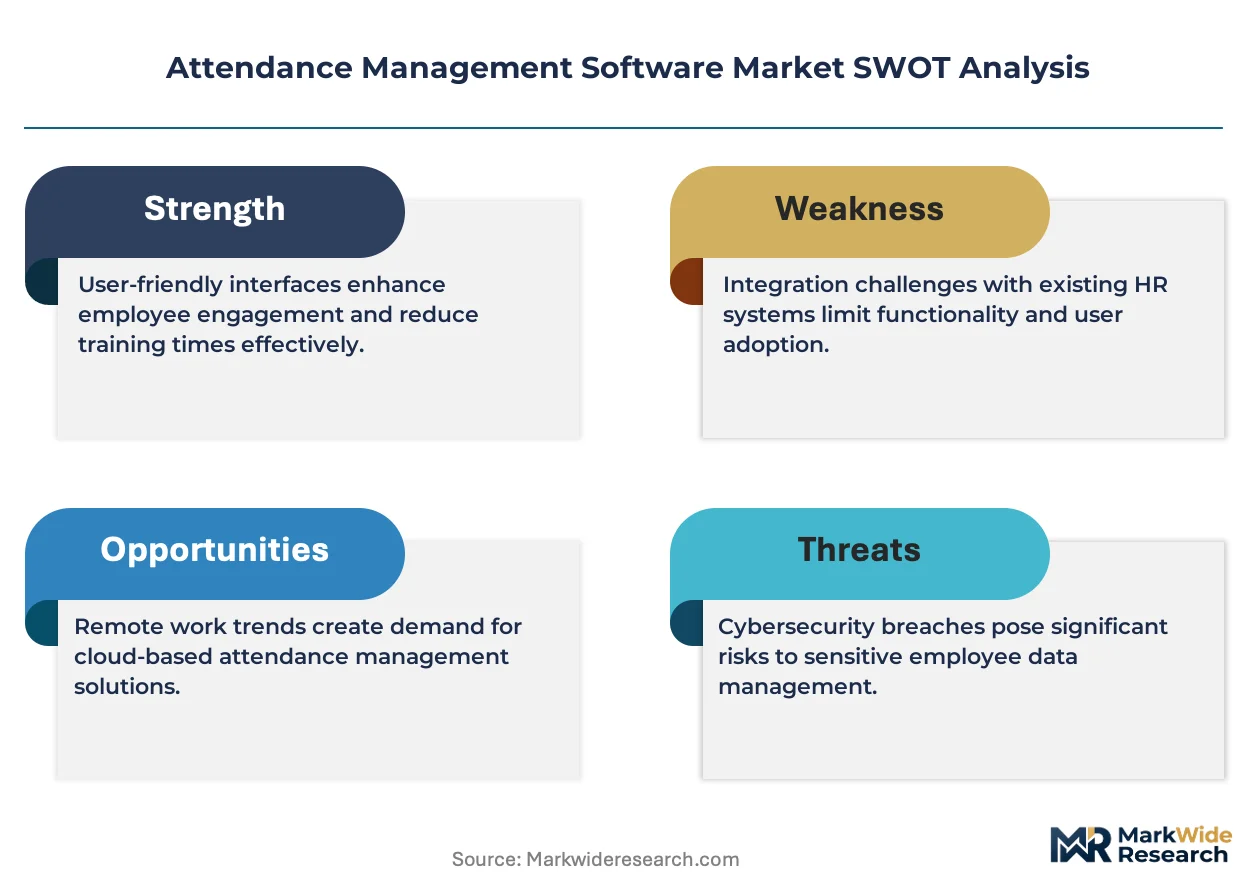
Cloud migration and biometric hardware commoditization are compressing deployment timelines while fragmenting vendor revenue models across SaaS tiers and API ecosystems. Healthcare facilities drive hardware refresh cycles as patient-staff ratio mandates intensify workforce tracking requirements.
Growth Catalysts
- GDPR Article 32 Security Requirements:European enterprises accelerate cloud migration to achieve encryption and access-control compliance, expanding addressable market for hosted attendance platforms with built-in data residency controls.
- Biometric sensor cost deflation:Fingerprint and facial recognition module prices dropped substantially, enabling mid-market employers to deploy enterprise-grade verification previously limited to Fortune 500 budgets.
- Healthcare staffing mandates:US state-level nurse-to-patient ratio laws in California and Massachusetts create audit-trail requirements that automate attendance system procurement for hospital networks.
Market Restraints
- Biometric data storage liability:Illinois BIPA and Texas CUBI impose per-violation statutory damages that inflate cyber insurance premiums for vendors retaining facial geometry templates.
- API dependency concentration:Payroll system integration reliability hinges on three dominant HCM platforms, creating single-point-of-failure risk for attendance vendors without native ledger capabilities.
- On-premise legacy lock-in:Manufacturing sites with air-gapped production networks resist cloud migration due to OT/IT segmentation requirements, slowing subscription revenue conversion.
Strategic Opportunities
- India's Digital India stack:Aadhaar-linked attendance verification creates regulatory-compliant entry path for vendors integrating with the country's public biometric infrastructure.
- Edge AI processing convergence:On-device neural inference for facial recognition eliminates cloud transmission latency, enabling real-time verification in bandwidth-constrained field environments.
- Gig platform channel expansion:Staffing marketplaces and freelance management systems represent unserved distribution channels where attendance APIs embed directly into contractor payment workflows.
Industry Challenges
- Multi-jurisdiction compliance engineering:Product teams must architect simultaneous GDPR right-to-erasure, BIPA informed-consent, and CCPA disclosure workflows, fragmenting development roadmaps.
- Legacy time-clock hardware retrofit complexity:Decades-old badge readers and proprietary control boards require custom middleware development, inflating professional services margins and delaying recurring revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attendance Management Software Market |
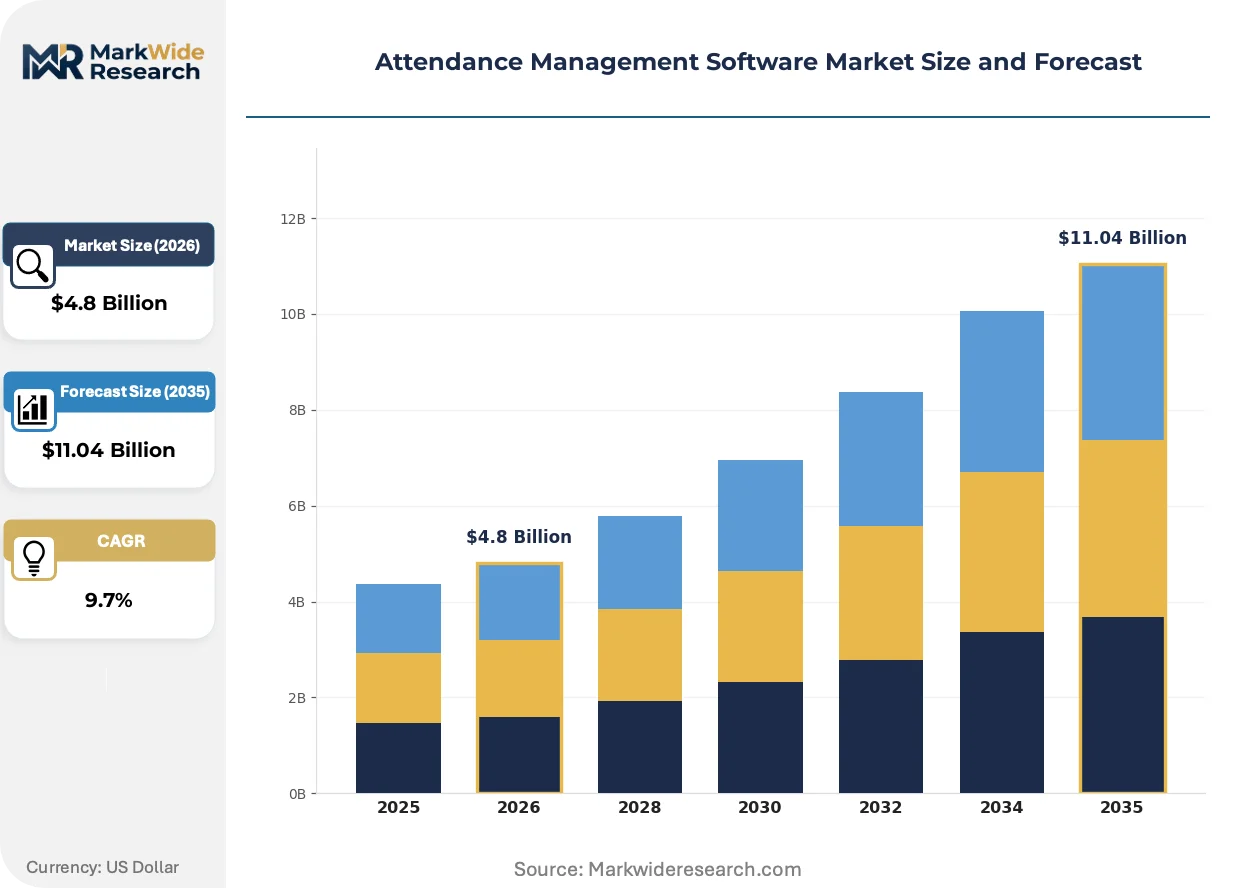
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Corporate, Educational Institutions, Healthcare Facilities, Government Feature: Time Tracking, Reporting, Integration, Leave Management Service Type: Installation, Support, Customization, Training |
| Companies Covered | TimeClock Plus, Hubstaff, Lark, ActivTrak, Toggl Track, TMetric, Zoho People, edays, DeskTime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attendance Management Software Market Strategic Shifts
Attendance systems are converging with workforce analytics platforms, transforming timekeeping from administrative utility into strategic labor optimization infrastructure. Three developments dominate current vendor roadmaps.
Computer vision-based passive attendance verification is digitizing workplace entry monitoring without explicit employee action. Corporate campuses and healthcare facilities deploy ceiling-mounted sensors that recognize individuals through gait analysis and facial geometry. This eliminates queue formation at traditional clock-in terminals. The technology is digitizing lobby architecture and security staffing models while compressing hardware capital requirements per employee.
The EU AI Act's risk-classification framework for biometric identification systems is forcing architecture redesigns toward on-device processing and explicit consent audit trails. Vendors serving European enterprises must demonstrate algorithmic transparency and human oversight protocols for automated attendance decisions. Healthcare and public sector deployments face the strictest conformity assessment obligations, driving demand for explainable AI documentation tools.
Subscription unbundling is fragmenting buyer relationships across point solutions and integrated suites. Mid-market employers increasingly procure attendance modules through vertical SaaS marketplaces rather than direct vendor relationships. This channel migration concentrates discovery power with platform orchestrators and compresses standalone pricing power for pure-play vendors. The shift is most visible in North American professional services and technology sectors where IT procurement centralization favors ecosystem bundles.
Attendance Management Software Market Segmentation
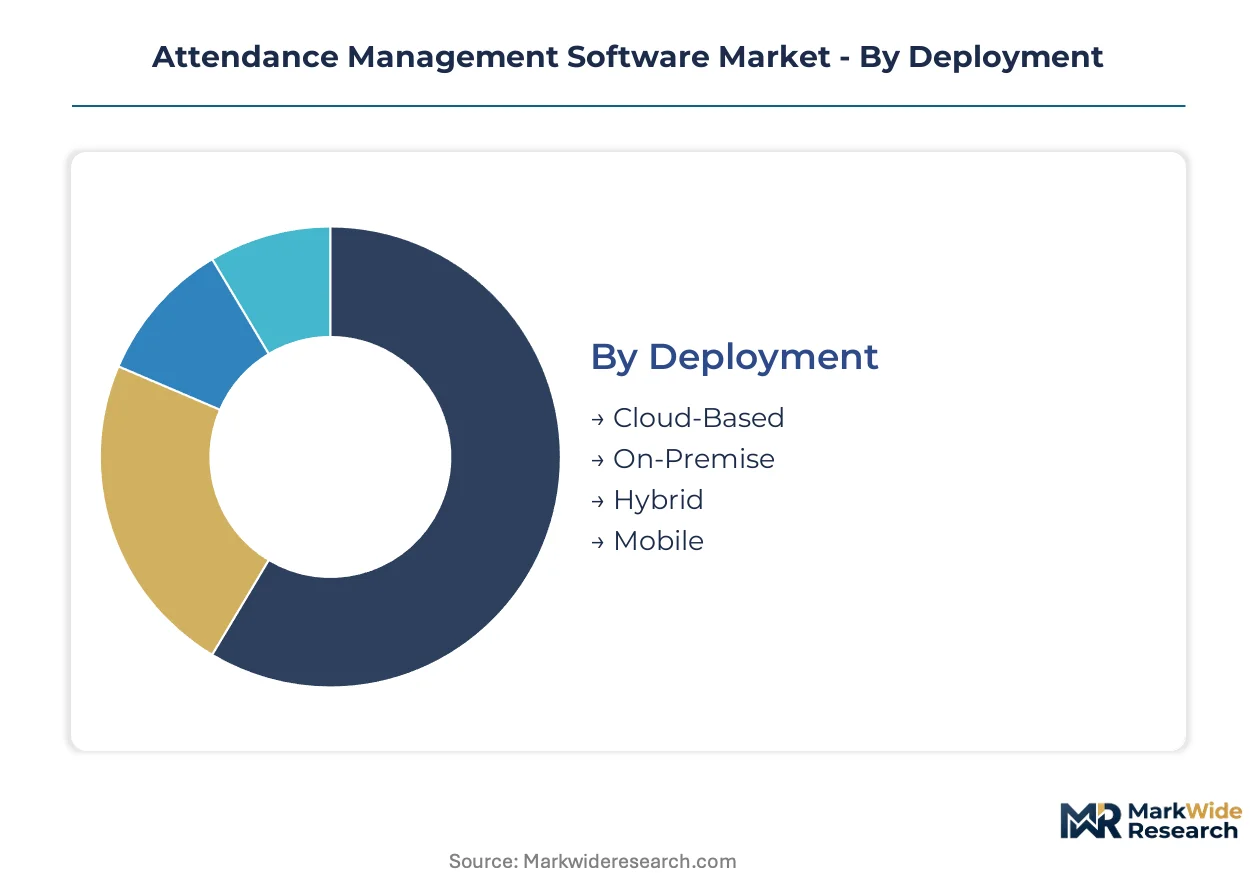
Attendance management software segments reflect divergent infrastructure requirements across regulated industries. Deployment mode determines data residency obligations, while end-user verticals impose distinct compliance architectures that reshape feature prioritization.
Deployment:
Use-case spectrum spans bandwidth-constrained field operations to air-gapped manufacturing floors with strict OT/IT segmentation.
- Cloud-Based:Multi-tenant SaaS architectures with automatic encryption and regional data residency controls serve distributed workforces. Healthcare networks in the United States select this model to satisfy HIPAA audit-trail mandates without capital expenditure.
- On-Premise:Local server installations behind corporate firewalls retain biometric templates within facility boundaries. Defense contractors and financial institutions in Germany deploy this mode to satisfy GDPR Article 32 security requirements and works-council data sovereignty demands.
- Hybrid:Edge processing for real-time verification paired with cloud analytics for workforce optimization. Manufacturing sites with mixed cleanroom and administrative zones favor this architecture.
- Mobile:GPS-stamped clock-in via employee smartphones serves construction crews and field service technicians without fixed terminals.
The dominant share belongs to Cloud-Based, while Mobile is closing the gap fastest.
End User:
Customer type dictates pricing tolerance and integration complexity, with regulated sectors commanding premium service tiers.
- Healthcare Facilities:Nurse-to-patient ratio mandates in California and Massachusetts drive audit-trail automation. These buyers require biometric verification with surgical-scheduling system integration and overtime alert workflows.
- Corporate:Enterprise HRIS integration dominates procurement criteria. Multinational employers prioritize API reliability with Workday, SAP SuccessFactors, and Oracle HCM platforms.
- Government:Federal contractors face Davis-Bacon Act prevailing-wage documentation requirements. Public sector RFPs emphasize FedRAMP authorization and Section 508 accessibility compliance.
- Educational Institutions:K-12 districts and university systems track substitute teacher fill rates and grant-funded researcher hours. State reporting standards in Texas and Florida shape attendance data export formats.
Healthcare Facilities command the highest per-seat pricing, while Corporate accounts deliver the largest contract volumes.
Feature:
Functional modules compete for roadmap priority based on integration depth and automation potential.
- Integration:Pre-built connectors to payroll, project management, and access control systems reduce implementation timelines. Buyers in professional services sectors rank this capability above native analytics.
- Time Tracking:Core clock-in/clock-out functionality with geofencing and biometric verification remains the entry-level requirement across all verticals.
- Reporting:Configurable dashboards for labor cost allocation and compliance documentation serve finance and HR stakeholders. Manufacturing buyers emphasize shift-pattern analysis for production planning.
- Leave Management:Automated accrual calculations and approval workflows reduce administrative overhead. European employers require this module to track statutory minimum vacation entitlements under the Working Time Directive.
Integration claims the largest development investment, while Leave Management is gaining feature parity fastest.
Service Type:
Revenue concentration shifts from perpetual licenses toward recurring professional services as implementation complexity rises.
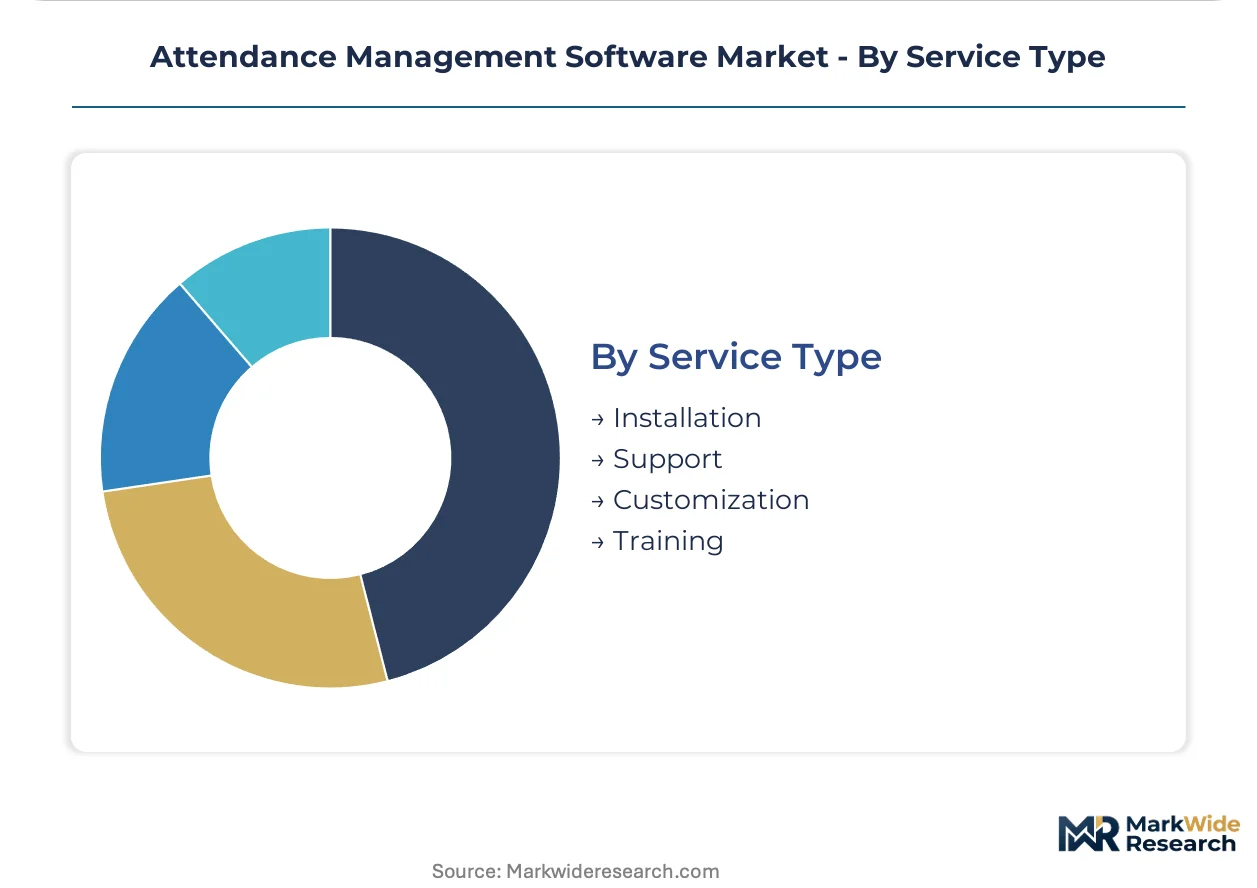
- Customization:Workflow adaptation for union bargaining agreements and multi-entity payroll structures commands premium day rates. System integrators in India deliver these services at cost advantages for North American buyers.
- Support:Tiered response-time guarantees with dedicated account management anchor enterprise renewals. Healthcare buyers require 24/7 availability for critical staffing systems.
- Installation:Hardware deployment and network configuration for biometric terminals and badge readers. Manufacturing retrofit projects extend timelines due to legacy control system interoperability.
- Training:Administrator certification and end-user onboarding programs reduce ticket volume post-launch. Educational institutions with high seasonal turnover prioritize scalable e-learning modules.
Support generates the steadiest recurring revenue, while Customization produces the highest margin per engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States show the lowest price elasticity, absorbing premium SaaS tiers for compliance-heavy deployments, while mid-market employers in India and Southeast Asia drive rapid volume expansion through cost-optimized cloud solutions. Regulatory fragmentation across biometric privacy regimes creates divergent product architectures that reshape geographic rollout sequencing.
United States
Federal contractor labor-rule enforcement and OSHA recordkeeping standards anchor enterprise procurement intensity. The Department of Labor's wage-and-hour audit protocols mandate granular audit trails that favor platforms with retroactive adjustment capabilities. Hospital networks in California and Massachusetts automate attendance systems to satisfy state-level nurse-to-patient ratio mandates.
Germany
Works-council data sovereignty demands and GDPR Article 32 security requirements push defense contractors and financial institutions toward on-premise deployments. The country's national data protection regulator enforces strict biometric consent workflows that complicate facial recognition rollouts. Manufacturing clusters in Bavaria and Baden-Württemberg favor hybrid architectures balancing cleanroom OT segmentation with cloud analytics.
India
Aadhaar-linked attendance verification through the Digital India stack creates regulatory-compliant entry paths for vendors integrating public biometric infrastructure. The country's central bank and securities regulator drive formalization of workforce tracking across banking and IT services sectors. Technology corridors in Karnataka and Telangana concentrate demand from IT-BPM employers managing hybrid workforces.
United Kingdom
Post-Brexit divergence from EU AI Act implementation creates transitional uncertainty for biometric system vendors. The Information Commissioner's Office enforces GDPR-derived standards that constrain automated decision-making in attendance verification. Professional services firms in London prioritize API reliability with dominant HCM platforms over native analytics capabilities.
Japan
METI's promotion of workplace digitalization and aging workforce management intensifies tracking requirements across manufacturing and care sectors. The country's pharmaceutical and medical device regulator influences data integrity standards for healthcare facility deployments. Industrial concentrations in Aichi Prefecture and the Kanto region drive demand for edge-processing solutions in bandwidth-constrained factory environments.
Attendance Management Software Market Competitive Environment
Enterprise suite vendors and specialized workforce analytics platforms split the market between integrated HR ecosystem plays and deep vertical functionality. The vendor base organizes around three strategic archetypes: broad enterprise application suites bundling attendance with payroll and HR workflows, pure-play time-tracking specialists emphasizing project management integration, and employee monitoring platforms extending into behavioral workforce intelligence. Dominant competitive moves include API ecosystem expansion to anchor third-party integrations and geographic localization to satisfy data residency requirements.
Within the enterprise suite tier, Zoho People represents the ecosystem-anchored archetype, while Hubstaff and ActivTrak occupy distinct positions on the workforce intelligence spectrum. Hubstaff exemplifies the project-management-integrated specialist model, and ActivTrak sits within the employee monitoring expansion trajectory. These three companies illustrate how vendor positioning fragments across bundling depth, integration breadth, and analytics intensity rather than converging on uniform feature parity.
| Leading Market Players |
|---|
| TimeClock Plus |
| Hubstaff |
| Lark |
| ActivTrak |
| Toggl Track |
| TMetric |
| Zoho People |
| edays |
| DeskTime |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in biometric sensor manufacturing across South Korea and Taiwan compresses module costs while expanding vendor margin headroom for software bundling. This utilization dynamic pushes attendance platform providers toward subscription-heavy revenue models that decouple hardware margins from long-term customer lifetime value extraction.
Pricing Analysis
Implementation and customization services drive lifetime value more than initial SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates enterprise buyers with FedRAMP requirements from mid-market employers seeking API-only integrations. Price differentiation rests on data residency certification tier and vertical-specific compliance module availability. Cost compression in the economy tier intensifies as Indian system integrators deliver implementation services at structural cost advantages. Corporate end users in the United States show the lowest price sensitivity, while educational institutions and small professional services firms absorb the highest procurement friction.
Supply Chain Analysis
Export-control restrictions on advanced facial recognition algorithms limit technology flows from United States and European Union vendors into certain jurisdictions. Hardware assembly concentrates in China, Taiwan, and Vietnam, with biometric sensor fabrication anchored in South Korea and Japan. Component dependencies include CMOS image sensors, edge AI inference chips, and secure element modules for template encryption. Single-source vulnerability runs through dominant HCM platform APIs that gate payroll integration reliability. Distribution runs through direct enterprise sales teams for large healthcare networks and vertical SaaS marketplaces for mid-market professional services buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional services and training revenue layers expand faster than hardware sales as legacy manufacturing retrofits prolong implementation timelines. This service-attach dynamic rewards vendors who front-load customer success investment.
For Market Incumbents: Harden API ecosystem control by acquiring niche integration specialists with pre-built connectors to legacy manufacturing execution systems. Expand on-premise edge processing capabilities to defend against cloud-native challengers targeting German works-council data sovereignty requirements. Biometric data storage liability under Illinois BIPA and Texas CUBI demands proactive cyber insurance architecture and consent workflow automation. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where Aadhaar-linked verification infrastructure creates regulatory-compliant deployment pathways. Healthcare staffing marketplaces and freelance management platforms offer unserved channels where attendance APIs embed directly into contractor payment workflows. Channel partnerships with dominant HCM platform orchestrators accelerate discovery velocity faster than direct sales investment. For Investors and Strategic Acquirers: Capital is best deployed toward vertically specialized vendors with deep healthcare or government compliance expertise rather than horizontal SaaS generalists. Long-term viability favors platforms demonstrating algorithmic transparency documentation for EU AI Act conformity assessment. Watch for regulatory fragmentation between permissive biometric jurisdictions and outright ban states as the signal for geographic rollout strategy recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built connectors to Workday, SAP SuccessFactors, and Oracle HCM reduce enterprise sales friction. |
| Edge AI Processing Deployment | On-device neural inference eliminates cloud transmission latency for bandwidth-constrained manufacturing floors. |
| Geographic Expansion | Aadhaar-linked verification through India's Digital India stack opens regulatory-compliant market entry. |
| Acquisition of Specialist Firm | Legacy manufacturing execution system integrators extend retrofit capabilities and professional services margins. |
| Strategic Partnership | Vertical SaaS marketplace placement concentrates discovery power with platform orchestrators. |
Study Parameters
Operator-level perspectives from HR technology directors, workforce analytics managers, biometric hardware procurement leads, and system integration specialists anchored the qualitative base. These primary insights combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, App Annie mobile workforce app analytics, and healthcare facility procurement databases. Bottom-up deployment modeling across cloud, on-premise, hybrid, and mobile architectures triangulated against top-down SaaS revenue estimates from public vendor disclosures.
Scenario-bracketing around regulatory divergence, biometric adoption curves, and healthcare staffing mandate intensity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment mode, end-user vertical, integration complexity tier, and regional data residency requirement cluster. CAGRs derived from installed base growth rates, seat expansion patterns, and pricing trajectory assumptions. Forecast inputs incorporated EU AI Act implementation timelines and state-level nurse-to-patient ratio mandate expansion patterns.
Practitioners should monitor biometric privacy legislation fragmentation, HCM platform API policy shifts, and healthcare staffing mandate geographic expansion for early signals. Forecasts reflect assumptions about cloud migration velocity and sensor cost deflation sustainability. Material shifts in Illinois BIPA or Texas CUBI damage award precedents would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Live Software Market
Software & Services
Web Framework Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
IT Services Market
Software & Services
Global Remote Work Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Enterprise Application Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Multivariate Testing Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Proxy Services and Software Market
Software & Services
Global Data Recovery Software Market