
 Collaboration Software Market | 2026-2036
Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Collaboration Software Market Analysis
The gap between premium enterprise suites and lightweight point solutions is shifting as IT procurement teams split budgets between all-in-one platforms and specialized tools. Microsoft Teams leverages its Office 365 ecosystem to anchor large-enterprise deployments. Notion differentiates through flexible workspace databases that appeal to creative and product teams. Slack competes as a messaging-first layer with deep third-party app connectivity.
Collaboration software encompasses digital platforms enabling synchronous and asynchronous communication, document co-authoring, and workflow orchestration across distributed teams, typically delivered through web clients, desktop applications, and mobile SDKs with 99.9% uptime SLAs. Cloud-based deployment leads volume due to zero-infrastructure onboarding, while hybrid configurations capture regulated sectors requiring on-premises data residency for video conferencing archives. Enterprise end users generate the deepest integration investments, though small businesses drive seat-count expansion through self-serve SaaS tiers.
FDA oversight affects healthcare collaboration through 21 CFR Part 11 requirements for electronic records, while HIPAA mandates encryption standards for patient data shared in clinical messaging. The EU AI Act imposes documentation obligations on vendors deploying automated transcription and sentiment analysis in meeting platforms. GDPR data-localization rules continue shaping where European enterprises host project management data. Stakeholders must weigh compliance roadmaps against feature velocity when selecting vendors for cross-border deployments.
Market Dynamics
Hybrid work permanence is fragmenting IT budgets across overlapping collaboration tools, forcing procurement teams to rationalize redundant subscriptions while vendors race to embed workflow automation that locks in enterprise switching costs.
Growth Catalysts
- EU AI Act documentation mandates:Vendors deploying automated transcription must maintain audit trails, creating differentiated compliance offerings that healthcare and financial services procurement teams prioritize.
- Industrial cluster demand in Germany:Automotive and precision manufacturing supply chains require secure supplier portals with role-based access controls, driving specialized procurement of collaboration platforms with embedded ERP connectors.
- HIPAA-compliant clinical messaging:Healthcare systems replacing pagers and consumer apps with encrypted, audit-logged platforms for care coordination generate sustained replacement cycles across hospital networks.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control the underlying compute and storage for most SaaS collaboration tools, creating systemic resilience risks and limited negotiation leverage for mid-market buyers.
- GDPR data-localization enforcement:European enterprises face mandatory data residency requirements that fragment vendor architectures and inflate operational costs for cross-border deployments.
- Generative AI training data liability:Unclear intellectual property frameworks around meeting transcript ingestion and model training expose vendors to litigation risk that slows feature rollout.
Strategic Opportunities
- India's PLI scheme for IT hardware:Local data center expansion and device manufacturing incentives enable vendors to offer sovereign-hosted collaboration stacks for government and defense contracts.
- Frontline worker enablement:Mobile-first, offline-capable messaging tools for retail, logistics, and field services represent an underpenetrated segment distinct from knowledge-worker platforms.
- CSRD sustainability reporting integration:European enterprises require collaboration tools that embed emissions tracking and supply chain disclosure workflows, creating feature differentiation for ESG-conscious procurement.
Industry Challenges
- Interoperability protocol fragmentation:Proprietary APIs and limited support for open standards like Matrix or ActivityPub force enterprises into costly custom integration projects that delay deployment timelines.
- Security clearance timelines for federal sales:FedRAMP and comparable national certification processes in Germany, Japan, and Australia extend sales cycles by 12-18 months for vendors targeting public sector accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaboration Software Market |
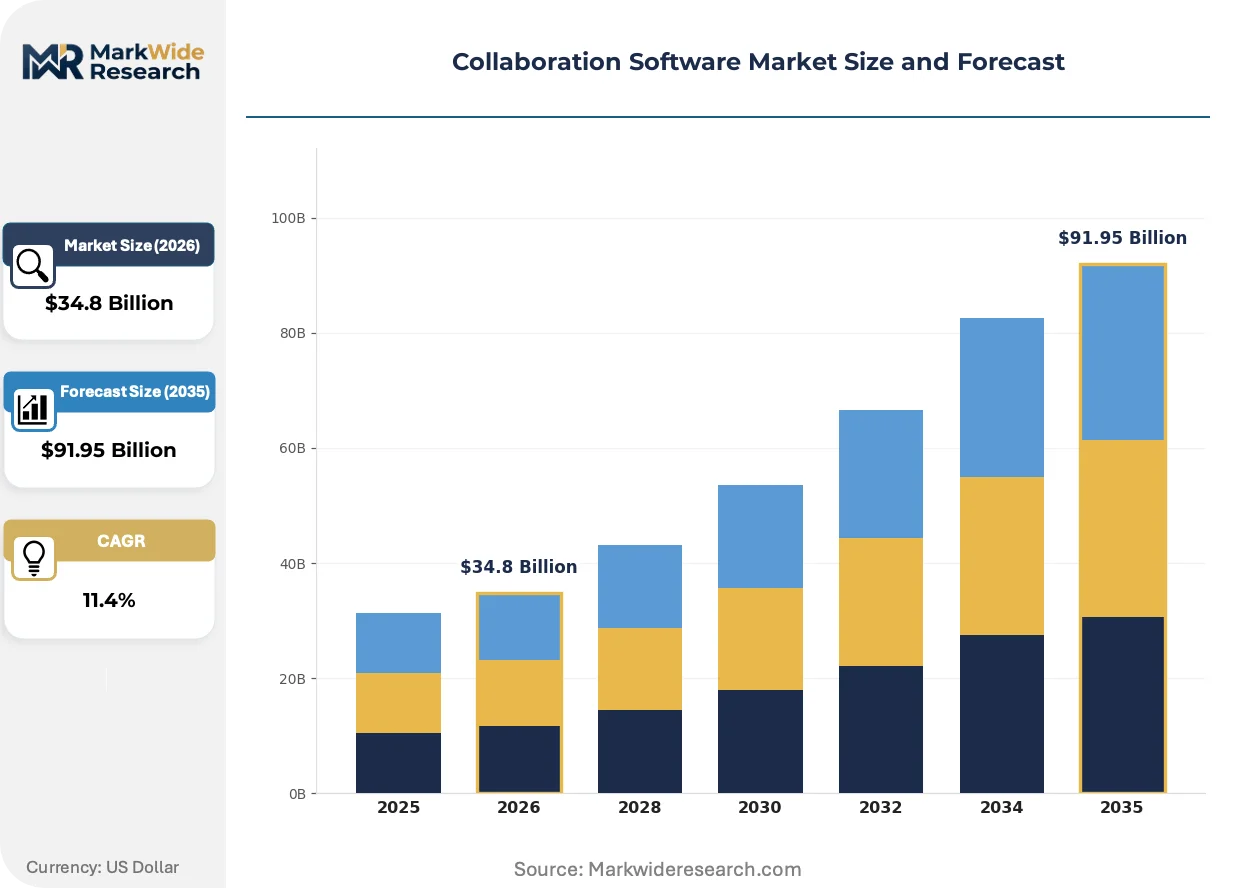
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $91.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS End User: Enterprises, Small Businesses, Educational Institutions, Nonprofits Feature: File Sharing, Instant Messaging, Video Conferencing, Project Management Integration Level: API Integration, Third-party Apps, Custom Integrations, Native Integrations |
| Companies Covered | Zoom Workplace, Miro, Microsoft Teams, Monday.com, Notion, Slack, Asana, ClickUp, Google Workspace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaboration Software Market Emerging Trajectories
Artificial intelligence capabilities are migrating from standalone features to embedded workflow agents that anticipate user intent, compressing the gap between communication and action execution within collaboration interfaces.
Real-time translation and summarization engines are integrating directly into video conferencing and asynchronous messaging threads. Multinational enterprises with distributed engineering teams in Poland, Mexico, and Vietnam adopt these tools to collapse language barriers that previously required dedicated interpretation staff. The technology is integrating meeting content with downstream task management systems, eliminating manual note-taking handoffs.
The EU AI Act's risk-classification framework imposes documentation and human oversight requirements on automated sentiment analysis and decision-support features. Vendors must maintain technical files and conformity assessments for high-risk AI deployments, particularly affecting platforms used in hiring, performance evaluation, and clinical settings. German industrial firms and French public administrations are demanding vendor transparency reports that exceed baseline compliance to satisfy procurement due diligence.
Enterprise buyers are consolidating vendor relationships through platform bundling rather than point-solution accumulation. IT departments in financial services and professional services verticals favor suites that combine messaging, document collaboration, and low-code automation over best-of-breed toolchains. This preference shift is most pronounced in the United States and United Kingdom, where procurement teams face explicit mandates to reduce application sprawl and associated security surface area.
Collaboration Software Market Segmentation
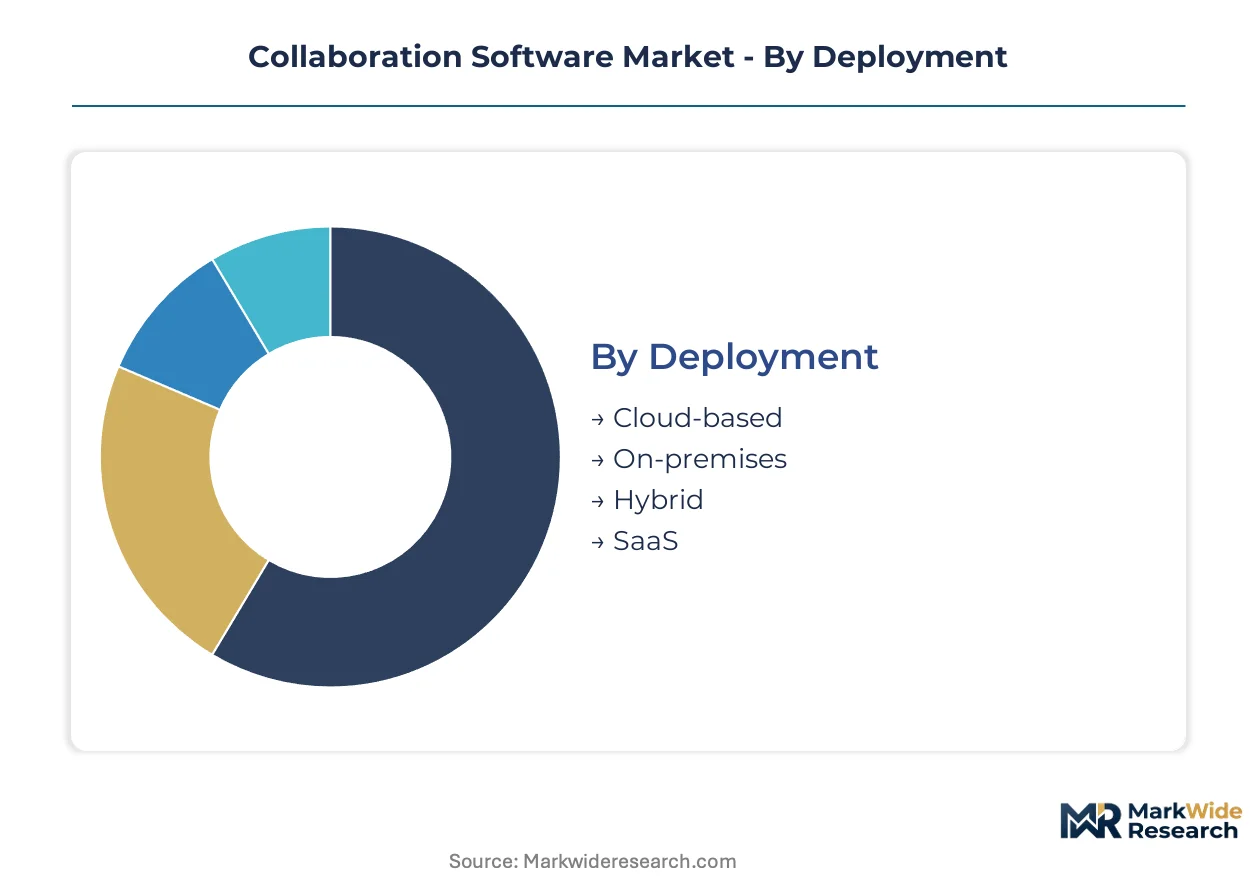
Procurement teams in the Collaboration Software Market split investments across deployment architectures, user scale tiers, and integration depth. Segment selection determines compliance posture, total cost of ownership, and workflow automation potential for distributed teams.
Deployment:
Architecture choice reflects data sovereignty requirements and IT infrastructure maturity across buyer organizations.
- Cloud-based:Multi-tenant SaaS delivery eliminates server maintenance overhead. Healthcare systems in Germany and financial services firms in Singapore prioritize ISO 27001-certified cloud regions for patient and transaction data residency under GDPR and MAS TRM guidelines.
- On-premises:Single-tenant installation on customer-managed hardware. Defense contractors in the United States and classified research facilities in France mandate air-gapped deployments to satisfy FedRAMP High and ANSSI certification requirements.
- Hybrid:Split architecture with sensitive workloads local and collaboration layers cloud-hosted. German automotive supply chains adopt hybrid models to keep CAD files on-premises while routing supplier messaging through encrypted cloud gateways.
- SaaS:Subscription software delivered via browser and mobile applications with automatic updates. Small businesses across India and Brazil drive seat expansion through self-serve tiers with per-user monthly billing.
Mature deployment sits with On-premises. Newer deployment is concentrated in SaaS.
End User:
Budget authority and integration complexity diverge sharply across organizational scale and sector.
- Enterprises:Organizations exceeding 1,000 employees with dedicated IT procurement functions. Multinational banks in London and pharmaceutical headquarters in Basel negotiate enterprise agreements with 99.99% uptime SLAs and dedicated customer success managers.
- Small Businesses:Companies under 500 employees with founder-led software decisions. Creative agencies in Melbourne and specialty manufacturers in Milan adopt freemium tiers that scale to paid seats as headcount expands.
- Educational Institutions:Universities and K-12 districts with volume licensing needs. State university systems in Texas and vocational colleges in Ontario require FERPA-compliant platforms with learning management system connectors.
- Nonprofits:Charitable organizations with constrained technology budgets. International development NGOs in Geneva and community health networks in Nairobi leverage donated or heavily discounted tiers with volunteer coordination features.
Integration investment concentrates with Enterprises. Seat-count velocity is climbing fastest in Small Businesses.
Feature:
Core functionality modules compete for user attention and platform stickiness within unified suites.
- File Sharing:Document storage with version control and granular permissions. Legal departments in New York and architecture studios in Copenhagen demand watermarking and audit logs for client deliverables.
- Instant Messaging:Real-time text communication with threading and search. Hospital nursing stations in Chicago and warehouse floor supervisors in Rotterdam replace pagers and walkie-talkies with HIPAA-compliant and ATEX-certified messaging.
- Video Conferencing:Synchronous audio-visual meetings with recording and transcription. Distributed engineering teams in Warsaw and Mexico City adopt real-time translation engines to collapse language barriers without dedicated interpreters.
- Project Management:Task tracking with Gantt charts, dependencies, and resource allocation. Construction project offices in Dubai and product teams in Stockholm integrate project data with ERP systems for budget synchronization.
Platform stickiness anchors on Video Conferencing. Workflow automation expansion is gaining share fastest in Project Management.
Integration Level:
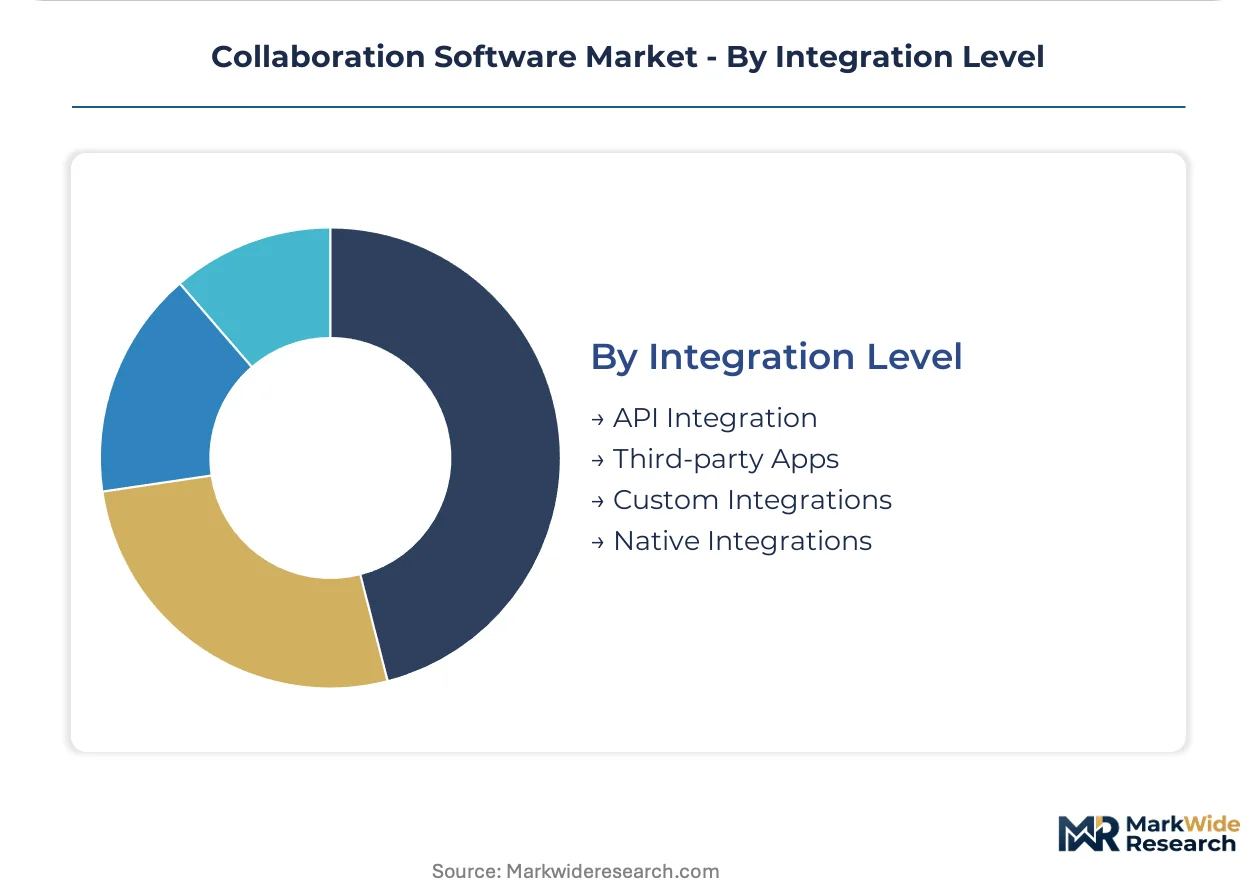
Connectivity depth determines whether collaboration platforms serve as communication endpoints or workflow orchestration hubs.
- API Integration:Programmatic access via REST or GraphQL endpoints. Fintech developers in Bangalore and logistics operators in Hamburg build custom connectors between collaboration tools and proprietary shipment tracking systems.
- Third-party Apps:Pre-built connectors to external SaaS tools. Sales operations teams in Sydney and marketing departments in Toronto integrate CRM and email automation without engineering resources.
- Custom Integrations:Bespoke development for unique enterprise workflows. Aerospace manufacturers in Toulouse and semiconductor fabricators in Hsinchu commission custom plugins linking collaboration platforms to proprietary manufacturing execution systems.
- Native Integrations:First-party connectivity within vendor ecosystems. Organizations standardized on Microsoft 365 or Google Workspace prioritize native integrations that preserve single sign-on and unified admin consoles.
IT governance favors Native Integrations. Technical differentiation is expanding most quickly in API Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Redmond anchors the highest concentration of enterprise collaboration platform development, with Microsoft Teams leveraging its Office 365 ecosystem to capture large-enterprise deployments across Fortune 500 headquarters.
United States
FDA oversight through 21 CFR Part 11 requirements shapes healthcare collaboration procurement, driving hospital networks toward encrypted, audit-logged clinical messaging platforms. HIPAA mandates encryption standards for patient data shared in nursing stations and care coordination workflows. Chicago's hospital systems are replacing pagers with HIPAA-compliant messaging tools that integrate with electronic health records.
Germany
Industrial clusters in automotive and precision manufacturing prioritize secure supplier portals with role-based access controls for supply-chain collaboration. The EU AI Act imposes documentation obligations on vendors deploying automated transcription in meeting platforms used by Frankfurt financial services firms. Bavaria's automotive supply chains adopt hybrid deployment models to keep CAD files on-premises while routing supplier messaging through encrypted cloud gateways.
India
Bangalore's fintech developers build custom API connectors between collaboration tools and proprietary shipment tracking systems for logistics operators. The PLI scheme for IT hardware enables local data center expansion and device manufacturing incentives for sovereign-hosted collaboration stacks. Government and defense contracts in Delhi-NCR drive demand for air-gapped deployments satisfying national security requirements.
United Kingdom
GDPR data-localization rules shape where London-based financial services firms host project management data, fragmenting vendor architectures for cross-border deployments. Procurement teams face explicit mandates to reduce application sprawl and associated security surface area. The City of London's professional services verticals favor suites combining messaging, document collaboration, and low-code automation over best-of-breed toolchains.
Japan
METI guidelines influence enterprise software procurement patterns, with Tokyo headquarters negotiating enterprise agreements carrying 99.99% uptime SLAs. Security clearance timelines for public sector sales extend vendor certification processes by 12-18 months. Osaka's manufacturing execution systems commission custom plugins linking collaboration platforms to proprietary semiconductor fabrication workflows.
Collaboration Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and compliance certification tiers, with suite providers commanding higher annual contract values than point-solution vendors. The market structure consolidates around platform bundling rather than point-solution accumulation, as IT departments favor unified ecosystems over fragmented toolchains. Three strategic archetypes dominate: ecosystem-anchored suites, messaging-first layers with deep third-party connectivity, and flexible workspace databases for creative teams. Dominant competitive moves include embedding workflow automation to lock in enterprise switching costs and racing to certify FedRAMP High and comparable national security clearances for public sector accounts.
Within the ecosystem-anchored tier, Microsoft Teams and Google Workspace represent the dominant platform bundling strategies, occupying positions that leverage existing productivity suite relationships to capture large-enterprise deployments. Slack exemplifies the messaging-first archetype with its emphasis on real-time communication infrastructure, while Notion sits within the flexible workspace database category appealing to product and creative teams requiring customizable information architecture. Monday.com and Asana occupy positions in the project management specialization tier, with ClickUp and Miro representing adjacent workspace visualization and task orchestration archetypes respectively.
| Leading Market Players |
|---|
| Zoom Workplace |
| Miro |
| Microsoft Teams |
| Monday.com |
| Notion |
| Slack |
| Asana |
| ClickUp |
| Google Workspace |
| Others |
Supply Flow & Price Mechanics
Enterprise procurement mandates to reduce application sprawl are compressing vendor pricing power and forcing hyperscalers to absorb integration costs that previously flowed through to end customers. This demand-side consolidation reshapes how collaboration platforms source compute capacity and route data across sovereign jurisdictions.
Pricing Analysis
Uptime guarantees anchor value-based pricing in enterprise collaboration contracts, with 99.99% SLAs commanding premiums over standard 99.9% tiers. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified deployments from mid-market SaaS tiers and self-serve freemium offerings. Cost compression in the mid-market tier intensifies because Microsoft Teams bundles messaging at marginal cost to Office 365 subscribers. Small businesses exhibit highest price sensitivity, while defense contractors and pharmaceutical headquarters accept premium pricing for air-gapped deployments with dedicated customer success managers.
Supply Chain Analysis
India's PLI scheme for IT hardware and data center localization mandates are reshaping sourcing patterns for vendors seeking government contracts in Delhi-NCR and Bangalore. Cloud infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, with submarine cable capacity and terrestrial fiber backbones determining latency performance. Single-source vulnerability concentrates in three hyperscalers controlling underlying compute and storage for most SaaS collaboration tools. Distribution runs through direct enterprise sales teams for large accounts and self-serve web portals for seat expansion in small businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into proprietary AI model training and on-premises hardware certification is becoming the decisive competitive lever as vendors race to satisfy FedRAMP High and EU AI Act documentation requirements without ceding margin to third-party infrastructure providers.
For Market Incumbents: Anchor platform stickiness through embedded workflow automation that locks in enterprise switching costs, particularly for hospital networks replacing pagers with HIPAA-compliant clinical messaging and German automotive supply chains requiring CAD-integrated supplier portals. Defend against open-source protocols like Matrix by accelerating native ERP connector development and prioritizing FedRAMP High certification timelines for public sector accounts. For New Entrants and Emerging Players: Enter via frontline worker enablement in retail, logistics, and field services, where mobile-first offline-capable messaging tools remain underpenetrated relative to knowledge-worker platforms. Target India's government and defense contracts through sovereign-hosted collaboration stacks satisfying PLI scheme localization requirements. Pursue channel partnerships with device manufacturers and industrial automation vendors rather than direct enterprise sales. For Investors and Strategic Acquirers: Re-rating potential sits with specialized compliance vendors given EU AI Act documentation mandates and HIPAA enforcement tightening, as healthcare and financial services procurement teams prioritize audit-trail capabilities over feature velocity. Acquisition target archetype: mid-cap platforms with existing FedRAMP Moderate certification and embedded ERP connectors for German industrial clusters. Signal to watch: security clearance timeline compression in Japan and Australia as leading indicators of public sector revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Teams leverages Office 365 ecosystem to capture large-enterprise deployments with unified admin consoles. |
| Acquisition of Specialist Firm | Consolidation targets workflow automation vendors that compress gaps between communication and action execution. |
| Geographic Expansion | India's PLI scheme enables sovereign-hosted stacks for government contracts requiring air-gapped data residency. |
| Product Launch | Real-time translation engines collapse language barriers for distributed engineering teams in Poland and Mexico. |
| Strategic Partnership | ERP connector development with SAP and Oracle locks in German automotive supply chain procurement decisions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across CTOs, IT procurement officers, platform engineers, and integration specialists at multinational enterprises and mid-market SaaS adopters. FDA 21 CFR Part 11 guidance documents, EU AI Act technical standards, and hyperscaler capex disclosures provided compliance and infrastructure demand signals. Bottom-up seat-count modeling across deployment tiers reconciled against top-down market value estimates.
Granularity-level framing applied organization size, vertical sector, deployment architecture, and integration complexity as core segmentation dimensions across the projection horizon. CAGRs derived from logistic adoption curves fitted to historical cloud software penetration patterns, with healthcare compliance cycles and industrial cluster procurement timelines as industry-specific forecast inputs. Value outputs reflect blended pricing assumptions across freemium conversion rates and enterprise agreement structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or hyperscaler concentration regulatory intervention. Assumptions reflect current GDPR localization requirements and HIPAA encryption standards, with revision triggers including open-source protocol adoption breakthroughs or sovereign cloud mandate expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Payroll and HR Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Invoice Processing Software Market
Software & Services
Office Software Market
Software & Services
Commissioning Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Winery Management Software Market
Software & Services
HPC Software Market
Software & Services
Feedback Management Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Managed Information Services Market
Software & Services
Global Microscope Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Global Home Inspection Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Website Builder Tool Market