
 B2B Gateway Software Market | 2026-2036
B2B Gateway Software Market Size, Share, and Industry Trends Forecast 2026-2036
B2B Gateway Software Market Outlook
Direct API-to-ERP channels between manufacturers and distributors is rewriting how enterprise data flows across supply chains. MuleSoft leverages its Anypoint platform to anchor connectivity across hybrid cloud environments. Boomi competes through low-code integration tools that simplify partner onboarding for mid-market distributors. Informatica sustains its position via advanced data transformation engines that handle high-velocity EDI transactions.
B2B Gateway Software constitutes middleware that translates, validates, and routes structured business documents between disparate enterprise systems using protocols such as AS2, SFTP, and REST APIs. The software enforces data integrity through schema validation and encryption, enabling automated purchase order, invoice, and shipping notice exchanges across organizational boundaries. Cloud-based deployment leads in new installations as retailers seek elastic capacity during seasonal demand spikes, while on-premises solutions retain dominance among defense contractors with air-gapped security requirements. API Management captures concentrated margin pools as enterprises replace legacy point-to-point connections with reusable interface catalogs.
The EU AI Act and GDPR impose strict audit trails on automated B2B decision systems, compelling vendors to embed consent management and explainability logs into gateway platforms. In the United States, HIPAA and SOC 2 Type II frameworks shape healthcare and financial services procurement criteria, filtering non-compliant vendors from RFP shortlists. Stakeholders must monitor how NIS2 cybersecurity directives in Europe and emerging FedRAMP requirements in North America redefine certification baselines before their next platform refresh cycles.
Market Dynamics
Direct API-to-ERP connectivity is collapsing traditional EDI broker networks as automotive and retail enterprises demand millisecond-order synchronization with tier-one partners. This structural shift forces middleware vendors to re-architect around real-time event streaming rather than batch document exchange.
Growth Catalysts
- GDPR Article 30 mandates:German automotive suppliers now require certified data processing agreements in all B2B gateway contracts, accelerating replacement of uncertified legacy systems.
- Cloud elasticity:European retail chains deploy auto-scaling gateway clusters to handle Black Friday transaction volumes without permanent infrastructure overbuild.
- Real-time inventory visibility:Just-in-sequence manufacturing lines at BMW and Volkswagen plants demand sub-second ASN (Advance Shipping Notice) validation.
Market Restraints
- Skilled integration architect scarcity:Boomi and MuleSoft certified professionals command 40% salary premiums in Frankfurt and Munich labor markets.
- Air-gapped security requirements:Defense contractors in classified supply chains cannot migrate to cloud gateways, fragmenting vendor R&D priorities.
- Schema standardization deadlock:EDIFACT, X12, and proprietary JSON formats coexist without convergence, multiplying mapping complexity for multi-national deployments.
Strategic Opportunities
- EU AI Act compliance modules:Automated decision logging for B2B pricing and credit approvals creates attach-rate potential for explainability software.
- Healthcare data interoperability:HIPAA-compliant gateway services for US hospital supply chains remain underpenetrated relative to retail and automotive saturation.
- Edge gateway nodes:Convergence of 5G latency guarantees and containerized micro-gateways enables factory-floor document processing without cloud round-trips.
Industry Challenges
- Mainframe EDI stack retirement:COBOL-based translation engines at Fortune 500 manufacturers lack documentation, forcing risky rip-and-replace projects.
- FedRAMP authorization timelines:Cloud gateway vendors targeting US federal contractors face 18-24 month certification cycles that freeze product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B Gateway Software Market |
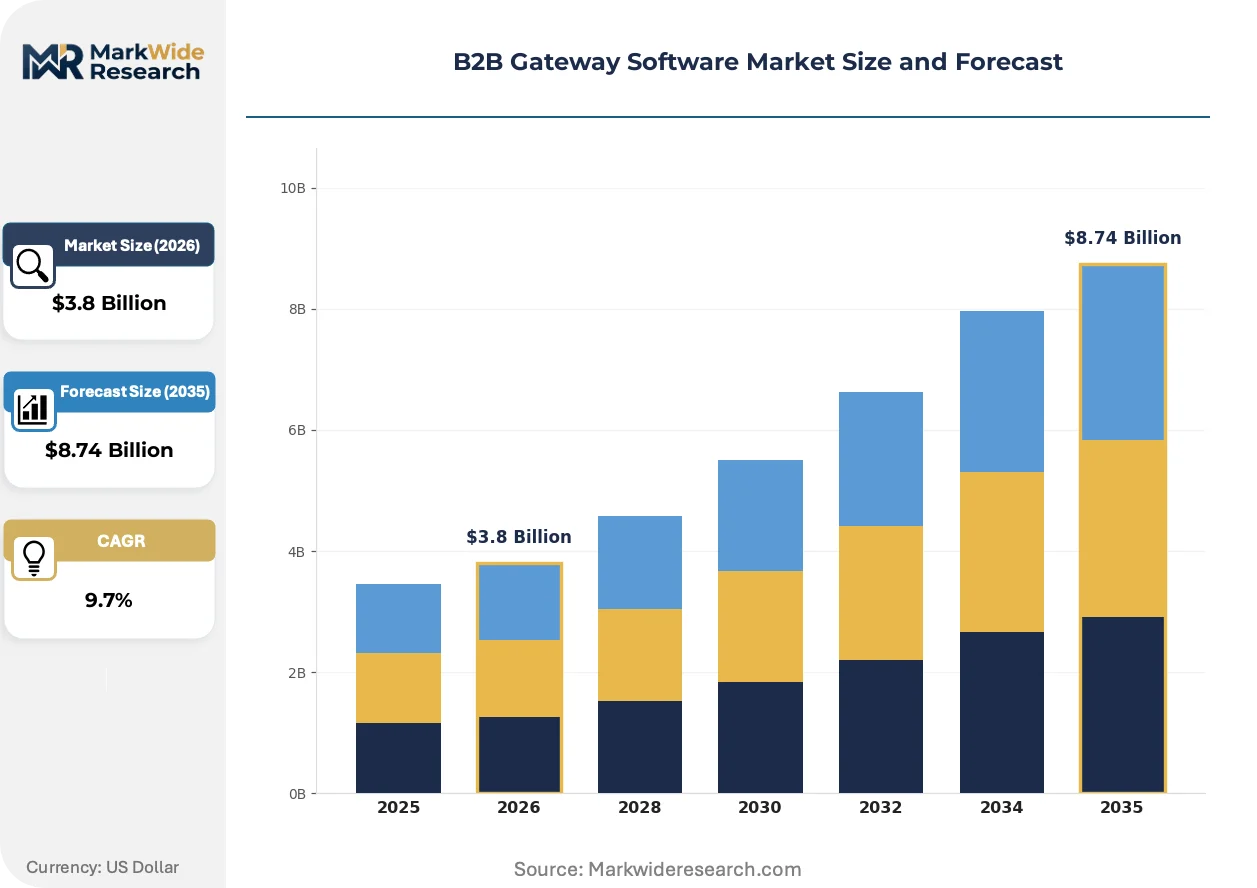
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud Service Type: Integration Services, Consulting, Technical Support, Managed Services End User: Manufacturers, Retailers, Distributors, Service Providers Solution: API Management, Data Transformation, EDI Solutions, Middleware |
| Companies Covered | Talend, Snaplogic, MuleSoft, Celigo, Jitterbit, Boomi, TIBCO Software, Workato, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B Gateway Software Market Strategic Shifts
Event-driven architecture is displacing scheduled batch processing as the dominant integration paradigm. This shift compresses document exchange latency from hours to seconds and enables predictive supply chain orchestration previously impossible with legacy polling mechanisms.
GraphQL query layers are collapsing REST API sprawl in multi-party supply networks. German automotive suppliers at BMW and Continental adopt federated schemas to consolidate supplier endpoints. The technology collapses point-to-point integration counts from hundreds to single gateway entry points.
EU AI Act risk classification rules now mandate human-in-the-loop checkpoints for automated B2B credit decisions. Financial services procurement teams in Frankfurt and Paris embed consent logging requirements into gateway RFPs. Vendors respond with embedded audit trail modules that capture decision rationale without exposing proprietary algorithms.
Subscription-based gateway pricing is displacing perpetual license models among mid-market distributors. European wholesalers prefer OpEx structures that align costs with transaction volumes. This shift concentrates in Benelux and Nordic markets where CFOs prioritize balance sheet flexibility over depreciation schedules.
B2B Gateway Software Market Segmentation
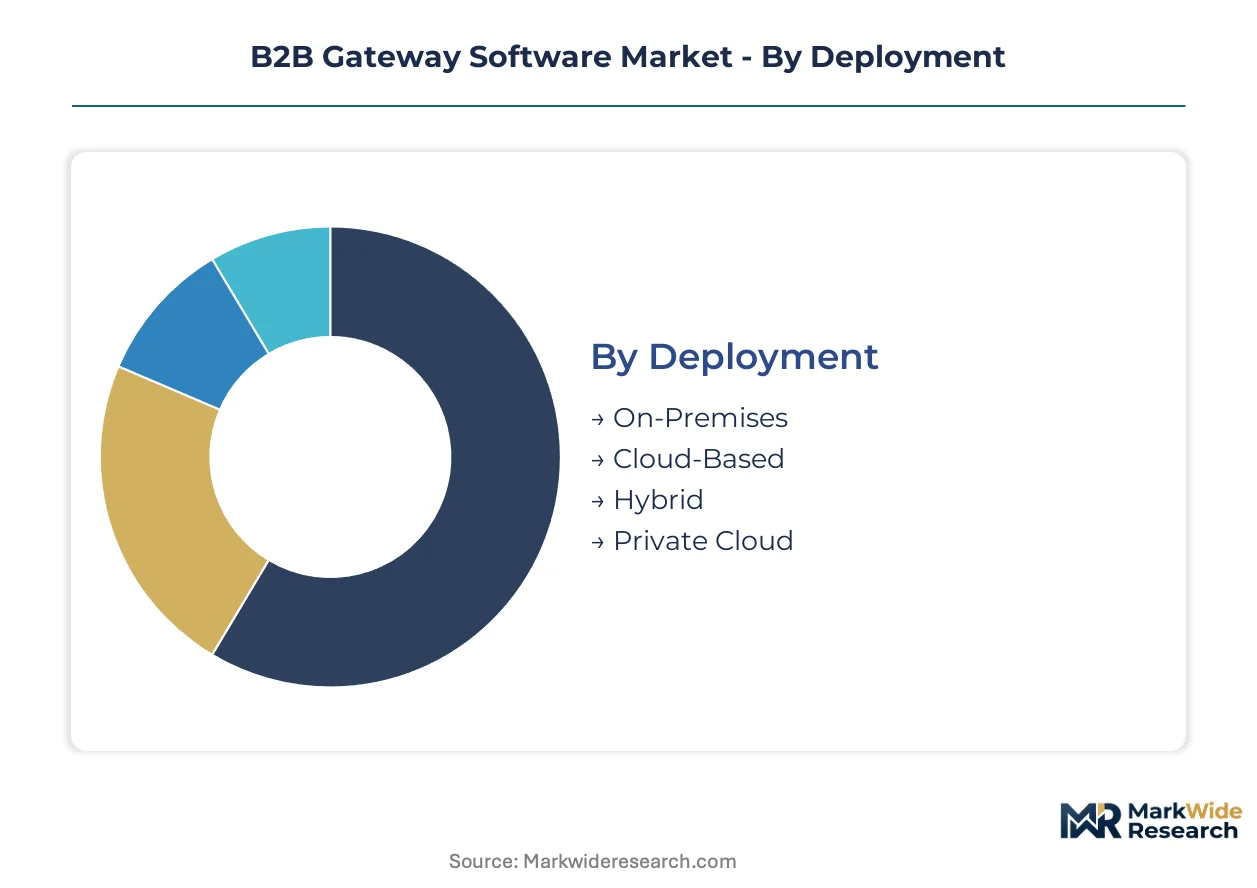
B2B gateway software segments reflect divergent technical requirements across enterprise maturity levels. Deployment models separate security-conscious defense contractors from elasticity-seeking retailers. Service types and solution stacks further stratify based on integration complexity and in-house technical capacity.
Deployment:
Cost tier structures the deployment landscape, with capital intensity and operational flexibility driving procurement decisions across enterprise segments.
- On-Premises:Hardware-resident gateway stacks operate within enterprise data centers with full physical control over encryption keys and audit logs. Defense contractors in classified supply chains mandate air-gapped installations, freezing this segment's share despite cloud migration pressures elsewhere.
- Cloud-Based:Multi-tenant SaaS platforms deliver elastic transaction capacity without permanent infrastructure commitment. European retail chains in Germany and France deploy auto-scaling clusters for seasonal demand spikes, converting fixed costs to variable spend aligned with transaction volumes.
- Hybrid:Split architectures route sensitive documents through on-premises nodes while pushing non-critical traffic to cloud tiers. Automotive suppliers at BMW and Volkswagen plants use this model to isolate proprietary design data while leveraging cloud analytics for supplier performance dashboards.
- Private Cloud:Single-tenant hosted environments replicate on-premises security postures with outsourced infrastructure management. Swiss pharmaceutical manufacturers and French aerospace subcontractors favor this middle path for GDPR Article 30 compliance without direct hardware ownership.
On-Premises retains the established installed base among regulated industries. The steepest expansion runs through Cloud-Based deployments as mid-market distributors prioritize OpEx flexibility.
Service Type:
Application complexity determines service procurement patterns, with integration maturity dictating whether enterprises buy outcomes or build capabilities.
- Integration Services:Project-based implementation of gateway connectivity between specific ERP and partner systems. German automotive tier-one suppliers consume these services for just-in-sequence EDI onboarding, compressing deployment timelines from quarters to weeks.
- Consulting:Advisory engagements mapping legacy EDI architectures to modern API strategies. Fortune 500 manufacturers in the United States engage consultants for COBOL stack retirement planning, mitigating rip-and-replace risks through phased migration roadmaps.
- Technical Support:Break-fix and maintenance contracts ensuring gateway uptime through vendor expertise. Mid-market distributors in Benelux markets purchase tiered support packages with guaranteed response SLAs for critical trading partner connections.
- Managed Services:Fully outsourced gateway operations including partner onboarding, schema mapping, and compliance monitoring. Healthcare supply chains in the United States adopt managed models to satisfy HIPAA audit requirements without expanding internal IT headcount.
Integration Services commands the established revenue base. Managed Services is climbing the fastest as CFOs prioritize balance sheet flexibility over capability building.
End User:
Customer type segmentation tracks how procurement authority and technical sophistication vary across supply chain positions.
- Manufacturers:OEMs and contract producers requiring high-velocity document exchange with tiered supplier networks. BMW and Continental plants mandate sub-second ASN validation for just-in-sequence production lines.
- Retailers:Omnichannel merchants needing elastic gateway capacity for promotional surges and seasonal demand. Benelux and Nordic retail chains lead cloud gateway adoption among this cohort.
- Distributors:Wholesale intermediaries managing many-to-many connectivity between fragmented supplier and customer bases. Mid-market distributors favor low-code onboarding tools to reduce technical dependency.
- Service Providers:Logistics, financial, and data intermediaries embedding gateway capabilities into value-added offerings. European freight forwarders integrate customs documentation gateways into track-and-trace platforms.
Manufacturers retain the deepest installed base. Retailers are gaining share fastest as digital commerce intensifies partner connectivity requirements.
Solution:
Maturity levels differentiate solution segments, with legacy EDI coexistence and emerging API strategies creating parallel demand tracks.
- API Management:Catalog, security, and governance layers for reusable REST and GraphQL interfaces. German automotive suppliers at BMW adopt federated schemas to collapse hundreds of point-to-point integrations into single gateway entry points.
- Data Transformation:Schema mapping engines translating between EDIFACT, X12, JSON, and proprietary formats. High-velocity EDI transactions at automotive and retail enterprises demand sub-millisecond transformation latency.
- EDI Solutions:Traditional AS2, SFTP, and value-added network connectivity for structured document exchange. Defense contractors and long-tenured manufacturers maintain these stacks for partner compatibility despite API migration pressures.
- Middleware:General-purpose integration buses handling both B2B and internal application connectivity. Hybrid cloud environments leverage middleware for unified orchestration across on-premises ERP and cloud-native services.
EDI Solutions anchors the legacy installed base. API Management shows the steepest expansion trajectory as real-time inventory visibility becomes competitive table stakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by CNIL and BfDI anchors European procurement criteria, while HIPAA compliance requirements shape United States healthcare adoption patterns.
United States
Federal contractors drive FedRAMP-authorized gateway procurement for classified supply chain connectivity. HIPAA audit requirements from HHS Office for Civil Rights filter vendor shortlists for hospital supply chains. Healthcare clusters in Nashville and Boston mandate SOC 2 Type II certification for B2B document exchange platforms.
Germany
Automotive suppliers at BMW and Volkswagen plants require sub-second ASN validation for just-in-sequence manufacturing lines. BfDI enforcement of GDPR Article 30 mandates certified data processing agreements in all gateway contracts. Industrial corridors in Bavaria and Baden-Württemberg concentrate EDI replacement spending among tier-one suppliers.
France
CNIL sanctions for inadequate consent logging accelerate explainability module adoption in financial services procurement. EU AI Act risk classification rules embed human-in-the-loop checkpoints for automated credit decisions. Paris-based banking consortia embed audit trail requirements into gateway RFP specifications.
United Kingdom
Post-Brexit customs documentation complexity drives freight forwarder investment in multi-protocol gateway stacks. FCA guidelines on operational resilience shape financial services vendor selection criteria. London fintech clusters adopt GraphQL federated schemas to collapse supplier endpoint sprawl.
Switzerland
Swissmedic serialization requirements for pharmaceutical track-and-trace mandate validated gateway architectures. FINMA operational risk frameworks elevate audit trail capabilities in procurement scoring. Basel and Geneva pharmaceutical manufacturers favor private cloud deployments for GDPR Article 30 compliance without direct hardware ownership.
B2B Gateway Software Market Competitive Environment
Cloud-native specialists and legacy integration incumbents split the market along deployment architecture lines. Consolidation pressure concentrates among mid-market distributors seeking low-code onboarding capabilities. Three archetypes dominate: hyperscaler-aligned platforms, independent integration pure-plays, and ERP-embedded gateway modules. Competitive moves center on API catalog expansion and managed services attach-rate growth.
Within the independent pure-play tier, MuleSoft, Boomi, and Informatica occupy positions spanning hybrid cloud connectivity, low-code tooling, and high-velocity data transformation respectively. Talend represents the open-source-originated archetype with European commercial traction. Celigo and Workato exemplify the low-code-native segment targeting mid-market distributor onboarding efficiency. Jitterbit, Snaplogic, and TIBCO Software anchor specialized positions across event-streaming, AI-augmented mapping, and legacy EDI modernization vectors.
| Leading Market Players |
|---|
| Talend |
| Snaplogic |
| MuleSoft |
| Celigo |
| Jitterbit |
| Boomi |
| TIBCO Software |
| Workato |
| Informatica |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp logistics corridor compresses gateway software delivery timelines for European automotive suppliers, concentrating vendor pricing power among certified integrators while forcing mid-market distributors toward standardized SaaS tiers that sacrifice customization for cost predictability.
Pricing Analysis
The customization-premium spread separates configured-to-order implementations from off-the-shelf SaaS tiers, with subscription-based models now dominating European retail procurement while project-based integration services retain pricing power among German automotive tier-one suppliers. Price differentiation hinges on GDPR Article 30 certification grade and transaction volume scale, with certified vendors commanding substantial premiums over uncertified competitors. Cost compression in the mid-market SaaS tier is intensifying as low-code platforms commoditize basic EDI connectivity. Healthcare supply chains exhibit the highest price sensitivity due to constrained IT budgets, while defense contractors show the least sensitivity given air-gapped security requirements that limit vendor choice.
Supply Chain Analysis
Contract manufacturing concentration for gateway hardware appliances rests with Foxconn, Jabil, and Flex facilities in Taiwan, Mexico, and Poland, while software development capacity clusters in India, Ireland, and the United States. Component dependencies include cryptographic security modules from Thales and Gemalto, cloud infrastructure from AWS and Azure hyperscale regions, and specialized EDI translation engines from a shrinking pool of COBOL-literate developers. Single-source vulnerability in legacy EDI stack maintenance poses acute supply chain risk as retiring mainframe specialists leave undocumented codebases. Distribution runs through direct enterprise sales teams for large manufacturers, value-added resellers for mid-market distributors, and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
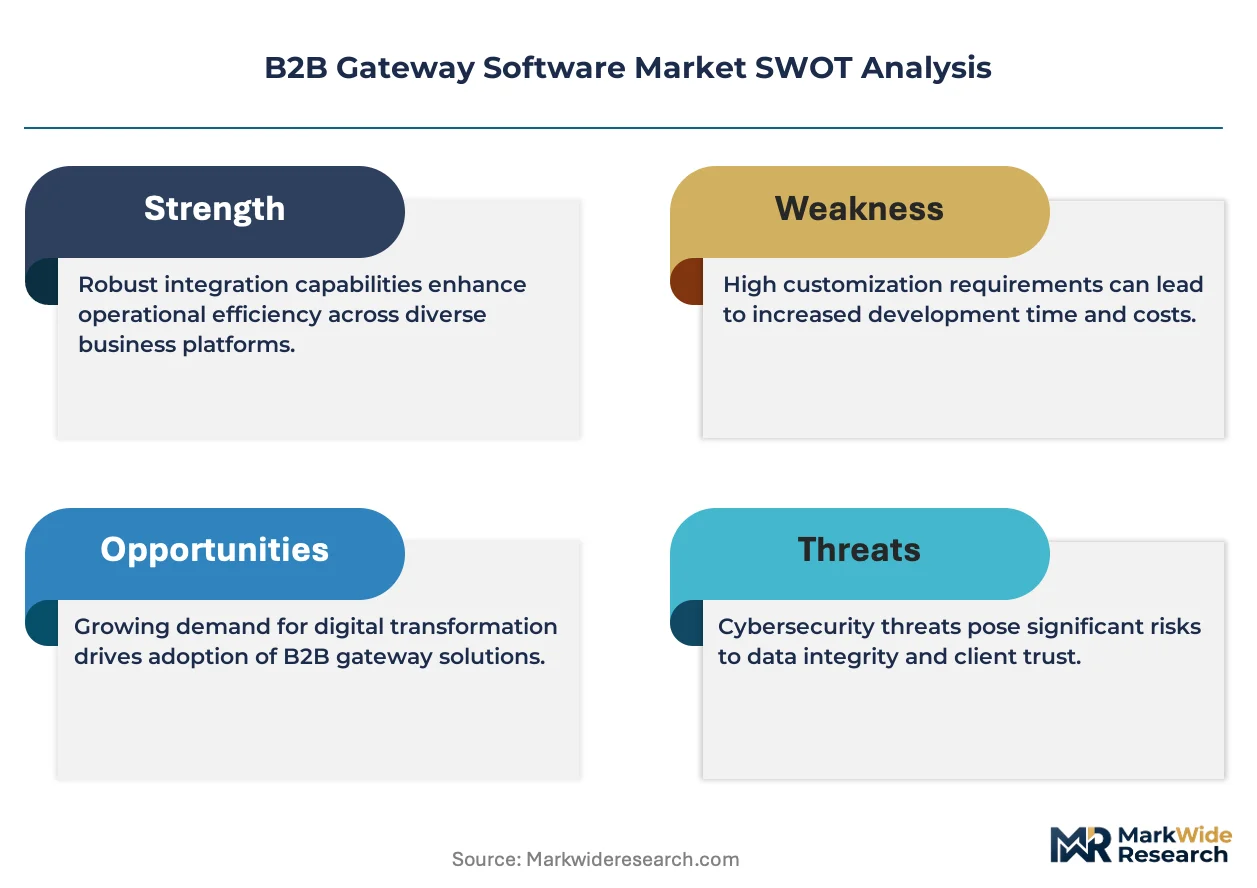
The acute scarcity of Boomi and MuleSoft certified integration architects in Frankfurt and Munich labor markets—where salary premiums reach 40%—creates structural bottlenecks that constrain vendor expansion and inflate implementation costs across the European automotive supply base.
For Market Incumbents: Insulate recurring revenue streams by embedding managed services attach-rates into core gateway contracts, and accelerate certification investments for EU AI Act compliance modules before competitor platforms achieve explainability feature parity. The threat of low-code-native entrants commoditizing basic EDI connectivity demands defensive consolidation of implementation partner networks. For New Entrants and Emerging Players: Healthcare data interoperability in the United States represents the most penetrable white-space target, where HIPAA-compliant gateway services remain underdeveloped relative to retail and automotive saturation. A direct-to-hospital-system sales model bypassing traditional distributor channels offers the clearest go-to-market angle for specialized compliance-first platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from ERP vendors seeking to divest non-core integration modules, particularly legacy EDI stacks that lack cloud-native architecture but retain sticky installed bases among defense and manufacturing accounts. Long-term viability favors platforms with federated GraphQL capabilities and embedded AI audit trails. The signal to watch is FedRAMP authorization velocity among cloud gateway vendors targeting federal contractor segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Federated GraphQL schemas at BMW collapse hundreds of point-to-point supplier connections into unified gateway entry points. |
| Acquisition of Specialist Firm | Low-code onboarding specialists accelerate mid-market distributor penetration without proportional headcount expansion. |
| Geographic Expansion | Private cloud deployments in Swiss pharmaceutical corridors capture GDPR Article 30 compliance demand without direct hardware ownership. |
| Product Launch | Edge gateway nodes with 5G latency guarantees enable factory-floor document processing without cloud round-trips at Volkswagen plants. |
| Strategic Partnership | Hyperscaler alliances embed gateway capabilities into AWS and Azure marketplaces, reducing enterprise procurement friction. |
Study Parameters
Desk research of vendor SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across automotive, retail, and healthcare verticals. Primary fieldwork with German automotive tier-one suppliers, Benelux retail chains, and US hospital supply chains informed demand-side validation, while bottom-up and top-down triangulation against secondary trade data anchored volume estimates.
Assumptions regarding GDPR enforcement intensity, FedRAMP authorization timelines, and cloud migration velocity were held fixed across baseline scenarios while sensitivity analysis varied automotive production schedules and healthcare IT spending cycles. The analytical framework modeled deployment models, organization size tiers, vertical industry segments, integration complexity levels, and regional adoption patterns throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators, with specific inputs including EDI transaction volume growth at BMW and Volkswagen plants and cloud gateway adoption rates among Nordic retail chains.
Practitioners should monitor NIS2 cybersecurity directive implementation timelines and emerging FedRAMP authorization backlogs for early signals of vendor competitive positioning shifts. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and hyperscaler infrastructure investment patterns. Cross-checking against IEA digital infrastructure spending benchmarks and EU automotive production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
BIM Objects Software Market
Software & Services
App Uninstall Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
HCS Software and Services Market
Software & Services
Family Office Software Solutions Market
Software & Services
Life Sciences Software Market
Software & Services
Home Design Software Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Vlog Editing Software Market
Software & Services
Software Testing Tools Market
Software & Services
Lifecycle Management Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Vending Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Product Lifecycle Management Software Market