
 Global Project Software Market | 2026-2036
Global Project Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Project Software Market Foresight
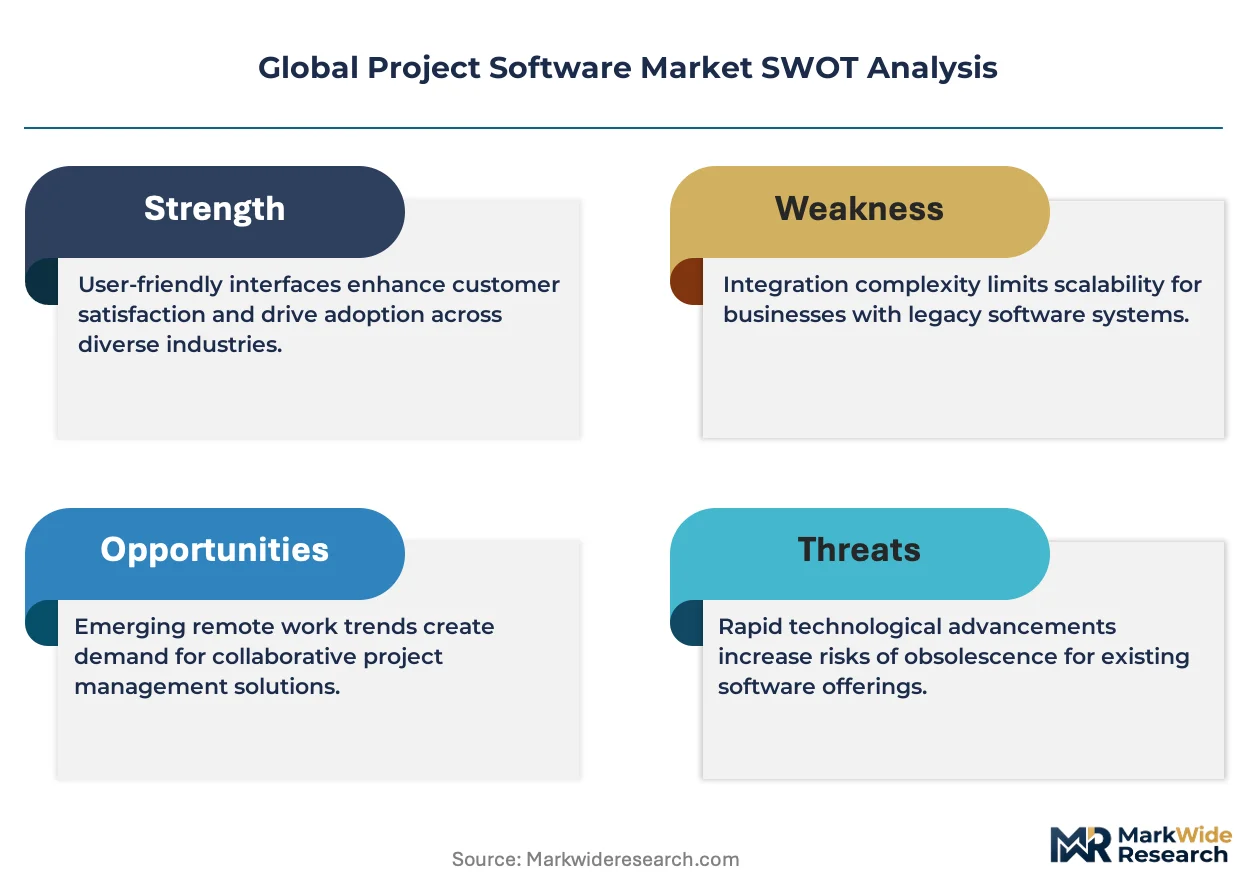
Enterprise-grade security certification is unwinding competitive barriers for premium project software vendors. Microsoft Corporation leverages its Azure cloud infrastructure to anchor large government and defense contracts with FedRAMP-authorized deployments. Atlassian Corporation Plc specializes in developer-centric workflows, sustaining dominance among agile software teams through deep Jira-Confluence integration. Oracle Corporation competes in capital-intensive industries by bundling project software with ERP databases for unified financial tracking.
Project software encompasses applications that plan, execute, and monitor work across distributed teams through Gantt charting, critical path analysis, and real-time resource leveling algorithms. These systems integrate with enterprise data warehouses to automate budget variance alerts and milestone dependency mapping. Cloud-based deployment leads solution type adoption as construction and IT services buyers prioritize remote accessibility and API extensibility over on-premise control. Task management and resource scheduling command the largest margin pools within solution types, while risk management modules represent the fastest-expanding segment as capital project complexity rises.
FDA 21 CFR Part 11 shapes validation requirements for project software used in pharmaceutical clinical trials, mandating electronic signature audit trails. The EU AI Act and GDPR jointly constrain automated resource allocation algorithms in European deployments, forcing transparency disclosures for machine-learning-driven scheduling recommendations. ISO 27001 certification has become a baseline procurement filter across regulated industries. Stakeholders must weigh compliance investment against vertical specialization depth when selecting expansion targets.
Market Dynamics
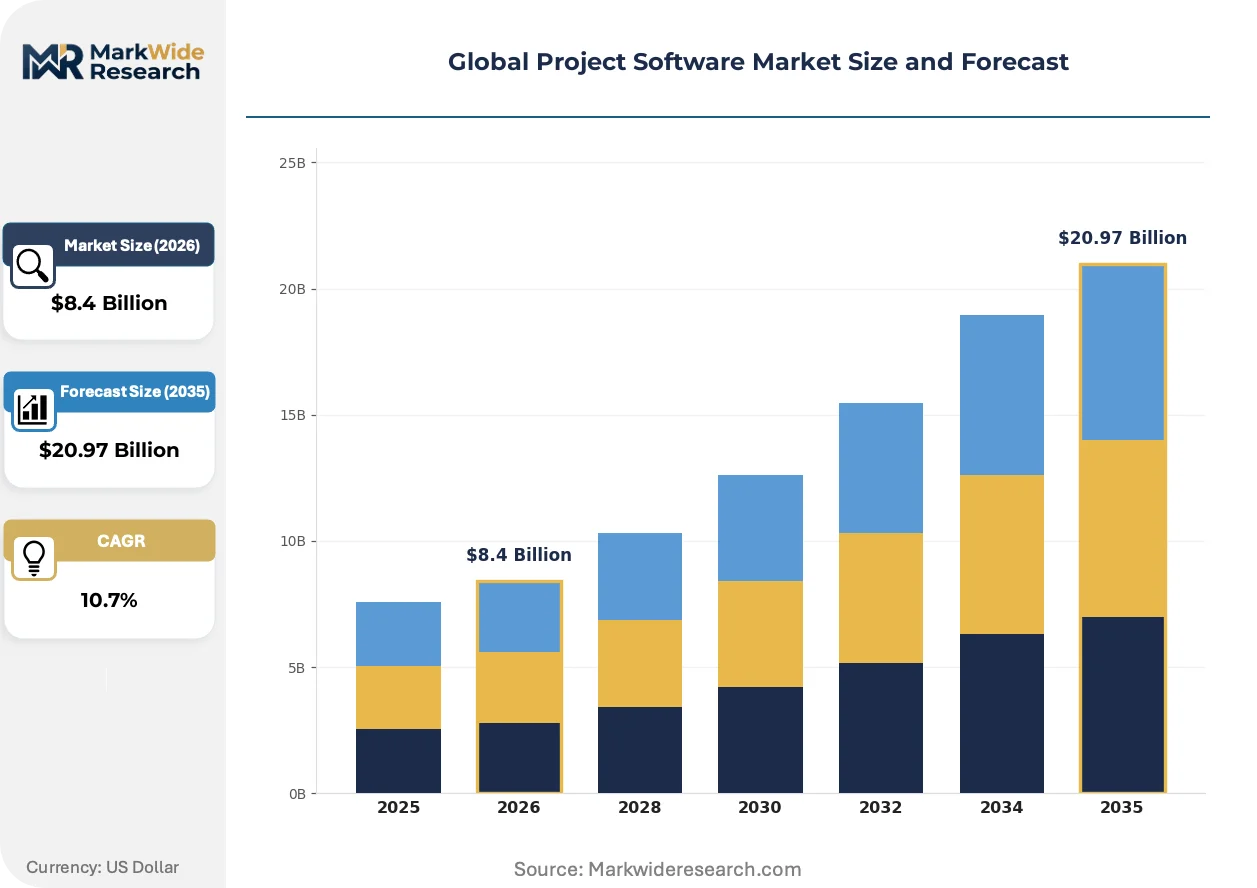
Cloud migration is compressing deployment cycles while the EU AI Act forces algorithmic transparency into resource scheduling modules, creating a dual pressure on vendors to modernize infrastructure and embed compliance architecture simultaneously.
Growth Catalysts
- Construction sector digitization:Capital project owners in the United States mandate integrated BIM-to-scheduling workflows, pulling cloud-native platforms into greenfield developments and infrastructure renewals.
- FedRAMP authorization:US federal procurement rules now require FedRAMP Moderate or High for project software handling CUI, opening defense and civilian agency contracts to certified vendors.
- API-first architectures:Open integration standards let pharmaceutical firms embed project milestones directly into CTMS platforms, collapsing handoff latency between clinical operations and regulatory submission teams.
Market Restraints
- Specialized talent scarcity:Implementation of ISO 27001-certified deployments requires certified security architects and GxP validation specialists, with median search timelines exceeding four months in North American and European labor pools.
- Data residency fragmentation:Divergent national cloud sovereignty laws in Germany, France, and China force vendors to maintain region-segregated infrastructure, raising fixed cost bases without proportional revenue expansion.
- Legacy ERP entrenchment:Oracle and SAP database footprints in heavy industry create switching friction that delays cloud migration decisions by 18-36 months even where TCO favors replacement.
Strategic Opportunities
- India infrastructure buildout:National highway and smart city projects under the PLI scheme generate demand for localized project software with Hindi interface support and domestic data center hosting.
- CSRD mandate convergence:European sustainability reporting rules require capital project carbon tracking, creating attach revenue for emissions monitoring modules within existing scheduling platforms.
- Edge-to-cloud orchestration:Convergence of 5G field connectivity with containerized microservices enables real-time resource reallocation at remote construction sites previously dependent on batch synchronization.
Industry Challenges
- FDA 21 CFR Part 11 validation:Pharmaceutical buyers require documented IQ/OQ/PQ protocols for electronic signatures and audit trails, extending sales cycles by 6-9 months and demanding specialized compliance engineering headcount.
- Multi-tenant security architecture:Isolating government, healthcare, and commercial workloads on shared infrastructure while maintaining FedRAMP, HIPAA, and ISO 27001 attestations simultaneously strains engineering bandwidth and third-party audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Project Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.97 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Type: Task Management, Resource Scheduling, Budget Tracking, Collaboration Platforms, Risk Management End User Industry: Construction, IT Services, Manufacturing, Consulting, Telecommunications Pricing Model: Subscription, Perpetual License, Freemium, Pay-As-You-Go, Enterprise License |
| Companies Covered | Microsoft Corporation, Atlassian Corporation Plc, Oracle Corporation, ServiceNow Inc., SAP SE, Broadcom Inc., Asana Inc., Smartsheet Inc., monday.com Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Project Software Market Shifts & Advancements
Generative AI is penetrating project documentation and risk forecasting workflows, while regulatory pressure on algorithmic decision-making forces architectural choices that prioritize explainability over raw prediction accuracy.
Natural language interfaces for project status queries are bifurcating user adoption patterns. Large engineering-construction firms deploy conversational analytics for executive dashboards, compressing reporting preparation from hours to minutes. This capability is enabling self-service analytics among non-technical stakeholders while marginalizing traditional business intelligence specialist roles within project management offices.
The EU AI Act's risk classification system imposes mandatory human oversight on high-risk automated scheduling decisions in European deployments. Vendors must now implement "human-in-the-loop" checkpoints for machine-learning-driven resource allocation, adding latency to previously instantaneous optimization runs. Pharmaceutical and energy infrastructure buyers in Germany and France are prioritizing vendors with pre-built compliance documentation over feature-rich alternatives lacking regulatory pre-certification.
Consolidated platform procurement is displacing best-of-breed point solutions in enterprise accounts. United States-based buyers with $500M+ project portfolios now mandate unified vendor relationships spanning scheduling, risk, and financial modules, collapsing the addressable market for standalone task management tools. Construction and IT services verticals show the fastest consolidation velocity, with RFP language increasingly specifying single-platform architectures and penalizing integration-heavy proposals.
Global Project Software Market Segmentation
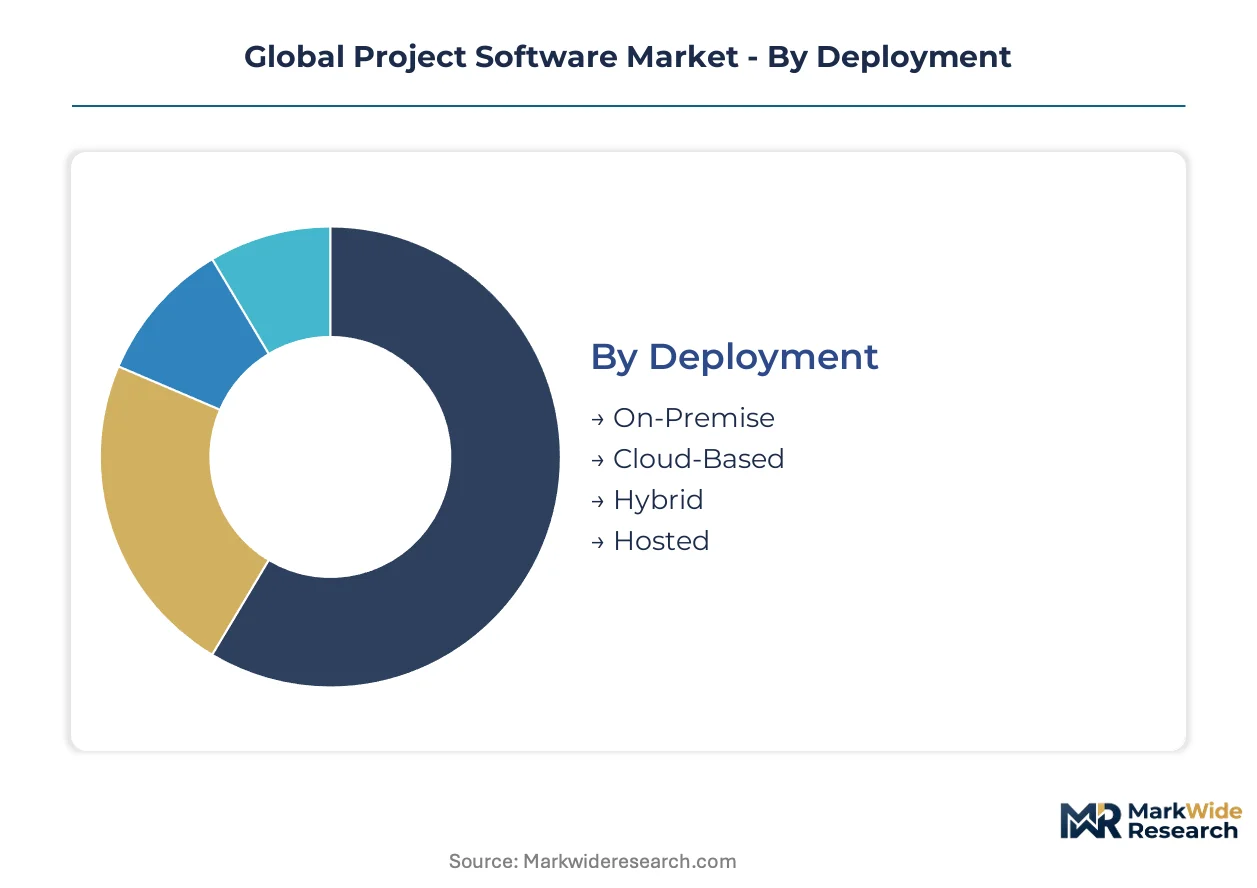
Project software buyers fragment sharply across deployment preferences and pricing sensitivity, forcing vendors to maintain parallel engineering tracks for cloud-native architectures and legacy-compatible systems. Segmentation clarity determines whether providers capture construction firms migrating from spreadsheets or defend entrenched positions in regulated pharmaceutical environments.
Deployment:
Cloud-based platforms face substitution pressure from hybrid configurations as data residency mandates multiply across national jurisdictions.
- Cloud-Based:Multi-tenant SaaS architectures with API extensibility dominate new procurement in United States construction and IT services verticals. FedRAMP authorization requirements filter vendor eligibility for federal contracts, compressing the qualified supplier pool.
- On-Premise:Air-gapped installations persist in defense and classified research environments where network segmentation mandates physical infrastructure control. German industrial buyers under BSI IT-Grundschutz frameworks maintain on-premise preference for critical path systems.
- Hybrid:Split workloads synchronize sensitive financial data on-premise while pushing collaboration features to cloud edge nodes.
- Hosted:Single-tenant managed deployments serve mid-market buyers lacking internal DevOps capacity but rejecting multi-tenant risk profiles.
Cloud-based deployments anchor the volume base while hybrid configurations gain share at the steepest rate.
Solution Type:
Margin concentration follows module complexity, with resource scheduling commanding premium pricing against commoditized task tracking.
- Resource Scheduling:Algorithm-driven leveling engines optimize labor and equipment allocation across interdependent workstreams. Pharmaceutical clinical trial managers in Switzerland and the United States demand GxP-validated scheduling with audit trail immutability.
- Risk Management:Monte Carlo simulation modules quantify schedule and cost uncertainty for capital projects exceeding $100 million contract value. Energy infrastructure developers in Norway and Australia prioritize predictive risk analytics for offshore construction exposure.
- Task Management:Kanban and Gantt visualization tools serve distributed software development teams with lightweight workflow orchestration.
- Budget Tracking:Earned value management integration links cost performance indices to milestone completion for defense procurement compliance.
- Collaboration Platforms:Document co-authoring and threaded discussion features consolidate communication previously fragmented across email and instant messaging.
Task management modules anchor the volume base while risk management gains share at the steepest rate.
End User Industry:
Vertical specialization depth determines vendor defensibility, with construction and IT services presenting divergent integration requirements.
- Construction:BIM-to-scheduling interoperability mandates pull cloud platforms into greenfield developments across United States infrastructure renewals. PLI scheme projects in India generate localized demand for Hindi interface support and domestic data center hosting.
- IT Services:Agile methodology alignment and DevOps toolchain integration dominate procurement criteria for software development consultancies in Israel and Ireland.
- Manufacturing:Shop floor integration with MES systems requires real-time production schedule synchronization for automotive and aerospace suppliers.
- Consulting:Time-and-materials billing automation drives professional services adoption with granular effort capture against client engagements.
- Telecommunications:5G rollout project coordination across tower construction, fiber deployment, and spectrum licensing creates multi-workstream complexity.
Construction anchors the volume base while IT services gains share at the steepest rate.
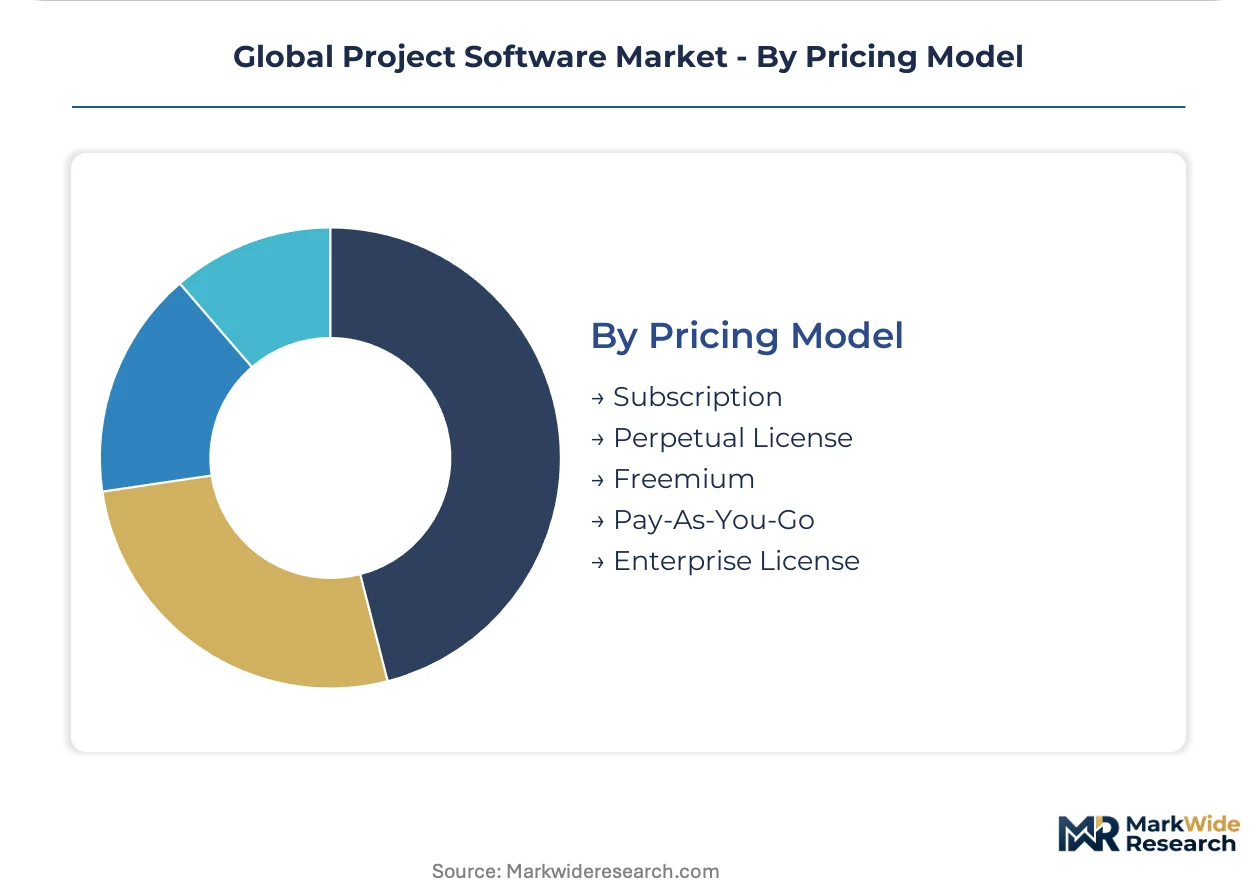
Pricing Model:
Revenue predictability separates subscription economics from lumpy perpetual license recognition, reshaping vendor cash flow profiles.
- Subscription:Monthly or annual recurring revenue models align vendor incentives with customer success outcomes and reduce upfront capital expenditure barriers. United States enterprise buyers with $500 million plus project portfolios increasingly mandate subscription flexibility for portfolio scaling.
- Enterprise License:Unlimited user deployments with custom SLA terms serve consolidated platform procurement mandates in Fortune 500 accounts.
- Perpetual License:One-time purchase with maintenance contracts persists in public sector procurement constrained by capital budget cycles.
- Freemium:Feature-limited entry tiers convert individual users and small teams to paid plans through storage and integration limits.
- Pay-As-You-Go:Consumption-based metering for compute-intensive simulation workloads matches cost to actual platform utilization.
Subscription pricing anchors the volume base while enterprise license structures gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit the highest price elasticity, squeezing margins on standardized task management modules, while United States and Swiss pharmaceutical buyers absorb premium pricing for GxP-validated scheduling systems without volume contraction.
United States
Defense agencies and civilian departments mandate FedRAMP Moderate or High authorization for project software handling controlled unclassified information, compressing the qualified vendor pool for federal contracts. Infrastructure renewal programs across the Midwest and Southeast pull cloud-native platforms into greenfield developments requiring BIM-to-scheduling interoperability. Seattle and Austin host the densest concentrations of enterprise SaaS buyers consolidating procurement around unified vendor relationships.
Germany
BSI IT-Grundschutz frameworks sustain on-premise preference for critical path systems among automotive and industrial machinery producers. The EU AI Act's risk classification system imposes mandatory human-in-the-loop checkpoints for machine-learning-driven resource allocation in pharmaceutical and energy deployments. Munich and Stuttgart anchor demand for hybrid configurations that synchronize sensitive financial data on-premise while pushing collaboration features to cloud edge nodes.
India
National highway and smart city projects under the PLI scheme generate localized demand for Hindi interface support and domestic data center hosting. CDSCO validation requirements for clinical trial project software extend sales cycles but open attach revenue for compliance documentation modules. Mumbai and Bengaluru concentrate procurement from IT services consultancies prioritizing agile methodology alignment and DevOps toolchain integration.
Switzerland
Pharmaceutical clinical trial managers demand GxP-validated scheduling with audit trail immutability, sustaining premium pricing for specialized vendors. Swissmedic oversight shapes validation protocols for electronic signatures in project documentation workflows. Basel and Zurich host the highest density of buyers bundling project software with CTMS platforms to collapse handoff latency between clinical operations and regulatory submission teams.
United Kingdom
CSRD mandate convergence requires capital project carbon tracking, creating attach revenue for emissions monitoring modules within existing scheduling platforms. GDPR constraints on automated resource allocation algorithms force transparency disclosures for machine-learning-driven recommendations. London anchors procurement from professional services firms automating time-and-materials billing with granular effort capture against client engagements.
Global Project Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud-native specialists commanding premium pricing for API extensibility while legacy ERP bundlers compete on total cost of ownership for capital-intensive industries. The vendor base organizes into three tiers: hyperscale cloud platforms with FedRAMP authorization, agile-workflow specialists with deep developer ecosystem integration, and ERP-anchored suites bundling project modules with financial databases. Consolidation pressure favors unified platform procurement mandates in Fortune 500 accounts, collapsing addressable market for standalone task management tools. Dominant competitive moves include strategic partnerships embedding project milestones into vertical CTMS platforms and geographic expansion targeting India infrastructure buildout with localized hosting.
Within the hyperscale tier, Microsoft Corporation and Oracle Corporation occupy positions anchored by cloud infrastructure and database bundling respectively. Atlassian Corporation Plc exemplifies the agile-workflow specialist archetype, sustaining dominance among software development teams through ecosystem integration depth. These three entities collectively represent the strategic poles—cloud authorization, ERP bundling, and developer-centric workflow—that structure competitive positioning across construction, pharmaceutical, and IT services verticals.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Atlassian Corporation Plc |
| Oracle Corporation |
| ServiceNow Inc. |
| SAP SE |
| Broadcom Inc. |
| Asana Inc. |
| Smartsheet Inc. |
| monday.com Ltd |
| Others |
Supply & Pricing Matrix
Azure-scale infrastructure amortization across multi-tenant SaaS architectures compresses marginal delivery costs for cloud-native vendors while erecting price floors that exclude subscale competitors from FedRAMP-authorized procurement channels. This scale dynamic concentrates supply-side leverage among hyperscale platforms capable of absorbing compliance engineering overhead across dispersed geographic deployments.
Pricing Analysis
FedRAMP authorization dictates the pricing tier structure for project software serving United States federal agencies, with Moderate and High baseline certifications separating premium vendor tiers from uncertified alternatives excluded from CUI-handling contracts. Pricing stratifies across GxP-validated, ISO 27001-certified, and standard SaaS tiers based on audit trail immutability and security architecture depth. Cost compression in the mid-market stems from freemium conversion friction and API commoditization. Indian infrastructure buyers exhibit highest price elasticity, while Swiss pharmaceutical procurement absorbs premium pricing without volume contraction.
Supply Chain Analysis
Data center chokepoints in Northern Virginia, Frankfurt, and Mumbai anchor global SaaS delivery for project software vendors serving regulated industries with residency mandates. Engineering talent pools draw from Bangalore, Tel Aviv, and Dublin for platform development, while compliance documentation specialists concentrate in Basel and Boston. Single-source vulnerability runs through hyperscaler cloud infrastructure dependencies. Distribution runs through direct enterprise sales teams with vertical specialization, supplemented by systems integrators embedding project milestones into CTMS and ERP deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Project software markets reward defensive moats built on regulatory entrenchment, where certification backlogs and validation protocols create 18-36 month switching friction that protects incumbent revenue bases.
For Market Incumbents: Compound platform consolidation momentum by bundling risk management and carbon tracking modules into existing scheduling subscriptions before standalone competitors achieve GxP validation. Acquire specialized compliance engineering teams in Basel and Boston to compress pharmaceutical sales cycles threatened by FDA 21 CFR Part 11 documentation delays. Capacity addition in Mumbai and Bengaluru captures India PLI scheme infrastructure demand with localized Hindi interfaces and domestic hosting. For New Entrants and Emerging Players: Differentiate on edge-to-cloud orchestration for remote construction sites lacking reliable connectivity, where 5G field deployment creates whitespace incumbents have deprioritized. Target mid-market consulting firms in London and New York with time-and-materials billing automation that Oracle and SAP bundles underserve. Pursue API-first partnerships with CTMS vendors rather than direct platform competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists with pre-built compliance documentation for EU AI Act and FDA 21 CFR Part 11 deployments. Long-term viability favors vendors whose validation investments compound into multi-tenant security architectures serving government, healthcare, and commercial workloads simultaneously. Acquisition target archetype: GxP-validated scheduling specialists in Switzerland with immature US federal sales channels. Watch for inflection when CSRD carbon tracking mandates convert attach revenue into core procurement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks defense and civilian agency contracts handling controlled unclassified information under federal procurement rules. |
| GxP Validation Documentation Buildout | Compresses pharmaceutical sales cycles in Basel and Boston by pre-qualifying for Swissmedic and FDA oversight. |
| India Localization Partnership | Captures PLI scheme highway and smart city demand through Hindi interfaces and domestic data center hosting. |
| CTMS Platform Integration | Collapses handoff latency between clinical operations and regulatory submission teams in pharmaceutical deployments. |
| Carbon Tracking Module Attachment | Monetizes CSRD mandate convergence in European capital projects with emissions monitoring embedded in scheduling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory submission databases. Primary interviews engaged CTOs, IT procurement officers at Fortune 500 construction and pharmaceutical enterprises, platform engineers, and GxP validation specialists. Secondary sources encompassed FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, and CDSCO clinical trial software requirements. Bottom-up sizing of deployment models and solution types triangulated against top-down macroeconomic indicators and vertical IT spending patterns.
Segmentation dimensions modeled span cloud-based, on-premise, hybrid, and hosted deployments; resource scheduling, risk management, task management, budget tracking, and collaboration platform modules; construction, IT services, manufacturing, consulting, and telecommunications end-user industries; and subscription, enterprise license, perpetual license, freemium, and pay-as-you-go pricing models. CAGRs were derived from logistic adoption curves fitted to vertical penetration data and compliance mandate implementation timelines. Industry-specific forecast inputs included BIM-to-scheduling interoperability adoption rates and 5G field connectivity deployment trajectories.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU AI Act, and BSI IT-Grundschutz frameworks; material policy shifts would require re-modeling of validation cost structures and sales cycle assumptions. Practitioner judgment applied to pharmaceutical clinical trial manager interviews and construction project owner procurement patterns. Practitioners should keep alternative scenarios live as cloud sovereignty law fragmentation and AI risk classification enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Staffing Software Market
Software & Services
Legal Software Market
Software & Services
App Building Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Fiber Simulation Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
CAM Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Employee Wellness Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Staffing Agency Software Market
Software & Services
CGI Software Market
Software & Services
Global Test Data Management Market