
 Engineering Software Market | 2026-2036
Engineering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Software Market Intelligence
Cloud-native compute infrastructure is expanding access to high-fidelity simulation for mid-tier manufacturers. Autodesk leverages its subscription architecture to sustain recurring engagement across construction and manufacturing verticals. Siemens Digital Industries Software anchors industrial digital-twin deployments through deep automation protocol integration. PTC specializes in IoT-augmented CAD workflows that differentiate its offering for discrete manufacturers seeking closed-loop design feedback.
Engineering software encompasses computer-aided tools for geometric modeling, physics simulation, manufacturing process planning, and lifecycle data management, typically executing finite-element analysis, parametric solid modeling, or toolpath generation with micron-level precision. Its primary purpose is compressing product development cycles while ensuring regulatory-compliant performance validation. CAD and CAE constitute the deepest margin pools due to entrenched workflow dependencies and high switching costs, while cloud-based deployment is the fastest-expanding configuration as aerospace and automotive end users migrate off legacy workstation clusters. PLM adoption lags in smaller construction firms where fragmented project ownership impedes centralized data governance.
OSHA workplace safety standards, FAA airworthiness certification protocols, and the EU AI Act collectively shape engineering software requirements by mandating traceable simulation audit trails and human-in-the-loop decision documentation. Germany's KBA enforces stringent automotive validation rules that CAE vendors must embed to maintain market access. Stakeholders should monitor how divergent transatlantic AI liability frameworks reshape cross-border licensing terms and cloud data residency obligations.
Market Dynamics
Cloud-native simulation platforms are compressing product development cycles for aerospace and automotive manufacturers while forcing legacy workstation vendors to rearchitect licensing models around elastic compute consumption.
Growth Catalysts
- FAA Airworthiness Certification:Mandates for traceable simulation audit trails drive CAE software upgrades across US defense contractors.
- EU AI Act:Algorithmic accountability requirements accelerate human-in-the-loop documentation features in automated design tools.
- Parametric Solid Modeling:Micron-level precision demands in German automotive tooling sustain entrenched CAD workflow dependencies.
Market Restraints
- Cloud Data Residency:Divergent transatlantic AI liability frameworks fragment cross-border licensing terms for SaaS vendors.
- GPU Compute Costs:High-fidelity finite-element analysis consumes specialized hardware cycles that mid-tier manufacturers struggle to provision.
- Construction Sector Fragmentation:Project ownership dispersion in smaller firms impedes centralized PLM data governance adoption.
Strategic Opportunities
- India Manufacturing PLI Scheme:Production-linked incentives for domestic engineering capacity create greenfield digital-twin deployments.
- IoT-CAD Convergence:Closed-loop design feedback systems open discrete manufacturing segments previously locked in static modeling workflows.
- France CNIL Algorithmic Audits:Emerging compliance frameworks for automated decision systems create advisory service revenue streams.
Industry Challenges
- Finite-Element Specialist Shortage:Physics simulation expertise concentrates in aerospace hubs, leaving automotive suppliers talent-constrained.
- Legacy Protocol Integration:Industrial automation stack heterogeneity complicates Siemens-compatible digital-twin deployments for brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Software Market |
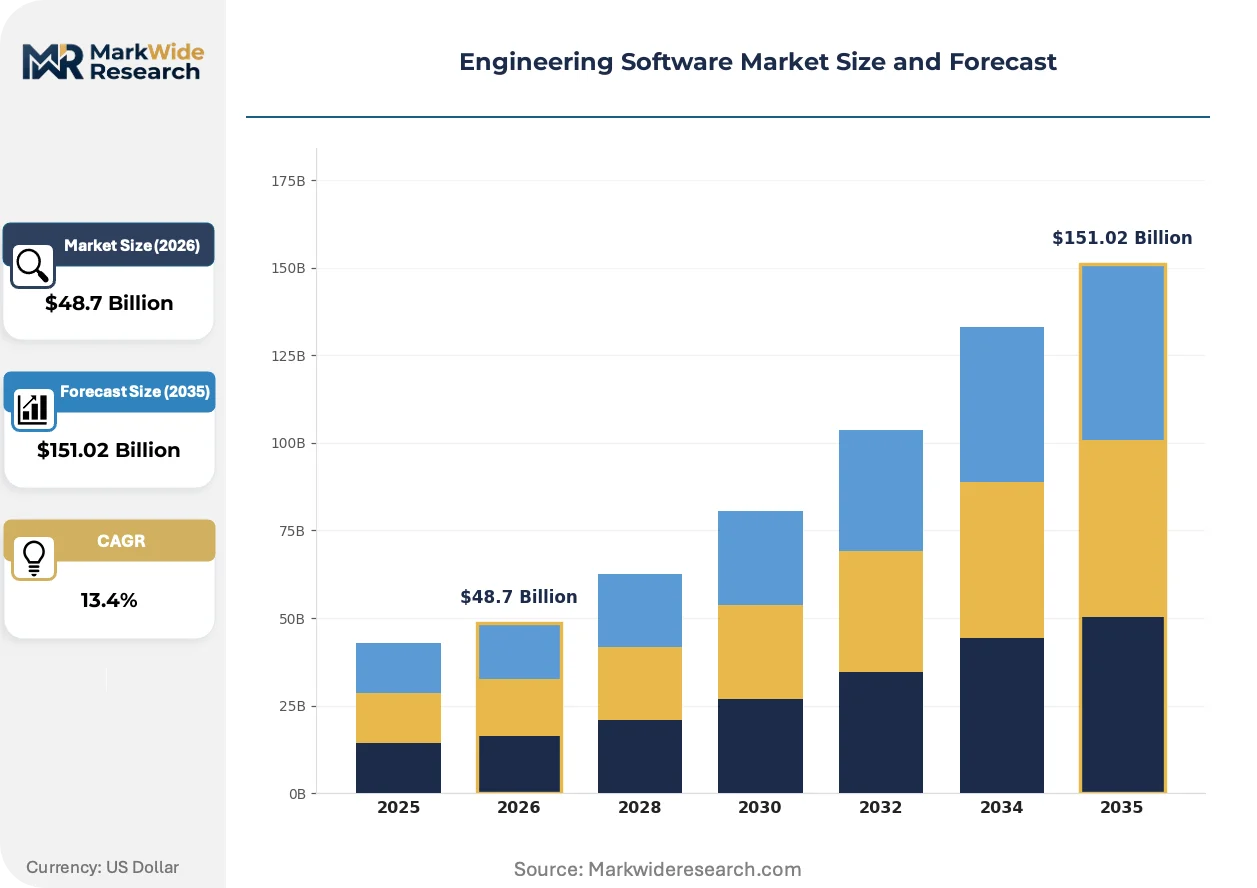
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD, CAM, CAE, PLM Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Aerospace, Automotive, Construction, Electronics Application: Simulation, Design, Analysis, Project Management |
| Companies Covered | Dassault Systèmes, Altair Engineering, Autodesk, Hexagon AB, Bentley Systems, PTC, Ansys, MathWorks, Siemens Digital Industries Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Software Market Strategic Shifts & Innovations
Generative design algorithms and real-time collaborative modeling are restructuring how engineering teams validate performance before physical prototyping.
GPU-accelerated cloud solvers is overtaking on-premise workstation clusters for computational fluid dynamics workloads. Aerospace manufacturers in Texas and California are migrating simulation fleets to elastic infrastructure within eighteen-month procurement cycles. This compression is overtaking perpetual license economics and forcing vendors toward consumption-based pricing.
Germany's KBA automotive validation rules now require embedded CAE traceability for type approval. Tier-1 suppliers must demonstrate reproducible simulation chains across toolchain versions. French and German OEMs are consolidating vendor panels to reduce compliance documentation fragmentation.
Subscription elasticity now dominates enterprise procurement for construction and manufacturing verticals. Multi-year perpetual agreements are contracting to annual renewals with usage-scaled tiers. Defense-adjacent engineering hubs in the United States exhibit the fastest contract-cycle compression as federal acquisition adapts to commercial software velocity.
Engineering Software Market Segmentation
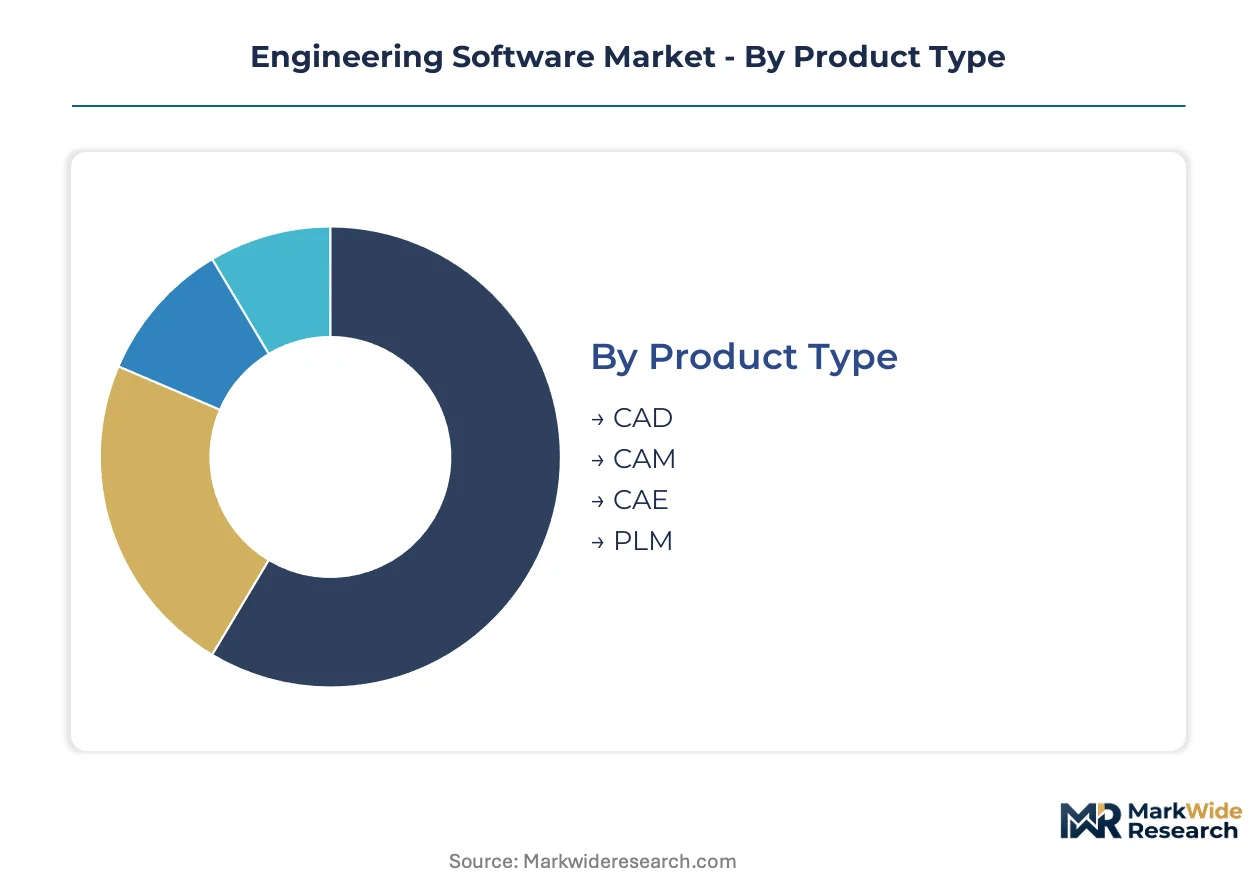
Engineering software segmentation reveals how deployment architectures and end-use specifications reshape vendor pricing power. Product type and deployment mode together determine switching costs and recurring revenue durability across manufacturing verticals.
Product Type:
CAD, CAM, CAE, and PLM modules differ in workflow integration depth and margin structure.
- Computer-Aided Design (CAD):Parametric solid modeling tools execute micron-level geometric precision for German automotive tooling suppliers. Entrenched workflow dependencies in discrete manufacturing sustain the deepest recurring revenue pools and highest switching costs among all product categories.
- Computer-Aided Engineering (CAE):Finite-element analysis and physics simulation platforms compress validation cycles for aerospace manufacturers in Texas and California. FAA airworthiness mandates for traceable audit trails drive upgrade cycles across US defense contractors.
- Computer-Aided Manufacturing (CAM):Toolpath generation software bridges design data to CNC machining operations. Shop-floor protocol heterogeneity complicates vendor consolidation for tier-1 suppliers seeking Siemens-compatible deployments.
- Product Lifecycle Management (PLM):Centralized data governance systems struggle in construction sectors where fragmented project ownership impedes adoption. Smaller firms lack the organizational scale to justify enterprise-wide implementation.
CAD leads on scale; CAE leads on momentum.
Deployment:
Delivery models segment by infrastructure control, cost predictability, and compliance flexibility.
- Cloud-Based:GPU-accelerated elastic compute overtakes on-premise clusters for computational fluid dynamics. Aerospace procurement cycles compress to eighteen-month horizons as manufacturers migrate simulation fleets off legacy workstation infrastructure.
- Software-as-a-Service (SaaS):Subscription elasticity now dominates enterprise construction and manufacturing procurement. Annual renewals with usage-scaled tiers displace multi-year perpetual agreements.
- On-Premise:Perpetual licensing persists in defense-adjacent engineering hubs requiring air-gapped security. Federal acquisition protocols lag commercial software velocity.
- Hybrid:Mixed deployments accommodate EU AI Act data residency constraints while preserving sensitive simulation workloads locally. Divergent transatlantic liability frameworks fragment cross-border licensing terms.
Cloud-Based claims the steepest expansion trajectory; On-Premise retains the most defensive revenue base.
End User:
Vertical specialization dictates feature roadmaps and compliance embedding requirements.
- Aerospace:Cloud-native simulation adoption accelerates around defense-adjacent engineering hubs in Texas and California. FAA certification protocols mandate reproducible simulation chains across toolchain versions.
- Automotive:Germany's KBA enforces stringent CAE traceability requirements for type approval. Tier-1 suppliers consolidate vendor panels to reduce compliance documentation fragmentation.
- Electronics:IoT-augmented design workflows demand closed-loop feedback between field performance and geometric iteration. Miniaturization pressures sustain micron-level precision requirements.
- Construction:Fragmented project ownership and dispersed stakeholder accountability impede centralized PLM governance. Autodesk's subscription architecture targets this gap with lighter-weight collaboration tools.
Automotive leads on scale; Aerospace leads on momentum.
Application:
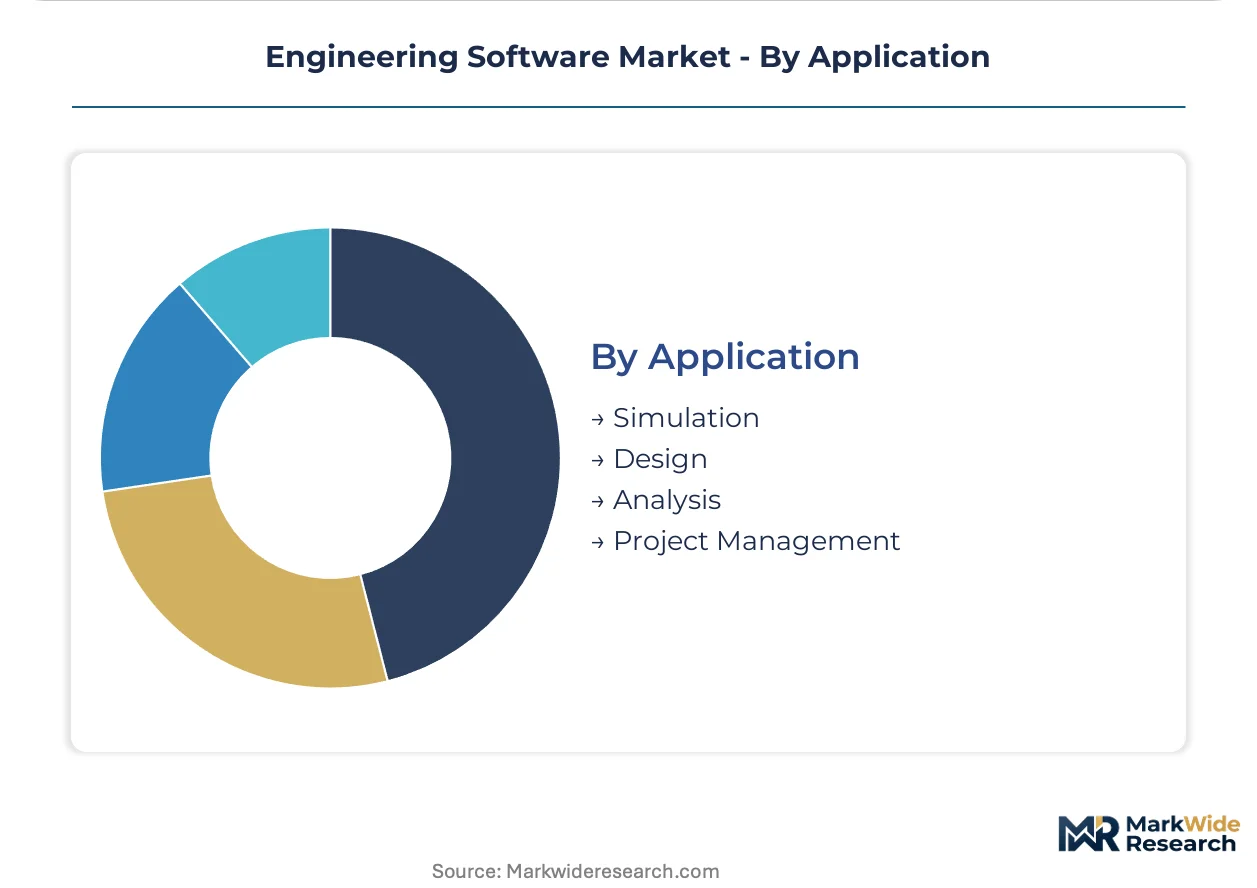
Functional use cases segment by computational intensity and human-in-the-loop documentation requirements.
- Simulation:High-fidelity finite-element analysis consumes specialized GPU cycles that mid-tier manufacturers struggle to provision. Physics expertise concentrates in aerospace hubs, leaving automotive suppliers talent-constrained.
- Design:Generative algorithms and real-time collaborative modeling restructure validation before physical prototyping. French CNIL algorithmic audit frameworks create advisory service revenue streams.
- Analysis:Performance validation tools embed EU AI Act human-in-the-loop documentation features. Algorithmic accountability rules reshape automated decision system requirements.
- Project Management:Lifecycle coordination modules lag in adoption where construction sector fragmentation impedes centralized data governance. Smaller firms prioritize point solutions over integrated suites.
Simulation leads on scale; Design leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense-adjacent engineering hubs in Texas and California anchor current demand concentration for cloud-native simulation platforms. Aerospace procurement cycles in these clusters compress to eighteen-month horizons as manufacturers migrate off legacy workstation infrastructure.
United States
FAA airworthiness certification mandates for traceable simulation audit trails drive CAE software upgrades across defense contractors. OSHA workplace safety standards shape engineering software requirements for human-in-the-loop documentation. Dallas-Fort Worth and Houston engineering clusters accelerate adoption of elastic compute infrastructure for computational fluid dynamics workloads.
Germany
KBA automotive validation rules enforce stringent CAE traceability requirements for type approval that sustain entrenched CAD workflow dependencies. Tier-1 suppliers consolidate vendor panels to reduce compliance documentation fragmentation. Stuttgart and Munich automotive engineering centers embed reproducible simulation chains across toolchain versions.
France
CNIL algorithmic audit frameworks for automated decision systems create advisory service revenue streams for engineering software vendors. EU AI Act compliance requirements accelerate human-in-the-loop documentation features in automated design tools. Toulouse aerospace engineering clusters adopt cloud-native platforms for defense-adjacent simulation workloads.
India
Production-linked incentives for domestic engineering capacity create greenfield digital-twin deployments across automotive and aerospace manufacturing. BIS standards alignment pressures software localization for safety-critical applications. Bengaluru and Pune engineering services hubs expand simulation talent pools for finite-element analysis specialization.
Japan
METI industrial digitalization policies accelerate IoT-augmented CAD workflow adoption for discrete manufacturers seeking closed-loop design feedback. JIS standards compliance shapes software feature roadmaps for precision manufacturing. Nagoya automotive engineering clusters integrate cloud-based PLM systems for supplier coordination.
Engineering Software Market Key Industry Players
Portfolio diversification dominates the current landscape as established industrial software conglomerates and specialized simulation vendors compete for aerospace and automotive procurement contracts. The market structure consolidates around three strategic tiers: diversified industrial technology conglomerates with deep automation protocol integration, specialized physics simulation vendors with entrenched aerospace relationships, and cloud-native challengers attacking mid-tier manufacturing segments. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping vendor consolidation patterns.
Within the diversified conglomerate tier, Siemens Digital Industries Software and Dassault Systèmes exemplify archetypes anchoring industrial digital-twin deployments through deep automation stack integration. Autodesk occupies a position representing the subscription-architecture specialists targeting construction and manufacturing verticals with lighter-weight collaboration tools. Among specialized simulation vendors, Ansys exemplifies the physics-engineering archetype sustaining entrenched relationships with aerospace manufacturers in Texas and California defense clusters.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Altair Engineering |
| Autodesk |
| Hexagon AB |
| Bentley Systems |
| PTC |
| Ansys |
| MathWorks |
| Siemens Digital Industries Software |
| Others |
Cost & Logistics Intelligence
Defense-adjacent engineering hubs in Texas and California anchor demand concentration that forces vendors toward consumption-based subscription models with usage-scaled tiers. FAA certification mandates and EU AI Act compliance requirements create pricing power for CAE vendors embedding traceable audit trails.
Pricing Analysis
GPU compute costs pass through directly to end-user pricing, with elastic consumption tiers replacing perpetual licenses. Pricing stratifies across enterprise, mid-market, and entry-level tiers based on simulation fidelity and compliance certification grade. Cost compression in mid-market segments intensifies because specialized hardware cycles strain manufacturer budgets. Tier-1 aerospace contractors exhibit lowest price sensitivity; smaller construction firms show highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for legacy workstation clusters slow as aerospace manufacturers migrate simulation fleets to cloud-native infrastructure within compressed procurement cycles. Software development concentrates in the United States, Germany, and India, with Bengaluru and Pune engineering services hubs expanding finite-element analysis talent pools. The supply chain draws from specialized GPU hardware vendors and hyperscaler cloud infrastructure providers. Single-source vulnerability in GPU semiconductor supply creates concentration risk. Distribution runs through direct enterprise sales teams and strategic systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering software functions as a stable compounder market where regulatory-mandated compliance upgrades sustain recurring revenue durability across aerospace and automotive verticals.
For Market Incumbents: Cement dominance by deepening automation protocol integration for Siemens-compatible digital-twin deployments in brownfield facilities. Expand cloud-native platform capacity in defense-adjacent Texas and California clusters before emerging GPU-accelerated challengers capture procurement cycles. FAA airworthiness mandates and EU AI Act traceability requirements provide defensive moats against price erosion. For New Entrants and Emerging Players: GPU-accelerated real-time collaborative modeling offers a technology-first wedge into mid-tier automotive suppliers talent-constrained for finite-element expertise. Target India's Production-Linked Incentive manufacturing corridors for greenfield digital-twin deployments without legacy protocol entanglement. Position advisory services around France CNIL algorithmic audit frameworks as a compliance-first go-to-market angle. For Investors and Strategic Acquirers: Industrial technology conglomerates represent the most active acquirer category in this space, seeking physics-simulation capabilities to complete digital-twin portfolios. The five-to-ten-year viability window favors vendors with embedded aerospace relationships and multi-cloud deployment flexibility. Acquisition target archetypes include specialized CAE vendors with reproducible simulation chain technology. Monitor divergence in transatlantic AI liability frameworks as an inflection signal for cross-border licensing complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD-CAE-PLM workflows for German automotive KBA compliance. |
| Strategic Partnership | Secures GPU cloud capacity for Texas aerospace simulation clusters. |
| Acquisition of Specialist Firm | Adds finite-element physics engines for defense contractor upgrade cycles. |
| Geographic Expansion | Captures India's PLI manufacturing incentives for greenfield deployments. |
| Product Launch | Introduces human-in-the-loop documentation for EU AI Act conformity. |
Research Approach
Bottom-up aerospace and automotive modeling reconciled against top-down cloud infrastructure and GPU hardware tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combined with secondary validation against FAA certification databases, EU regulatory filings, hyperscaler capex disclosures, and automotive production records. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map deployment architecture adoption against end-use vertical requirements across the projection horizon. Segmentation dimensions include product type, deployment mode, organization size, vertical specialization, and regional regulatory cluster. CAGRs derive from elasticity modeling of subscription conversion rates and compliance-driven upgrade cycles. Cloud-native migration velocity and finite-element specialist labor supply constraints inform scenario boundaries.
The model holds under stable transatlantic regulatory alignment; deviation in AI liability framework divergence or GPU semiconductor supply disruption would shift vendor consolidation patterns. Practitioners should monitor FAA certification protocol updates and EU AI Act enforcement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Dialer Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Event Management Software Market
Software & Services
Public Financial Management Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Global Remote Work Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
MRP Software Market
Software & Services
HPC Software Market
Software & Services
API Testing Market
Software & Services
Embroidery Design Software Market
Software & Services
Ecommerce Inventory Management Software Market