
 Mainframe Software Market | 2026-2036
Mainframe Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mainframe Software Market Insights
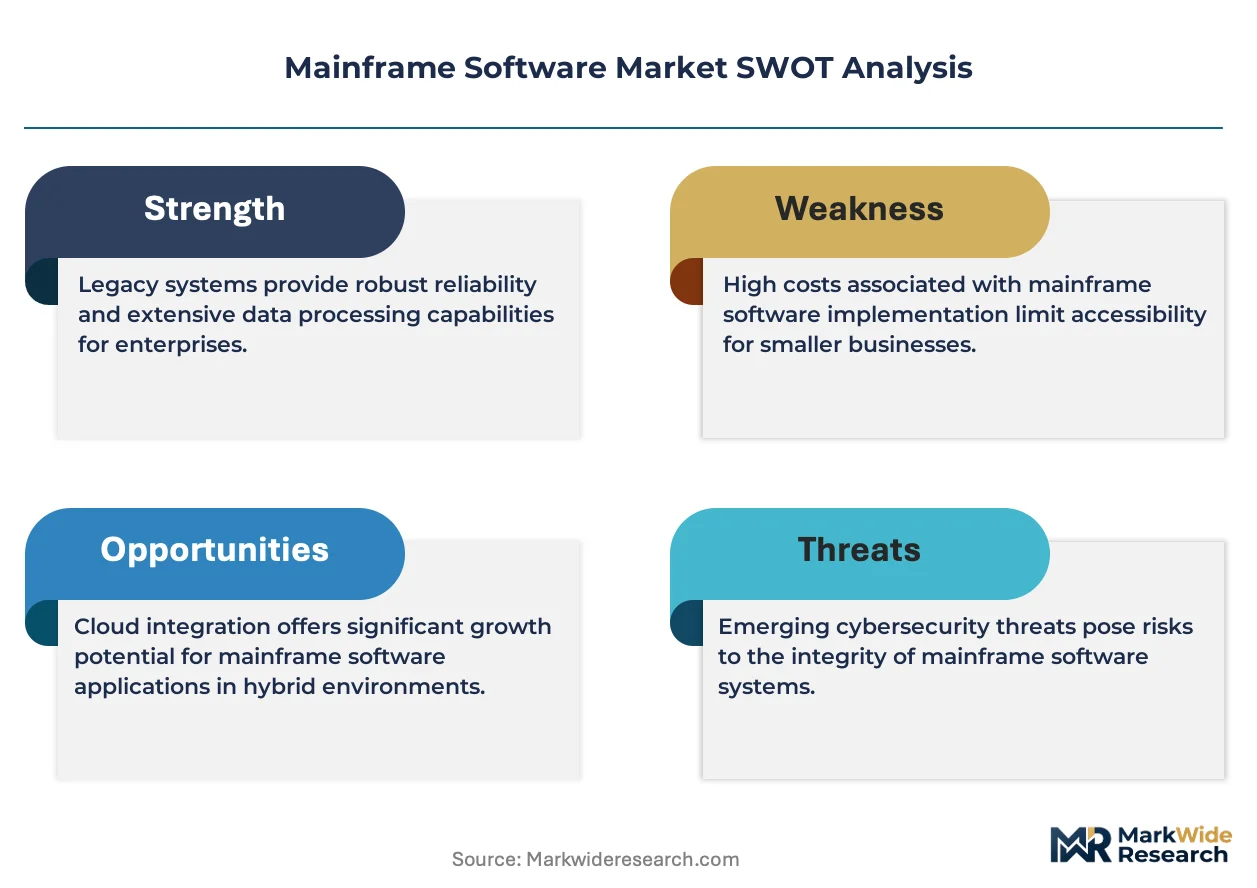
Enterprise-grade security certification tiers is reorganizing procurement priorities across the Mainframe Software Market. IBM Corporation leverages its z/OS ecosystem dominance to sustain long-term contracts with Fortune 500 banking clients. Broadcom Inc. anchors mainframe utility software portfolios through centralized licensing control. BMC Software, Inc. differentiates via automated workload management tools that reduce operational overhead for hybrid deployments.
Mainframe software encompasses operating systems, database management systems, middleware, and security tools engineered to run on IBM Z and compatible architectures, typically supporting millions of transactions per second with 99.999% uptime requirements. These platforms process core banking, insurance claims, and government benefit distributions through centralized, vertically scaled compute. Database management and security software command the strongest margin pools as financial services end users prioritize encryption-at-rest and real-time fraud detection capabilities. Cloud-based and hybrid deployment modes are expanding fastest as organizations phase out pure on-premises footprints without abandoning mainframe transaction integrity.
FDIC, SEC, and FFIEC frameworks in the United States mandate operational resilience and data retention standards that directly shape mainframe software procurement specifications for financial services buyers. The EU Digital Operational Resilience Act and GDPR cross-border data rules impose comparable compliance burdens on European banking infrastructure. Organizations must evaluate vendor roadmaps for quantum-safe cryptography integration and containerized workload portability before committing to next-generation platform contracts.
Market Dynamics
Regulatory mandates for operational resilience are forcing financial institutions to retain mainframe infrastructure while modernizing software layers, creating sustained demand for security-hardened platforms that bridge legacy transaction integrity with hybrid cloud architectures.
Growth Catalysts
- FDIC Operational Resilience Guidelines:United States banking regulators mandate system availability thresholds that require hardened mainframe database management platforms for core transaction processing.
- Hybrid Cloud Integration:Containerized workload portability tools enable phased migration of batch processing to cloud without abandoning mainframe transaction integrity.
- Quantum-Safe Cryptography Mandates:Bundesbank oversight requirements across German central banking infrastructure accelerate procurement of encryption-at-rest capabilities for cross-border settlement systems.
Market Restraints
- Specialized Talent Scarcity:COBOL and z/OS systems programming expertise concentrates among aging workforce cohorts, constraining implementation velocity for complex migrations.
- Vendor Lock-In Concentration:Proprietary licensing architectures around IBM Z ecosystems limit substitution options and inflate long-term contract renewal leverage.
- Legacy Integration Friction:Decades-old custom codebases in insurance claims processing resist containerization, extending deployment timelines for hybrid architectures.
Strategic Opportunities
- EU Digital Operational Resilience Act:DORA compliance deadlines create procurement windows for real-time fraud detection middleware across European banking infrastructure.
- AI-Driven Workload Optimization:Machine learning algorithms converging with automated capacity planning tools reduce operational overhead for hybrid mainframe-cloud deployments.
- Government Benefit Distribution Modernization:Social security agencies in Japan and South Korea initiate mainframe software refresh cycles for population-scale payment systems.
Industry Challenges
- Skills Pipeline Collapse:University computer science curricula have abandoned mainframe systems instruction, forcing enterprises to rely on vendor-sponsored certification programs for z/OS administration.
- Compliance Timeline Compression:GDPR cross-border data rules and quantum-safe migration mandates impose overlapping deadlines that strain IT procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mainframe Software Market |
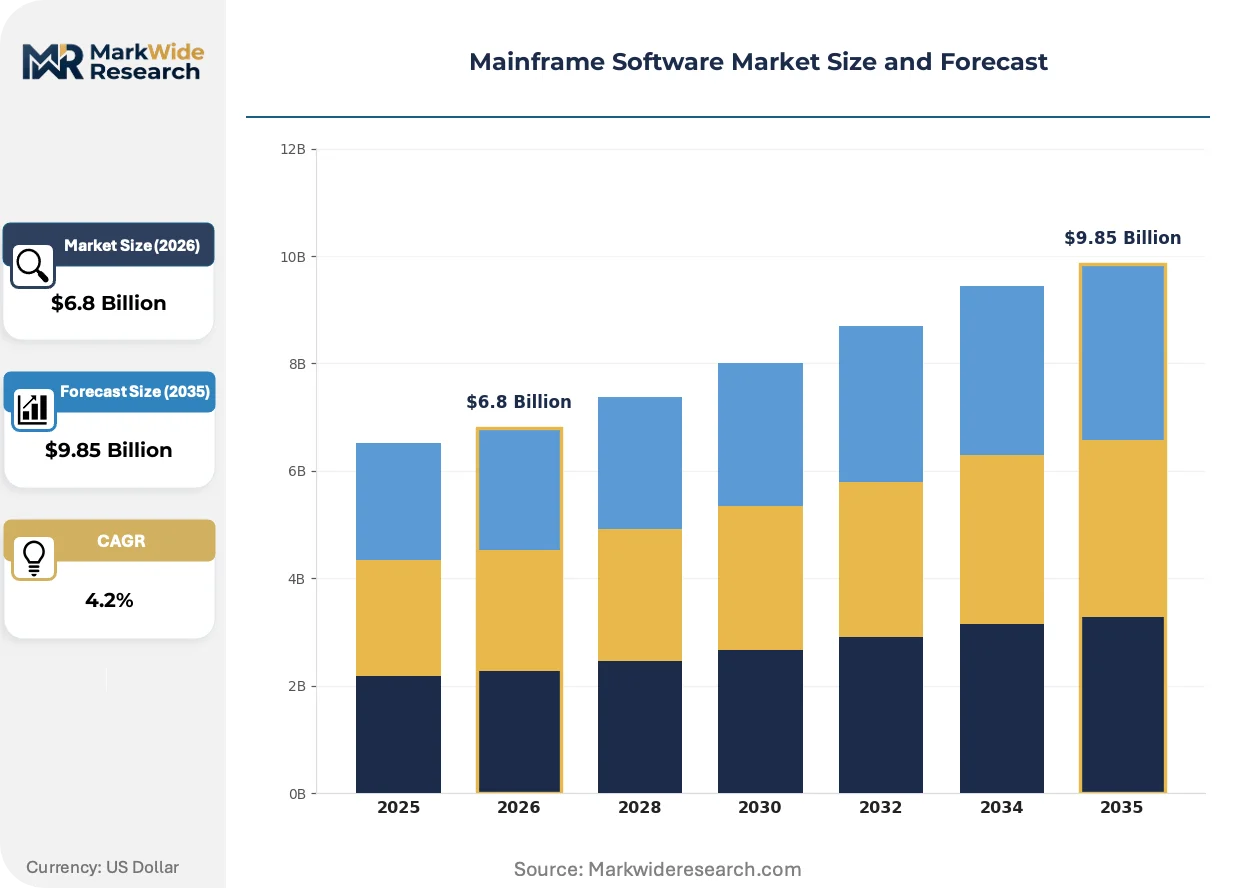
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
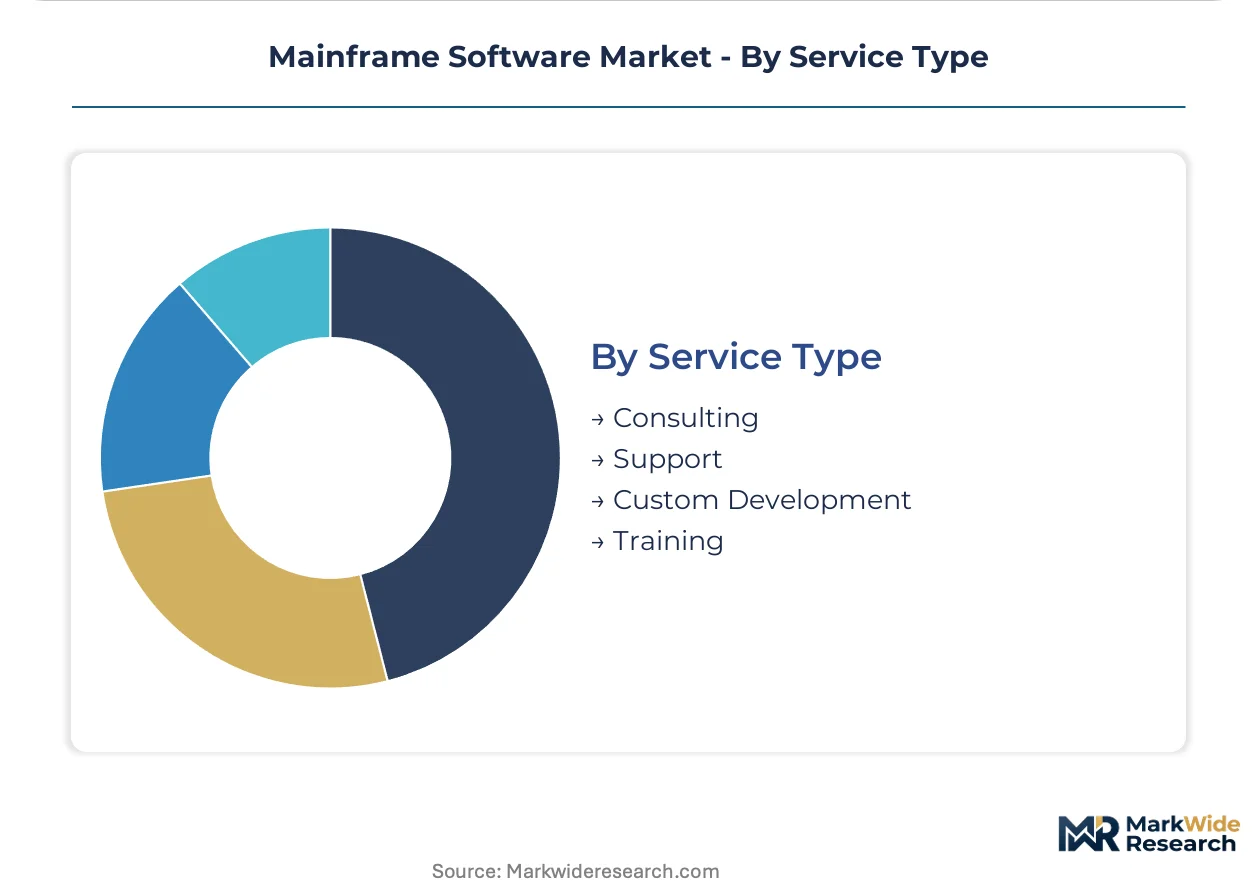
| Segmentation | Product Type: Operating System, Database Management, Middleware, Security Software Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized End User: Financial Services, Healthcare, Government, Telecommunications Service Type: Consulting, Support, Custom Development, Training |
| Companies Covered | CA Technologies, Software AG, IBM Corporation, TmaxSoft, ASG Technologies, Broadcom Inc., Compuware Corporation, Macro 4, BMC Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mainframe Software Market Trends and Innovations
Software-defined mainframe management is supplanting hardware-centric administration models, enabling granular resource allocation across hybrid estates while preserving the transaction throughput that legacy architectures guarantee.
Containerized Linux on IBM Z is supplanting traditional z/OS partition management for development and test workloads, allowing DevOps teams to deploy microservices natively on mainframe iron. Financial services IT departments in Germany and Switzerland are adopting this approach fastest, driven by Bundesbank and Swissmedic data localization requirements. The structural consequence is compression of release cycles from quarterly to weekly without sacrificing production environment stability.
EU AI Act risk classification frameworks are reshaping procurement specifications for automated decisioning tools embedded in mainframe transaction streams. Banking infrastructure buyers must now document algorithmic transparency for credit scoring and fraud detection modules. Italian and French retail banks are front-loading compliance investments ahead of enforcement deadlines, prioritizing vendors with pre-certified explainability tooling.
Consumption-based licensing models are displacing perpetual seat agreements for database management and security software tiers. Large European insurers negotiate transaction-volume pricing that aligns costs with seasonal claims processing peaks. This shift is most visible in the United Kingdom and Netherlands, where Lloyd's syndicates and pension administrators have consolidated vendor relationships around outcome-aligned contracts.
Mainframe Software Market Segmentation

Mainframe software procurement patterns diverge sharply across product tiers and deployment architectures, with financial services buyers prioritizing security-hardened database platforms while government agencies favor on-premises transaction integrity. Understanding these segment boundaries clarifies where vendor roadmaps align with compliance-driven refresh cycles versus cost-optimization mandates.
Product Type:
Database management and security software concentrate demand in export-led financial hubs like Frankfurt and Singapore, while operating system renewals remain anchored in domestic banking infrastructure modernization.
- Database Management:Platforms engineered for encryption-at-rest and real-time fraud detection command premium positioning. Bundesbank oversight requirements in Germany and FDIC resilience mandates in the United States drive concentrated procurement of hardened transaction processing engines.
- Security Software:Quantum-safe cryptography modules and access control frameworks represent the fastest-expanding tier. Swissmedic data localization rules and EU AI Act risk classification frameworks accelerate deployment of explainable security tooling across European banking infrastructure.
- Operating System:z/OS ecosystem renewals sustain long-term vendor relationships through centralized licensing architectures.
- Middleware:Integration layers bridge legacy COBOL codebases with containerized microservices for phased cloud migration.
Database management holds the largest share; momentum sits with security software.
Deployment:
Hybrid architectures dominate procurement specifications where transaction integrity requirements preclude full cloud abandonment, while pure cloud deployments concentrate in development and test environments.
- Hybrid:Containerized workload portability tools enable selective batch processing migration without sacrificing mainframe throughput guarantees. Japanese social security agencies and South Korean pension administrators prioritize this architecture for population-scale payment system modernization.
- Cloud-Based:DevOps teams deploy Linux on IBM Z for microservices-native development, compressing release cycles from quarterly to weekly. Swiss and German financial services IT departments adopt this fastest under strict data localization requirements.
- On-Premises:Pure mainframe estates persist where regulatory data sovereignty mandates prohibit off-premise transaction processing.
- Virtualized:Software-defined resource allocation supplants hardware-centric administration for granular capacity management.
Hybrid deployment captures dominant procurement volume; cloud-based configurations climb fastest among development workloads.
End User:
Financial services generate the majority of security software and database management demand, while government end users sustain operating system renewal cycles through benefit distribution infrastructure.
- Financial Services:Core banking, insurance claims, and cross-border settlement systems require 99.999% uptime with hardened encryption capabilities. Lloyd's syndicates in the United Kingdom and Dutch pension administrators negotiate transaction-volume pricing aligned with seasonal processing peaks.
- Government:Social security and tax administration systems depend on mainframe transaction integrity for population-scale distributions. Japan and South Korea initiate refresh cycles for aging benefit payment platforms.
- Healthcare:Claims processing and patient record systems utilize mainframe batch processing for high-volume administrative workloads.
- Telecommunications:Billing and customer management platforms leverage mainframe throughput for real-time transaction streams.
Financial services anchors revenue concentration; government verticals show steepest procurement acceleration from infrastructure modernization mandates.
Service Type:
Support and consulting services concentrate where specialized z/OS and COBOL expertise scarcity constrains in-house implementation velocity.
- Consulting:Migration architecture design and compliance roadmap planning address quantum-safe cryptography integration and containerized workload portability. European banks front-load DORA compliance investments ahead of enforcement deadlines.
- Support:24/7 operational coverage and incident response sustain production environment stability for core transaction processing.
- Custom Development:Legacy codebase modernization and API layer construction bridge decades-old systems with hybrid architectures.
- Training:Vendor-sponsored certification programs fill pipeline gaps where university curricula have abandoned mainframe systems instruction.
Consulting commands premium pricing; support services generate recurring revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor licensing concentration clusters in economies with the deepest financial services infrastructure and most stringent operational resilience mandates. IBM Z ecosystem dominance persists where regulatory frameworks explicitly require mainframe-grade transaction integrity.
United States
FDIC operational resilience guidelines and SEC data retention mandates drive sustained procurement of hardened database management platforms. Fortune 500 banking clients renew long-term z/OS contracts under FFIEC framework specifications. New York and Charlotte financial clusters anchor concentrated demand for encryption-at-rest capabilities.
Germany
Bundesbank oversight requirements accelerate security-hardened platform deployment across central banking infrastructure. EU Digital Operational Resilience Act deadlines compress procurement cycles for real-time fraud detection middleware. Frankfurt's concentration of cross-border settlement systems generates concentrated demand for quantum-safe cryptography modules.
Japan
Social security agencies initiate mainframe refresh cycles for population-scale benefit distribution systems. METI guidelines shape procurement specifications for hybrid cloud integration tools. Tokyo's government IT clusters prioritize automated workload management for seasonal payment processing peaks.
United Kingdom
Lloyd's syndicates negotiate transaction-volume pricing aligned with insurance claims seasonality. GDPR cross-border data rules and quantum-safe migration mandates impose overlapping compliance deadlines. London's regulatory technology sector drives consumption-based licensing adoption for database management tiers.
Switzerland
Swissmedic data localization requirements accelerate containerized Linux on IBM Z adoption for development workloads. Banking infrastructure buyers prioritize vendors with pre-certified explainability tooling under EU AI Act risk classifications. Zurich and Geneva financial centers compress release cycles from quarterly to weekly without sacrificing production stability.
Mainframe Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the mainframe software market. The vendor base concentrates around centralized licensing architectures that sustain multi-decade customer relationships. Two strategic archetypes dominate: ecosystem incumbents leveraging z/OS platform dominance, and specialized utility providers differentiating through automated operational tooling. Competitive moves center on strategic partnerships for hybrid cloud integration and portfolio diversification into quantum-safe cryptography modules.
Within the ecosystem incumbent tier, IBM Corporation and Broadcom Inc. exemplify contrasting approaches to platform control. IBM Corporation anchors long-term relationships through centralized z/OS licensing architectures. Broadcom Inc. occupies a position focused on utility software consolidation. BMC Software, Inc. represents the specialized automation archetype, with workload management tools reducing operational overhead for hybrid deployments. These three players collectively illustrate how vendor concentration persists despite containerization pressures.
| Leading Market Players |
|---|
| CA Technologies |
| Software AG |
| IBM Corporation |
| TmaxSoft |
| ASG Technologies |
| Broadcom Inc. |
| Compuware Corporation |
| Macro 4 |
| BMC Software, Inc. |
| Others |
Pricing and Supply Chain Analysis
Consumption-based licensing displaces perpetual seat agreements across the mainframe software market, compressing supplier margins in the United States and United Kingdom while concentrating procurement leverage among Fortune 500 banking clients in New York and London. This substitution simultaneously redistributes value capture toward transaction-volume pricing models and reshapes vendor geography toward centralized licensing architectures anchored by IBM Z ecosystem dominance.
Pricing Analysis
FDIC operational resilience guidelines dictate the pricing tier structure for database management platforms across United States financial services procurement. Three-tier pricing structure across enterprise-grade encryption, standard compliance, and economy workload tiers separates hardened security modules from basic transaction processing engines. Cost compression in the economy tier intensifies because containerized Linux alternatives erode z/OS partition premiums. Regional banking consortia exhibit highest price sensitivity; central banking infrastructure in Germany and Switzerland shows lowest sensitivity due to Bundesbank oversight mandates.
Supply Chain Analysis
Specialized COBOL and z/OS systems programming expertise constitutes a chokepoint that underwrites vendor lock-in concentration across the mainframe software supply chain. Software engineering talent concentrates in the United States, Germany, and Japan where vendor-sponsored certification programs feed implementation pipelines. The supply chain draws from aging workforce cohorts, proprietary licensing architectures, and university curriculum gaps. Single-source vulnerability persists around IBM Z ecosystem dependencies. Distribution runs through centralized enterprise licensing agreements with long-term contract renewal cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mainframe software market sits in a cyclical recovery phase driven by overlapping regulatory compliance deadlines across FDIC, EU Digital Operational Resilience Act, and Bundesbank frameworks. Procurement acceleration from infrastructure modernization mandates creates temporary demand expansion before talent scarcity constraints reassert pricing power.
For Market Incumbents: Consolidate automated workload management capabilities through targeted capability acquisition in hybrid cloud integration tooling. Deepen vertical integration into quantum-safe cryptography modules before EU AI Act enforcement deadlines compress procurement windows. Channel control over vendor-sponsored certification programs defends against emerging container-native entrants eroding z/OS partition premiums.
For New Entrants and Emerging Players: FDIC operational resilience certification fast-tracks unlock procurement access to regional banking consortia in the United States seeking alternatives to centralized IBM licensing. White-space targets concentrate in development and test workload containerization for Swiss and German financial services IT departments under strict data localization requirements. Consumption-based pricing models penetrate fastest among Lloyd's syndicates and Dutch pension administrators negotiating seasonal transaction-volume alignment.
For Investors and Strategic Acquirers: The market sits at a pre-enforcement phase that favors specialized automation tooling providers over ecosystem incumbents. Long-term viability over the next decade hinges on containerized workload portability capabilities bridging legacy COBOL codebases with hybrid architectures. Acquisition target archetype: automated capacity planning vendors with pre-certified explainability tooling under EU AI Act risk classifications. The signal to watch is quantum-safe cryptography mandate acceleration across cross-border settlement systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized Linux on IBM Z compresses release cycles for Swissmedic-regulated development workloads in Zurich. |
| Strategic Partnership | Hybrid cloud alliances enable phased batch migration without abandoning mainframe transaction integrity for Japanese social security agencies. |
| Acquisition of Specialist Firm | Automated workload management capabilities reduce operational overhead for Lloyd's syndicates processing seasonal insurance claims peaks. |
| Geographic Expansion | EU Digital Operational Resilience Act compliance investments front-load procurement windows for real-time fraud detection middleware across Frankfurt banking infrastructure. |
| Product Launch | Quantum-safe cryptography modules address Bundesbank oversight requirements for encryption-at-rest in German central banking cross-border settlement systems. |
Research Methodology
A spread of perspectives from mainframe systems architects, IT procurement officers at financial services institutions, regulatory compliance leads, and vendor product managers converged on the working assumptions shaping this analysis. Primary interviews with z/OS administration specialists and hybrid cloud integration engineers combined with secondary validation from SEC filings, FFIEC framework documentation, Bundesbank oversight circulars, and EU Digital Operational Resilience Act regulatory texts. Bottom-up transaction-volume modeling and top-down ecosystem revenue triangulation anchored quantitative outputs.
Segmentation dimensions modeled span product type, deployment architecture, end-user vertical, and service tier across the analysis window. Deployment mode differentiation between hybrid, cloud-based, on-premises, and virtualized configurations captured procurement pattern divergence. Financial services, government, healthcare, and telecommunications verticals tracked compliance-driven refresh cycles versus cost-optimization mandates. CAGRs derived from historical contract renewal velocity and regulatory deadline clustering without year-specific assumptions.
Decision-makers should treat outputs as directional under sustained FDIC operational resilience enforcement and EU AI Act risk classification implementation; material deviation would warrant model refresh. Forecasts reflect assumptions around specialized talent pipeline stability and containerized workload adoption curves. Revision becomes warranted when quantum-safe cryptography mandate acceleration crosses implementation capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global ITSM Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Inventory Management Software Market
Software & Services
App Uninstall Software Market
Software & Services
Global Personalisation Software Market
Software & Services
Global Directory Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Tableau Services Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Note Taking App Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Global Self-Service BI Market