
 Europe Digital Signage Software Market | 2026-2036
Europe Digital Signage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Signage Software Market Foresight
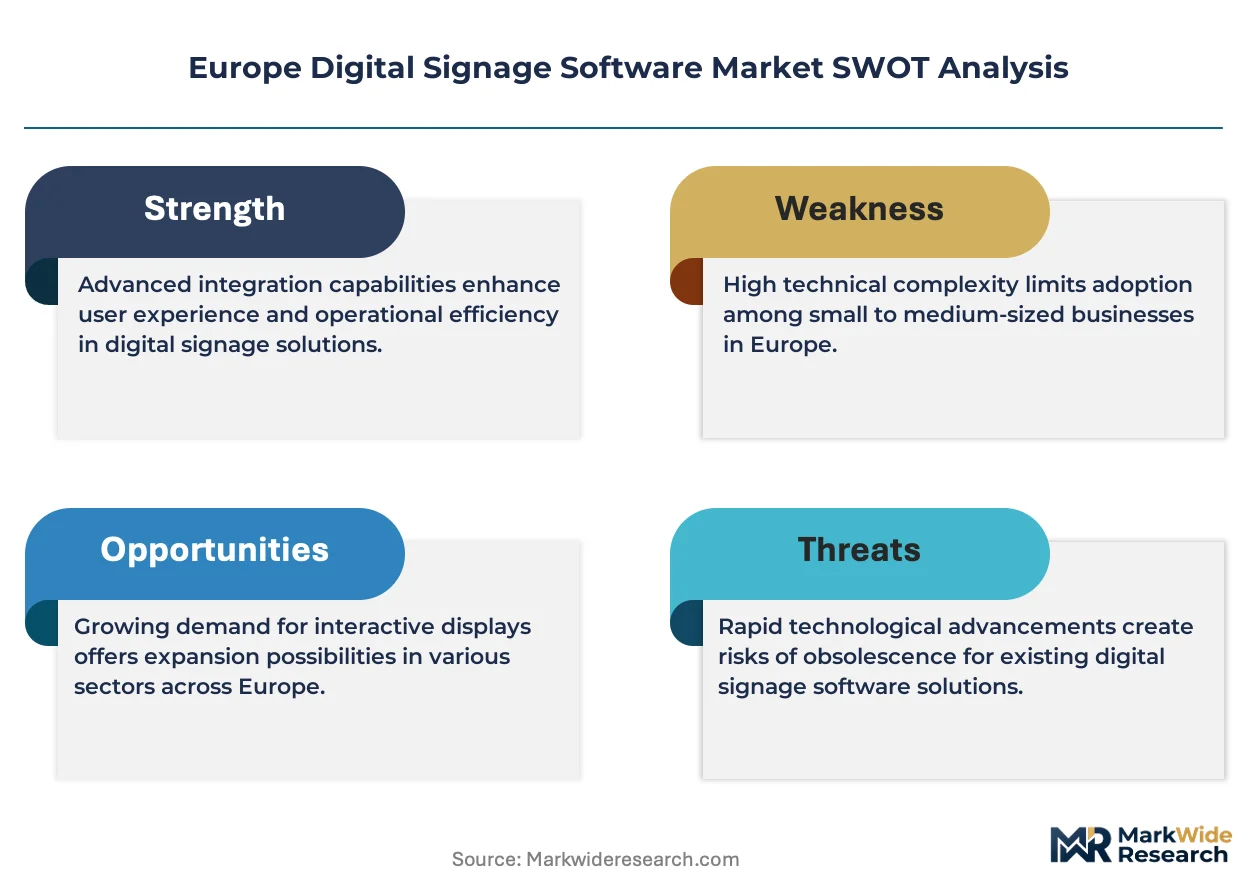
CE marking under the EU Radio Equipment Directive is collapsing the vendor landscape for connected display systems sold across member states. Broadsign International LLC leverages its programmatic advertising heritage to dominate transit and airport networks. Scala sustains deep integration with retail analytics platforms. SpinetiX SA anchors its position through edge-computing players that reduce cloud dependency.
Europe digital signage software encompasses content management systems, media players, and device orchestration platforms that schedule, distribute, and render visual media across networked screens. These systems typically run on Linux or Android kernels with HTML5 rendering engines and support 4K output at 60 frames per second for commercial environments. Cloud-based deployments are capturing the fastest expansion as franchise operators seek centralized template control across hundreds of locations. On-premise installations retain favor among financial institutions with strict data residency requirements. The advertising application segment concentrates margin pools through programmatic yield optimization and audience measurement integrations.
GDPR enforcement by national data protection authorities restricts facial analytics and audience measurement without explicit consent, forcing vendors to redesign sensor architectures. The EU Green Deal and Ecodesign for Energy-Related Products Directive pressure hardware refresh cycles and elevate energy efficiency in outdoor installations. REACH compliance governs substance restrictions in display manufacturing supply chains. Stakeholders must weigh interoperability investments against the risk of fragmented national certification requirements as member states transpose delegated acts.
Market Dynamics
Cloud-native content management architectures are consolidating operational control for multi-location operators, while edge computing deployments reduce latency for real-time audience analytics. The EU AI Act's risk classification system for biometric inference is forcing vendors to re-engineer sensor-to-cloud data pipelines.
Growth Catalysts
- EU Green Deal Ecodesign mandates:Energy efficiency requirements for outdoor displays are accelerating hardware refresh cycles and creating attach opportunities for software-based power management platforms.
- Programmatic advertising integration:Transit authorities and airport operators are adopting yield-optimization engines that dynamically price screen inventory based on footfall sensors.
- France and Germany retail consolidation:Pan-European franchise networks are standardizing on centralized template libraries to enforce brand consistency across hundreds of locations.
Market Restraints
- GDPR biometric consent architecture:Facial analytics deployment requires explicit opt-in frameworks that degrade audience measurement accuracy and increase sensor hardware costs.
- CE marking compliance concentration:Radio Equipment Directive certification bottlenecks favor incumbent vendors with established notified body relationships, raising barriers for new entrants.
- Cloud infrastructure vendor lock-in:Deep integration with hyperscaler ecosystems creates switching costs that limit procurement flexibility for mid-size operators.
Strategic Opportunities
- Spain and Italy hospitality modernization:Hotel groups in Southern Europe lag Northern counterparts in guest-facing screen deployment, creating whitespace for integrated room-to-lobby solutions.
- CSRD sustainability reporting convergence:Corporate disclosure requirements are elevating demand for carbon-footprint dashboards that visualize real-time energy consumption across display fleets.
- 5G multicast and edge AI fusion:Low-latency content synchronization combined with on-device inference enables contextual messaging without cloud round-trips.
Industry Challenges
- Embedded Linux security patching:Media player firmware maintenance requires specialized DevOps capabilities that many systems integrators lack in-house.
- REACH substance documentation:Supply chain transparency requirements for display electronics demand extended producer responsibility systems that smaller vendors struggle to operationalize.
- Legacy on-premise migration friction:Financial institutions with strict data residency rules face complex API reconciliation when bridging existing installations to hybrid cloud architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Signage Software Market |
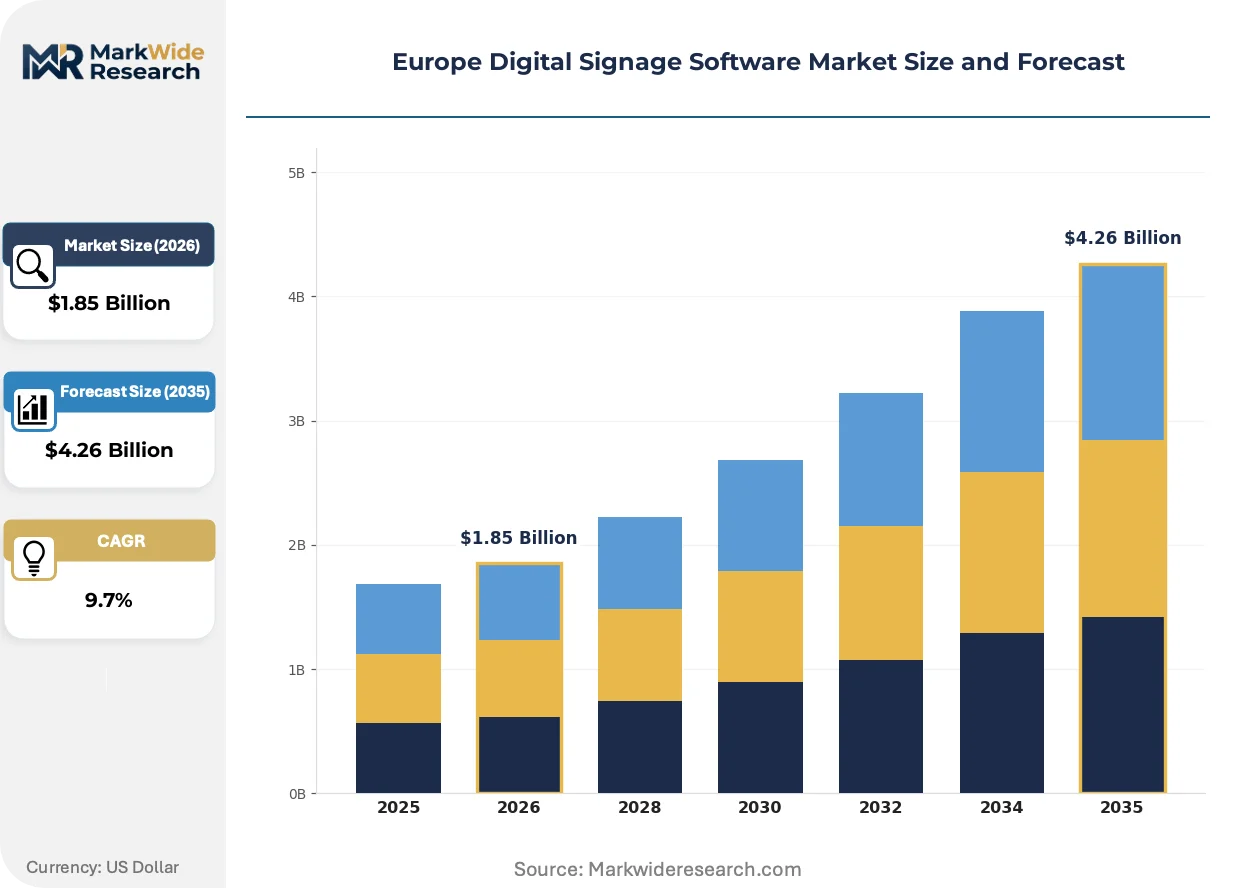
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Open-Source End User: Retailers, Educational Institutions, Corporate Offices, Restaurants Installation Type: Indoor, Outdoor, Mobile, Fixed Application: Advertising, Information Display, Wayfinding, Event Promotion |
| Companies Covered | BrightSign LLC, STRATACACHE, Scala, signageOS Inc., Signagelive, SpinetiX SA, Broadsign International LLC, Navori Labs SA, ZetaDisplay AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Signage Software Market Shifts & Advancements
Software-defined display management is decoupling hardware procurement from content orchestration, enabling subscription-based operational models. Vendors are racing to embed compliance automation that preempts regulatory enforcement actions.
Edge-native media players with ARM-based inference accelerators are bifurcating the market between cloud-dependent and autonomous screen networks. Quick-service restaurant chains in the Netherlands and Belgium are piloting these units for drive-thru menu adaptation. The technology is compressing infrastructure costs for locations with unreliable connectivity while fragmenting vendor support models.
GDPR enforcement by CNIL and other national data protection authorities is restricting facial analytics deployment without granular consent mechanisms. Retail analytics platforms are redesigning sensor architectures to aggregate demographic data without individual identification. French shopping mall operators are most affected, shifting investment toward dwell-time heat mapping that avoids biometric capture.
Subscription-based content management licensing is displacing perpetual software purchases among mid-market franchise operators. Systems integrators are unbundling installation and creative services from recurring platform fees. This pattern is most visible in the United Kingdom, where hospitality groups prioritize operational expenditure predictability over capital ownership.
Europe Digital Signage Software Market Segmentation
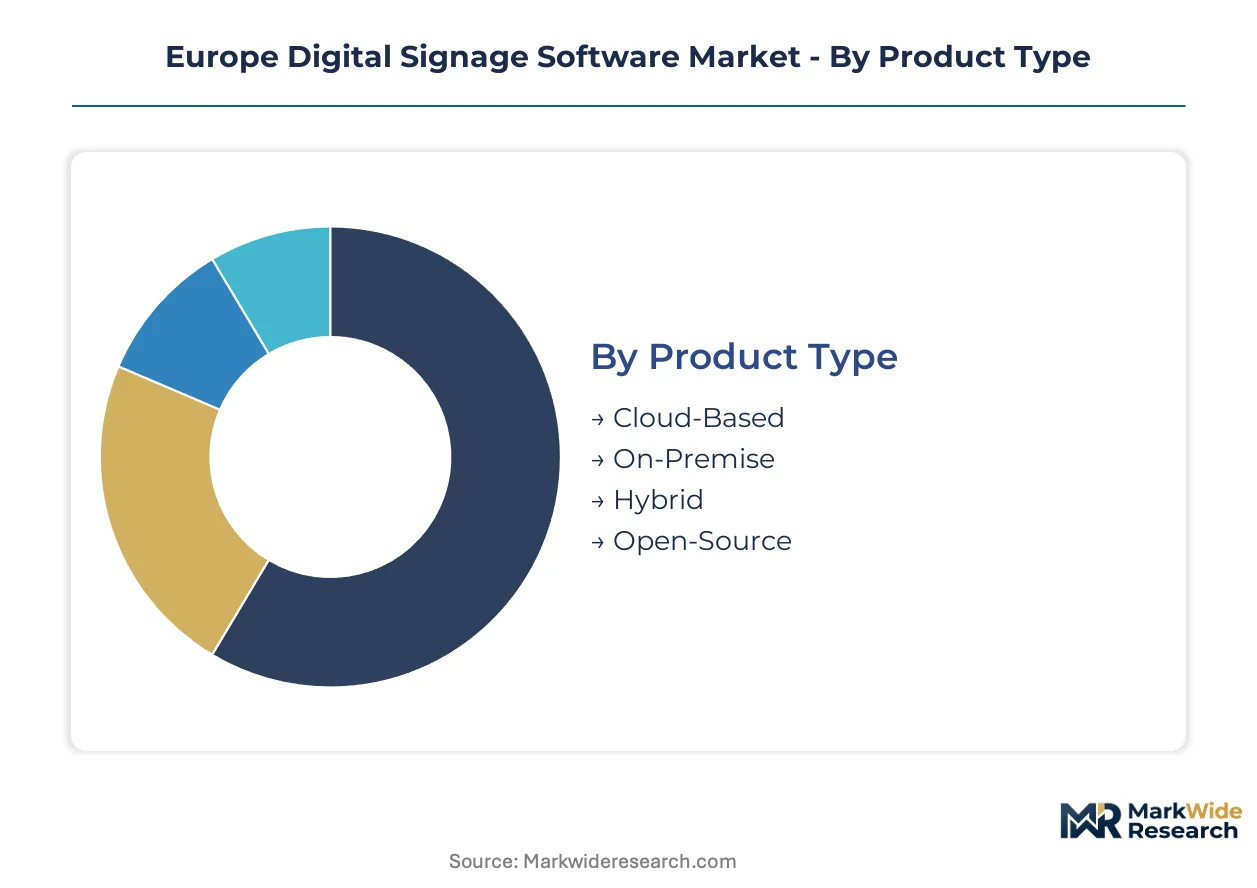
Segmentation in Europe digital signage software reveals divergent deployment architectures across national regulatory environments. Cloud-native solutions dominate franchise networks spanning multiple member states, while on-premise installations cluster in jurisdictions with strict data localization mandates.
Product Type:
Cloud-based deployments concentrate in pan-European retail chains seeking centralized template control across Germany, France, and the United Kingdom. On-premise installations anchor financial services clusters in Switzerland and Luxembourg where GDPR Article 44 cross-border transfer restrictions bite hardest.
- Cloud-Based:Multi-tenant SaaS architectures with HTML5 rendering engines support 4K output at 60 frames per second. Demand clusters in United Kingdom hospitality groups modernizing guest communication infrastructure under operational expenditure models. The EU AI Act's risk classification system is forcing vendors to re-engineer sensor-to-cloud data pipelines for algorithmic content recommendation engines.
- On-Premise:Linux-based server deployments with local content repositories and air-gapped update mechanisms. German automotive manufacturers and French defense-adjacent facilities favor these installations to satisfy national data sovereignty requirements. CNIL enforcement actions on facial analytics have accelerated investment in on-device processing architectures that bypass cloud round-trips.
- Hybrid:Edge-to-cloud orchestration with local caching and remote template synchronization.
- Open-Source:Community-maintained frameworks with customizable player software and self-hosted management dashboards.
On-premise solutions command the established base among financial institutions. The steepest expansion runs through cloud-based deployments as franchise operators prioritize centralized operational control.
End User:
Retailers generate the highest volume deployments with standardized screen networks across hundreds of locations. Educational institutions present fragmented procurement with national ministry-level purchasing frameworks dominating in France and Italy.
- Retailers:Pan-European chains in Germany and France are scaling networked screen deployments to unify in-store messaging and enforce brand consistency. Scala's deep integration with retail analytics platforms captures this segment through dwell-time heat mapping that avoids biometric capture under GDPR constraints.
- Educational Institutions:University campuses and K-12 districts deploy wayfinding and emergency notification systems. Italian and Spanish public procurement frameworks favor open-source solutions to minimize licensing expenditure under constrained education budgets.
- Corporate Offices:Workplace communication platforms with room booking integration and visitor management displays.
- Restaurants:Quick-service operators in the Netherlands and Belgium pilot edge-native media players for drive-thru menu adaptation with unreliable connectivity.
Retailers anchor volume concentration through standardization mandates. Educational institutions represent the most price-sensitive procurement channel with longest sales cycles.
Installation Type:
Indoor deployments dominate revenue with controlled environmental conditions simplifying hardware specifications. Outdoor installations face Ecodesign for Energy-Related Products Directive compliance costs that favor incumbent vendors with established notified body relationships.
- Indoor:Climate-controlled environments with standard commercial displays and PoE-powered media players. United Kingdom hospitality groups drive modernization of guest-facing screen infrastructure from room to lobby. Subscription-based licensing is displacing perpetual purchases among mid-market operators prioritizing operational expenditure predictability.
- Outdoor:Weather-hardened displays with IP65 enclosures and thermal management for direct sunlight operation. EU Green Deal energy efficiency mandates are accelerating hardware refresh cycles and creating attach opportunities for software-based power management platforms. Transit authorities and airport operators adopt yield-optimization engines with dynamic pricing based on footfall sensors.
- Mobile:Battery-powered or vehicle-mounted displays for temporary deployments and event coverage.
- Fixed:Permanent structural installations with embedded power and network infrastructure.
Indoor installations command margin concentration through simpler support requirements. Outdoor deployments are climbing the fastest as Ecodesign mandates force infrastructure replacement.
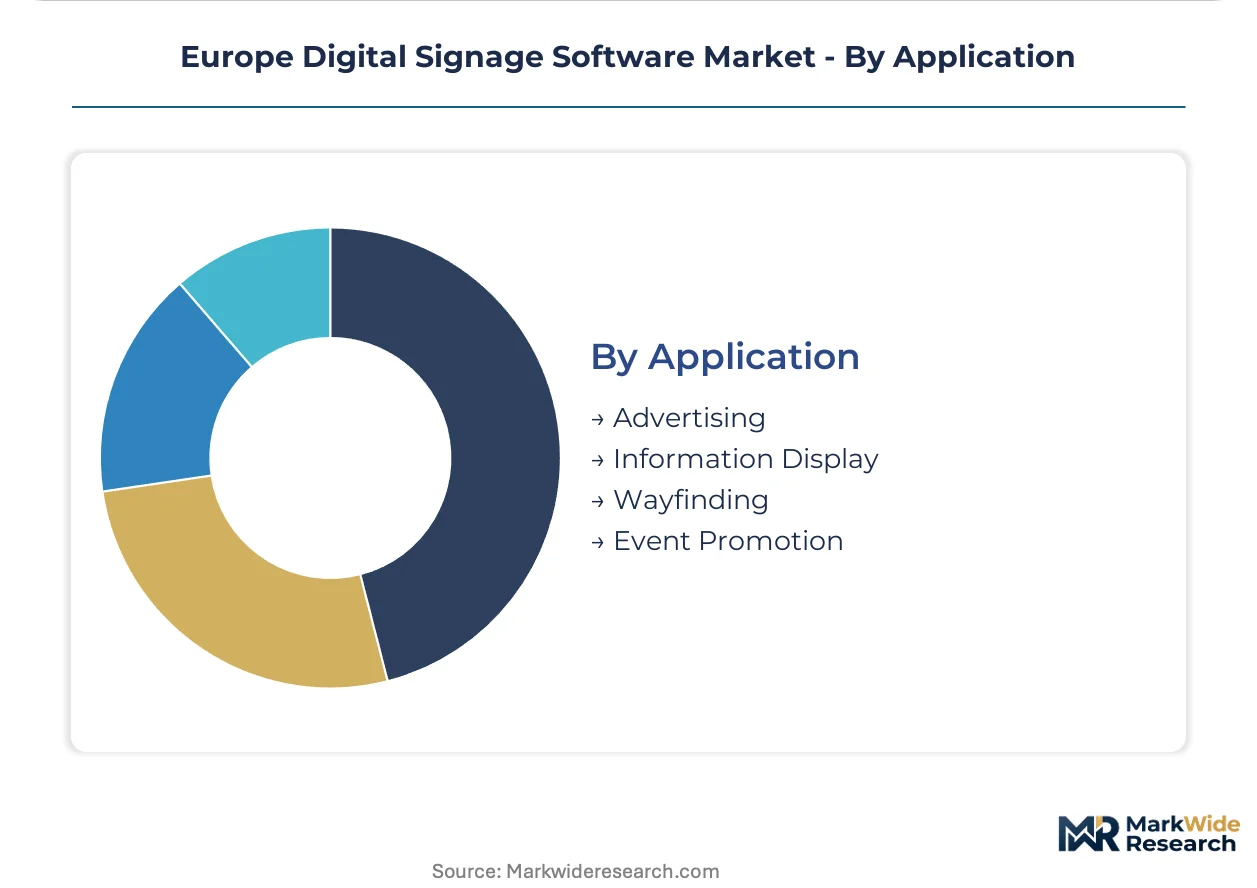
Application:
Advertising applications concentrate margin pools through programmatic yield optimization and audience measurement integrations. Information display serves cost-sensitive public sector deployments with basic scheduling requirements.
- Advertising:Programmatic inventory management with real-time bidding and demographic targeting. Broadsign International LLC leverages its programmatic heritage to dominate transit and airport networks across European member states. GDPR biometric consent requirements restrict facial analytics deployment without explicit opt-in frameworks that degrade measurement accuracy.
- Information Display:Static and lightly dynamic content for corporate communications, public announcements, and menu boards. SpinetiX SA anchors its position through edge-computing players that reduce cloud dependency for locations with intermittent connectivity.
- Wayfinding:Interactive directory systems with touchscreen navigation and point-of-interest mapping.
- Event Promotion:Temporary digital poster networks for conferences, exhibitions, and seasonal campaigns.
Advertising applications capture premium pricing through data integration. Information display represents the volume foundation with fastest deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies and national digital infrastructure programs are accelerating screen network deployments across member states. CE marking under the Radio Equipment Directive is compressing vendor options for connected displays. GDPR enforcement by national data protection authorities is reshaping biometric analytics deployment patterns.
Germany
Automotive manufacturers and retail chains in Bavaria and North Rhine-Westphalia are scaling centralized content management for factory-floor and showroom networks. The Federal Network Agency enforces strict electromagnetic compatibility standards for industrial IoT displays. Frankfurt's financial district maintains on-premise installations to satisfy data localization requirements under national banking regulations.
United Kingdom
Hospitality groups in London and Manchester are modernizing guest-facing screen infrastructure from hotel rooms to lobbies. The Information Commissioner's Office mandates explicit consent frameworks for facial analytics in public venues. Edinburgh and Glasgow cluster operators favor subscription licensing models to convert capital expenditure into predictable operational costs.
France
Shopping mall operators in Île-de-France are shifting investment toward dwell-time heat mapping after CNIL enforcement actions restricted biometric capture. The EU AI Act's risk classification system forces re-engineering of algorithmic content recommendation engines on public displays. Lyon and Marseille transit authorities adopt programmatic yield-optimization platforms for dynamic screen inventory pricing.
Netherlands
Quick-service restaurant chains in Amsterdam and Rotterdam pilot edge-native media players for drive-thru menu adaptation with unreliable connectivity. The Dutch Authority for Digital Infrastructure promotes 5G multicast trials for low-latency content synchronization. Eindhoven's technology corridor hosts systems integrators specializing in ARM-based inference accelerators for autonomous screen networks.
Italy
Hotel groups in Lombardy and Lazio lag Northern European counterparts in guest-facing screen deployment, creating whitespace for integrated room-to-lobby solutions. National public procurement frameworks favor open-source content management to minimize licensing expenditure under constrained hospitality budgets. Milan's fashion retail district experiments with software-defined display management decoupled from hardware procurement cycles.
Europe Digital Signage Software Market Competitive Landscape
Player mix skews toward specialized software vendors with deep vertical integration into specific end-use segments. The vendor landscape concentrates around three strategic archetypes: cloud-native platform providers, edge-computing hardware-software bundlers, and programmatic advertising infrastructure specialists. Dominant competitive moves include portfolio diversification into adjacent analytics services and strategic partnerships with systems integrators for national deployment scale.
Among North American-origin platform providers, BrightSign LLC and STRATACACHE occupy positions exemplifying the hardware-software convergence archetype. Scala and SpinetiX SA represent the European specialist tier with embedded computing heritage. Broadsign International LLC anchors the programmatic advertising infrastructure segment with transit and airport network concentration.
| Leading Market Players |
|---|
| BrightSign LLC |
| STRATACACHE |
| Scala |
| signageOS Inc. |
| Signagelive |
| SpinetiX SA |
| Broadsign International LLC |
| Navori Labs SA |
| ZetaDisplay AB |
| Others |
Supply & Pricing Matrix
Multi-tenant SaaS scale economies among cloud-native platform providers compress marginal delivery costs while anchoring subscription price floors across European member states. CE marking bottlenecks under the Radio Equipment Directive concentrate supply-side leverage with incumbent vendors possessing established notified body relationships, amplifying pricing power for certified hardware-software bundles.
Pricing Analysis
Certification level under CE marking and GDPR compliance architecture creates the primary spread between premium and standard tiers. Subscription-based SaaS licensing dominates cloud deployments while perpetual licenses persist in on-premise financial services installations. Cost compression in mid-market hospitality segments intensifies as operators convert capital expenditure to operational expenditure models. Educational institutions exhibit highest price sensitivity due to constrained public procurement budgets, whereas transit authorities demonstrate lowest sensitivity given yield-optimization revenue attach.
Supply Chain Analysis
Inventory cycles for ARM-based media player chipsets extend lead times when foundry capacity tightens in Taiwan and South Korea. Display panel supply concentrates in China and Vietnam with final assembly clustering in Poland and the Czech Republic for EU market access. Component sourcing draws from specialized fabs for edge AI accelerators and industrial-grade flash storage. Single-source vulnerability in system-on-chip supply creates exposure when geopolitical friction disrupts semiconductor logistics. Distribution runs through systems integrators with national deployment scale rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification system for biometric inference triggers a high-growth disruption window as vendors re-engineer sensor-to-cloud data pipelines across public display networks.
For Market Incumbents: Compound platform stickiness through deeper integration with retail analytics and hospitality property management systems. Incumbents must accelerate edge-native media player development to preempt ARM-based inference accelerator specialists from capturing autonomous screen network deployments. Certification investment in CSRD-aligned carbon footprint dashboards creates defensive moats against sustainability-focused challengers. For New Entrants and Emerging Players: White-space in Southern European hospitality modernization offers penetration pathways where hotel groups lag Northern counterparts in guest-facing screen infrastructure. Spain and Italy procurement frameworks favor open-source solutions to minimize licensing expenditure, creating entry angles for community-maintained platforms with localized support partnerships. Target integration complexity reduction as the primary go-to-market angle for mid-market franchise operators lacking specialized DevOps capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-computing hardware-software bundlers with established hyperscaler partnerships over pure-play cloud-native platforms. Long-term viability hinges on compliance automation capabilities that preempt regulatory enforcement actions across fragmented national certification requirements. Watch 5G multicast trial outcomes as the inflection signal determining whether low-latency content synchronization enables contextual messaging without cloud dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens vendor lock-in through embedded retail analytics and hospitality PMS connectivity. |
| CE Marking Pathway | Accelerates market access by satisfying Radio Equipment Directive electromagnetic compatibility mandates. |
| Strategic Partnership | Systems integrator alliances enable national deployment scale across pan-European franchise networks. |
| Acquisition of Specialist Firm | Captures edge AI inference capabilities and ARM-based media player engineering talent. |
| Geographic Expansion | Southern Europe hospitality whitespace in Italy and Spain offers growth outside saturated Northern markets. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs at retail chains, IT procurement officers in hospitality groups, platform engineers at systems integrators, and channel partners distributing edge hardware, then refined through secondary validation. Primary intelligence combined structured interviews with secondary sources including SEC filings from North American platform providers, hyperscaler capex disclosures, EU regulatory delegated acts, and national data protection authority enforcement records. Bottom-up deployment counts across member states triangulated against top-down addressable market sizing.
Variance decomposition across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern structured the analytical framework. CAGRs derived from logistic diffusion curves fitted to cloud-native adoption patterns and hardware refresh cycle timing. Edge AI inference penetration rates and GDPR consent framework compliance costs served as industry-specific forecast inputs across the projection horizon.
Material uncertainties — regulatory enforcement intensity on biometric analytics, CE marking processing delays, and hyperscaler pricing volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution rates and cross-border data transfer rule stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Live Chat Software Market
Software & Services
Latin America ERP Software Market
Software & Services
Cemetery Software Market
Software & Services
Data Integration Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global DevOps Software Market
Software & Services
RIP Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
3D Animation Software Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Plant Design Software Market
Software & Services
Global Construction Management Software Market
Software & Services
BIM Objects Software Market
Software & Services
Embedded Hypervisor Market