
 APAC Data Wrangling Market | 2026-2036
APAC Data Wrangling Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Data Wrangling Market Outlook
Enterprise buyer concentration in APAC financial services is consolidating around fewer institutions with larger data transformation budgets. Trifacta Software Inc. leverages its visual data preparation interface to compete for these high-value contracts. Oracle Corporation anchors its position through deep integration with enterprise database estates across the region. SAS Institute Inc. differentiates via advanced analytics coupling that extends beyond raw data preparation into downstream modeling workflows.
Data wrangling encompasses the iterative process of discovering, structuring, cleaning, enriching, validating, and transforming raw data into analysis-ready formats, typically involving schema inference, missing-value imputation, and format standardization at throughput rates exceeding millions of records per hour. Cloud deployment models now dominate new implementations as hyperscaler infrastructure reduces latency for distributed data pipelines across multi-country operations. Open source tool types capture significant developer mindshare, though commercial integrated solutions command premium pricing where governance and audit trails are mandatory. Healthcare end users represent an emerging growth pocket as clinical data interoperability requirements intensify across national health systems.
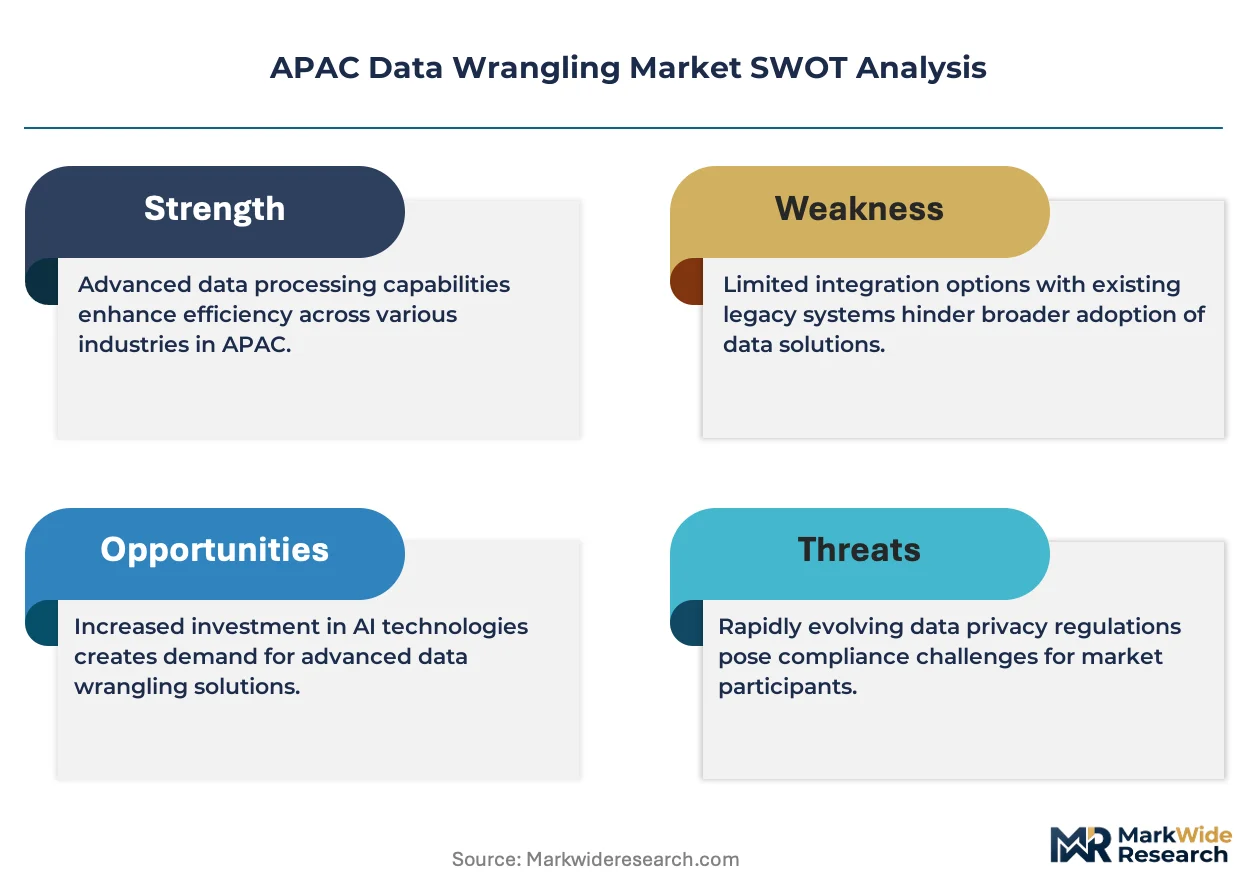
Japan's Personal Information Protection Commission and China's MIIT enforce divergent data localization mandates that fragment cross-border wrangling architectures. India's Digital Personal Data Protection Act introduces consent-layer complexity that reshapes how streaming data sources can be ingested and processed. BIS certification requirements for data management software add compliance overhead for vendors targeting government and defense end users. Stakeholders must evaluate regulatory divergence as a primary constraint on platform standardization strategies rather than treating compliance as a secondary implementation concern.
Market Dynamics
Cross-border data localization mandates are fragmenting platform architectures across APAC, forcing vendors to engineer jurisdiction-specific processing nodes rather than unified regional deployments.
Growth Catalysts
- Real-time risk analytics:Banking and financial services institutions across Southeast Asia are expanding data wrangling investments to support instantaneous credit scoring and fraud detection pipelines.
- MIIT data governance standards:China's tightening compliance requirements for cross-border data processing are creating captive demand for certified domestic preparation platforms.
- Clinical data interoperability:National health systems across the region are mandating standardized patient record formats that require intensive schema normalization and enrichment workflows.
Market Restraints
- Hyperscaler dependency:Cloud deployment concentration in AWS, Azure, and Alibaba Cloud creates single-point-of-failure risk for multi-country data pipelines.
- API rate limiting:Source system throttling from legacy enterprise databases constrains throughput for real-time streaming ingestion architectures.
- Divergent localization mandates:Japan's APPI amendments and China's data sovereignty rules impose incompatible architectural requirements that inflate engineering overhead.
Strategic Opportunities
- India's technology hubs:Domestic IT services firms in Bangalore and Hyderabad are building proprietary data preparation pipelines for global enterprise clients, creating anchor demand for specialized tooling.
- Edge preprocessing nodes:Manufacturing IoT deployments across Vietnam and Indonesia require localized wrangling capabilities that reduce backhaul bandwidth costs.
- Consent-layer automation:India's Digital Personal Data Protection Act introduces technical requirements for dynamic consent management that vendors can productize as platform features.
Industry Challenges
- Schema drift management:Financial services data teams report that upstream source system changes propagate downstream errors at rates exceeding manual remediation capacity.
- BIS certification timelines:Government and defense end users require Bureau of Indian Standards approval cycles that extend sales-to-deployment intervals by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Data Wrangling Market |
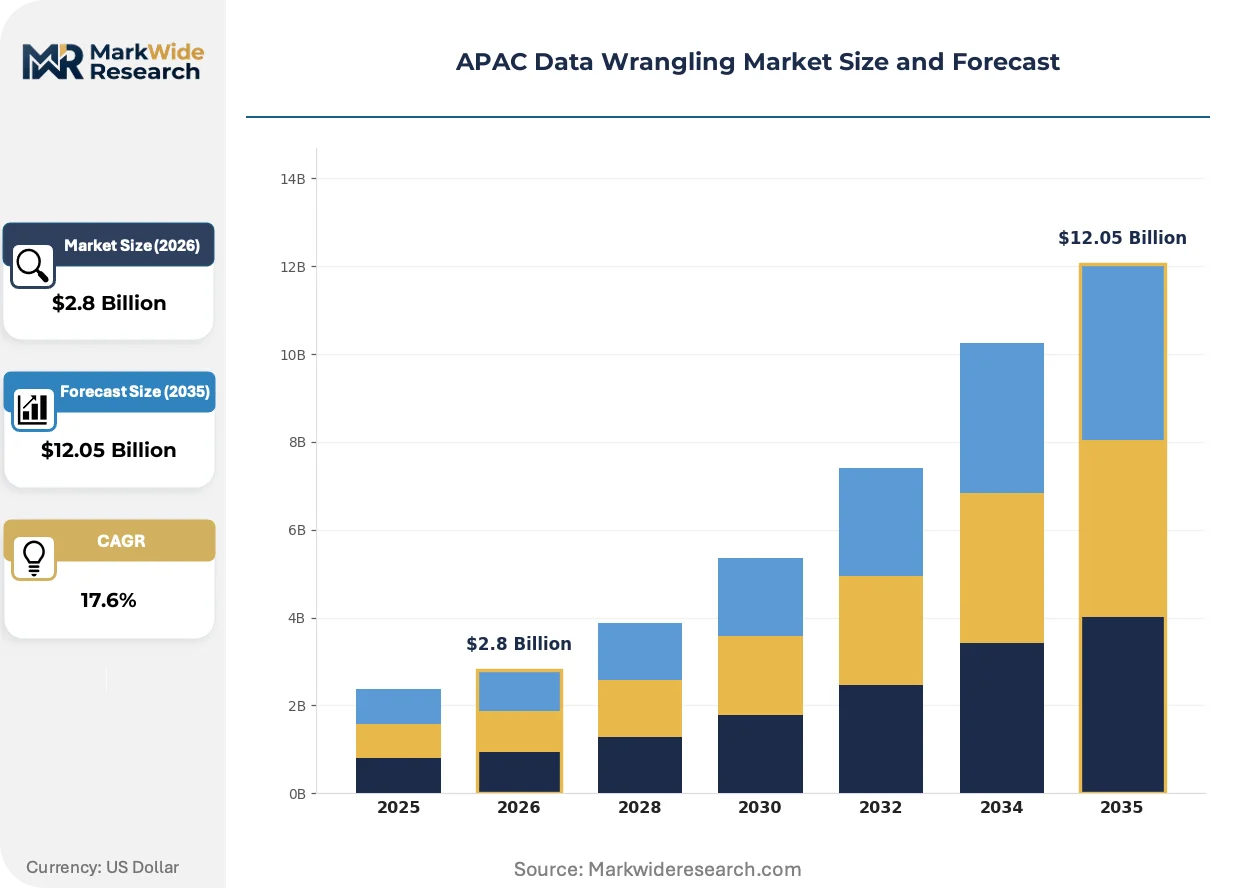
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Services End User: Retail, Finance, Healthcare, Telecommunications Data Source: Structured Data, Unstructured Data, Streaming Data, Data Lakes Tool Type: Open Source, Commercial, Integrated Solutions, Custom Tools |
| Companies Covered | Trifacta Software Inc., TIBCO Software Inc., Oracle Corporation, Teradata Corporation, Talend Inc., Alteryx Inc., Informatica Inc., SAS Institute Inc., Hitachi Vantara Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Data Wrangling Market Strategic Shifts
Automated data preparation is compressing the traditional extract-transform-load cycle from batch overnight jobs to continuous streaming pipelines, eliminating the latency gap between operational systems and analytical environments.
Graph-based data lineage tracking is unifying schema inference, quality monitoring, and compliance auditing into single-pane interfaces. Banking risk teams in Singapore and Sydney are adopting these platforms at accelerated procurement cycles. The technology is unifying previously siloed data stewardship functions, collapsing organizational friction between IT operations and business analysts.
China's MIIT cross-border data transfer security assessment framework is mandating pre-transfer classification and anonymization for all personal information leaving mainland infrastructure. Multinational corporations are responding by deploying in-country preparation clusters that perform de-identification before any cross-border movement. Financial services and healthcare verticals face the steepest compliance burdens under these rules.
Enterprise buyers are consolidating vendor relationships around integrated platforms that combine preparation, governance, and analytics rather than assembling point solutions. Systems integrators in India and consulting practices in Australia are displacing pure-play data preparation vendors in competitive evaluations. This concentration is most visible in Australia and Japan, where procurement teams prioritize audit trail completeness over functional breadth.
APAC Data Wrangling Market Segmentation
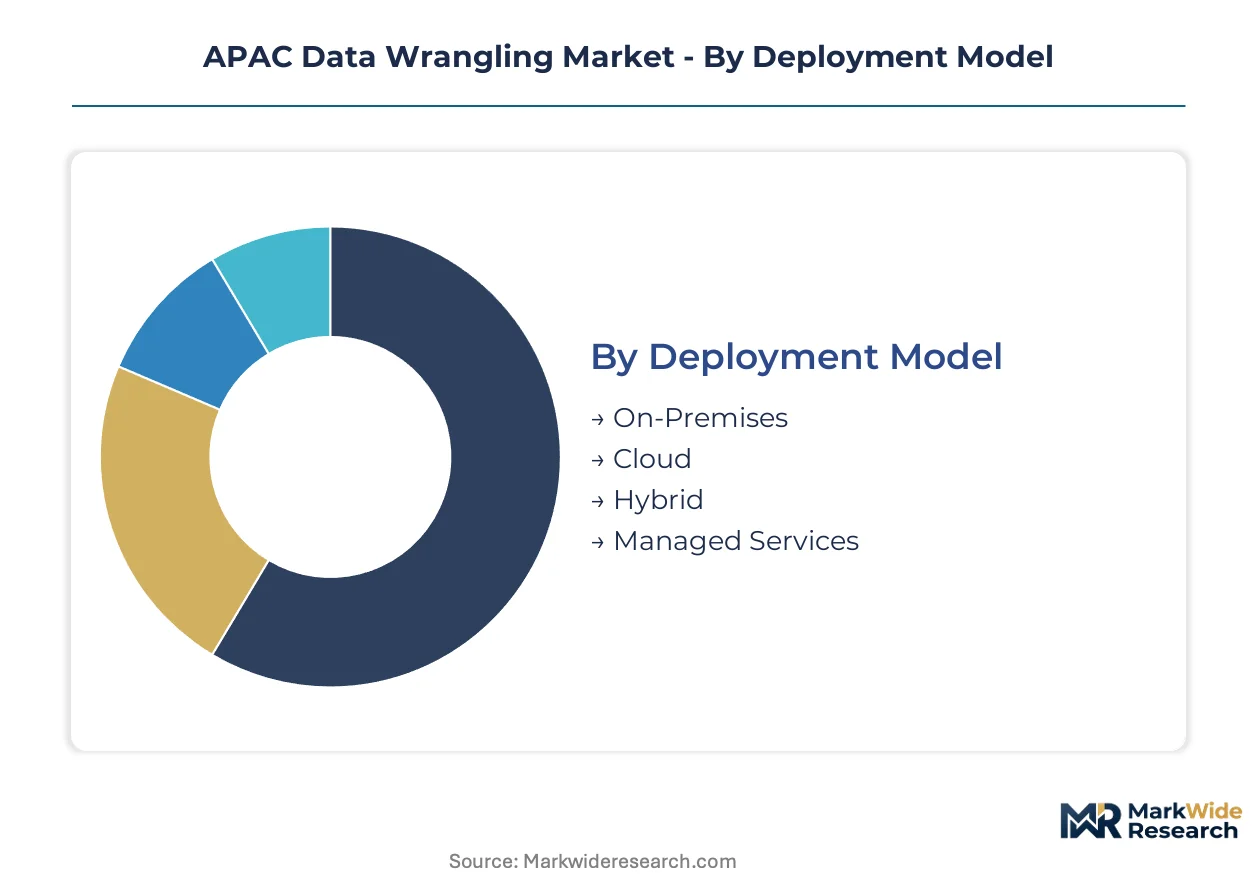
Data wrangling platforms fragment across deployment architectures, end-user sophistication, and data source complexity. Buyers prioritize segments that reconcile latency requirements with regulatory constraints across APAC's divergent compliance environments.
Deployment Model:
Latency tolerance and data sovereignty mandates determine infrastructure selection.
- Cloud:Hyperscaler infrastructure reduces latency for distributed pipelines across multi-country operations. Financial services institutions in Singapore and Sydney deploy these for real-time risk analytics, though MIIT certification requirements in China restrict eligible providers.
- On-Premises:Dedicated hardware within enterprise data centers maintains physical control over sensitive records. Japan's APPI amendments and India's BIS certification requirements drive captive installations for government and defense end users.
- Hybrid:Workload splitting between private infrastructure and public cloud balances compliance with elasticity.
- Managed Services:Third-party operational responsibility for pipeline maintenance and schema drift remediation.
Volume sits with Cloud; growth tilts toward Hybrid as cross-border localization mandates intensify.
End User:
Regulatory stringency and data velocity separate high-investment verticals from cost-constrained adopters.
- Finance:Real-time fraud detection and credit scoring pipelines require sub-second preparation throughput. Southeast Asian banking institutions consolidate vendor relationships around integrated platforms that combine preparation with downstream analytics.
- Healthcare:Clinical data interoperability mandates across national health systems demand intensive schema normalization. China's MIIT cross-border transfer assessments impose pre-transfer anonymization burdens on multinational hospital networks.
- Telecommunications:Subscriber data lakes and call detail record processing at carrier scale.
- Retail:Customer journey stitching across omnichannel touchpoints with lower compliance overhead.
Finance commands the largest procurement budgets; healthcare is expanding most quickly as interoperability deadlines approach.
Data Source:
Schema predictability governs tooling selection and engineering overhead.
- Streaming Data:Continuous ingestion from IoT sensors and operational systems demands low-latency transformation engines. Manufacturing deployments across Vietnam and Indonesia require edge preprocessing nodes that reduce backhaul costs.
- Structured Data:Relational database exports with predefined schemas enable automated quality monitoring. India's technology hubs process these for global enterprise clients through proprietary preparation pipelines.
- Unstructured Data:Text, image, and document formats requiring inference-based extraction.
- Data Lakes:Schema-on-read architectures with latent structure discovery requirements.
Structured data dominates current processing volumes; streaming architectures are gaining share fastest as real-time analytics mature.
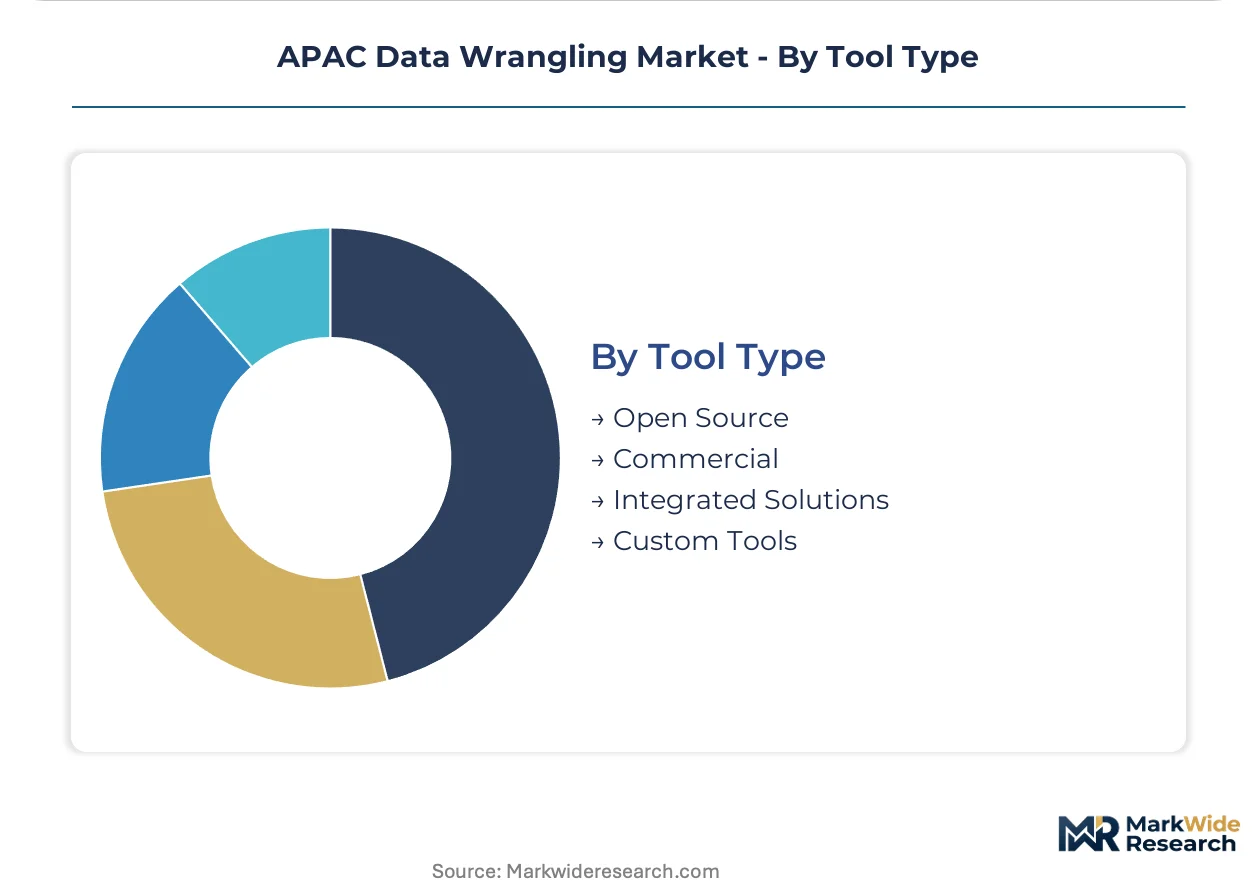
Tool Type:
Governance requirements and audit trail mandates separate commercial procurement from developer-driven adoption.
- Integrated Solutions:Unified platforms combining preparation, lineage tracking, and compliance auditing into single-pane interfaces. Australian and Japanese procurement teams prioritize these for audit trail completeness over functional breadth.
- Commercial:Licensed software with vendor support and guaranteed update cycles. China's MIIT data governance standards create captive demand for certified domestic preparation platforms.
- Open Source:Community-maintained libraries capturing developer mindshare in early-stage pipelines.
- Custom Tools:Proprietary tooling built in-house by systems integrators and domestic IT services firms.
Integrated solutions capture the steepest expansion trajectory as enterprise buyers consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking and financial services institutions across Southeast Asia concentrate the region's largest data transformation procurement budgets. Real-time risk analytics requirements are consolidating vendor relationships around integrated platforms with sub-second throughput capabilities.
China
MIIT data governance standards and cross-border transfer security assessments are creating captive demand for certified domestic preparation platforms. Multinational corporations deploy in-country processing clusters to perform de-identification before any data leaves mainland infrastructure. Shanghai and Beijing technology corridors host the densest concentration of compliance-engineering talent for these architectures.
Japan
APPI amendments and PMDA clinical data requirements are tightening consent-layer complexity for streaming data ingestion. Financial services and healthcare verticals face the steepest compliance burdens under evolving localization mandates. Tokyo and Osaka procurement teams prioritize audit trail completeness over functional breadth in vendor selection.
India
BIS certification requirements and the Digital Personal Data Protection Act are reshaping how government and defense end users evaluate pipeline solutions. Domestic IT services firms in Bangalore and Hyderabad are building proprietary data preparation pipelines for global enterprise clients. These technology hubs anchor regional demand for specialized tooling and engineering services.
Australia
TGA clinical data interoperability mandates and APRA prudential reporting requirements are driving schema normalization investments across healthcare and banking. Sydney and Melbourne risk teams are adopting graph-based lineage tracking platforms at accelerated procurement cycles. Systems integrators are displacing pure-play vendors in competitive evaluations.
Singapore
MAS regulatory technology initiatives and real-time payment infrastructure are expanding data wrangling investments for instantaneous fraud detection. The city-state's banking institutions consolidate vendor relationships around platforms combining preparation with downstream analytics. Singapore serves as the regional procurement hub for Southeast Asian financial services expansion.
APAC Data Wrangling Market Competitive Environment
United States-based software vendors anchor the premium tier; Asia-Pacific specialists hold position in compliance-engineering services. The vendor base organizes around three strategic archetypes: integrated platform providers, open-source tooling distributors, and systems integration consultancies. Competitive moves concentrate on strategic partnerships with hyperscaler infrastructure providers and geographic expansion through localized engineering centers.
Within the integrated platform tier, Trifacta Software Inc., Oracle Corporation, and SAS Institute Inc. occupy anchor positions. Trifacta leverages visual data preparation interfaces to compete for high-value financial services contracts. Oracle anchors through deep integration with enterprise database estates across the region. SAS Institute differentiates via advanced analytics coupling that extends beyond raw preparation into downstream modeling workflows. These three exemplify the consolidation pattern where enterprise buyers favor unified platforms over assembled point solutions.
| Leading Market Players |
|---|
| Trifacta Software Inc. |
| TIBCO Software Inc. |
| Oracle Corporation |
| Teradata Corporation |
| Talend Inc. |
| Alteryx Inc. |
| Informatica Inc. |
| SAS Institute Inc. |
| Hitachi Vantara Corporation |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler compute pricing indices cascade through data wrangling supply chains, compressing margins on cloud-native deployments while amplifying premiums for certified on-premises installations in China and Japan.
Pricing Analysis
Volume concentrates in SaaS-tiered subscription models serving mid-market adopters, while margin accrues to perpetual-license deployments with embedded compliance engineering for MIIT-certified platforms in China. Price differentiation separates certified domestic preparation platforms from uncertified alternatives, with BIS-approved installations in India commanding additional premiums. Cost compression in cloud-native tiers stems from hyperscaler commoditization of underlying infrastructure. Government and defense end users exhibit lowest price sensitivity due to mandatory certification requirements, while retail and mid-market finance show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Singaporean banking consortia and Australian healthcare networks, while systems integrators in India intermediate fragmented mid-market procurement. Engineering talent concentrates in Bangalore, Hyderabad, and Shanghai technology corridors, with specialized compliance expertise tethered to Beijing and Tokyo regulatory consulting ecosystems. Raw material dependencies span hyperscaler compute capacity, open-source framework maintenance, and proprietary algorithm licensing. Single-source vulnerability runs through AWS, Azure, and Alibaba Cloud concentration for multi-country pipeline orchestration. Distribution runs through value-added resellers with localized certification expertise in each jurisdiction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified engineering capacity scarcity props pricing power for vendors with established MIIT, BIS, and APPI compliance track records, creating defendable positions as localization mandates proliferate.
For Market Incumbents: Hedge against open-source displacement by embedding proprietary lineage-tracking modules into existing enterprise deployments. Acquire specialized consent-layer automation capabilities to address India's Digital Personal Data Protection Act requirements. Channel control through exclusive systems integrator relationships in Bangalore and Sydney protects against pure-play vendor erosion.
For New Entrants and Emerging Players: Automated schema drift remediation technology offers entry into financial services accounts struggling with manual remediation capacity constraints. Target Vietnam and Indonesia manufacturing IoT deployments where edge preprocessing demand outstrips incumbent coverage. Go-to-market through domestic IT services partnerships accelerates credibility with global enterprise clients.
For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-engineering boutiques with established PMDA and TGA track records in Tokyo and Melbourne. Long-term viability hinges on regulatory divergence persisting across the projection horizon. Acquisition target archetype: specialized vendors with dual China-Japan certification and existing hyperscaler marketplace listings. Watch for MIIT cross-border assessment enforcement intensity as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies preparation, governance, and analytics into single-pane interfaces for Australian procurement teams. |
| Geographic Expansion | Establishes localized engineering centers in Shanghai and Beijing to address MIIT certification requirements. |
| Strategic Partnership | Aligns with hyperscaler infrastructure providers to reduce latency for distributed multi-country pipelines. |
| Acquisition of Specialist Firm | Absorbs consent-layer automation capabilities for India's Digital Personal Data Protection Act compliance. |
| Product Launch | Introduces edge preprocessing nodes for Vietnam and Indonesia manufacturing IoT deployments. |
Study Parameters
Independent corroboration across vendor product roadmaps, systems integrator deployment records, and regulatory filing databases underwrites the qualitative findings. Primary interviews with data engineering directors, compliance officers at multinational corporations, procurement leads at Southeast Asian banking institutions, and cloud solution architects informed demand-side validation. Secondary sources include MIIT cross-border transfer security assessment filings, Japan's Personal Information Protection Commission guidance documents, India's Digital Personal Data Protection Act technical specifications, and hyperscaler regional capex disclosures. Bottom-up deployment sizing and top-down market aggregation triangulate volume estimates.
Comparable-period anchoring to historical cloud infrastructure adoption curves and enterprise software procurement cycles shaped the projection framework. The analysis models deployment architecture, end-user vertical, data source complexity, and tool type as core segmentation dimensions. CAGRs derive from regression against technology spending elasticity and regulatory enforcement intensity trajectories. Forecast inputs incorporate schema normalization workload intensity for healthcare interoperability mandates and real-time streaming throughput requirements in financial services.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory harmonization or hyperscaler market exit scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Industrial Analytics Market
Analytics
Data Analytics in Telecom Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Content Analytics and Search Software Market
Analytics
Big Data Analytics in Automotive Market
Analytics
APAC Location Analytics Market
Analytics
Cloud Analytics Market
Analytics
Event Stream Processing Market
Analytics
Global Graph Analytics Market
Analytics
Retail Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Global People and HR Analytics Software Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Text Analytics Market
Analytics
Speech Analytics Market
Analytics
Content Analytics Software Market