
 Data Wrangling Market | 2026-2036
Data Wrangling Market Size, Share, and Industry Trends Forecast 2026-2036
Data Wrangling Market Intelligence
Enterprise-grade data quality certification is unwinding competitive dynamics across the data wrangling landscape. Informatica Inc. leverages its cloud-native integration stack to anchor governance-heavy deployments in regulated industries. SAS Institute Inc. sustains deep R&D intensity around visual data preparation interfaces for business analysts. Databricks Inc. competes through unified lakehouse architectures that collapse separate transformation layers into single environments.
Data wrangling encompasses the systematic discovery, structuring, cleaning, enriching, validating, and transformation of raw data into analysis-ready formats, typically involving schema inference, outlier detection, and format normalization across heterogeneous sources. Its primary commercial purpose is to reduce the time data scientists and analysts spend on preparatory tasks, thereby accelerating model deployment and business intelligence cycles. Cloud-based deployment now captures the fastest expansion as organizations retire on-premises ETL infrastructure, while data cleaning and data integration applications together hold the deepest margin pools due to recurring enterprise subscription structures. Machine learning-augmented wrangling represents the emerging technology frontier, with automated schema mapping and intelligent imputation displacing manual scripting workflows.
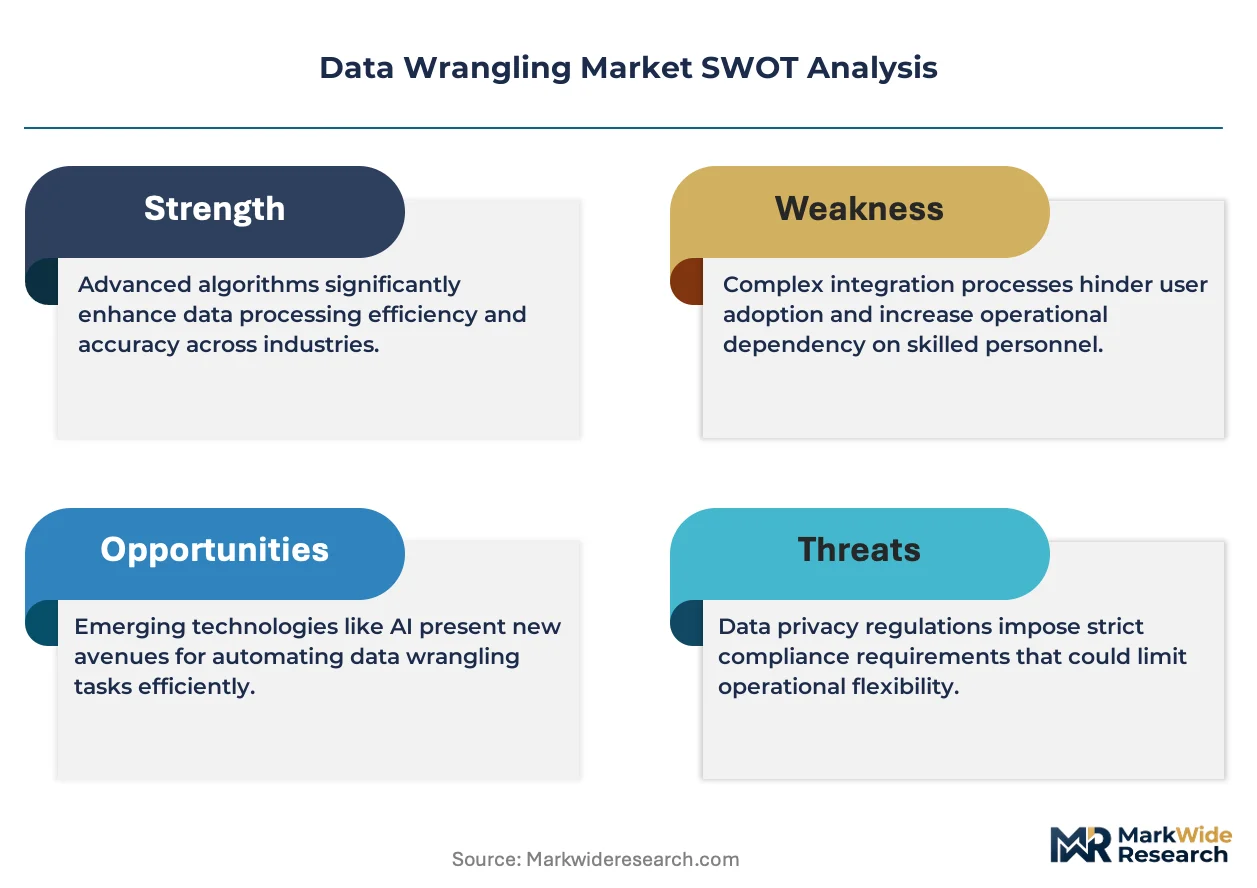
The EU AI Act imposes strict training data governance requirements that directly expand demand for traceable data lineage and documented transformation workflows. HIPAA in the United States mandates de-identification standards that elevate data cleaning and validation to compliance-critical functions, while ISO 8000 data quality frameworks shape procurement specifications for enterprise buyers. Stakeholders must monitor how emerging algorithmic accountability regulations in multiple jurisdictions redefine the minimum viable feature set for wrangling platforms.
Market Dynamics
Machine learning-augmented automation is compressing the traditional manual scripting layer that once dominated data preparation workflows, forcing vendors to rearchitect around intelligent schema inference and automated imputation engines.
Growth Catalysts
- EU AI Act training data mandates:Traceable lineage requirements are pulling governed pipeline investments from financial services and healthcare providers across European member states.
- Cloud-native ETL retirement:Organizations migrating from on-premises infrastructure are expanding subscription bases for integrated preparation platforms that collapse transformation layers.
- HIPAA de-identification standards:US healthcare systems are elevating data cleaning and validation to compliance-critical procurement criteria, tightening vendor selection filters.
Market Restraints
- Specialized talent scarcity:Shortages of engineers fluent in both data engineering and domain-specific compliance are extending implementation timelines and inflating project costs.
- Legacy system entrenchment:Fortune 500 enterprises with decades-old data architectures face prohibitive switching costs that slow platform consolidation.
- Input cost volatility:Cloud compute pricing fluctuations are compressing margins for vendors offering fixed-rate subscription models.
Strategic Opportunities
- ISO 8000 procurement integration:Enterprise buyers are baking data quality certification into RFP requirements, creating certification-based vendor differentiation.
- Mid-market underpenetration:US-based companies below Fortune 500 scale remain underserved by current enterprise-focused platform pricing and deployment complexity.
- Real-time streaming convergence:Fusion of batch wrangling with stream processing architectures is opening new product categories for operational analytics use cases.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments face fragmented governance and inconsistent transformation logic.
- Algorithmic accountability compliance:Emerging documentation requirements for automated decision systems are forcing vendors to rebuild audit trail capabilities from core architecture levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Wrangling Market |
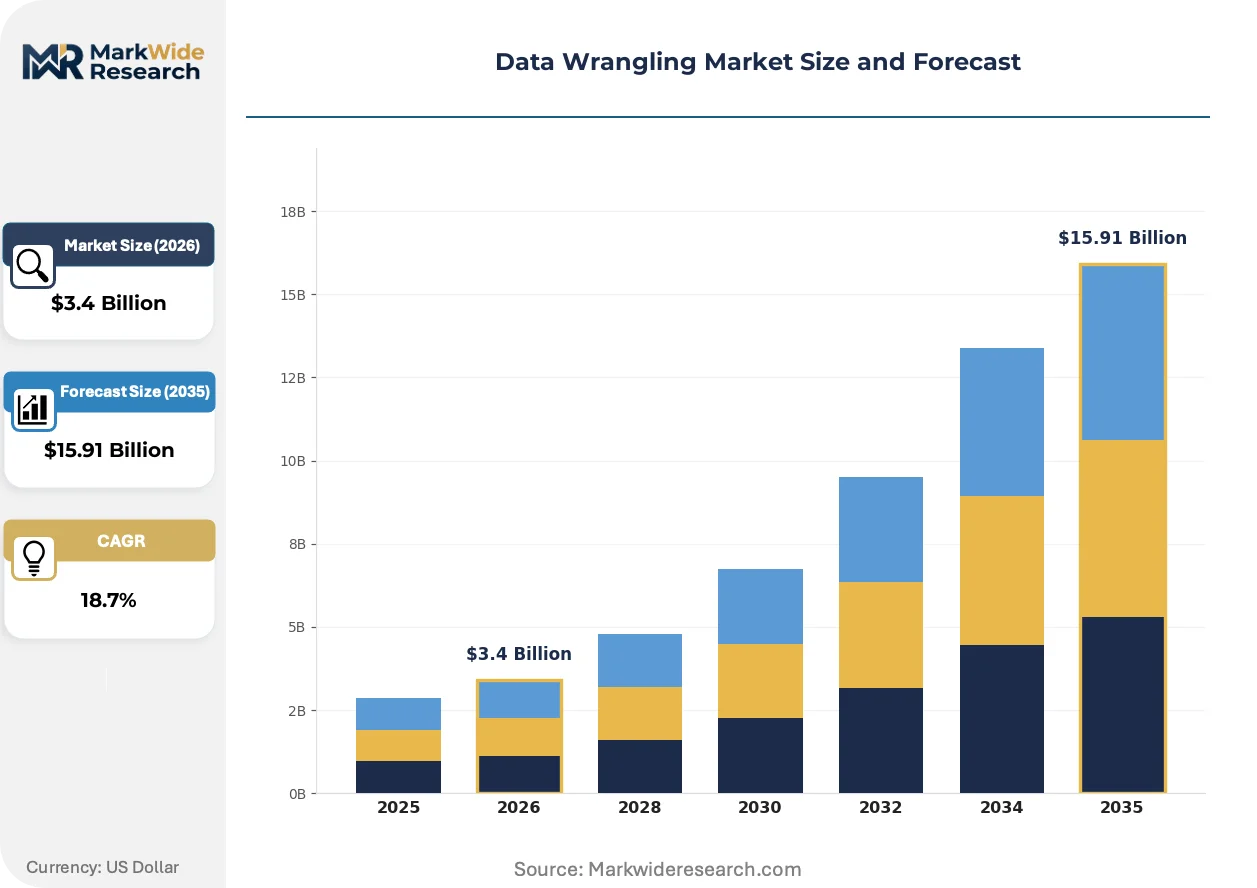
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $15.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Data Preparation, Data Cleaning, Data Transformation, Data Integration End User: IT Departments, Data Analysts, Business Intelligence Professionals, Data Scientists Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Technology: ETL Tools, Data Lakes, Data Pipelines, Machine Learning |
| Companies Covered | SAS Institute Inc., Informatica Inc., Alteryx Inc., Databricks Inc., IBM Corporation, Oracle Corporation, Altair Engineering Inc., TIBCO Software Inc., Teradata Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Wrangling Market Strategic Shifts & Innovations
Automated intelligence layers are resequencing how data moves from raw ingestion to model-ready states, eliminating friction points that previously required human intervention.
Neural schema mapping engines are displacing manual pattern recognition in heterogeneous source integration. Financial services firms in the United States are deploying these systems at scale for regulatory reporting pipelines. The technology is displacing traditional ETL developer roles while compressing preparation cycle times from weeks to hours.
The EU AI Act's governance requirements are mandating documented transformation workflows and immutable audit trails for training data pipelines. European financial institutions and healthcare providers are restructuring procurement specifications to prioritize lineage-native platforms. German and French regulators are already enforcing documentation standards that exceed current vendor capabilities.
Subscription-based platform procurement is replacing perpetual license models across enterprise data infrastructure. CIOs in US Fortune 500 companies are consolidating vendor relationships around integrated lakehouse architectures. This consolidation pattern is most visible in financial services and healthcare verticals where compliance overhead favors single-platform standardization.
Data Wrangling Market Segmentation
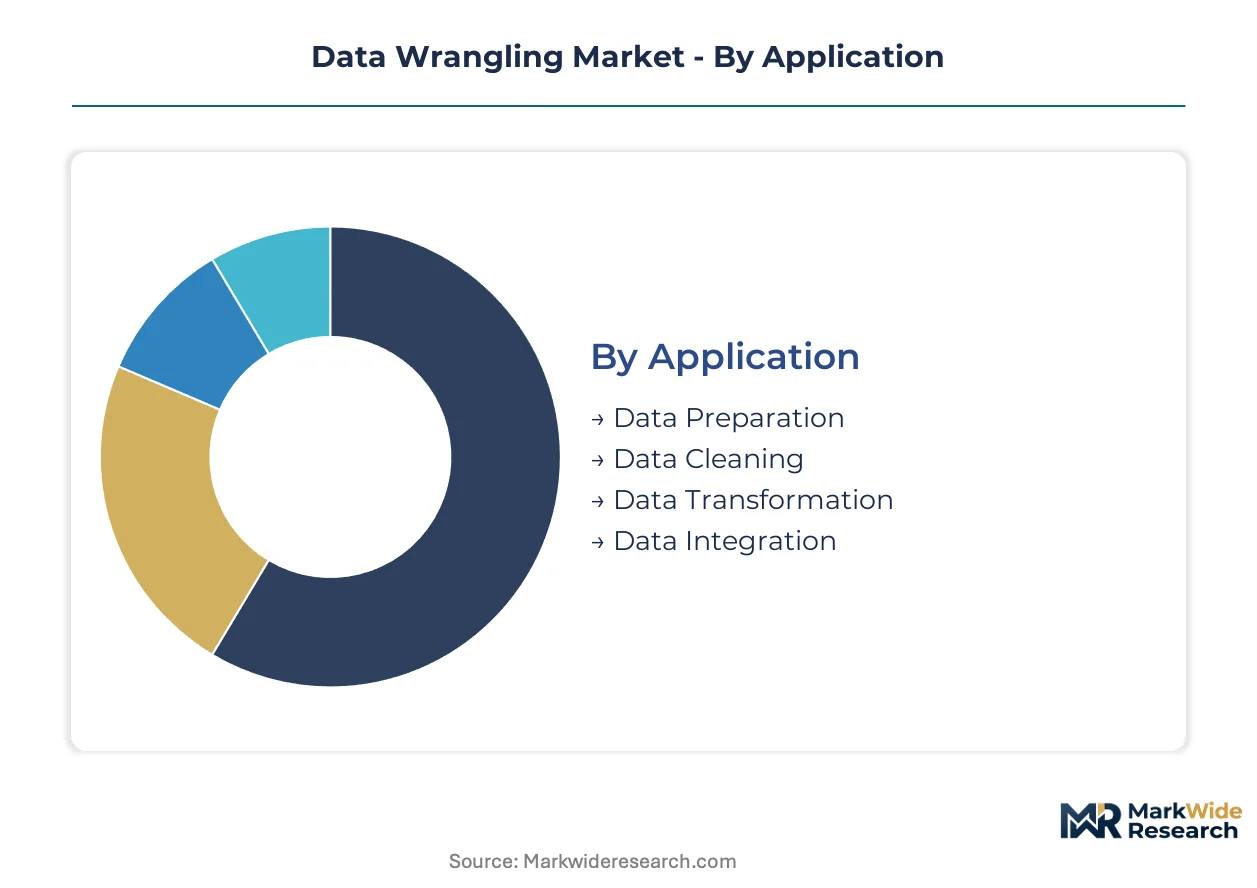
Segmentation in data wrangling reveals how procurement authority, infrastructure maturity, and automation readiness fragment purchasing behavior. Buyers prioritize different capability bundles based on compliance exposure, technical debt, and workforce composition.
Application:
Substitution pressure runs strongest through data preparation and data cleaning segments as machine learning automation collapses manual workflows into unified platforms.
- Data Preparation:Schema inference engines and automated type detection now handle ingestion-to-analysis pipelines previously requiring manual scripting. Financial services firms in the United States deploy these capabilities for regulatory reporting compression.
- Data Cleaning:Outlier detection, deduplication, and imputation algorithms displace spreadsheet-based quality assurance. HIPAA de-identification requirements elevate this function to compliance-critical status among US healthcare systems.
- Data Transformation:Format normalization and structural conversion for heterogeneous source integration.
- Data Integration:Unified access layers bridging siloed operational and analytical data stores.
Data preparation retains volume leadership; data cleaning holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade governance deployments from self-service analyst tools.
- IT Departments:Centralized procurement of governed pipeline infrastructure with enterprise security certifications. These buyers consolidate vendor relationships around lakehouse architectures in US Fortune 500 enterprises.
- Data Analysts:Visual preparation interfaces with minimal coding requirements. SAS Institute sustains R&D intensity around this persona to sustain business-user accessibility.
- Business Intelligence Professionals:Dashboard-ready data feeds with semantic layer integration.
- Data Scientists:Programmatic access to raw and transformed features for model development.
IT departments retain volume leadership; data analysts represent the fastest-growing trajectory.
Deployment:
Volume concentration shifts toward consumption-based models as organizations retire capital-intensive infrastructure.
- Cloud-Based:Elastic compute for variable transformation workloads with usage-based billing. Cloud-native ETL retirement accelerates subscription expansion across North American enterprises.
- SaaS:Fully managed platforms eliminating infrastructure operations overhead. Databricks competes through unified lakehouse architectures collapsing separate transformation layers.
- On-Premises:Air-gapped environments for classified or sovereignty-constrained data processing.
- Hybrid:Split architectures preserving sensitive data locally while bursting transformation to cloud.
Cloud-based deployment retains volume leadership; SaaS gains share fastest.
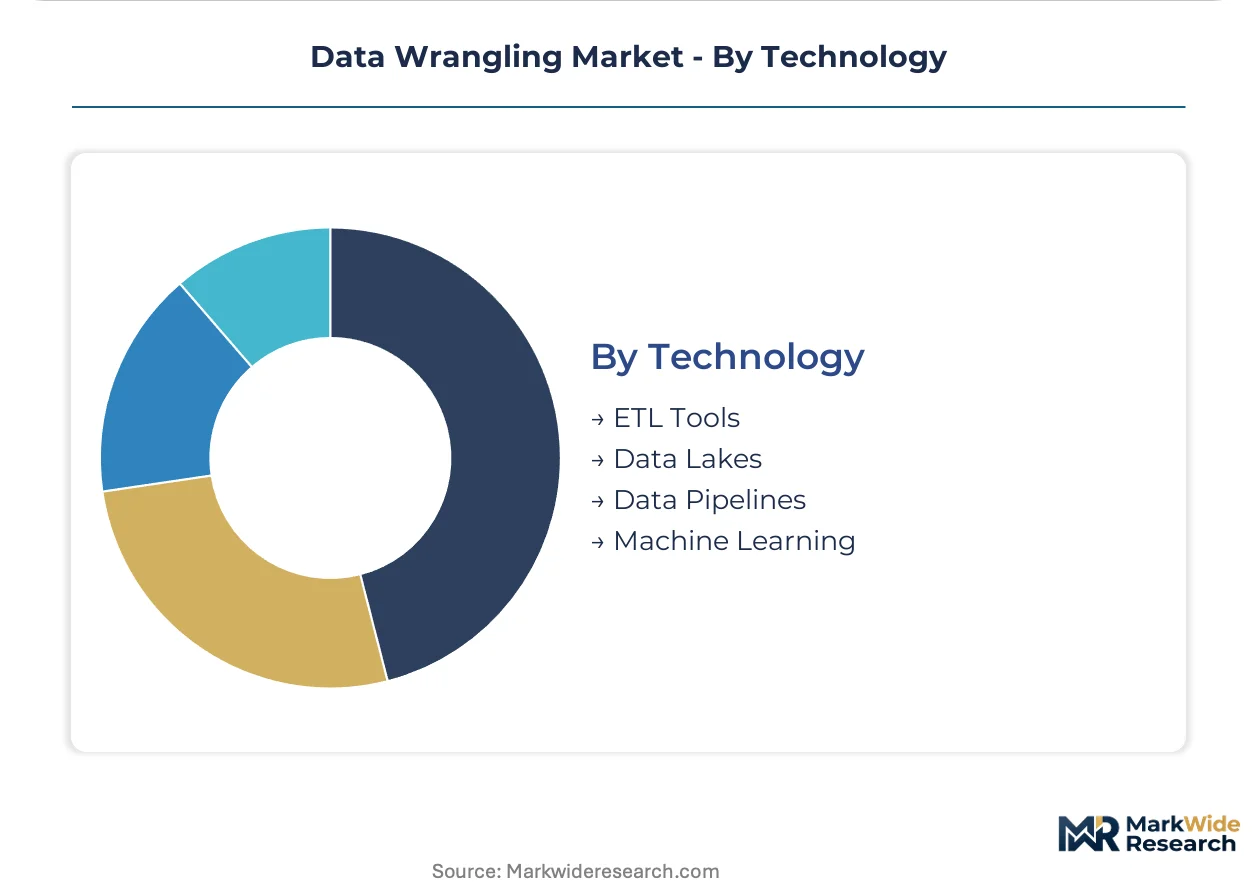
Technology:
Margin concentration pools in integration and pipeline segments where recurring enterprise subscriptions lock in multi-year contracts.
- Data Pipelines:Orchestrated movement and transformation workflows with lineage tracking. EU AI Act training data mandates pull governed pipeline investments from European financial services and healthcare providers.
- ETL Tools:Traditional extract-transform-load engines facing displacement by streaming-native alternatives. Legacy entrenchment extends timelines for Fortune 500 platform consolidation.
- Data Lakes:Raw storage architectures requiring subsequent wrangling for analytical consumption.
- Machine Learning:Automated schema mapping and intelligent imputation displacing manual scripting workflows.
Data pipelines retain volume leadership; machine learning holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium platform costs for compliance-critical deployments, while emerging market procurement remains highly sensitive to subscription pricing tiers.
United States
Fortune 500 enterprises in financial services and healthcare drive concentrated demand for governed pipeline infrastructure. HIPAA de-identification standards and SEC audit trail requirements elevate data cleaning and validation to procurement-critical status. New York and San Francisco Bay Area clusters host the densest concentrations of lakehouse architecture deployments.
Germany
Automotive and industrial manufacturing conglomerates anchor European demand for traceable data lineage systems. EU AI Act training data mandates and GDPR compliance frameworks pull investment toward immutable audit trail capabilities. Munich and Stuttgart industrial corridors are restructuring procurement specifications to prioritize lineage-native platforms.
United Kingdom
London-based financial services firms expand adoption of automated schema mapping for regulatory reporting compression. FCA operational resilience requirements intersect with emerging algorithmic accountability standards. The City of London and Canary Wharf clusters are displacing traditional ETL developer roles through neural schema inference engines.
France
Healthcare providers and pharmaceutical groups elevate data quality certification to RFP-mandated status. CNIL enforcement of GDPR data processing documentation shapes vendor selection filters. Paris-Saclay research cluster and Lyon biotech corridor are consolidating around ISO 8000-compliant preparation platforms.
Japan
Manufacturing keiretsu and automotive suppliers drive demand for hybrid deployment architectures bridging on-premises sovereignty constraints with cloud burst capacity. METI data governance guidelines and JIS quality standards shape procurement specifications. Tokyo-Osaka industrial corridor is piloting real-time streaming convergence for operational analytics use cases.
Data Wrangling Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Cloud-native specialists command premium positioning through unified architecture stacks, while legacy integration vendors defend installed bases through compliance certification depth. Three archetypes dominate: governance-heavy enterprise platforms, visual self-service tools, and unified lakehouse environments. Competitive moves concentrate on M&A for ML-augmented capabilities and strategic partnerships for multi-cloud integration coverage.
Within the governance-centric tier, Informatica Inc. and SAS Institute Inc. exemplify archetypes anchored in regulated industry penetration. Databricks Inc. occupies a distinct position representing unified lakehouse consolidation. These three entities collectively illustrate how competitive positioning fragments across architectural philosophy rather than converging on uniform platform design.
| Leading Market Players |
|---|
| SAS Institute Inc. |
| Informatica Inc. |
| Alteryx Inc. |
| Databricks Inc. |
| IBM Corporation |
| Oracle Corporation |
| Altair Engineering Inc. |
| TIBCO Software Inc. |
| Teradata Corporation |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day implementation timelines for enterprise data pipeline deployments concentrate pricing power with vendors possessing pre-certified compliance modules, while cloud compute cost volatility feeds back into subscription model design. This lead-time band separates governed platform providers from point-solution competitors.
Pricing Analysis
After-sales revenue from professional services and extended support contracts drives lifetime value for data wrangling platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance exposure and integration complexity. Price differentiation rests on ISO 8000 certification grade and dedicated customer success engineering. Cost compression in the standard tier is intensifying because hyperscaler marketplace listings commoditize basic transformation features. Mid-market companies below Fortune 500 scale demonstrate highest price sensitivity; regulated financial services firms show lowest.
Supply Chain Analysis
Inbound logistics costs for GPU-accelerated compute instances fluctuate with container availability across Pacific trade lanes serving US West Coast cloud regions. Geographic supply concentration centers on the United States, Ireland, and Singapore for hyperscaler data center infrastructure. Raw material dependencies include advanced semiconductors, specialized memory modules, and redundant fiber connectivity. Single-source vulnerability in NVIDIA GPU supply creates procurement risk for ML-augmented wrangling vendors. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data wrangling incumbents face substitution defense against unified lakehouse platforms collapsing separate transformation layers into single environments. This threat compresses addressable market for standalone preparation tools.
For Market Incumbents: Consolidate around governance-heavy certification depth to defend against Databricks-style architectural consolidation. Deepen ISO 8000 and EU AI Act compliance modules to anchor regulated industry relationships. Acquire streaming-native specialists to address real-time operational analytics convergence.
For New Entrants and Emerging Players: Anchor in mid-market underpenetration below Fortune 500 scale where current platform pricing and deployment complexity create white space. Target US healthcare systems with HIPAA-optimized, lightweight SaaS offerings. Pursue channel partnerships with regional systems integrators lacking data engineering practices.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment infrastructure as hyperscaler capex efficiency improves. Long-term viability favors platforms with embedded compliance automation rather than point-tool architectures. Acquisition target archetype: ML-augmented schema inference specialists with financial services referenceability. Signal to watch: EU AI Act enforcement velocity accelerating procurement specification changes.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Lakehouse architectures from Databricks collapse separate ETL layers into unified environments. |
| Acquisition of Specialist Firm | Neural schema mapping engines displace manual pattern recognition in regulatory reporting pipelines. |
| Strategic Partnership | Multi-cloud coverage partnerships address fragmented governance across AWS, Azure, and Google Cloud. |
| Geographic Expansion | European investment responds to EU AI Act training data mandates pulling governed pipeline demand. |
| Product Launch | Real-time streaming convergence opens operational analytics categories beyond batch processing. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews combined with secondary validation. Stakeholder roles included data engineering directors, compliance officers at financial services firms, healthcare IT procurement leads, cloud platform integration specialists, and regulatory affairs managers. Secondary sources encompassed SEC filings from publicly traded vendors, hyperscaler capex disclosures, EU regulatory documentation, and hospital procurement databases. Bottom-up sizing of deployment instances was triangulated against top-down IT spending allocation models.
Across the analysis window, forecasts were derived from segmented growth trajectory modeling. Segmentation dimensions included deployment model, organization size tier, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were computed from year-over-year expansion rates applied to base-year volume estimates. Industry-specific inputs incorporated cloud-native ETL retirement velocity and EU AI Act implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and stable hyperscaler pricing; material deviation would warrant model refresh. Specific risk factors include algorithmic accountability legislation acceleration and legacy system entrenchment extending beyond projected consolidation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Mining Tools Market
Analytics
Europe Retail Analytics Market
Analytics
Advanced Analytics Market
Analytics
Latin America Big Data Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Text Analytics Market
Analytics
Content Analytics Software Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Patent Analytics Services Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Prescriptive Analytics Market