
 Car-Hailing Software Market | 2026-2036
Car-Hailing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Car-Hailing Software Market Insights
The EU AI Act is shifting the cost-of-entry calculus for algorithmic pricing and driver-matching systems across European deployments. Uber Technologies, Inc. leverages its proprietary mapping stack to sustain route-optimization advantages in dense urban corridors. Didi Chuxing Technology Co., Ltd. anchors its competitive posture through in-house development of autonomous vehicle interfaces and electric fleet integration. Lyft, Inc. differentiates via subscription loyalty programs that lock in recurring commuter revenue.
Car-hailing software comprises cloud-native platforms that coordinate real-time matching between vehicle supply and passenger demand through GPS telemetry, dynamic pricing engines, and embedded payment rails. These systems process sub-second location updates across millions of concurrent sessions to minimize wait times and maximize driver utilization. Ride-sharing and taxi services dominate transaction volume, while shuttle services capture expanding share in corporate campus and airport corridor contracts. Cloud-based deployment leads infrastructure spend as fleet operators abandon on-premise data centers for elastic compute capacity.
The EU AI Act, GDPR, and the F-Gas Regulation collectively reshape platform architecture requirements from data governance to vehicle fleet emissions tracking. India's BIS standards and CDSCO guidelines for connected vehicle data add compliance layers for operators expanding into South Asian markets. Stakeholders must monitor regulatory divergence between algorithmic accountability regimes and emissions disclosure mandates when prioritizing platform development roadmaps.
Market Dynamics
Cloud-native dispatch architectures are forcing incumbent operators to abandon monolithic codebases as real-time matching latency becomes the primary competitive battleground. The shift from on-premise data centers to elastic compute infrastructure concentrates vendor leverage among hyperscale cloud providers.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Fleet operators deploying in Germany, France, and the Netherlands must document decision logic for driver-ranking systems, creating standardized procurement requirements for compliant software vendors.
- Corporate campus shuttle contracts:Enterprise mobility budgets are consolidating around integrated platform providers that bundle employee transit with carbon accounting dashboards for ESG reporting.
- India's connected vehicle data infrastructure:BIS standards for telematics interoperability are accelerating fleet digitization in Bangalore and Mumbai, where driver network density determines market access.
Market Restraints
- Hyperscale cloud concentration:AWS, Azure, and GCP control elastic compute pricing for dispatch platforms, exposing operators to egress cost volatility during demand spikes.
- F-Gas Regulation refrigerant tracking:EU fleet electrification mandates require embedded emissions monitoring for thermal management systems, adding hardware integration complexity to software stacks.
- Autonomous vehicle interface fragmentation:Proprietary sensor fusion protocols from lidar and camera suppliers prevent modular substitution, locking platforms into single-source perception hardware.
Strategic Opportunities
- India's tier-2 city expansion:Hyderabad, Pune, and Chennai present driver supply gaps that cloud-native platforms can capture before network effects consolidate around incumbents.
- ISO 26262 functional safety certification:Platforms achieving ASIL-D ratings for autonomous dispatch modules can access automotive OEM white-label contracts currently closed to consumer-grade software.
- Edge computing and 5G network slicing convergence:Sub-10ms location update processing enables predictive demand positioning without centralized cloud dependency, reducing latency for airport and stadium corridors.
Industry Challenges
- Real-time systems engineering talent scarcity:Distributed systems architects capable of sub-second matching at million-concurrent-session scale command compensation premiums that strain R&D budgets.
- Legacy taxi cooperative integration friction:Municipal fleet operators in Italy and Spain operate on decades-old dispatch protocols that resist API-based interoperability without middleware translation layers.
- GDPR data localization audit timelines:Cross-border passenger trip records require jurisdictional partitioning that extends platform deployment cycles by six to nine months in multi-country rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car-Hailing Software Market |
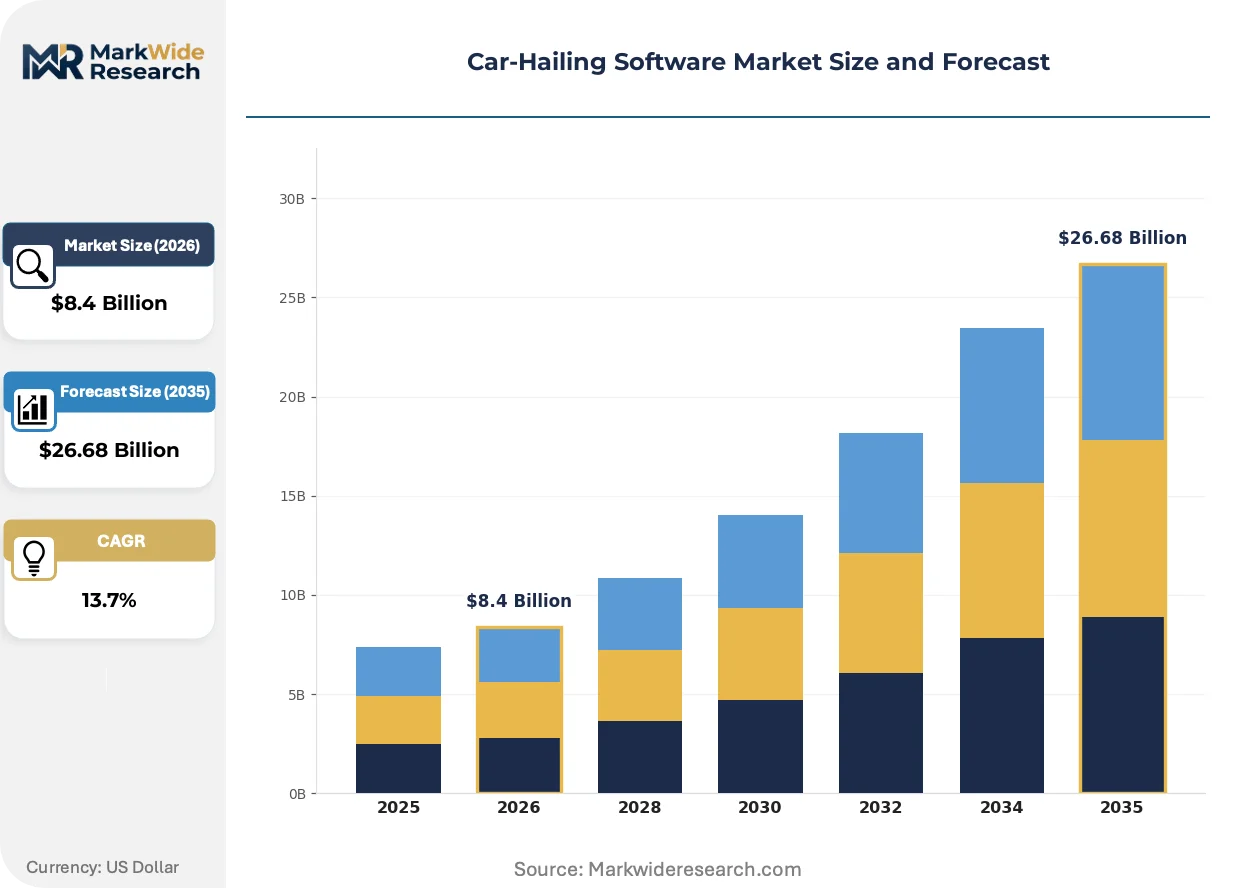
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Sharing, Carpooling, Shuttle Services, Taxi Services Deployment Model: Cloud-Based, On-Premise, Hybrid, Mobile Application End User: Individuals, Enterprises, Fleet Operators, Service Providers Features: GPS Tracking, Payment Integration, Driver Rating, Customer Support |
| Companies Covered | Uber Technologies, Inc., Didi Chuxing Technology Co., Ltd., Lyft, Inc., Grab, Ola Cabs, Careem, Bolt, Go-Jek, VivoCabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car-Hailing Software Market Trends and Innovations
Edge-native inference engines are compressing decision latency from centralized cloud dependencies to roadside and vehicle-embedded compute nodes. This architectural pivot is redistributing software value capture from platform operators to semiconductor and telecom infrastructure suppliers.
Transformer-based demand prediction models trained on multimodal traffic, weather, and event data are rewriting how platforms position idle supply before ride requests materialize. Fleet operators in Tokyo and Singapore are deploying these systems for predictive repositioning in central business districts. The compression of driver deadhead miles is shifting unit economics toward utilization rate rather than trip volume as the primary margin driver.
The EU AI Act's risk classification framework for automated decision systems is forcing algorithmic documentation standards that previously existed only in financial services. Platforms serving European markets must maintain technical files demonstrating human oversight capabilities for driver deactivation and pricing surge triggers. Germany's KBA and France's CNIL are conducting coordinated enforcement sweeps that favor vendors with pre-built audit trail modules.
Subscription-based commuter contracts are displacing per-trip transactions in dense urban corridors where riders value price predictability over flexibility. Corporate benefits administrators in London and New York are consolidating vendor relationships around annual mobility budgets rather than expense reimbursement workflows. This procurement consolidation concentrates buyer power and pressures platforms to integrate with HRIS and carbon accounting systems as table stakes for contract renewal.
Car-Hailing Software Market Segmentation
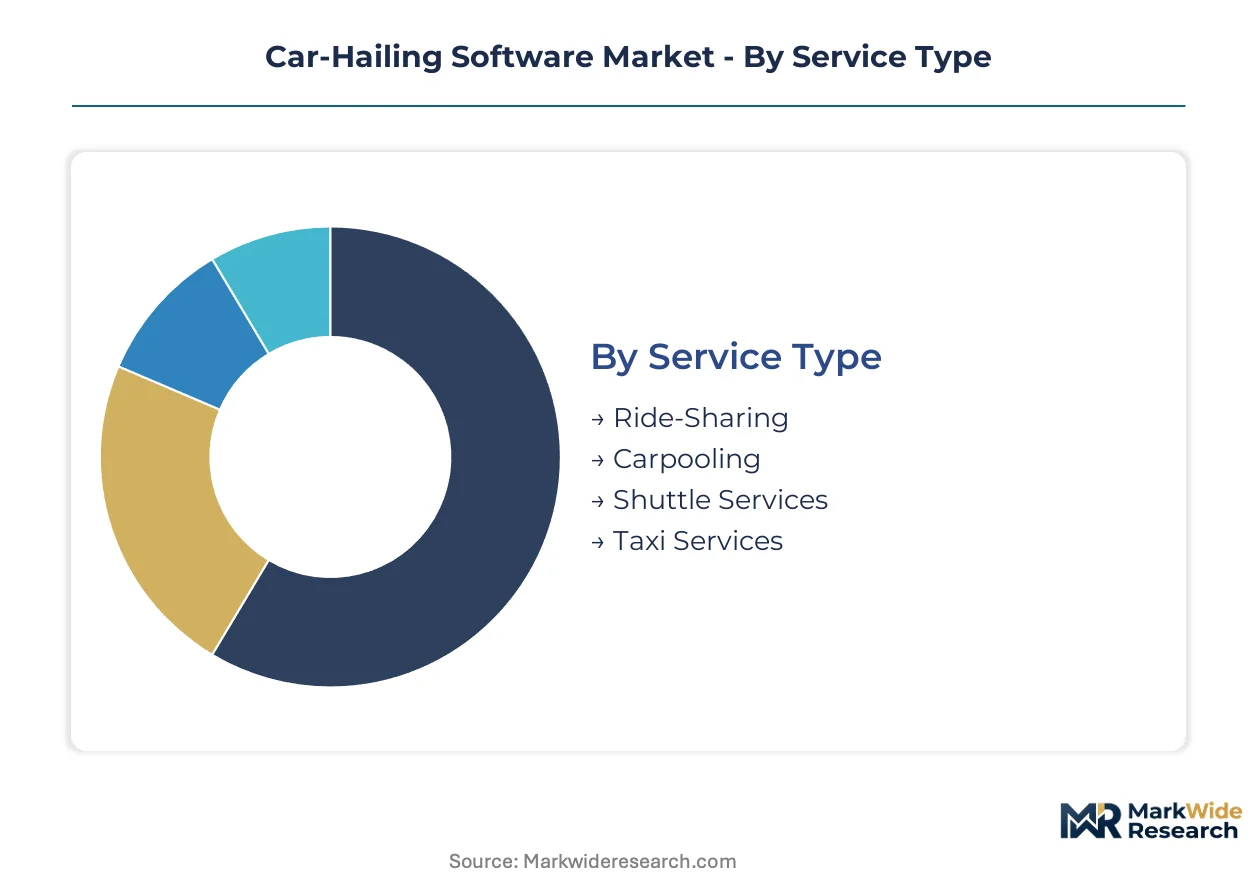
Car-hailing software segments diverge sharply in capital requirements, with cloud infrastructure and enterprise deployment demanding sustained R&D investment while consumer-facing features compete on marginal development cost. Platform operators must align segment focus with balance sheet capacity and technical debt tolerance.
Service Type:
Ride-sharing and taxi platforms require the heaviest upfront investment in driver acquisition subsidies and regulatory compliance infrastructure across multiple jurisdictions.
- Ride-Sharing:Dynamic pricing engines coordinate peer-to-peer vehicle supply through algorithmic matching that processes millions of concurrent location updates. Demand concentrates in India's tier-1 corridors where Ola Cabs and Uber compete for driver network density in Bangalore and Mumbai; network effects create winner-take-most dynamics that demand patient capital.
- Taxi Services:Legacy dispatch protocol integration dominates municipal procurement in Italy and Spain, where decades-old cooperative systems resist API interoperability without middleware investment. Fleet digitization mandates from Germany's KBA and France's CNIL are accelerating compliance spend for audit trail modules.
- Carpooling:Route-optimization algorithms match multiple passengers along shared corridors, reducing per-trip emissions for ESG reporting.
- Shuttle Services:Corporate campus and airport corridor contracts bundle fixed-route scheduling with carbon accounting dashboards.
Ride-sharing absorbs the bulk of installed capacity; shuttle services are expanding most quickly through enterprise mobility budget consolidation.
Deployment Model:
Cloud-native architectures dominate new platform builds as elastic compute capacity replaces fixed data center commitments, though hybrid deployments persist in markets with strict data localization requirements.
- Cloud-Based:Hyperscale providers AWS, Azure, and GCP supply elastic infrastructure that scales with demand spikes, though egress cost volatility exposes operators to margin compression. EU AI Act algorithmic transparency mandates in Germany, France, and Netherlands require standardized procurement documentation that favors vendors with pre-built compliance modules.
- Hybrid:Jurisdictional partitioning for GDPR compliance extends deployment cycles by six to nine months in multi-country rollouts, demanding dedicated DevOps investment.
- On-Premise:Legacy operators in Italy and Spain maintain fixed infrastructure to preserve municipal cooperative relationships.
- Mobile Application:Consumer-facing interfaces compete on sub-second latency optimization and embedded payment rail integration.
Cloud-based deployment captures the greatest share of new infrastructure spend; hybrid configurations are climbing the fastest as regulatory divergence multiplies.
End User:
Enterprise and fleet operator segments command premium pricing through annual contract value, while individual consumers drive transaction volume at lower per-unit economics.
- Enterprises:Corporate benefits administrators in London and New York consolidate vendor relationships around annual mobility budgets rather than expense reimbursement workflows, demanding HRIS and carbon accounting integration as table stakes. Subscription-based commuter contracts displace per-trip transactions where riders value price predictability.
- Individuals:Price-sensitive demand in India's tier-2 cities of Hyderabad, Pune, and Chennai presents driver supply gaps that platforms can capture before network effects consolidate.
- Fleet Operators:Electrification mandates require embedded emissions monitoring for thermal management systems under EU F-Gas Regulation.
- Service Providers:White-label platform licensing to automotive OEMs demands ISO 26262 ASIL-D functional safety certification.
Individual users generate the highest transaction volume; enterprise contracts are gaining share fastest through procurement consolidation.
Features:
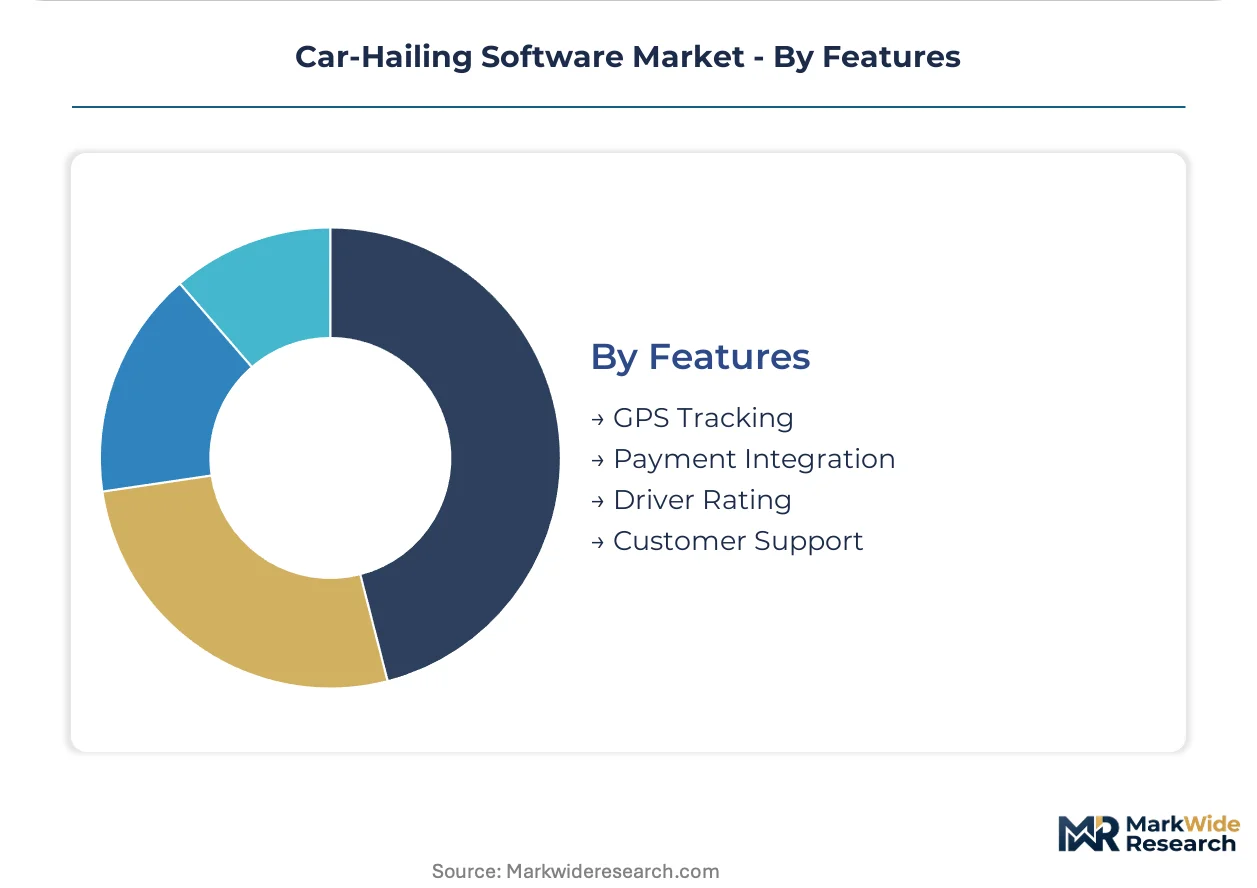
Core infrastructure features command development priority as competitive table stakes, while differentiation shifts toward predictive capabilities and compliance tooling.
- GPS Tracking:Sub-second location telemetry underpins real-time matching latency that determines wait times and driver utilization rates. Edge computing and 5G network slicing convergence enables sub-10ms processing for predictive demand positioning in airport and stadium corridors.
- Payment Integration:Embedded payment rails reduce friction but require PCI-DSS compliance investment and regional processor partnerships.
- Driver Rating:Algorithmic deactivation systems fall under EU AI Act risk classification, requiring technical files demonstrating human oversight capabilities.
- Customer Support:Automated resolution layers reduce unit costs but must escalate to human agents for regulatory complaints.
GPS tracking underpins the majority of platform architecture decisions; payment integration is expanding most quickly through embedded finance partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme and special economic zones in Bangalore and Hyderabad have concentrated cloud-native dispatch platform development, drawing hyperscale cloud infrastructure investment toward South Asian corridors.
United States
Corporate campus shuttle contracts and subscription commuter programs drive enterprise mobility spend in New York and San Francisco. The SEC's climate disclosure rules pressure platforms to integrate carbon accounting dashboards for ESG reporting. Silicon Valley clusters anchor real-time systems engineering talent pools for sub-second matching optimization.
Germany
Fleet electrification mandates and autonomous vehicle testing corridors accelerate software-hardware integration demand. Germany's KBA enforces EU AI Act algorithmic transparency requirements for driver-ranking systems. Berlin and Munich host automotive OEM white-label platform development for ISO 26262 ASIL-D certification.
India
Driver network density competition between Ola Cabs and Uber concentrates procurement of BIS-compliant telematics in Bangalore and Mumbai. CDSCO guidelines for connected vehicle data add compliance layers for fleet digitization. Hyderabad, Pune, and Chennai present tier-2 expansion opportunities before network effects consolidate.
France
Municipal taxi cooperative digitization and airport corridor predictive positioning systems reshape urban mobility procurement. France's CNIL coordinates with Germany's KBA on EU AI Act enforcement sweeps favoring audit trail modules. Paris anchors transformer-based demand prediction model deployment for central business district repositioning.
United Kingdom
Corporate benefits administrator consolidation around annual mobility budgets pressures HRIS and carbon accounting integration. GDPR data localization requirements extend multi-country platform deployment cycles. London's subscription commuter contracts displace per-trip transactions where riders value price predictability.
Car-Hailing Software Market Competitive Landscape
United States-based platform operators anchor the cloud-native tier; Chinese specialists hold autonomous vehicle interface development. The vendor base clusters around three strategic archetypes: hyperscale-integrated dispatch platforms, automotive OEM white-label licensors, and enterprise mobility suite bundlers. Dominant competitive moves include geographic expansion into India's tier-2 corridors and strategic partnerships for edge computing infrastructure.
Within the hyperscale-integrated tier, Uber Technologies, Inc. and Lyft, Inc. exemplify North American platform architecture, while Didi Chuxing Technology Co., Ltd. occupies a parallel position in autonomous vehicle interface development. These three entities represent divergent strategic postures: proprietary mapping stack leverage, subscription loyalty program lock-in, and in-house electric fleet integration respectively.
| Leading Market Players |
|---|
| Uber Technologies, Inc. |
| Didi Chuxing Technology Co., Ltd. |
| Lyft, Inc. |
| Grab |
| Ola Cabs |
| Careem |
| Bolt |
| Go-Jek |
| VivoCabs |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud egress fees cascade through software vendor pricing tiers as AWS, Azure, and GCP concentrate elastic compute supply. Fleet operators absorbing these input costs pass differential pricing to enterprise buyers locking annual contracts versus spot-demand consumers in India's tier-2 corridors.
Pricing Analysis
Short lead-time premiums attach to compliant deployments under Germany's KBA and France's CNIL enforcement timelines, while spot procurement discounts emerge for non-certified modules. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 26262 certification grade and GDPR audit trail completeness. Pricing pressure stems from hyperscale cloud concentration exposing margins to egress cost volatility during demand spikes. Enterprise fleet operators exhibit lowest price sensitivity due to ESG reporting mandates; individual consumers in Hyderabad and Pune show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for edge-compute semiconductor fabrication feeding dispatch optimization hardware. The supply chain draws from China's rare earth processing for electric fleet magnetics, German automotive sensor production, and Indian software engineering clusters for platform development. Tariff exposure runs through US-China technology trade restrictions on AI training chips. Distribution runs through hyperscale cloud marketplaces and direct enterprise licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
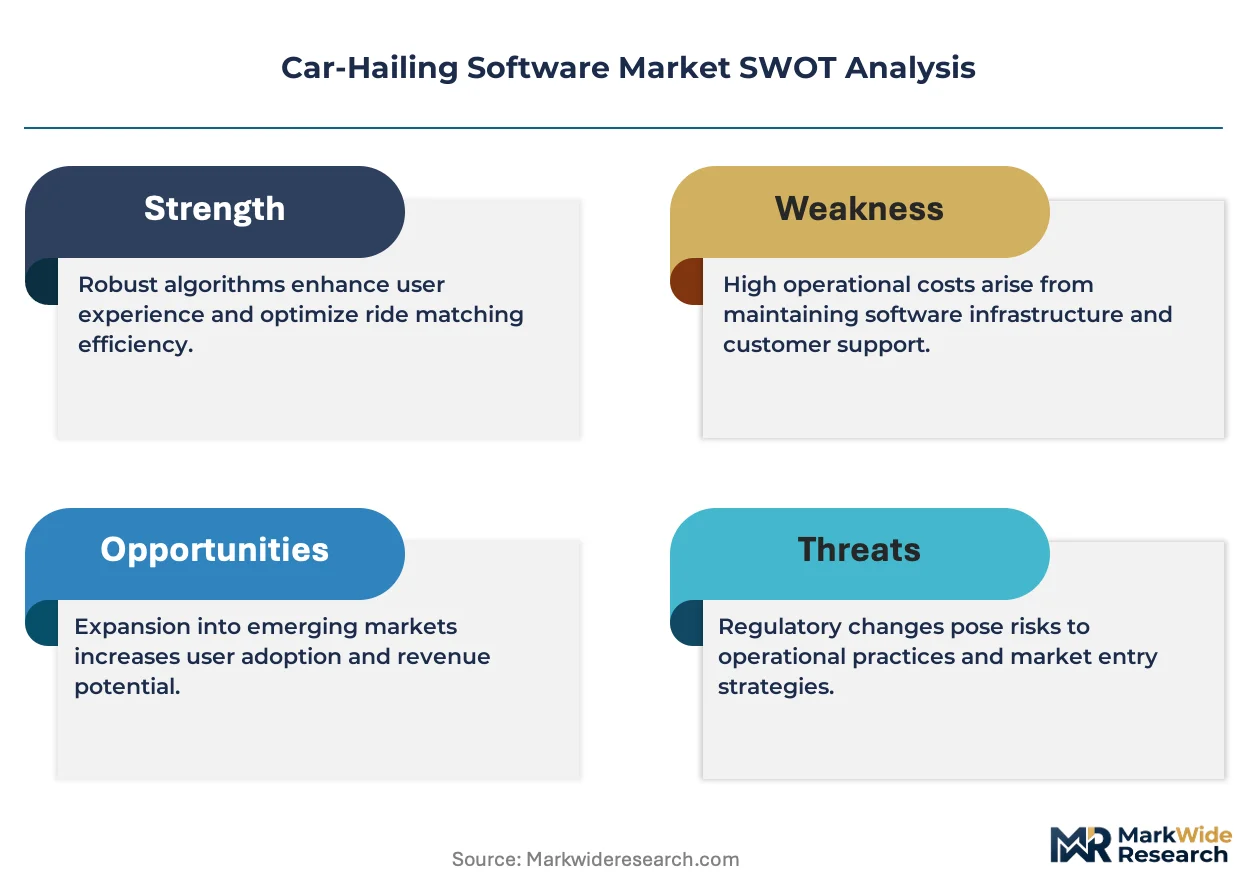
Real-time systems engineering talent scarcity props pricing power for platforms achieving sub-second matching latency, as distributed systems architects command compensation premiums that strain competitor R&D budgets.
For Market Incumbents: Anchor proprietary mapping stack advantages through continued investment in route-optimization R&D to defend against edge-native inference competitors. Pursue ISO 26262 ASIL-D certification for autonomous dispatch modules to lock automotive OEM white-label contracts. Deepen backward integration into cloud infrastructure through reserved capacity agreements with hyperscale providers to buffer egress cost volatility. For New Entrants and Emerging Players: India's BIS standards for telematics interoperability in tier-2 cities open a window for cloud-native platforms to capture driver supply gaps before network effects consolidate. Target Hyderabad, Pune, and Chennai with lightweight deployment models emphasizing rapid driver onboarding subsidies. Leverage subscription-based commuter contracts as the go-to-market angle to displace per-trip transactions in corporate mobility budgets. For Investors and Strategic Acquirers: Coordinated enforcement sweeps by Germany's KBA and France's CNIL is the leading indicator that algorithmic transparency compliance capabilities will separate viable acquisition targets from stranded assets. Platforms with pre-built audit trail modules and documented human oversight systems represent the durable archetype across the investment horizon. Monitor EU AI Act risk classification expansions as the signal for regulatory compliance premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Partnership | Sub-10ms location processing reduces cloud dependency for airport and stadium corridors. |
| ISO 26262 ASIL-D Certification Investment | Automotive OEM white-label contracts demand functional safety ratings unavailable to consumer-grade platforms. |
| GDPR Audit Trail Module Development | Germany's KBA and France's CNIL enforcement sweeps favor vendors with pre-built compliance documentation. |
| India Tier-2 City Geographic Expansion | Hyderabad, Pune, and Chennai present driver supply gaps before network effects consolidate around incumbents. |
| Subscription Loyalty Program Launch | Corporate benefits administrators in London and New York consolidate annual mobility budgets around price predictability. |
Research Methodology
Independent corroboration across platform engineering leads, fleet procurement officers, and hyperscale cloud solution architects underwrites the qualitative findings. Primary interviews with CTOs at dispatch software vendors, enterprise mobility managers, and regulatory compliance specialists combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement databases. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure spend patterns and connected vehicle deployment data.
Rate-of-change decomposition separates volume growth from pricing evolution across the analysis window. Segmentation dimensions modeled include deployment model, fleet size tier, vertical integration depth, regional regulatory cluster, and algorithmic complexity tier. CAGRs derive from elasticity-adjusted demand curves incorporating driver network density saturation points and compliance cost pass-through rates. Forecast inputs incorporate edge computing adoption curves and 5G network slicing deployment timelines.
Caveats apply where EU AI Act enforcement intensity, hyperscale cloud pricing resets, or autonomous vehicle interface standardization could materially shift the outlook. Forecasts reflect assumptions about regulatory divergence persistence and talent scarcity duration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Meditation Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Global Local SEO Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Business Card Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Global App Design Software Market
Software & Services
Time and Attendance Software Market
Software & Services
SAP HANA and S4HANA Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Custom Software Development Market