
 Bank Reconciliation Software Market | 2026-2036
Bank Reconciliation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bank Reconciliation Software Market Insights
Market Context with Strategic Players
Legacy spreadsheet-based reconciliation is shifting toward API-native platforms as enterprises demand real-time cash visibility. BlackLine leverages deep ERP integrations to anchor its position among Fortune 500 treasury departments. HighRadius competes through AI-powered cash application modules that reduce manual matching labor. FloQast specializes in close-management workflows that extend reconciliation into the broader financial close process.
Technical Definition and Structural Segments
Bank reconciliation software automates the matching of internal general ledger entries against external bank statements through rule engines, machine learning algorithms, and exception-flagging protocols, serving primarily to eliminate manual variances and accelerate period-end close cycles. Cloud-based deployment leads absolute revenue contribution as finance teams abandon on-premise maintenance overhead, while automated reconciliation solutions capture the fastest growth trajectory by embedding predictive matching logic that learns from historical transaction patterns. Large enterprises still occupy the deepest margin pools due to complex multi-entity, multi-currency requirements, though medium enterprises represent the most contested acquisition segment as vendors race to capture upgrade cycles from QuickBooks and Excel-dependent operations.
Regulatory Framework and Forward Outlook
SOX compliance mandates in the United States and GDPR data-handling requirements in Europe shape product architecture by demanding immutable audit trails and geographic data residency controls, while ISO 20022 message standards across the Eurosystem and Federal Reserve wire modernization programs force vendors to rebuild ingestion pipelines around structured XML formats. SEC climate disclosure rules and EU CSRD reporting obligations are expanding reconciliation scope into sustainability-linked financial metrics. Stakeholders must monitor which vendors achieve native ISO 20022 compatibility versus bolt-on adapters, as this distinction will separate retained enterprise contracts from displacement risk during the ongoing payment infrastructure transition.
Market Dynamics
ISO 20022 migration across the Eurosystem and Federal Reserve wire modernization programs is forcing treasury departments to rebuild ingestion pipelines around structured XML formats, compressing vendor evaluation cycles and accelerating displacement of legacy flat-file systems.
Growth Catalysts
- Mid-sized enterprise automation:Finance teams at mid-market companies are abandoning Excel-dependent reconciliation workflows for cloud-native platforms that compress period-end close cycles from weeks to days.
- SOX compliance mandates:United States public companies face heightened audit scrutiny over cash controls, driving immutable audit trail requirements into procurement specifications.
- AI-powered matching engines:Machine learning algorithms that learn from historical transaction patterns are reducing manual exception handling labor by predicting variance sources before they surface.
Market Restraints
- Data residency requirements:GDPR geographic controls and emerging national data sovereignty laws in India and China fragment cloud deployment architectures, forcing vendors to maintain region-specific infrastructure.
- Legacy system entrenchment:Decades-old ERP installations at Fortune 500 treasuries create switching friction that extends sales cycles and inflates implementation costs.
- Talent scarcity in structured finance XML:The shallow pool of engineers fluent in ISO 20022 message standards constrains vendor development velocity and inflates compensation costs.
Strategic Opportunities
- Sustainability-linked financial metrics:SEC climate disclosure rules and EU CSRD reporting obligations are expanding reconciliation scope into carbon accounting and ESG-linked treasury data.
- API-native platform convergence:The intersection of open banking APIs and real-time payment rails is electrifying demand for continuous reconciliation rather than batch-processed matching.
- Embedded finance integration:Neobanks and fintech platforms serving small businesses represent an underpenetrated channel for white-labeled reconciliation modules.
Industry Challenges
- Multi-entity consolidation complexity:Corporate treasuries managing dozens of legal entities across jurisdictions struggle to harmonize chart-of-accounts structures for automated matching.
- Bank format heterogeneity:Thousands of regional and community banks maintain proprietary statement formats that resist standardization, forcing costly custom parser development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bank Reconciliation Software Market |
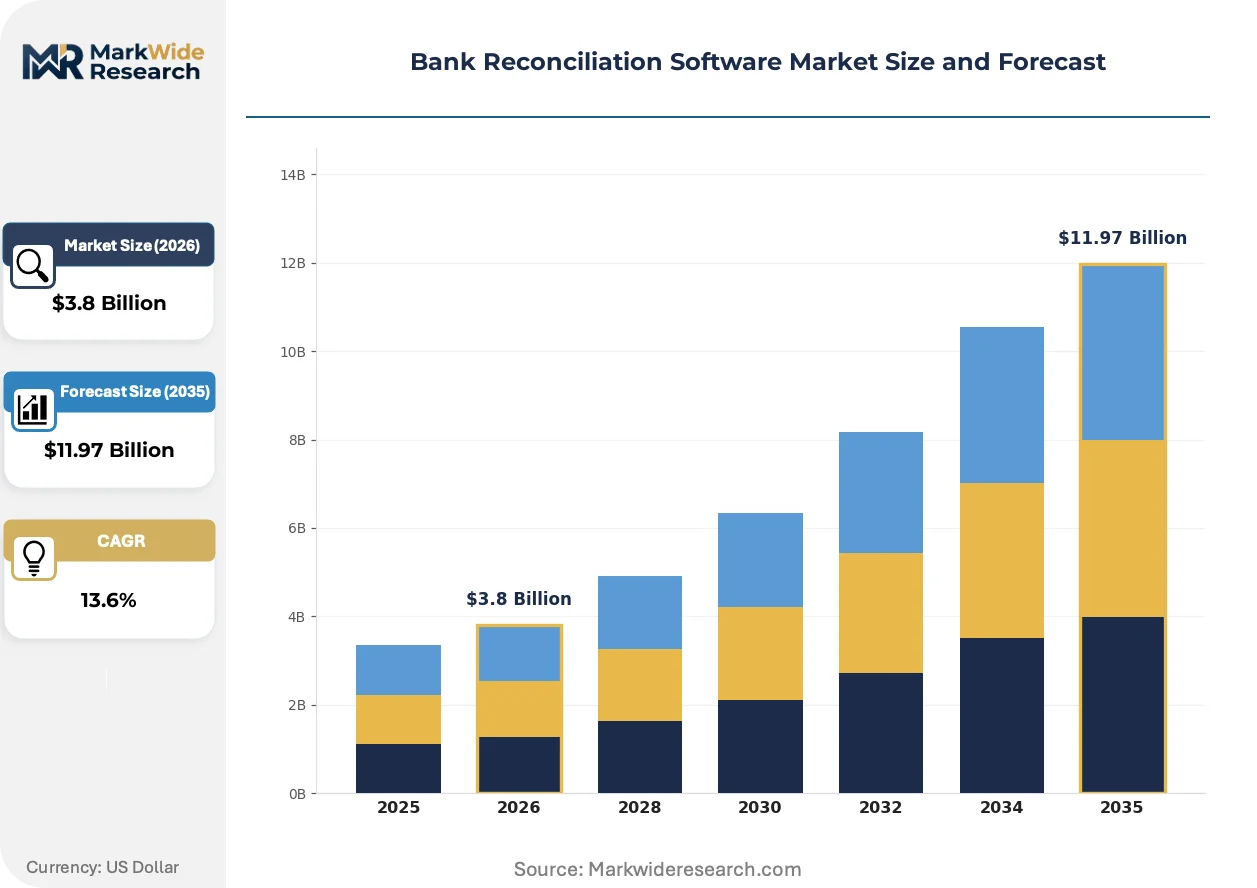
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Automated Reconciliation, Transaction Matching, Exception Management, Reporting & Analytics Use Case: Accounts Payable, Accounts Receivable, Cash Management, Fraud Detection Customer Type: Small Businesses, Medium Enterprises, Large Enterprises, Non-Profit Organizations |
| Companies Covered | BlackLine, HighRadius, FloQast, NetSuite, Xero, Sage Intacct, Trintech, Nomentia, ReconArt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bank Reconciliation Software Market Trends and Innovations
Real-time cash visibility is displacing batch-processed reconciliation as the defining capability for treasury technology investments, compressing the acceptable latency between transaction occurrence and ledger confirmation from days to minutes.
Embedded machine learning for predictive cash application is electrifying exception management workflows by anticipating which open invoices correspond to incoming payments before manual review. Mid-sized enterprises adopting these modules are reducing unapplied cash balances by half within two quarters. The technology is compressing headcount requirements in high-volume accounts receivable operations while elevating staff focus toward variance analysis rather than mechanical matching.
Federal Reserve wire modernization alongside Eurosystem ISO 20022 deadlines is mandating XML-native ingestion architectures by 2025. Vendors lacking native structured message capabilities face displacement risk as enterprise RFPs now specify real-time payment message compatibility as a threshold requirement. Treasury departments in the United States and Germany are prioritizing vendors that rebuilt core engines rather than bolted on format adapters.
Subscription pricing for reconciliation platforms is displacing perpetual license models as finance leaders prefer operational expenditure treatment and demand continuous feature delivery. Mid-market buyers in particular are rejecting upfront capital commitments in favor of per-entity or per-transaction pricing that scales with organizational complexity. This shift is most visible among technology and professional services firms with volatile headcount and entity structures.
Bank Reconciliation Software Market Segmentation
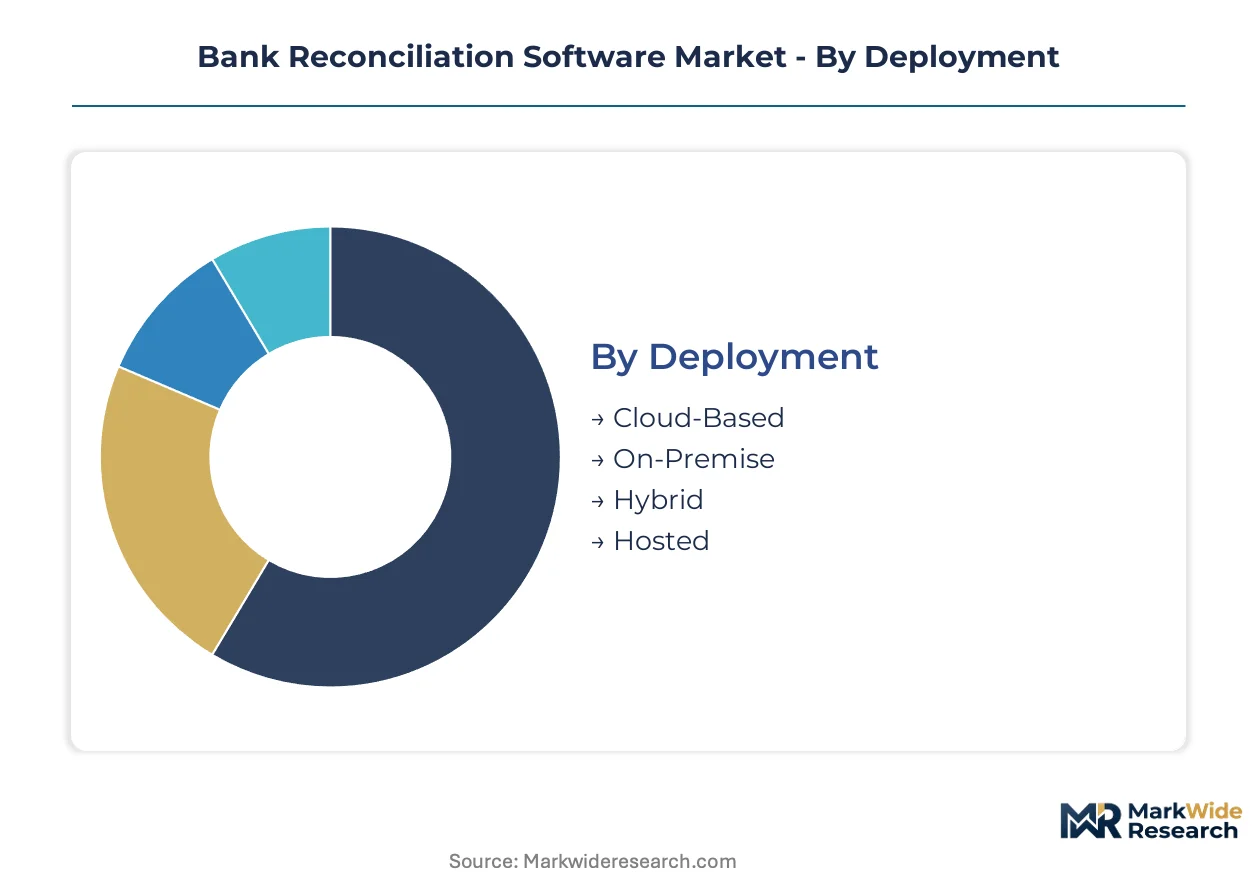
Bank reconciliation software segments reflect divergent compliance burdens across deployment modes and customer scales. SOX mandates, GDPR data residency rules, and ISO 20022 technical standards create tiered certification requirements that reshape vendor product roadmaps and procurement specifications.
Deployment:
Cloud-based installations face GDPR geographic controls and emerging data sovereignty laws in India and China, while on-premise deployments carry heavier SOX audit documentation burdens for United States public companies.
- Cloud-Based:Multi-tenant architectures with automatic updates dominate mid-sized enterprise procurement. Finance teams in Germany and the United States prioritize vendors with EU-US Data Privacy Framework certification and FedRAMP authorization respectively.
- On-Premise:Legacy installations at Fortune 500 treasuries require dedicated infrastructure maintenance. These deployments persist where national regulators mandate physical data control, particularly in Swiss banking and Japanese insurance sectors.
- Hybrid:Split architectures segregate sensitive payment data on-premise while routing analytics to cloud environments.
- Hosted:Single-tenant private cloud configurations serve organizations needing dedicated instances without capital expenditure.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as treasuries navigate fragmented regulatory landscapes.
Solution Type:
Functional modules align with distinct workflow automation depths, from basic matching engines through predictive exception handling.
- Automated Reconciliation:End-to-end platforms embed machine learning for predictive cash application. These systems reduce manual labor in high-volume accounts receivable operations at technology firms and professional services companies.
- Transaction Matching:Core engines applying rule-based algorithms to bank statement ingestion. Demand concentrates among mid-sized enterprises upgrading from Excel-dependent workflows in the United States and United Kingdom.
- Exception Management:Variance flagging and resolution workflows for unmatched items.
- Reporting & Analytics:Dashboard and visualization tools for treasury visibility.
Automated Reconciliation commands the deepest margin pools, while Exception Management gains share fastest as AI-powered prediction reduces manual review queues.
Use Case:
Workflow applications map to distinct treasury functions with varying automation maturity and fraud exposure profiles.
- Accounts Receivable:Cash application automation matches incoming payments to open invoices. Manufacturing and distribution companies in Germany deploy these modules to compress days sales outstanding metrics.
- Accounts Payable:Outgoing payment reconciliation against bank debits. Large enterprises with complex multi-entity structures in the United States prioritize these capabilities for SOX control documentation.
- Cash Management:Real-time liquidity visibility across banking relationships.
- Fraud Detection:Anomaly detection for unauthorized transactions and duplicate payments.
Accounts Receivable leads absolute deployment volume, with Fraud Detection expanding most quickly as real-time payment rails elevate exposure windows.
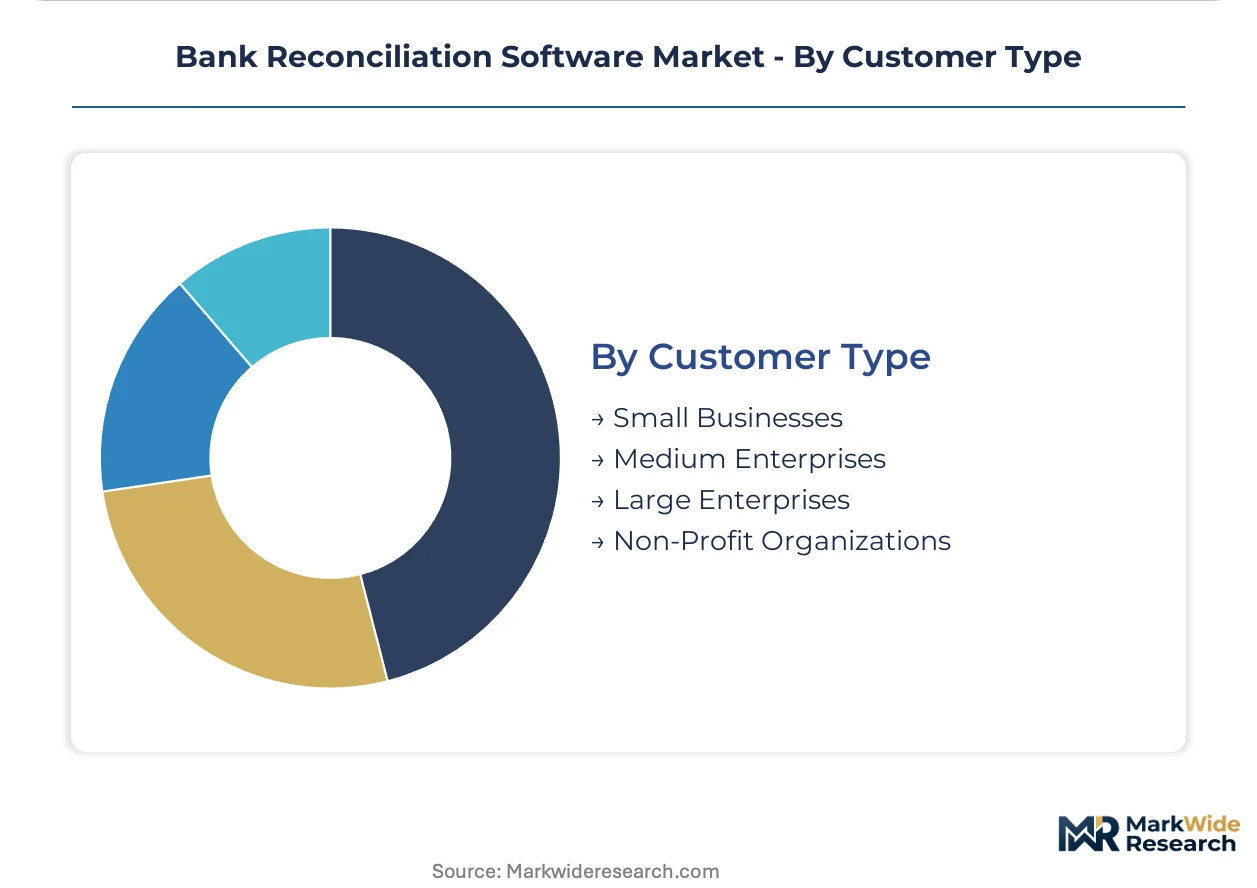
Customer Type:
Organizational scale determines integration complexity, entity count, and procurement authority structures.
- Medium Enterprises:Finance teams abandoning QuickBooks and Excel for cloud-native platforms. These buyers drive the steepest expansion trajectory as previously manual workflows automate across professional services and technology verticals.
- Large Enterprises:Multi-entity, multi-currency requirements with complex ERP integrations. Corporate treasuries in the United States with dozens of legal entities occupy the deepest margin pools.
- Small Businesses:Entry-level platforms with limited customization.
- Non-Profit Organizations:Grant-funded procurement with restricted implementation budgets.
Large Enterprises anchor current revenue concentration, with Medium Enterprises gaining share fastest as vendor sales teams target upgrade cycles from spreadsheet-dependent operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate treasury density in the United States generates the strongest adoption pull for bank reconciliation platforms, with multi-bank enterprises driving premium solution demand across North America and Western Europe.
United States
Fortune 500 treasuries with complex multi-entity structures dominate procurement volume. SEC mandates under SOX require immutable audit trails for cash controls, compressing vendor evaluation cycles. New York and Chicago financial centers anchor deployment concentration as corporate headquarters automate previously spreadsheet-dependent workflows.
Germany
Manufacturing and distribution companies deploy cash application modules to compress days sales outstanding metrics. Bundesbank oversight of Eurosystem ISO 20022 migration forces XML-native ingestion upgrades by 2025. Frankfurt and Munich industrial clusters lead adoption as mid-sized enterprises abandon Excel for cloud-native platforms.
United Kingdom
Professional services firms and technology companies drive mid-market expansion from QuickBooks-dependent operations. FCA conduct rules and GDPR data residency requirements shape vendor selection criteria. London fintech corridors concentrate demand for API-native platforms serving real-time payment rails.
India
RBI payment modernization programs accelerate enterprise treasury automation among IT services exporters and manufacturing conglomerates. Data localization mandates under the Digital Personal Data Protection Act fragment cloud deployment architectures. Bengaluru and Mumbai technology clusters represent contested acquisition territory for vendors targeting upgrade cycles.
Japan
Insurance and banking sectors maintain on-premise installations where METI guidelines emphasize physical data control. Complex multi-currency requirements at trading houses sustain demand for high-entity-count solutions. Tokyo and Osaka corporate headquarters prioritize vendors with native Japanese language support and local implementation partnerships.
Bank Reconciliation Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors race to embed reconciliation capabilities within broader financial close ecosystems. The market exhibits tiered concentration with enterprise-grade platforms serving Fortune 500 treasuries, mid-market specialists capturing QuickBooks upgrade cycles, and ERP-native modules absorbing adjacent workflow demand. Three archetypes anchor competitive positioning: deep ERP integrators, AI-powered matching engine specialists, and close-management workflow extenders. M&A activity and API partnership networks constitute the primary competitive vectors as vendors seek to compress implementation friction and expand addressable workflows.
Among ERP-anchored platforms, NetSuite and Sage Intacct exemplify the embedded-finance archetype by native reconciliation modules that reduce standalone procurement requirements. BlackLine occupies a position within the enterprise-tier specialist category, representing deep treasury workflow integration at scale-driven corporate deployments. These three companies illustrate how competitive positioning stratifies across deployment complexity tiers rather than converging on undifferentiated feature parity.
| Leading Market Players |
|---|
| BlackLine |
| HighRadius |
| FloQast |
| NetSuite |
| Xero |
| Sage Intacct |
| Trintech |
| Nomentia |
| ReconArt |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure cost indices cascade through vendor pricing tiers, compressing margins for SaaS providers while amplifying differentiation between API-native platforms and legacy on-premise installations. Mid-sized enterprises absorb the steepest cost pass-through as vendors recalibrate per-entity subscription models against hyperscaler compute pricing volatility.
Pricing Analysis
Input-cost pass-through from AWS and Azure compute pricing reshapes vendor margin structures, forcing tiered pricing stratification across premium enterprise, standard professional, and economy small-business tiers. Price differentiation hinges on ISO 20022 native certification and FedRAMP authorization grade, with unauthenticated cloud deployments facing steepest discount pressure. Cost compression in the mid-market tier intensifies because QuickBooks migrants demand per-transaction scalability without upfront capital commitment. Small businesses exhibit highest price sensitivity, while Fortune 500 treasuries prioritize audit-trail immutability over subscription cost.
Supply Chain Analysis
Engineering talent supply rests on Indian IT services clusters, United States fintech corridors, and German industrial software hubs for XML-native development capacity. Cloud infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Singapore, while specialized ISO 20022 parser libraries feed from SWIFT cooperative development programs. Single-source vulnerability concentrates in machine-learning training data repositories held by dominant platform vendors. Distribution runs through direct enterprise sales teams, ERP marketplace integrations, and channel partners serving mid-market verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bank reconciliation software constitutes a late-cycle quality story as treasury departments prioritize ISO 20022 native architectures over adapter-dependent alternatives, elevating specification premiums for vendors with rebuilt ingestion engines.
For Market Incumbents: Hedge against displacement risk by accelerating native XML pipeline development ahead of Federal Reserve wire modernization deadlines. Deepen ERP integration moats through exclusive certification partnerships with NetSuite and Sage Intacct. Talent scarcity in structured finance XML engineering threatens development velocity; captive acquisition of specialized development shops in Bengaluru and Frankfurt secures critical capabilities. For New Entrants and Emerging Players: EU CSRD in Europe opens a window for carbon-accounting reconciliation modules that embed emissions data into treasury workflows. White-label partnerships with neobanks serving small-business depositors represent the most penetrable channel, bypassing entrenched direct-sales competition. API-native positioning against batch-processed incumbents accelerates time-to-value demonstrations for mid-market procurement committees. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing native ISO 20022 engines and established FedRAMP authorization. Five-to-ten-year viability favors vendors with recurring revenue above eighty percent and customer concentration below fifteen percent per account. Monitor enterprise RFP language shifts from "format adapter compatibility" toward "native structured message ingestion" as inflection indicator for displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Native Engine Development | Federal Reserve wire modernization mandates XML-native ingestion by treasury departments. |
| ERP Marketplace Integration | NetSuite and Sage Intacct certification reduces standalone procurement friction for mid-market buyers. |
| AI-Powered Cash Application Module Launch | Machine learning algorithms compress unapplied cash balances by half within two quarters. |
| Geographic Data Residency Expansion | GDPR and Digital Personal Data Protection Act compliance requires EU and India-specific infrastructure. |
| Strategic Partnership with Hyperscaler | AWS and Azure co-sell agreements accelerate enterprise procurement through existing cloud commitments. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with corporate treasury directors, ERP implementation consultants, bank technology officers, and fintech product managers alongside secondary validation. SEC 10-K filings, SWIFT message standard documentation, Federal Reserve payment system reports, and hyperscaler capex disclosures anchor quantitative triangulation. Bottom-up deployment estimates and top-down market sizing reconcile through iterative stakeholder feedback.
Granularity-level modeling extends to deployment mode, organization size tier, solution type, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-specific adoption curves weighted by ISO 20022 migration timelines and SOX compliance audit intensities. Forecast inputs incorporate ERP upgrade cycle velocity, cloud infrastructure cost trajectories, and mid-market automation penetration rates.
Revisions become necessary when Federal Reserve wire modernization deadlines shift, data sovereignty mandates expand beyond current geographic scope, or machine-learning talent availability contracts sharply. Forecasts reflect documented assumptions about regulatory implementation schedules and enterprise procurement authority migration patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Email Applications Market
Software & Services
Global Membership Management Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Adaptive Learning Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Content Distribution Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Global Website Builder Software Market