
 System Infrastructure Software Market | 2026-2036
System Infrastructure Software Market Size, Share, and Industry Trends Forecast 2026-2036
System Infrastructure Software Market Intelligence
The capability gap between hyperscale cloud operators and legacy hardware-centric vendors is collapsing as software-defined infrastructure commoditizes proprietary silicon advantages. Microsoft Corporation leverages its Azure stack to extend control across hybrid deployment models, while Broadcom anchors its position through upstream control over virtualization licensing after the VMware acquisition. Cisco Systems competes by integrating network management software with its installed base of routing and switching hardware.
System infrastructure software comprises the foundational programs that manage computing resources, orchestrate workloads across distributed architectures, and enforce security policies through kernel-level access controls and API-driven automation. Its primary purpose is to abstract physical hardware into scalable, policy-governed resource pools that enterprise IT organizations consume through self-service portals and automated pipelines. Operating system and virtualization software categories dominate current revenue as organizations consolidate server footprints and containerize legacy applications. Security software within the solution dimension is expanding fastest, driven by zero-trust mandates and encryption requirements that permeate every layer of the stack.
FCC guidelines on communications infrastructure resilience, EPA directives on data center energy efficiency, and SEC cybersecurity disclosure rules are collectively elevating procurement standards for backup, recovery, and performance monitoring solutions across regulated industries. ISO 27001 and NIST frameworks further harden requirements for vendors seeking access to federal and financial services contracts. Stakeholders must weigh the trade-off between cloud-native subscription agility and the long-term cost compression achievable through in-house production of container orchestration and observability tooling.
Market Dynamics
The transition from perpetual licensing to consumption-based cloud subscriptions is compressing vendor revenue recognition cycles while simultaneously expanding total addressable spend through API-metered microservices. This structural shift forces infrastructure software providers to rebuild financial operations around usage telemetry rather than upfront enterprise agreements.
Growth Catalysts
- EU AI Act enforcement:European enterprises face mandatory algorithmic risk classification systems, triggering procurement of automated compliance monitoring and audit trail infrastructure.
- Hyperscale data center buildouts:United States federal cloud mandates under FedRAMP authorization are accelerating demand for container orchestration platforms that satisfy sovereign data requirements.
- Kernel-level security hardening:Zero-trust architecture mandates from NIST SP 800-207 are penetrating financial services and healthcare verticals, driving replacement of perimeter-based network access controls.
Market Restraints
- Virtualization licensing concentration:Upstream control over enterprise hypervisor stacks by a single dominant licensor creates cost volatility and contract renegotiation risk for mid-market buyers.
- Specialized kernel engineering talent scarcity:The shallow labor pool for eBPF programming and secure boot architecture limits vendor R&D velocity and customer implementation capacity.
- Legacy mainframe integration drag:COBOL-dependent financial institutions face structural friction modernizing core banking systems without disrupting real-time transaction processing.
Strategic Opportunities
- India PLI scheme for semiconductor design:Domestic software-defined networking talent pools are expanding around Bangalore and Hyderabad, creating captive engineering capabilities for global vendors.
- Edge computing orchestration:Convergence of 5G network slicing with lightweight Kubernetes distributions enables real-time workload placement for manufacturing and autonomous vehicle applications.
- Japan METI data free flow with trust:Cross-border data governance frameworks are opening compliant pathways for SaaS infrastructure vendors to serve enterprise customers across Asia-Pacific.
Industry Challenges
- Container security certification timelines:FedRAMP authorization for orchestration platforms requires 12-18 month assessment cycles, delaying revenue recognition for new entrants.
- Observability data gravity costs:Telemetry volume from microservices architectures generates exabyte-scale storage requirements that compress gross margins for monitoring vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System Infrastructure Software Market |
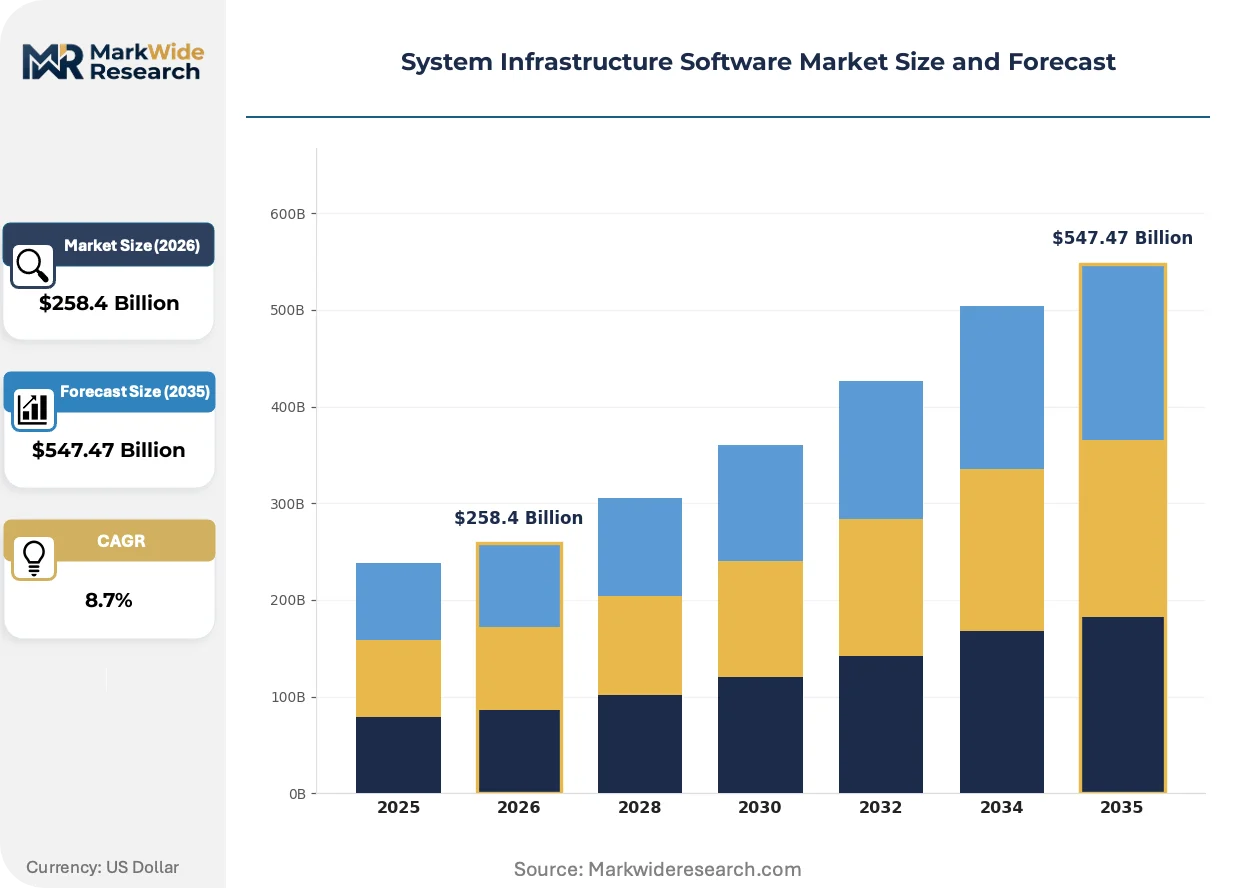
| Market Size in 2026 | $258.4 Billion |
| Market Size in 2035 | $547.47 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operating System, Virtualization Software, Middleware, Network Management Software Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government, Educational Institutions Solution: Backup & Recovery, Security Software, Performance Monitoring, Data Integration |
| Companies Covered | Amazon Web Services, Cisco Systems, Microsoft Corporation, Hewlett Packard Enterprise, Broadcom, Oracle Corporation, VMware, Red Hat, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System Infrastructure Software Market Strategic Shifts & Innovations
Software-defined infrastructure is fragmenting traditional hardware-software bundling, creating parallel markets for commodity silicon and premium control plane abstraction layers. Vendors now compete on API ergonomics and policy engine flexibility rather than proprietary hardware lock-in.
eBPF technology is bifurcating kernel observability from traditional agent-based monitoring approaches. Cloud-native enterprises in fintech and ad-tech verticals are deploying eBPF-powered security tools at production scale within 6-12 month adoption windows. This compression is displacing legacy APM vendors whose instrumentation overhead cannot match kernel-level execution efficiency.
SEC cybersecurity disclosure rules under Item 106 are mandating board-level visibility into material infrastructure vulnerabilities. Publicly traded enterprises must now document incident response capabilities and third-party software supply chain attestations. Financial services and critical infrastructure operators are responding by consolidating vendor relationships and demanding ISO 27001 certification as a baseline procurement filter.
Consumption-based pricing is displacing enterprise licensing agreements across mid-market buyers. Infrastructure software vendors are unbundling professional services from core platform subscriptions, forcing channel partners to absorb implementation risk. This pattern is most visible in Germany and France, where Mittelstand manufacturers prefer outcome-guaranteed service contracts over self-managed deployments.
System Infrastructure Software Market Segmentation
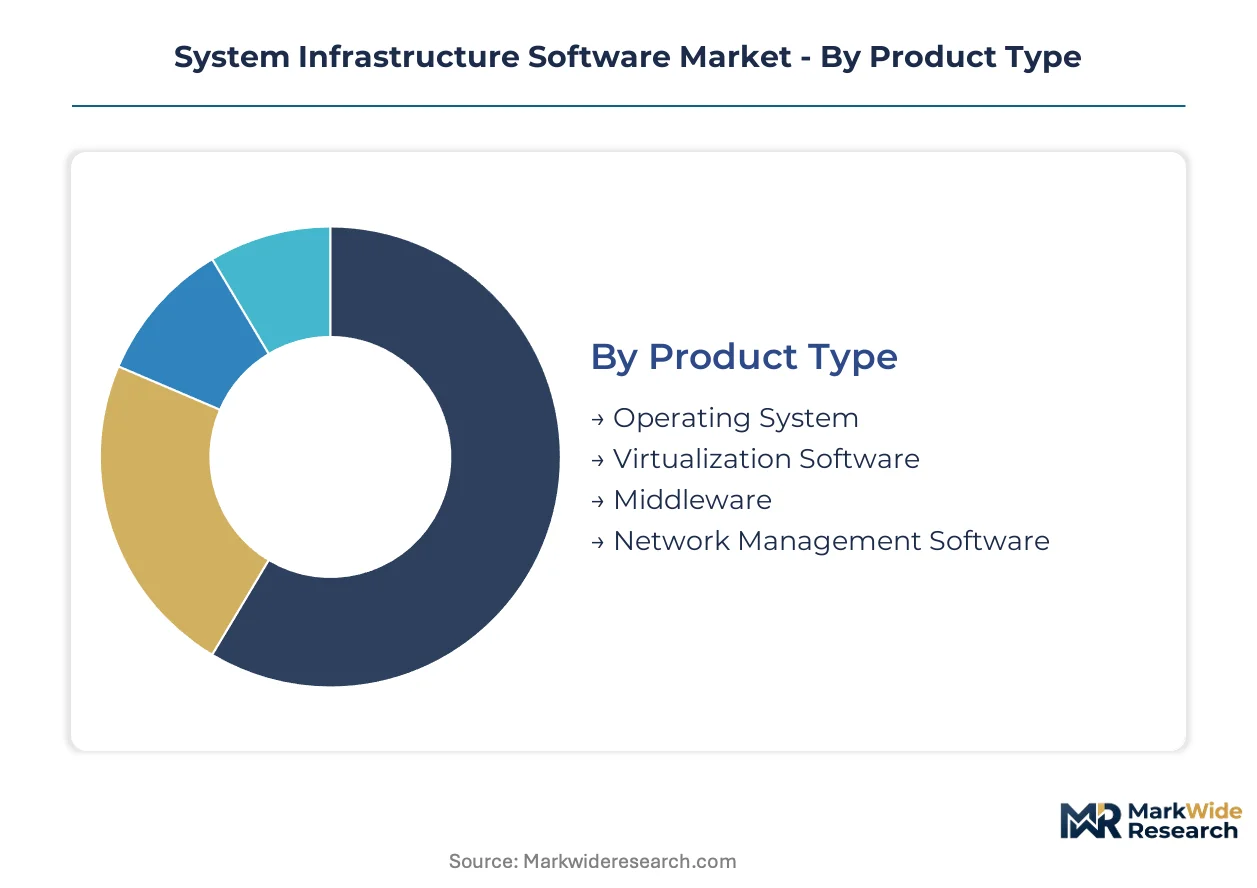
Segmentation in system infrastructure software reveals how procurement patterns diverge across technical architectures, operational models, and compliance postures. Understanding these fault lines exposes where vendor R&D investments concentrate and which customer profiles drive margin expansion.
Product Type:
Geographic concentration varies sharply across product categories, with virtualization and middleware platforms skewing toward export-led demand from US hyperscalers while operating systems retain stronger domestic anchoring in regulated European markets.
- Operating System:Kernel-level software manages hardware abstraction and process scheduling for server, desktop, and embedded deployments. Demand clusters in German automotive manufacturing and US defense contracting, where FedRAMP authorization requirements enforce specific kernel hardening standards.
- Virtualization Software:Hypervisors partition physical compute into isolated virtual machines with policy-governed resource allocation. Procurement concentrates among US financial services firms modernizing mainframe-dependent core banking systems under SEC cybersecurity disclosure mandates.
- Middleware:Application servers and message brokers bridge disparate software components in distributed architectures. Japanese automotive OEMs deploy middleware stacks for connected vehicle telemetry pipelines under METI data governance frameworks.
- Network Management Software:SDN controllers and traffic engineering platforms orchestrate data center and WAN connectivity. Indian IT services exporters drive adoption for managing multi-tenant cloud delivery infrastructure.
Operating System commands the established base. The steepest expansion runs through Security Software.
Deployment Model:
Cost tier stratification separates self-managed deployments from premium managed offerings, with hybrid architectures occupying the mid-tier pricing band as enterprises balance sovereignty requirements against cloud agility.
- On-Premises:Licensed software deployed within customer-controlled data centers with full operational responsibility. French healthcare providers retain on-premises electronic health record systems to satisfy CNIL data localization rulings.
- Cloud-Based:SaaS delivery of infrastructure platforms with API-metered consumption billing. US fintech startups leverage cloud-based container orchestration to compress time-to-market for payment processing applications.
- Hybrid:Workload portability across private infrastructure and public cloud with unified control planes. German Mittelstand manufacturers adopt hybrid models to keep proprietary CAD data on-premises while bursting simulation workloads to cloud.
- Managed Services:Third-party operational assumption of infrastructure software with outcome-guaranteed SLAs. UK financial institutions outsource security software management to meet FCA operational resilience deadlines.
On-Premises retains the largest installed footprint. Managed Services is climbing the fastest as skills scarcity deepens.
End User:
Volume concentration tilts toward large enterprises, though government verticals exhibit inelastic demand characteristics that insulate vendors from cyclical IT budget compression.
- SMEs:Mid-market buyers with constrained IT staffing and preference for consolidated platform suites. Italian regional banks select SaaS backup solutions to avoid dedicated infrastructure engineering hires.
- Large Enterprises:Complex multi-site organizations with heterogeneous legacy estates and formal procurement processes. US hyperscale retailers deploy custom network management stacks across continental distribution networks.
- Government:Sovereign entities with mandatory certification requirements and extended vendor qualification timelines. Australian federal agencies mandate ISO 27001 certification for all security software under TGA-aligned procurement rules.
- Educational Institutions:Universities and research consortia with seasonal usage patterns and grant-dependent funding cycles. South Korean technical institutes build virtualization labs for semiconductor engineering curricula.
Large Enterprises anchor revenue concentration. Government represents the most durable demand pool through budget cycles.
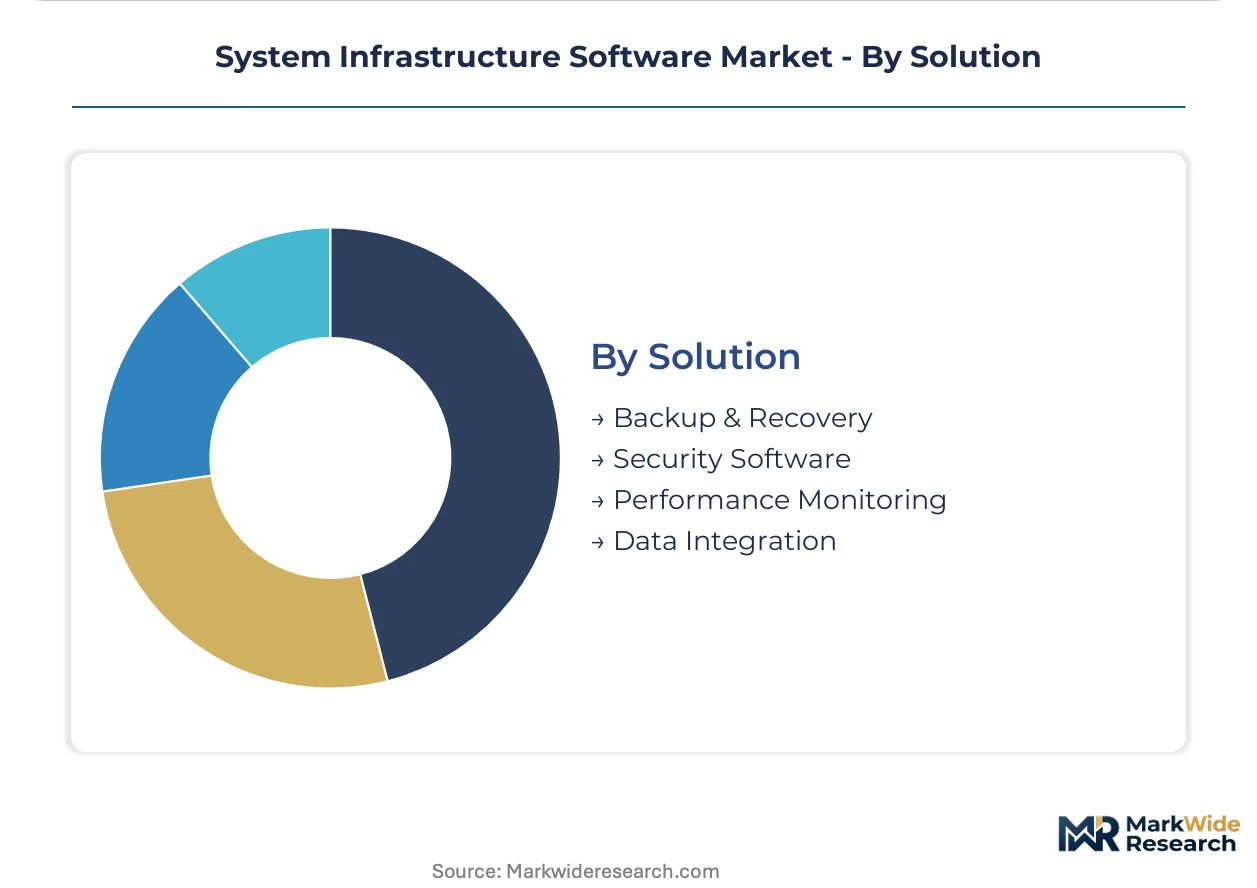
Solution:
Maturity gradients separate established backup markets from emerging security segments, with performance monitoring occupying an intermediate growth trajectory as observability data gravity intensifies.
- Backup & Recovery:Point-in-time data protection with automated failover orchestration and geographic replication. Swiss private banks mandate immutable backup architectures under FINMA operational risk guidelines.
- Security Software:Zero-trust access controls, encryption management, and threat detection with kernel-level enforcement. EU AI Act compliance drives French enterprises toward automated algorithmic audit trail infrastructure.
- Performance Monitoring:Telemetry ingestion and anomaly detection across distributed application stacks. Brazilian e-commerce platforms deploy eBPF-based monitoring to manage microservices latency during seasonal demand spikes.
- Data Integration:ETL pipelines and real-time streaming connectors unifying disparate enterprise data sources. Singaporean trade finance platforms integrate data layers to comply with MAS cross-border data flow certifications.
Backup & Recovery holds the deepest penetration. Security Software is gaining share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of system infrastructure software concentrate from US-headquartered hyperscalers toward European and Asia-Pacific enterprise buyers. Import dependency for specialized virtualization and security modules runs through Ireland and Singapore as regional licensing hubs. Currency-adjusted procurement costs in emerging markets are compressing margins for on-premises deployment vendors.
United States
Federal cloud mandates under FedRAMP authorization accelerate hyperscale data center buildouts across Northern Virginia and Dallas-Fort Worth. SEC cybersecurity disclosure rules force publicly traded enterprises to document third-party software supply chain attestations. Microsoft Corporation leverages its Azure stack to extend control across hybrid deployment models from Seattle-area headquarters.
Germany
Mittelstand manufacturers prefer outcome-guaranteed managed service contracts over self-managed deployments for proprietary CAD data protection. GDPR and EU AI Act compliance requirements trigger upgrades to security software and automated audit trail infrastructure. Frankfurt and Munich clusters concentrate demand for backup and recovery solutions under FINMA-aligned operational risk frameworks.
India
PLI scheme incentives for semiconductor design expand domestic software-defined networking talent pools around Bangalore and Hyderabad. IT services exporters drive network management software adoption for multi-tenant cloud delivery infrastructure. Mumbai financial institutions procure middleware stacks for real-time transaction processing modernization.
Japan
METI data free flow with trust frameworks open compliant pathways for SaaS infrastructure vendors serving Asia-Pacific enterprise customers. Automotive OEMs in Nagoya and Tokyo deploy middleware for connected vehicle telemetry pipelines. Kernel-level security hardening requirements penetrate financial services verticals under NIST-influenced local standards.
United Kingdom
FCA operational resilience deadlines push financial institutions toward outsourced security software management with outcome-guaranteed SLAs. London-headquartered fintech startups leverage cloud-based container orchestration to compress payment processing time-to-market. Edinburgh and Manchester clusters concentrate demand for hybrid deployment models balancing sovereignty against cloud agility.
System Infrastructure Software Market Key Industry Players
Concentration sits with hyperscale cloud operators and legacy hardware-software bundlers competing through divergent control plane strategies. The vendor base spans three tiers: subscription-native platform providers, perpetual-license incumbents transitioning to consumption billing, and specialized security tool vendors. Strategic moves center on M&A for virtualization licensing control and geographic expansion through regional compliance certification.
Within the cloud-native tier, Amazon Web Services and Microsoft Corporation exemplify platform providers extending infrastructure control across hybrid architectures. Cisco Systems occupies a position bridging network hardware installed bases with software-defined management layers. Broadcom represents the upstream licensing consolidation archetype following strategic virtualization portfolio acquisition.
| Leading Market Players |
|---|
| Amazon Web Services |
| Cisco Systems |
| Microsoft Corporation |
| Hewlett Packard Enterprise |
| Broadcom |
| Oracle Corporation |
| VMware |
| Red Hat |
| IBM |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with hyperscale cloud providers lock in both supply access and price visibility for enterprise buyers navigating FedRAMP authorization timelines. These multi-year commitments stabilize procurement costs while constraining vendor flexibility to adjust pricing for emerging security modules.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across virtualization and middleware platforms. Price differentiation centers on FedRAMP certification tier and deployment scale, with sovereign-cloud premiums commanding substantial uplifts over standard SaaS tiers. Cost compression in mid-market segments is intensifying because Broadcom's upstream control over VMware licensing creates contract renegotiation leverage. Government verticals exhibit the lowest price sensitivity due to mandatory compliance requirements, while Mittelstand manufacturers in Germany demonstrate acute sensitivity to professional services bundling.
Supply Chain Analysis
The United States and Ireland anchor software licensing and compliance certification operations for global distribution. India and Poland feed engineering talent pipelines for kernel development and eBPF programming. The supply chain rests on concentrated hyperscaler infrastructure dependencies, with single-source vulnerability around Broadcom's virtualization stack. Distribution runs through channel partners absorbing implementation risk under outcome-guaranteed SLAs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act enforcement is compressing procurement cycles for automated compliance infrastructure, creating a regulatory inflection that rewards vendors with pre-certified audit trail capabilities.
For Market Incumbents: Secure upstream control over container orchestration licensing to defend against open-source substitution. Invest in FedRAMP certification velocity to capture federal cloud mandate spending. Broadcom's VMware integration demonstrates how licensing consolidation creates pricing power that emerging platform vendors cannot replicate.
For New Entrants and Emerging Players: Edge computing orchestration for manufacturing represents an under-served service layer where incumbents lack lightweight Kubernetes distributions. Target Japanese automotive OEMs deploying connected vehicle telemetry under METI data governance frameworks. Lead with API-metered consumption models that bypass enterprise procurement committee friction.
For Investors and Strategic Acquirers: Specialized eBPF security tool vendors with production-scale fintech deployments present compelling acquisition targets. Long-term viability hinges on kernel-level execution efficiency displacing legacy APM instrumentation. Watch for FedRAMP authorization timeline compression as the signal indicating regulatory barrier erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's Azure stack extension across hybrid deployments captures federal cloud mandate spending. |
| Acquisition of Specialist Firm | Broadcom's VMware purchase consolidated upstream virtualization licensing control against open-source alternatives. |
| Geographic Expansion | India PLI scheme incentives expand captive software-defined networking engineering around Bangalore. |
| Strategic Partnership | Cisco's network hardware installed base integration with SDN controllers defends against cloud-native displacement. |
| Product Launch | eBPF-powered security tools at production scale compress 6-12 month adoption windows in fintech verticals. |
Research Approach
A spread of perspectives from CTOs, IT procurement officers, platform engineers, and channel partners converged on the working assumptions driving segmentation models. Primary interviews with federal contracting officers and Mittelstand manufacturing executives combined with secondary validation against SEC cybersecurity disclosure filings, hyperscaler capex disclosures, and EU AI Act implementation guidance. Bottom-up deployment model sizing triangulated against top-down infrastructure spend estimates.
Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs were derived from trend extrapolation anchored to documented procurement velocity shifts. Industry-specific forecast inputs incorporated FedRAMP authorization pipeline data and eBPF production deployment metrics from fintech and ad-tech verticals.
Forecasts assume regulatory continuity in EU AI Act enforcement and NIST SP 800-207 zero-trust mandates; material policy shifts would require re-modeling. Specific risk factors include virtualization licensing concentration creating cost volatility and specialized kernel engineering talent scarcity limiting implementation capacity. Recalibration cycles align with material shifts in federal cloud procurement timelines and edge computing orchestration adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ad Creation Software Market
Software & Services
Fire Software Market
Software & Services
Global Chromatography Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Subscription Management Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Media Editing App Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Sales Compensation Software Market
Software & Services
Software Licensing Market
Software & Services
Commercial Drone Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
User Interface Software Market
Software & Services
Global Healthcare Contract Management Software Market