
 Asia Pacific Structured Cabling Market | 2026-2036
Asia Pacific Structured Cabling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Structured Cabling Market Outlook
Chinese cable manufacturers is repositioning capacity toward high-pair-count twisted pair and fiber optic lines to serve hyperscale data center builds. Nexans SA leverages its regional manufacturing footprint to sustain project delivery across Southeast Asian infrastructure corridors. Schneider Electric SE anchors its position through integrated power and cabling solutions for commercial building retrofits. LS Cable & System Ltd. dominates Korean industrial complexes with specialized heavy-duty assemblies.
Asia Pacific structured cabling comprises organized networks of copper twisted pair, fiber optic, and coaxial elements with defined performance specifications such as Category 8 shielded twisted pair supporting frequencies up to two gigahertz, engineered to deliver reliable signal transmission across commercial, industrial, and telecommunications environments. Fiber optic segments lead margin pools due to bandwidth density requirements in cloud computing facilities, while twisted pair sustains volume dominance in commercial building retrofits where cost sensitivity persists. Data center application demand outpaces other verticals as colocation providers expand footprint across Singapore, Sydney, and Mumbai.
China's MIIT enforces GB standards for structured cabling performance, while India's BIS mandates fire safety ratings for indoor installations, and Australia's TGA-aligned building codes govern healthcare facility telecommunications infrastructure, collectively elevating product certification barriers and procurement specifications. Stakeholders must monitor regulatory divergence across national standards bodies to optimize regional product portfolios and avoid compliance-driven market exclusion.
Market Dynamics
Hyperscale data center construction across Southeast Asia is compressing deployment timelines and forcing cable manufacturers to pre-certify assemblies against multiple national standards simultaneously.
Growth Catalysts
- Smart city mandates:India's Ministry of Urban Development is channeling infrastructure investment into tier-one technology corridors, requiring Category 6A and fiber backbone installations in municipal buildings.
- MIIT GB standard upgrades:China's tightened performance benchmarks for building information infrastructure are accelerating replacement cycles in commercial retrofits.
- Cloud computing density:Colocation providers in Singapore, Sydney, and Mumbai are specifying OM4 and OM5 multimode fiber for 400G migration paths.
Market Restraints
- Copper price volatility:LME copper fluctuations are compressing margin pools for twisted pair manufacturers serving cost-sensitive commercial building segments.
- Optical fiber import concentration:Preform supply concentrates among three regional suppliers, creating bottleneck risk for fiber optic cable assemblers.
- Category 8 deployment limits:Shielded twisted pair's 30-meter channel restriction constrains application scope to data center top-of-rack connections.
Strategic Opportunities
- Indonesia's digital infrastructure gap:Underpenetrated secondary cities present first-mover positioning for integrated power-and-data solution providers.
- Converged power-over-ethernet:IEEE 802.3bt 90W delivery is expanding addressable market for single-cable LED lighting and building automation deployments.
- Vietnam's data center licensing:New government incentives for foreign cloud operators are triggering greenfield construction requiring full structured cabling ecosystems.
Industry Challenges
- Multi-standard certification backlog:Testing laboratories in the region face 12-16 week queues for GB, BIS, and TGA-aligned product approvals.
- Legacy coaxial integration:Industrial facilities in Korea and Japan require hybrid fiber-coaxial transition expertise that few installers possess.
- Skilled termination technician scarcity:Fusion splicing certification programs are not scaling to match fiber deployment velocity in emerging ASEAN markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Structured Cabling Market |
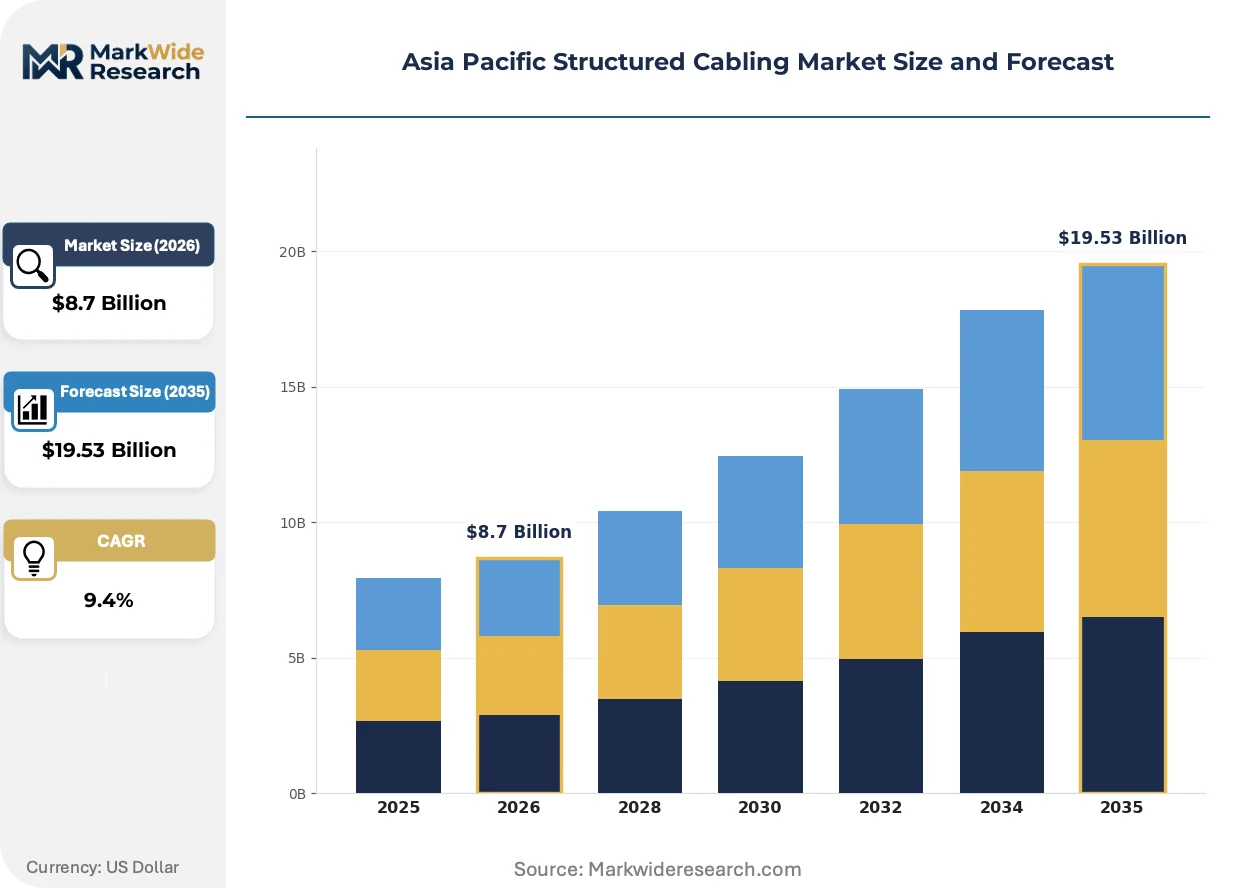
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twisted Pair, Coaxial Cable, Fiber Optic, Patch Panel Application: Data Center, Telecommunications, Commercial Buildings, Industrial Installation Type: On-Premise, Off-Premise, Outdoor, Indoor End User: Retail, Healthcare, Education, Government |
| Companies Covered | Nexans SA, Legrand S.A., CommScope Holding Company Inc., The Siemon Company, Schneider Electric SE, Belden Inc., Prysmian Group SpA, LS Cable & System Ltd., Corning Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Structured Cabling Market Strategic Shifts
Deployment velocity in hyperscale facilities is compressing product development cycles and forcing convergence between cabling infrastructure and thermal management design.
Single-mode fiber is expanding into data center interconnection applications previously served by multimode, driven by 800G coherent optics cost reductions. Cloud operators in Singapore and Sydney are specifying OS2 for spine-leaf architectures up to two kilometers. This shift is expanding into the structured cabling market's highest-margin product tier while pressuring multimode volume forecasts.
BIS fire safety ratings for indoor installations are mandating LSZH jacketing in commercial and healthcare verticals across India. Cable assemblers are reformulating compound recipes to meet smoke density and toxicity thresholds without sacrificing mechanical flexibility. The regulation is most affecting copper twisted pair procurement specifications in Mumbai and Delhi NCR smart city projects.
Direct-to-contractor digital procurement platforms are displacing traditional electrical distributor networks for standardized cable categories. Facility managers in Australian commercial retrofits are specifying products through online configurators that validate against TGA-aligned building codes. The channel shift is most visible in Sydney and Melbourne where project timelines compress bidding windows.
Asia Pacific Structured Cabling Market Segmentation
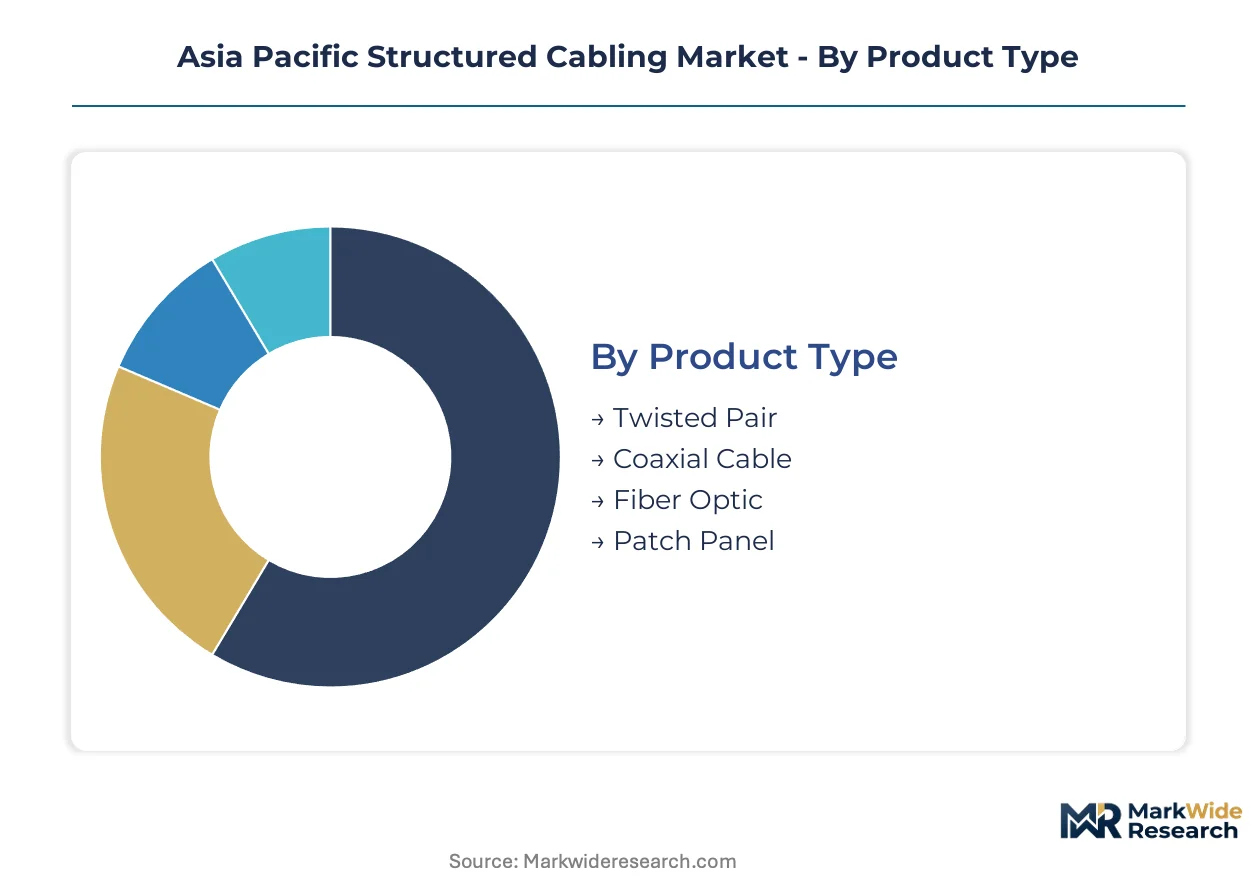
Segmentation in the Asia Pacific structured cabling market reveals how capital allocation, regulatory pressure, and deployment velocity concentrate across distinct technology and application boundaries. Understanding these divisions exposes where margin pools form and where procurement specifications diverge.
Product Type:
Capital intensity varies sharply across product categories, with fiber optic preform manufacturing and Category 8 shielding equipment demanding the heaviest upfront investment.
- Twisted Pair:Copper conductor assemblies ranging from Category 5e through Category 8 shielded twisted pair, with the latter supporting frequencies up to two gigahertz over 30-meter channels. Volume concentrates in India's tier-one technology corridors and commercial building retrofits across Australia, where BIS and TGA-aligned codes mandate fire-rated jacketing.
- Fiber Optic:Single-mode and multimode silica glass cables including OM4, OM5, and OS2 specifications engineered for bandwidth density in cloud computing facilities. Demand clusters in Singapore, Sydney, and Mumbai colocation builds where 400G and 800G coherent optics are compressing deployment timelines.
- Coaxial Cable:Hybrid fiber-coaxial assemblies serving legacy industrial infrastructure in Korea and Japan where transition expertise remains scarce.
- Patch Panel:Modular termination hardware for copper and fiber cross-connection in telecommunications closets and data center meet-me rooms.
Most installed capacity flows through twisted pair. Expansion is steepest in fiber optic.
Application:
Application segmentation tracks where procurement specifications tighten fastest and where project timelines compress most severely.
- Data Center:Hyperscale and colocation facilities requiring high-pair-count twisted pair and dense fiber optic spine-leaf architectures. Singapore, Sydney, and Mumbai host the most aggressive buildouts as cloud operators expand footprint.
- Telecommunications:Central office and mobile switching center infrastructure governed by MIIT GB standards in China and TRAI technical specifications in India.
- Commercial Buildings:Office retrofits and new construction across Australian cities where direct-to-contractor digital procurement is displacing traditional distributor networks.
- Industrial:Heavy-duty assemblies for Korean manufacturing complexes where LS Cable & System anchors supply relationships.
Data center procurement moves fastest. Commercial building volume remains largest.
Installation Type:
Installation segmentation separates projects by where cable assemblies face environmental stress versus regulatory scrutiny.
- On-Premise:Enterprise-owned infrastructure within building boundaries, common in government and healthcare verticals where TGA-aligned codes in Australia and BIS fire safety ratings in India govern indoor specifications.
- Off-Premise:Carrier-owned external plant connecting facilities to network points of presence.
- Outdoor:Aerial and underground deployments across Southeast Asian infrastructure corridors where climate exposure accelerates jacket compound degradation.
- Indoor:Plenum and riser-rated installations in Mumbai and Delhi NCR smart city projects where LSZH jacketing is becoming mandatory.
Indoor installations dominate value capture. Outdoor deployment is climbing fastest in Indonesia's secondary cities.
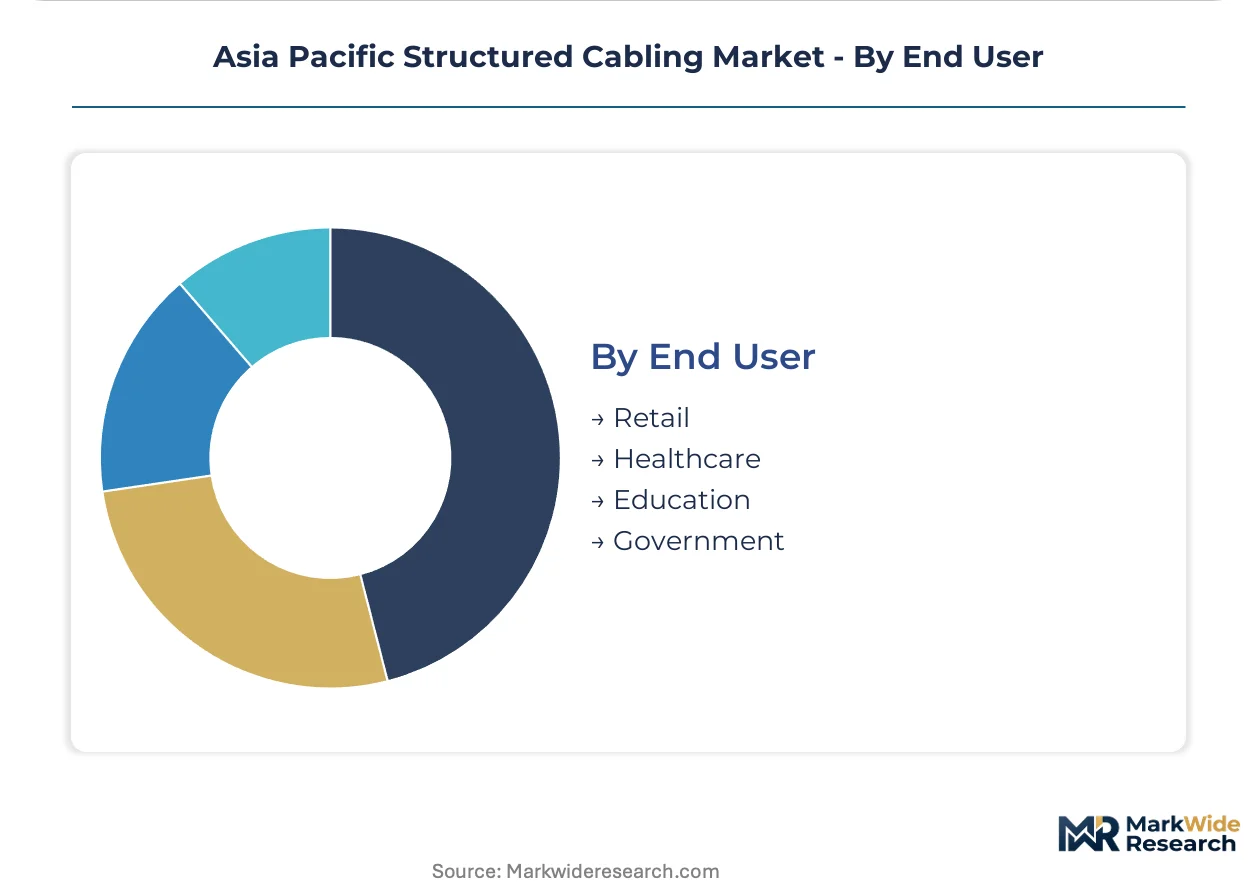
End User:
End user segmentation isolates where procurement authority concentrates and where specification complexity multiplies.
- Retail:Point-of-sale and inventory management networks across Australian shopping centers where converged power-over-ethernet is expanding single-cable deployments.
- Healthcare:Hospital and clinic telecommunications infrastructure in Australia governed by TGA-aligned building codes, with BIS fire safety ratings adding compliance layers in India.
- Education:Campus-wide networks in tier-one technology corridors where India's Ministry of Urban Development channels smart city investment.
- Government:Municipal building installations across Chinese provinces where MIIT enforces GB standard upgrades for building information infrastructure.
Government procurement carries the heaviest certification burden. Healthcare specifications are tightening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs across Asia Pacific by relocating preform production and cable assembly operations to jurisdictions with streamlined certification pathways. MIIT GB standards in China and BIS fire safety mandates in India impose divergent testing burdens that reshape where capacity concentrates.
China
Hyperscale data center construction in the Yangtze River Delta and Pearl River Delta is absorbing high-pair-count twisted pair and dense fiber spine-leaf architectures. MIIT enforces tightened GB standards for building information infrastructure that accelerate replacement cycles in commercial retrofits. Shenzhen and Shanghai host the most aggressive colocation builds as cloud operators expand footprint.
India
Smart city corridors in Mumbai and Delhi NCR are channeling infrastructure investment into Category 6A and fiber backbone installations in municipal buildings. BIS mandates LSZH jacketing for indoor installations to meet smoke density and toxicity thresholds. Tier-one technology parks in Bangalore and Hyderabad are specifying OM4 multimode fiber for 400G migration paths.
Australia
Commercial building retrofits across Sydney and Melbourne are displacing traditional electrical distributor networks with direct-to-contractor digital procurement platforms. TGA-aligned building codes govern healthcare facility telecommunications infrastructure with stringent certification requirements. New South Wales and Victoria concentrate demand for converged power-over-ethernet deployments in retail and education verticals.
Singapore
Colocation providers are specifying OS2 single-mode fiber for spine-leaf architectures up to two kilometers as 800G coherent optics cost reductions reshape interconnection economics. The city-state's data center licensing framework attracts foreign cloud operators triggering greenfield construction. Marina Bay and Changi technology corridors host the densest fiber deployments.
Indonesia
Underpenetrated secondary cities including Surabaya and Bandung present first-mover positioning for integrated power-and-data solution providers. New government incentives for digital infrastructure are compressing deployment timelines for cable manufacturers. Jakarta anchors procurement authority while outer island construction accelerates outdoor-rated cable demand.
Asia Pacific Structured Cabling Market Competitive Environment
Chinese producers anchor one tier; Korean and Japanese specialists hold differentiated positions in heavy-duty industrial assemblies. The vendor base organizes around three archetypes: integrated power-and-cabling conglomerates, fiber-centric pure-plays, and regional copper twisted pair specialists. Consolidation pressure concentrates among mid-scale assemblers facing multi-standard certification backlogs. Dominant competitive moves include backward integration into preform manufacturing and strategic partnerships with hyperscale data center developers.
Among France-based conglomerates, Nexans SA and Legrand S.A. exemplify the integrated solutions archetype spanning power distribution and telecommunications infrastructure. Schneider Electric SE anchors the premium-tier vector through combined electrical and data cabling offerings. LS Cable & System Ltd. represents Korean industrial specialization in heavy-duty assemblies for manufacturing complexes. These named entities occupy positions shaped by geographic manufacturing footprints and end-market concentration rather than uniform global scale.
| Leading Market Players |
|---|
| Nexans SA |
| Legrand S.A. |
| CommScope Holding Company Inc. |
| The Siemon Company |
| Schneider Electric SE |
| Belden Inc. |
| Prysmian Group SpA |
| LS Cable & System Ltd. |
| Corning Incorporated |
| Others |
Value Chain & Pricing Dynamics
Hyperscale data center operators in Singapore, Sydney, and Mumbai concentrate procurement authority through long-term framework agreements, compressing margin pools for cable assemblers serving fragmented commercial building retrofits. This buyer bifurcation splits the market between project-based premium pricing for certified fiber spine-leaf architectures and transactional spot purchasing for standardized twisted pair in cost-sensitive municipal builds.
Pricing Analysis
Distributor margins in Australia's commercial retrofit channel are compressing as direct-to-contractor digital procurement platforms validate TGA-aligned specifications without markup. Pricing stratifies across certified premium, standard compliance-grade, and economy non-rated tiers, with LSZH jacketing and Category 8 shielding commanding quality premiums. Cost compression in copper twisted pair is intensifying because LME volatility transfers downstream to fixed-bid contractors. Commercial building retrofitters exhibit highest price sensitivity; colocation providers in Singapore and Mumbai demonstrate lowest.
Supply Chain Analysis
Optical fiber preform supply rests on Japanese and Chinese specialty glass producers, with Korean compound manufacturers feeding jacketing formulations for LSZH-rated assemblies. Copper conductor drawing concentrates in China and India; fiber optic cable sheathing draws from Thai and Vietnamese polymer compounders. Single-source vulnerability in preform supply creates bottleneck risk for fiber optic cable assemblers. Distribution runs through project-direct channels for hyperscale data centers and electrical distributor networks for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific structured cabling market represents a late-cycle quality story as BIS fire safety ratings and MIIT GB standard upgrades shift procurement specifications toward certified premium tiers. Demand is migrating from commodity twisted pair to validated fiber spine-leaf architectures with traceable compliance documentation.
For Market Incumbents: Anchor defensive positioning through backward integration into preform manufacturing and captive supply of LSZH jacketing compounds. Multi-standard certification backlog at regional testing laboratories threatens market exclusion for assemblers lacking pre-certified product portfolios. Capacity addition in Vietnam and Indonesia secures proximity to greenfield data center licensing incentives. For New Entrants and Emerging Players: Electrical contractors in Indonesia's secondary cities present the most penetrable channel entry point. Surabaya and Bandung's underpenetrated digital infrastructure gap offers first-mover positioning for integrated power-and-data solution bundles. A go-to-market angle through direct digital procurement platforms bypasses entrenched distributor relationships in Australian commercial retrofits. For Investors and Strategic Acquirers: Integrated power-and-cabling conglomerates are the most active acquirer in this space, seeking fiber-centric pure-plays to complete solution portfolios. Mid-scale assemblers facing 12-16 week certification queues represent prime acquisition targets. Watch for MIIT GB standard enforcement intensity as inflection indicator for replacement cycle velocity in Chinese commercial retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive supply of optical fiber core material reduces dependency on Japanese and Chinese specialty glass producers. |
| Multi-Standard Certification Investment | Pre-certification against GB, BIS, and TGA standards accelerates project delivery across Southeast Asian infrastructure corridors. |
| Integrated Power-and-Data Solution Development | Converged IEEE 802.3bt 90W delivery expands addressable market for single-cable LED lighting and building automation deployments. |
| Direct-to-Contractor Digital Platform Launch | Online configurators validating against TGA-aligned codes displace traditional electrical distributor networks in Australian retrofits. |
| Regional Capacity Expansion in Vietnam | Proximity to new government data center licensing incentives triggers greenfield construction requiring full structured cabling ecosystems. |
Study Parameters
Multiple input streams — structured interviews with data center procurement officers and telecommunications infrastructure project managers, trade data from customs filings, MIIT GB standard documentation, and BIS certification registries — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of listed cable manufacturers, EPC contractor project databases, and colocation provider capex disclosures. Plant managers at Korean industrial complexes and channel partners in Australian electrical distribution contributed operational perspective.
Data-stream reconciliation across product type, application, installation type, and end-user segmentation dimensions shaped the analytical framework. CAGRs were derived through growth-rate convergence modeling across the projection horizon. Forecast inputs incorporated fiber deployment velocity in Singapore and Sydney, copper price trajectory sensitivity, and regulatory enforcement intensity for LSZH jacketing mandates in Indian smart city corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to preform supply concentration, multi-standard certification queue duration, and 800G coherent optics cost reduction trajectories. A small set of triggers — MIIT enforcement actions, BIS fire safety rating expansion, and Vietnam data center licensing volume — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Digital Repeater Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
2.4GHz Router Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global GPS Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Intelligent Network Management Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Network Packet Broker Market
Network Technology
Unified Network Management Market
Network Technology
Network Performance Monitoring Market
Network Technology
Global LWAN Market
Network Technology
North America Structured Cabling Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Fiber to the Premises Market