
 Automated Data Annotation Tool Market | 2026-2036
Automated Data Annotation Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Data Annotation Tool Market Outlook
ISO/IEC 42001 certification for artificial intelligence management systems is collapsing the barrier between enterprise-ready and experimental annotation vendors. Scale AI leverages its federal contracts to dominate defense and autonomous vehicle data pipelines. Labelbox sustains platform stickiness through workflow customization for healthcare AI developers. Appen competes on linguistic diversity, anchoring its position in multilingual natural language processing datasets.
Automated data annotation tools are software platforms that apply machine learning algorithms, computer vision models, and active learning loops to label raw unstructured data including images, video frames, text corpora, and audio waveforms with minimal human intervention, typically achieving throughput rates orders of magnitude above manual labeling while maintaining consistency through inter-annotator agreement algorithms and quality assurance pipelines. Image annotation solutions lead current revenue pools as autonomous driving and medical imaging consume massive labeled datasets, while text annotation grows fastest as large language model fine-tuning drives enterprise demand. Cloud-based deployment captures the dominant share of new implementations given elastic compute requirements for training data pipelines, though edge computing configurations gain traction in manufacturing quality control where latency constraints prohibit centralized processing.
The EU AI Act and GDPR impose strict provenance and bias-audit requirements on training data used in high-risk AI applications, directly shaping platform feature roadmaps toward explainability dashboards and lineage tracking. FDA guidance on machine learning-enabled medical devices in the United States further tightens validation protocols for healthcare annotation workflows. China's NMPA and MIIT coordinate algorithm registration rules that mandate domestic data residency for training sets used in commercial AI deployment. Stakeholders must monitor how divergent national AI governance regimes fragment platform architectures and compliance costs.
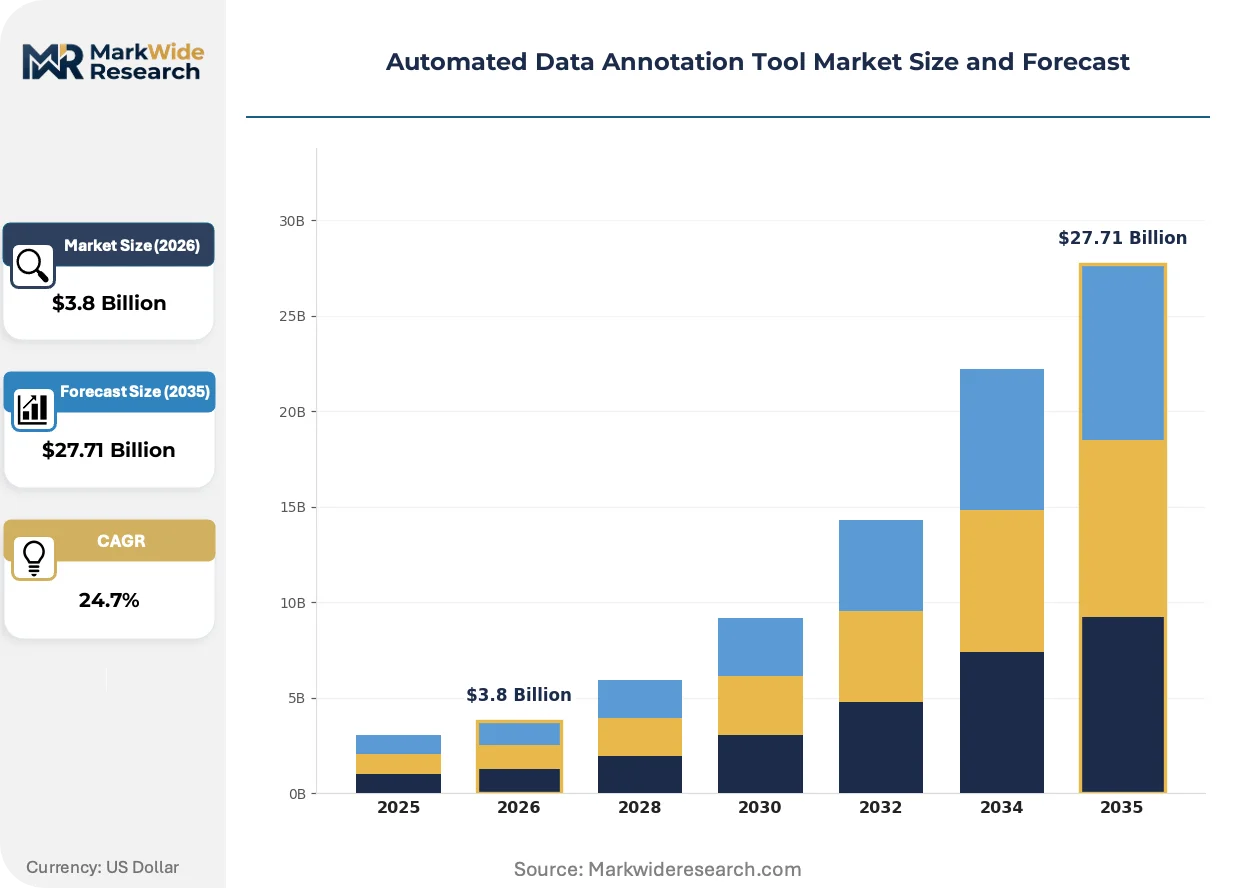
Market Dynamics
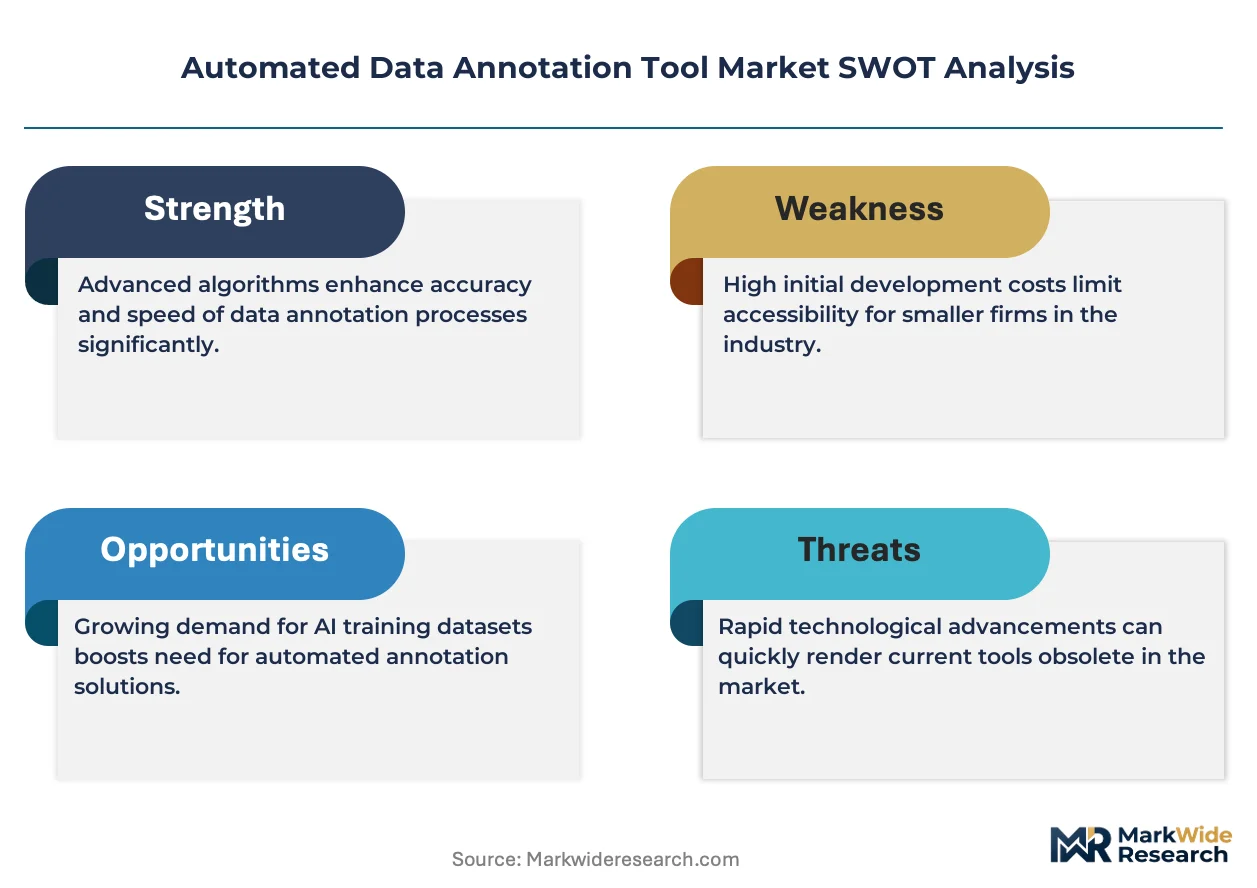
The automated data annotation tool market is restructuring around compliance-first architectures as the EU AI Act's risk-based classification framework forces vendors to embed provenance tracking and bias-audit capabilities directly into platform design.
Growth Catalysts
- Autonomous vehicle perception pipelines:Automotive manufacturers now require higher-quality training datasets for sensor fusion models, pulling annotation platforms toward specialized 3D point cloud and LiDAR labeling workflows.
- Federal AI procurement guidelines:United States defense and civilian agencies increasingly favor domestic annotation infrastructure, concentrating vendor investment in sovereign data residency capabilities.
- ISO/IEC 42001 certification mandates:Enterprise AI governance programs now require certified AI management systems, collapsing procurement barriers between experimental and production-ready annotation vendors.
Market Restraints
- Compute cost volatility:Elastic GPU and cloud storage pricing for training data pipelines creates margin pressure on platform operators during demand spikes.
- Geographic supply concentration:Specialized linguistic annotator pools cluster in specific emerging markets, creating single-source risk for multilingual natural language processing dataset production.
- GDPR data residency friction:Cross-border training data transfers face strict provenance requirements, fragmenting platform architectures and inflating compliance overhead for high-risk AI applications.
Strategic Opportunities
- Edge computing configurations:Manufacturing quality control applications with sub-50ms latency constraints are driving annotation platform deployment to factory floors, bypassing centralized cloud processing.
- Healthcare AI validation protocols:FDA guidance on machine learning-enabled medical devices creates demand for annotation workflows with embedded audit trails and inter-annotator agreement documentation.
- Active learning loop convergence:Integration of uncertainty sampling algorithms with synthetic data generation is reducing human-in-the-loop requirements for computer vision model training.
Industry Challenges
- Annotation workforce expertise gaps:Medical imaging and legal document labeling require domain-certified annotators, creating recruitment bottlenecks and quality variance across projects.
- Legacy system integration complexity:Enterprise data lakes built on decade-old schemas resist automated ingestion pipelines, forcing costly middleware development for annotation platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Data Annotation Tool Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Image Annotation, Video Annotation, Text Annotation, Audio Annotation End User: Healthcare Providers, Automotive Manufacturers, Retail Brands, Financial Institutions Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Industry Vertical: Telecommunications, Education, Agriculture, Entertainment |
| Companies Covered | Scale AI, Labelbox, Appen, SuperAnnotate, V7, Encord, BasicAI, Ango Hub, Kili, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Data Annotation Tool Market Strategic Shifts
Synthetic data generation paired with active learning is compressing the traditional annotation pipeline, while regulatory mandates are hardening platform requirements around explainability and lineage tracking.
Foundation model-based pre-labeling is supplanting rule-based heuristic approaches in computer vision workflows. Autonomous driving developers at Tier 1 suppliers now deploy these systems for initial bounding box and segmentation mask generation. The technology is compressing project timelines from months to weeks while reducing human annotator hours by orders of magnitude on routine object classes.
The EU AI Act's high-risk application classification is mandating bias detection and mitigation documentation for training datasets used in credit scoring, biometric identification, and critical infrastructure monitoring. Platform vendors must now embed fairness metric dashboards and demographic parity testing directly into annotation interfaces. Healthcare and financial services segments in Germany and France are accelerating procurement of compliant tooling ahead of enforcement deadlines.
Enterprise buyers are consolidating annotation spend through direct platform contracts rather than fragmented crowdsourcing relationships. Healthcare AI developers and defense contractors now prioritize workflow customization and API-native integration over per-label pricing. This concentration is most visible in the United States, where federal procurement vehicles and hospital system joint purchasing agreements are squeezing smaller annotation service providers from enterprise accounts.
Automated Data Annotation Tool Market Segmentation
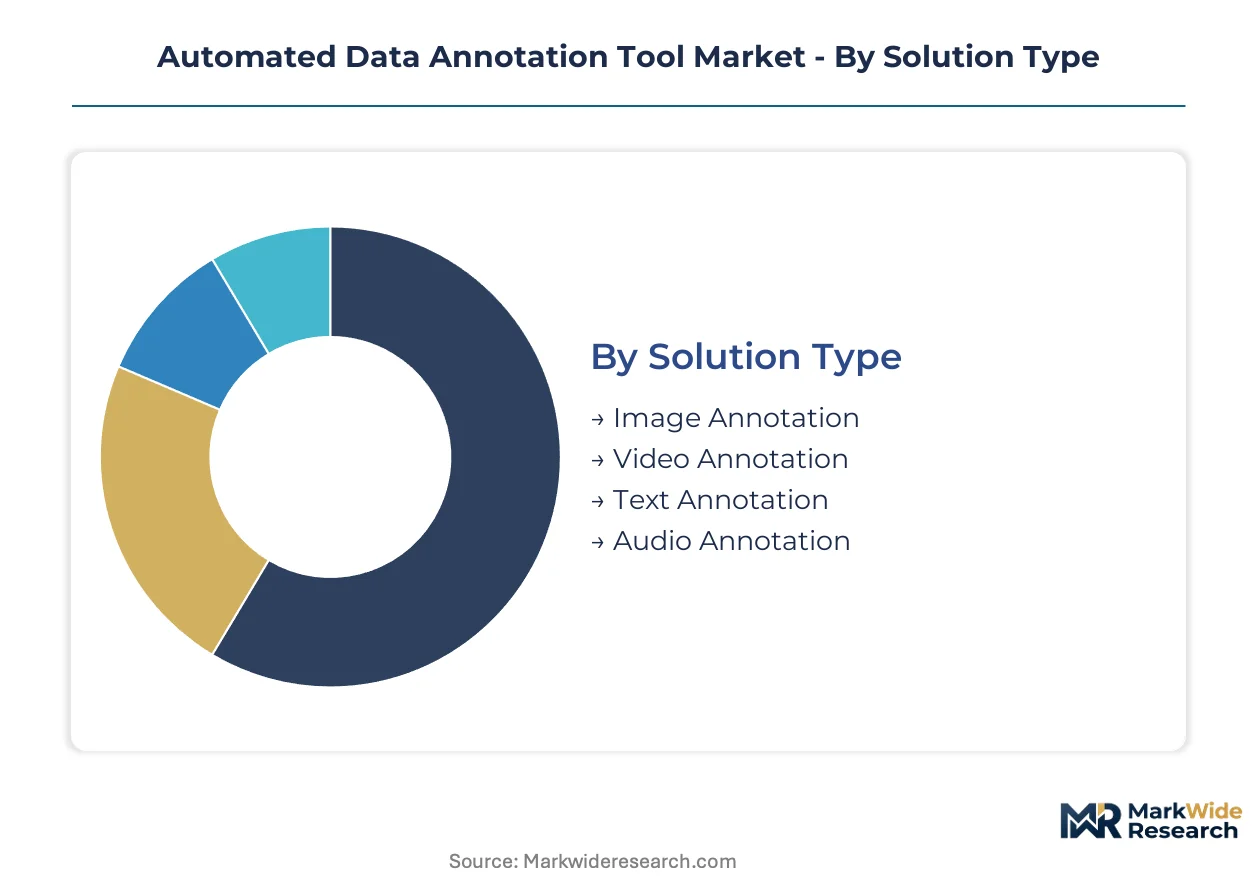
Segmentation in automated data annotation tools reveals how platform architectures diverge across workload types and compliance requirements. Each dimension exposes distinct margin structures and vendor specialization patterns that shape procurement decisions.
Solution Type:
Margin pools concentrate in modalities requiring specialized processing pipelines and domain-specific quality assurance layers.
- Image Annotation:Bounding box, segmentation mask, and keypoint labeling workflows dominate current revenue. Autonomous vehicle perception systems at Tier 1 suppliers and medical imaging AI developers in the United States and Germany consume massive labeled datasets for sensor fusion and diagnostic model training.
- Text Annotation:Named entity recognition, sentiment classification, and instruction-tuning datasets for large language models are climbing the fastest. Enterprise AI teams in financial services and legal technology sectors drive procurement of platforms with inter-annotator agreement algorithms and linguistic diversity coverage.
- Video Annotation:Temporal object tracking and action recognition labeling for surveillance and sports analytics applications.
- Audio Annotation:Speech-to-text alignment and acoustic event detection for voice assistant training and call center analytics.
Image annotation holds installed capacity. Text annotation is rotating up the share rankings.
End User:
Procurement authority and budget scale vary sharply across buyer categories, with regulated industries paying premium pricing for compliance-embedded tooling.
- Healthcare Providers:Hospital systems and medical device manufacturers require FDA-validated annotation workflows with embedded audit trails. Diagnostic imaging AI developers prioritize platforms with ISO 13485-aligned quality management and inter-annotator agreement documentation for regulatory submissions.
- Automotive Manufacturers:OEMs and Tier 1 suppliers demand 3D point cloud and LiDAR labeling capabilities for autonomous driving perception stacks. German and Japanese automakers specify platforms with functional safety certifications and domestic data residency options.
- Retail Brands:Visual search and inventory management AI drive demand for product attribute tagging and shelf monitoring datasets.
- Financial Institutions:Document understanding and compliance monitoring applications require secure on-premise deployment with encrypted annotation pipelines.
Automotive manufacturers anchor platform R&D investment. Healthcare providers are expanding procurement fastest.
Deployment Model:
Cost structures and latency constraints fragment implementation choices across centralized and distributed architectures.
- Cloud-Based:Elastic compute for training data pipelines captures dominant share of new implementations. GPU-accelerated preprocessing and active learning loops benefit from scalable infrastructure, though volatile pricing creates margin pressure during demand spikes.
- Edge Computing:Factory-floor deployment for manufacturing quality control with sub-50ms latency requirements is gaining traction. German automotive suppliers and Japanese electronics manufacturers lead adoption for real-time defect detection workflows.
- On-Premise:Air-gapped environments for defense contractors and classified research programs with strict data sovereignty mandates.
- Hybrid:Split processing architectures balancing preprocessing at the edge with model training in centralized cloud environments.
Cloud-based deployment holds installed capacity. Edge computing is rotating up the share rankings.
Industry Vertical:
Application maturity and annotation sophistication diverge widely across sectors with varying AI adoption timelines.
- Telecommunications:Network optimization and customer service chatbot training drive demand for conversational AI datasets and predictive maintenance imagery.
- Education:Adaptive learning platforms and automated assessment tools require text and multimodal annotation for personalized content delivery.
- Agriculture:Precision farming applications use drone imagery annotation for crop health monitoring and yield prediction models.
- Entertainment:Content moderation and recommendation engine training for streaming platforms and gaming environments.
Telecommunications holds installed capacity. Agriculture is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' federal cloud procurement infrastructure underwrites North American dominance in annotation platform deployment. Submarine cable landing stations in Virginia Beach and Los Angeles anchor trans-Pacific data flows for training dataset exchange.
United States
Defense contractors and autonomous vehicle developers in Michigan and California drive specialized 3D point cloud labeling demand. The FDA's machine learning-enabled medical device guidance tightens validation protocols for healthcare annotation workflows. Boston's hospital consortiums now require ISO 13485-aligned audit trails for diagnostic imaging AI training data.
Germany
Automotive OEMs in Stuttgart and Munich specify platforms with functional safety certifications for LiDAR perception stacks. The EU AI Act's high-risk application classification mandates bias detection documentation for credit scoring and biometric training datasets. Berlin's fintech clusters are accelerating procurement of compliant tooling ahead of enforcement deadlines.
China
Domestic AI developers in Beijing and Shenzhen face NMPA and MIIT algorithm registration rules mandating data residency for commercial deployment. The country's dual carbon goals are driving edge computing adoption for manufacturing quality control annotation. Shanghai's Pudong district hosts concentrated platform R&D for autonomous driving perception systems.
Japan
Electronics manufacturers in Osaka and Nagoya deploy factory-floor annotation for real-time defect detection with sub-50ms latency requirements. METI's AI governance frameworks emphasize domestic data sovereignty for industrial AI applications. Toyota City's supplier ecosystem is pioneering hybrid cloud-edge architectures for predictive maintenance imagery.
United Kingdom
Financial services AI developers in London require secure on-premise deployment with encrypted annotation pipelines for document understanding. The Information Commissioner's Office enforces GDPR provenance requirements on cross-border training data transfers. Cambridge's machine learning research clusters are driving demand for synthetic data generation paired with active learning loops.
Automated Data Annotation Tool Market Competitive Environment
Listed leaders compete with private specialists across compliance architecture and federal contracting channels. The vendor base stratifies between scale-driven platform operators and domain-specific workflow customizers. Three archetypes dominate: defense-focused sovereign data specialists, healthcare-validated compliance platforms, and multilingual linguistic diversity providers. Competitive moves concentrate on ISO/IEC 42001 certification acquisition and sovereign cloud partnership formation.
Within the federal contracting tier, Scale AI represents the sovereign data specialist archetype, leveraging domestic infrastructure requirements for defense and autonomous vehicle pipelines. Labelbox exemplifies the healthcare-validated platform model, sustaining workflow customization stickiness for FDA-aligned medical device developers. Appen occupies the multilingual specialist position, anchoring linguistic diversity coverage for enterprise natural language processing fine-tuning.
| Leading Market Players |
|---|
| Scale AI |
| Labelbox |
| Appen |
| SuperAnnotate |
| V7 |
| Encord |
| BasicAI |
| Ango Hub |
| Kili |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with hyperscaler cloud providers lock in GPU compute access and flatten cost volatility for annotation platform operators serving federal and healthcare clients. These multi-year agreements tether pricing visibility to sovereign data residency commitments demanded by United States defense procurement guidelines and EU AI Act compliance mandates.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and developer tiers based on annotation throughput commitments and API call volumes. Enterprise buyers in defense and healthcare segments pay premium rates for ISO/IEC 42001-certified platforms with embedded audit trails and lineage tracking. Pricing pressure stems from elastic cloud storage costs that spike during active learning loop iterations for computer vision model training. Mid-market AI developers exhibit highest price sensitivity, while federal contractors prioritize compliance over per-label economics.
Supply Chain Analysis
Just-in-time compute provisioning dominates cloud-based deployments, though strategic stockpiling of edge hardware is emerging among German automotive suppliers and Japanese electronics manufacturers with sub-50ms latency requirements. GPU clusters concentrate in the United States, China, and Germany. The supply chain draws from Taiwan for semiconductor components, South Korea for memory modules, and domestic foundries for sovereign-class processors. Single-source vulnerability in specialized LiDAR sensor arrays for autonomous vehicle annotation workflows poses structural risk. Distribution runs through direct platform contracts with enterprise buyers rather than fragmented crowdsourcing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in compliance-embedded tooling as divergent national AI governance regimes create specialized vendor niches. The EU AI Act's risk-based classification and FDA validation protocols split procurement requirements across geographies and verticals.
For Market Incumbents: Secure ISO/IEC 42001 certification moats before enforcement deadlines harden procurement barriers. Scale AI's federal contracting dominance demonstrates the defensibility of domestic data residency infrastructure. Incumbents should deepen backward integration into synthetic data generation to compress human-in-the-loop costs for routine annotation classes.
For New Entrants and Emerging Players: Anchor in edge computing configurations for manufacturing quality control where latency constraints exclude hyperscale incumbents. German automotive supplier ecosystems and Japanese electronics clusters represent penetrable beachheads with limited incumbent saturation. A hardware-software bundling go-to-market angle bypasses centralized cloud procurement channels.
For Investors and Strategic Acquirers: Capital is best deployed toward healthcare-validated platforms with FDA-aligned quality management and embedded audit trail architectures. Long-term viability hinges on regulatory compliance durability rather than raw annotation throughput. Watch for NMPA and MIIT algorithm registration enforcement in China as a signal for data residency mandate expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 42001 Certification Acquisition | Collapses procurement barriers between experimental and production-ready vendors for enterprise AI governance programs. |
| Sovereign Cloud Partnership Formation | Locks in federal and defense contracts requiring domestic data residency under United States procurement guidelines. |
| Synthetic Data Generation Integration | Compresses project timelines from months to weeks for autonomous vehicle perception pipeline developers. |
| Edge Computing Hardware Bundling | Captures manufacturing quality control workflows with sub-50ms latency constraints in Germany and Japan. |
| Healthcare Workflow Customization | Sustains platform stickiness for FDA-aligned medical device developers requiring inter-annotator agreement documentation. |
Study Parameters
A spread of perspectives from platform engineering leads, healthcare AI procurement officers, federal contracting specialists, and autonomous vehicle perception developers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of publicly listed annotation vendors, hyperscaler capex disclosures, FDA guidance documents, and EU AI Act implementation timelines. Bottom-up triangulation across deployment model adoption rates and top-down validation against vertical budget allocations anchored volume estimates.
Segmentation dimensions modeled span solution type, end-user industry, deployment architecture, and geographic regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted demand curves for training data pipelines. Industry-specific inputs include autonomous vehicle LiDAR dataset production rates and large language model fine-tuning corpus expansion trajectories.
Material uncertainties — algorithm registration enforcement timelines, GPU supply disruptions, and sovereign data residency mandate expansion — sit outside the modeled envelope. Forecasts reflect assumptions about compliance cost pass-through and elastic compute pricing stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Computer Vision Market