
 Speech-To-Text API Market | 2026-2036
Speech-To-Text API Market Size, Share, and Industry Trends Forecast 2026-2036
Speech-To-Text API Market Analysis
The Speech-To-Text API landscape is restructuring around a sharp divergence between premium accuracy tiers and commodity transcription layers. Google Inc. leverages its Tensor Processing Unit infrastructure to sustain sub-five-percent word-error-rate performance for enterprise medical dictation. Amazon Web Services, Inc. competes on cost-per-audio-hour, anchoring its position in high-volume call-center deployments where latency tolerance permits trade-offs against precision.
Speech-to-text application programming interfaces convert acoustic signals into machine-readable text through mel-frequency cepstral coefficient extraction and recurrent neural network decoding, serving industrial needs from real-time captioning to automated compliance logging. Cloud-based deployment dominates commercial uptake due to elastic scaling of GPU inference clusters, while on-premises configurations retain traction in financial services and defense contexts where data residency governs architecture selection. Healthcare end users generate outsized API consumption as ambient clinical documentation displaces manual note-taking, though media transcription and multilingual customer support represent faster-growing application categories with lower switching costs.
FDA oversight of clinical decision support tools intersects with HIPAA mandates to shape healthcare API procurement, requiring audit trails and business associate agreements that filter vendor eligibility. The EU AI Act's risk classification framework imposes conformity obligations on speech systems deployed in employment and education settings, creating compliance-driven demand for explainable model documentation. Stakeholders must weigh latency-accuracy trade-offs against evolving jurisdictional requirements as regulators on both sides of the Atlantic tighten algorithmic accountability standards.
Market Dynamics
The Speech-To-Text API market restructures around latency-accuracy tiering as healthcare and financial services impose divergent performance requirements on acoustic inference pipelines.
Growth Catalysts
- HIPAA-mandated clinical documentation:US healthcare providers embed transcription APIs into electronic health record workflows to reduce physician administrative burden.
- EU AI Act transparency obligations:Risk classification frameworks for automated speech systems in employment and education settings create compliance-driven procurement.
- Cloud GPU inference scaling:Elastic provisioning of tensor processing clusters enables real-time captioning for live broadcast and accessibility mandates.
Market Restraints
- Data residency requirements:Financial services and defense contractors in Germany and Switzerland reject cloud deployment, limiting addressable market for SaaS-native vendors.
- Accent and dialect coverage gaps:Training data concentration in North American English degrades word-error-rate performance for African, South Asian, and Nordic language variants.
- On-premises infrastructure costs:Air-gapped deployments require dedicated NVIDIA A100 or H100 clusters, tripling total cost of ownership against elastic cloud alternatives.
Strategic Opportunities
- India's BIS certification pathway:Domestic language support for Hindi, Tamil, and Telugu remains underdeveloped, creating first-mover advantage for localized acoustic models.
- Convergence with large language models:Speech-to-text outputs feeding retrieval-augmented generation pipelines enable ambient clinical intelligence and automated compliance summarization.
- Edge deployment for automotive:In-vehicle infotainment systems in Japan and South Korea demand sub-100-millisecond latency without cellular connectivity.
Industry Challenges
- Phonetic transcription specialist scarcity:Linguists capable of annotating low-resource languages command premium compensation, constraining training data expansion.
- FDA 510(k) pathway complexity:Clinical decision support tools incorporating speech recognition face extended review timelines for software-as-medical-device classification.
- Legacy telephony integration:Contact centers operating Nortel or Avaya premises-based switches require costly middleware development for API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech-To-Text API Market |
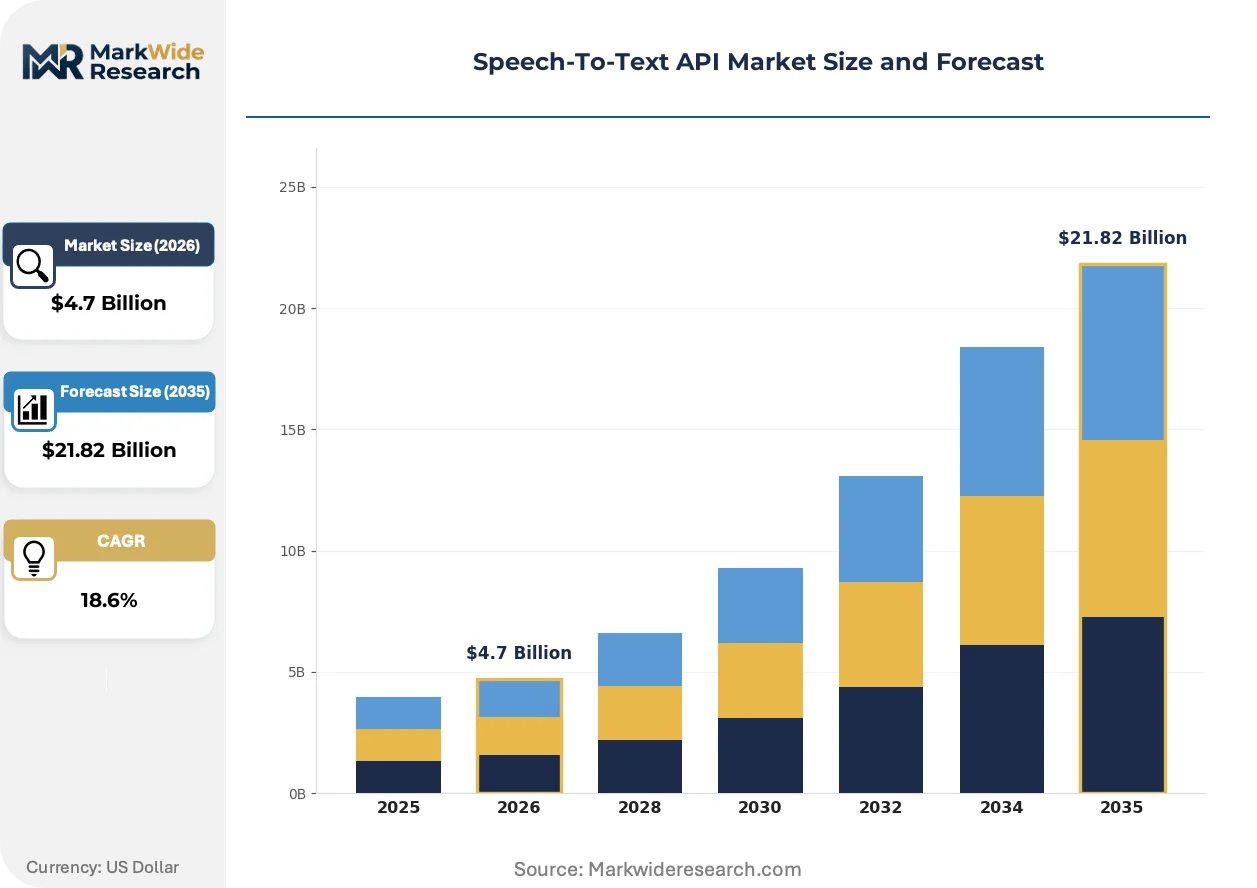
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud End User: Healthcare, Education, Media, Customer Support Application: Voice Assistants, Transcription Services, Language Translation, Accessibility Tools Technology: Machine Learning, Natural Language Processing, Deep Learning, Neural Networks |
| Companies Covered | Google Inc., Amazon Web Services, Inc., Microsoft Corporation, IBM Corporation, Speechmatics Ltd., Nuance Communications, Inc., Deepgram, AssemblyAI, Inc., Baidu, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech-To-Text API Market Emerging Trajectories
Neural architecture search and multimodal fusion are compressing the latency floor for real-time transcription while expanding deployment contexts beyond controlled acoustic environments.
Transformer-based conformer models is electrifying speech recognition accuracy by integrating convolutional subsampling with self-attention mechanisms. Medical dictation vendors in the United States adopt these architectures to achieve sub-three-percent word-error-rate for specialist terminology. The technology is electrifying competitive positioning by collapsing the performance gap between cloud and edge inference.
The EU AI Act's risk-based conformity framework imposes documentation and human oversight mandates on speech systems deployed in recruitment and credit scoring. Vendors must maintain model cards and algorithmic impact assessments for high-risk classifications. Healthcare and financial services procurement teams in France and Germany now require CE-marked conformity declarations before contract execution.
Consumption-based pricing for API calls is displacing perpetual licensing in enterprise procurement. Contact center operators in the United Kingdom and Netherlands negotiate per-audio-minute tiers with committed use discounts rather than capital expenditure for on-premises servers. This shift concentrates vendor selection authority with procurement functions previously excluded from technical evaluation.
Speech-To-Text API Market Segmentation
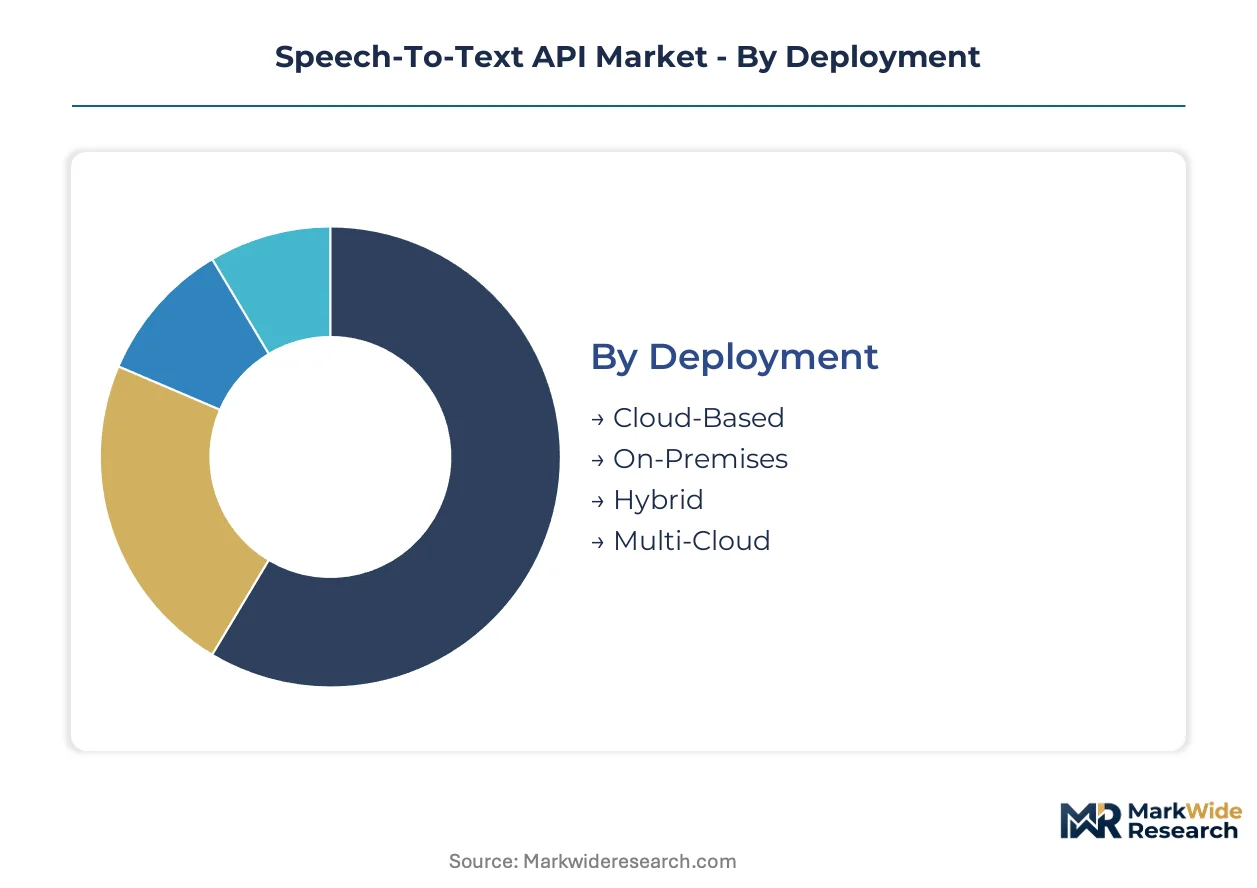
Speech-to-text API procurement diverges sharply across deployment architectures and end-use requirements, with HIPAA-mandated healthcare workflows demanding audit-trail precision while media broadcasters prioritize sub-second latency. Understanding these fault lines enables vendors to align inference infrastructure with buyer willingness-to-pay for accuracy tiers.
Deployment:
Standardized cloud configurations dominate high-volume segments, yet customization intensity escalates for air-gapped and multi-cloud architectures where data residency governs vendor selection.
- Cloud-Based:Elastic GPU clusters provision tensor processing capacity for real-time medical dictation and live broadcast captioning. Healthcare providers in the United States embed these APIs into Epic and Cerner workflows to satisfy HIPAA documentation mandates without capital expenditure.
- On-Premises:Dedicated NVIDIA A100 or H100 clusters operate within financial services data centers in Germany and Switzerland to satisfy BaFin and FINMA data localization requirements. Air-gapped inference triples total cost of ownership but remains non-negotiable for defense contractors handling classified acoustic signals.
- Hybrid:Split architectures route sensitive preprocessing on-site while delegating complex language modeling to cloud endpoints.
- Multi-Cloud:Redundancy across AWS, Azure, and GCP insulates enterprise buyers against single-provider outages.
Leading the category by volume: Cloud-Based. Growing fastest: Multi-Cloud.
End User:
Margin profiles invert across this category, with healthcare commanding premium pricing for regulatory compliance while media transcription competes on cost-per-audio-hour.
- Healthcare:Ambient clinical documentation displaces manual physician note-taking, with FDA 510(k) pathways filtering vendor eligibility for diagnostic support tools. Epic Systems integration consumes the majority of enterprise API procurement in the United States.
- Media:Live broadcast captioning for ESPN, BBC, and NHK demands sub-three-percent word-error-rate for proper noun recognition. Real-time latency requirements below 200 milliseconds compress margin as broadcasters negotiate volume-based per-minute pricing.
- Education:Lecture transcription for accessibility compliance drives procurement at public universities subject to ADA and Section 508 mandates.
- Customer Support:Contact centers in India and the Philippines deploy transcription for automated quality assurance and sentiment analysis.
Healthcare generates highest revenue per API call. Customer Support expands most quickly in emerging markets.
Application:
Application maturity separates established transcription services from experimental voice assistant deployments still navigating accuracy-utility trade-offs.
- Transcription Services:Post-processing of recorded audio dominates legal discovery and compliance logging, with verbatim requirements for deposition and arbitration proceedings. Law firms in New York and London represent concentrated demand for speaker diarization and timestamp precision.
- Voice Assistants:In-vehicle infotainment systems in Japan and South Korea require sub-100-millisecond edge inference without cellular connectivity. Automotive OEMs integrate wake-word detection with cloud-based natural language understanding.
- Language Translation:Simultaneous interpretation for diplomatic and enterprise conferencing pipelines speech recognition into neural machine translation.
- Accessibility Tools:Real-time captioning for deaf and hard-of-hearing users satisfies FCC mandates for broadcast television and extends to Zoom and Teams enterprise licensing.
Transcription Services anchor current revenue. Voice Assistants gain share fastest as automotive edge deployment accelerates.
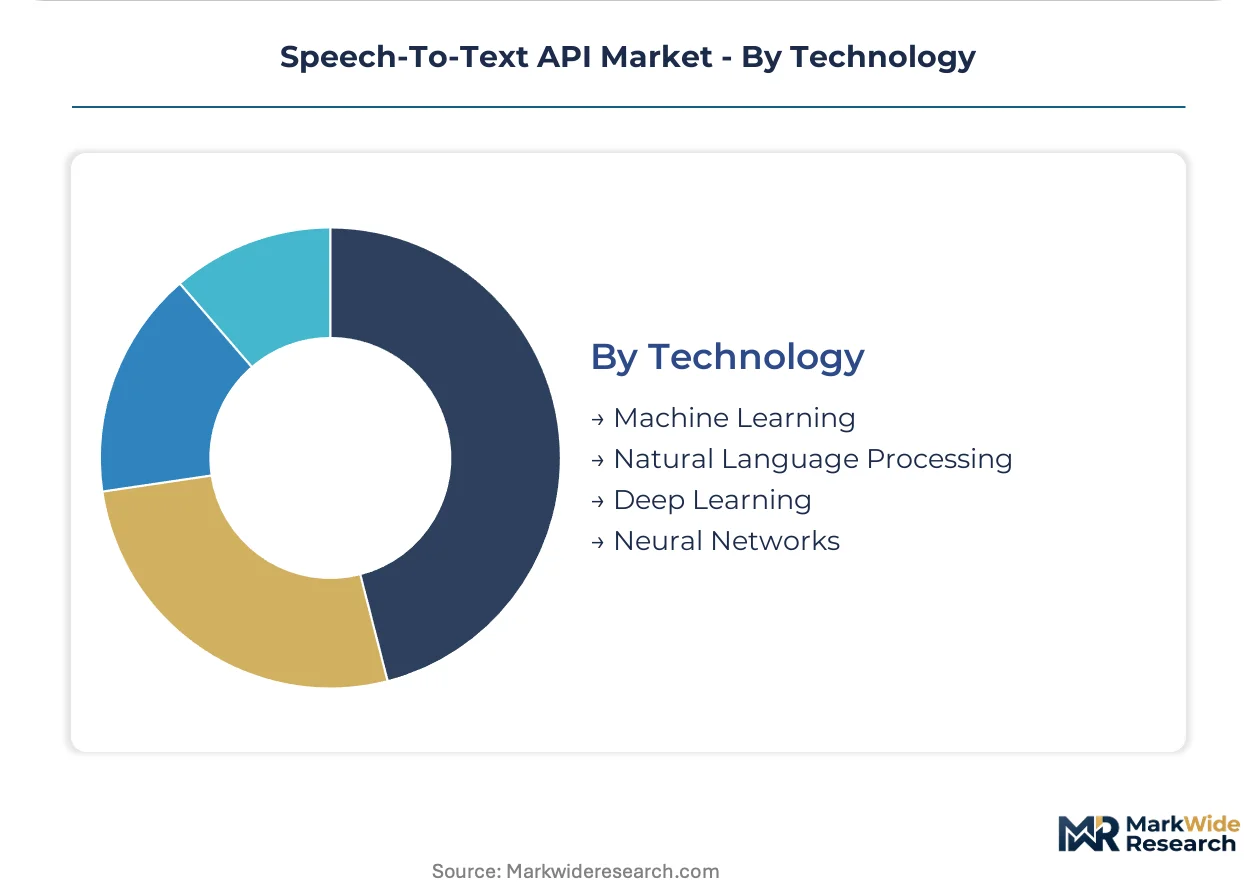
Technology:
Technology stack choices concentrate around transformer architectures, with differentiation emerging in how vendors composite acoustic and linguistic modeling layers.
- Deep Learning:Conformer models integrating convolutional subsampling with self-attention mechanisms achieve sub-three-percent word-error-rate for medical specialist terminology. Research groups at Johns Hopkins and Stanford drive benchmark competition for clinical acoustic modeling.
- Natural Language Processing:Post-processing pipelines correct disfluencies and insert punctuation for readable transcript output. Legal and medical domains require domain-specific language models trained on annotated corpora.
- Machine Learning:Classical Gaussian mixture models persist in resource-constrained edge devices where neural inference exceeds thermal envelopes.
- Neural Networks:End-to-end architectures compress pipeline latency by eliminating explicit phoneme representations.
Deep Learning commands R&D investment concentration. Neural Networks show steepest expansion trajectory for latency-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the densest concentration of speech-to-text API development, with venture-backed startups and hyperscaler engineering centers driving benchmark competition for medical and enterprise transcription accuracy.
United States
Federal accessibility mandates and HIPAA documentation requirements sustain enterprise API procurement across healthcare contact centers. FDA oversight of clinical decision support tools filters vendor eligibility for diagnostic applications. Epic Systems integration in Madison, Wisconsin and Cerner deployments in Kansas City concentrate procurement authority for hospital network transcription contracts.
Germany
BaFin data localization requirements and EU AI Act conformity obligations shape procurement for financial services transcription. Automotive OEMs in Stuttgart and Munich demand sub-100-millisecond edge inference for in-vehicle voice interfaces. Siemens Healthineers and SAP engineering centers in Munich drive healthcare and enterprise workflow integration standards.
United Kingdom
BBC live broadcast captioning mandates and Ofcom accessibility regulations sustain real-time transcription demand for media applications. Contact center operators in London and Manchester negotiate per-audio-minute consumption pricing with committed use discounts. Financial services firms in the City of London require audit-trail precision for compliance logging.
India
BIS certification pathways for domestic language support create first-mover opportunities for Hindi, Tamil, and Telugu acoustic models. IT services exporters in Bangalore and Hyderabad embed transcription APIs into business process outsourcing workflows for multinational clients. TRAI data governance consultations signal forthcoming localization requirements for voice data processing.
Japan
METI industrial digitization programs and automotive edge deployment requirements drive sub-100-millisecond latency specifications for in-vehicle infotainment. NHK broadcast captioning standards exceed FCC-equivalent accuracy thresholds for proper noun recognition. Toyota and Honda engineering centers in Nagoya and Tokyo specify wake-word detection without cellular connectivity dependency.
Speech-To-Text API Market Vendor Landscape
Premium-margin players sit above commodity-margin players across accuracy-latency tiering, with healthcare and financial services procurement teams willing to pay three-to-five-fold multiples for sub-three-percent word-error-rate performance. The vendor base stratifies into hyperscaler cloud platforms, specialized medical transcription providers, and API-native developer tools. Three strategic archetypes dominate: infrastructure-leveraged accuracy leaders, cost-optimized volume processors, and domain-specialized compliance vendors. Competitive moves concentrate on M&A for linguistic talent acquisition and strategic partnerships for EHR workflow integration.
Within the hyperscaler tier, Google Inc., Amazon Web Services, Inc., and Microsoft Corporation exemplify infrastructure-leveraged positioning, each representing distinct geographic origin and corporate structure archetypes. Google Inc. occupies a position anchored in Tensor Processing Unit infrastructure for medical dictation accuracy. Amazon Web Services, Inc. exemplifies cost-per-audio-hour optimization for high-volume call-center deployment. Microsoft Corporation represents enterprise workflow integration through Azure cloud services and Office 365 ecosystem embedding. These three entities collectively anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Google Inc. |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Speechmatics Ltd. |
| Nuance Communications, Inc. |
| Deepgram |
| AssemblyAI, Inc. |
| Baidu, Inc. |
| Others |
Supply Flow & Price Mechanics
Accuracy-latency tier divergence between sub-three-percent medical dictation and high-volume call-center commodity layers manifests in divergent cloud GPU provisioning and on-premises NVIDIA cluster sourcing strategies. Healthcare procurement teams in the United States absorb three-to-five-fold pricing multiples for FDA-filtered compliance tiers, while contact center operators in India and the Philippines negotiate per-audio-minute consumption contracts that compress margins for elastic cloud inference providers.
Pricing Analysis
Value-based pricing anchored to word-error-rate outcomes dominates healthcare procurement, with HIPAA-mandated clinical documentation commanding premium SaaS tiers against cost-per-audio-hour volume discounts for media transcription. Price differentiation separates CE-marked EU AI Act conformity tiers from standard cloud API offerings, with German automotive OEMs paying latency premiums for sub-100-millisecond edge inference. Cost compression in high-volume customer support segments intensifies as Indian BPO operators consolidate procurement authority. Media broadcasters exhibit highest price sensitivity, while financial services in Switzerland demonstrate lowest sensitivity due to FINMA-mandated data residency requirements.
Supply Chain Analysis
Tensor Processing Unit supply rests on Taiwan Semiconductor Manufacturing and South Korean memory fabricators, with NVIDIA A100 and H100 GPU sourcing concentrated in United States and China manufacturing nodes. Training data annotation draws from Philippines and Kenya linguist labor pools, while mel-frequency cepstral coefficient processing hardware sources from Japanese precision component suppliers. Single-source vulnerability in advanced node semiconductor fabrication threatens inference capacity expansion timelines. Distribution runs through hyperscaler cloud marketplaces and direct enterprise API licensing for air-gapped deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speech-to-text API competition has become a vertical-integration race, with model training infrastructure and clinical workflow embedding as the decisive downstream levers separating premium-margin from commodity-margin positioning.
For Market Incumbents: Lock in EHR workflow integration through Epic Systems and Cerner partnership exclusivity to defend against API-native challengers. Secure dedicated NVIDIA H100 cluster allocations through backward integration into cloud infrastructure provisioning. FDA 510(k) pathway expertise serves as the priority defensive moat against hyperscaler encroachment into clinical decision support.
For New Entrants and Emerging Players: Begin with BIS certification pathways for Hindi, Tamil, and Telugu acoustic models to exploit India's underdeveloped domestic language support. Target edge deployment for Japanese and South Korean automotive OEMs where sub-100-millisecond latency requirements filter out incumbent cloud-heavy architectures. Go-to-market through Tier 1 supplier integration partnerships bypasses direct hyperscaler competition.
For Investors and Strategic Acquirers: Re-rating potential sits with domain-specialized compliance vendors given EU AI Act CE marking mandates and FDA software-as-medical-device classification expansion. Long-term viability favors entities controlling both acoustic model IP and regulatory approval pathways rather than pure-play API layer providers. Watch FDA 510(k) submission volume acceleration as the inflection signal for clinical transcription market consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems and Cerner EHR embedding secures HIPAA-mandated clinical workflow lock-in. |
| Acquisition of Specialist Firm | Phonetic transcription linguist teams in low-resource languages command premium talent arbitrage. |
| Geographic Expansion | BIS certification for Hindi, Tamil, Telugu unlocks India's domestic language procurement demand. |
| Strategic Partnership | Toyota and Honda in-vehicle infotainment integration enables sub-100-millisecond edge deployment. |
| Product Launch | CE-marked EU AI Act conformity declarations satisfy French and German procurement mandates. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and FDA 510(k) submission databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with healthcare CTOs, hospital purchasing committee members, contact center operations directors, and automotive platform engineers validated demand assumptions and procurement timeline estimates. Bottom-up and top-down triangulation reconciled API call volume projections against cloud infrastructure capacity expansion plans.
Bottom-up modeling segmented the market across deployment architecture, end user vertical, application type, and technology stack complexity. Conformer model adoption curves, GPU inference cost trajectories, and regulatory approval pathway timelines served as industry-specific forecast inputs. CAGRs were derived from elasticity-adjusted demand projections across the analysis window.
EU AI Act enforcement delays, FDA software-as-medical-device reclassification, and NVIDIA advanced node supply constraints are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions subject to revision upon trigger materialization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Machine Learning in Communication Market